Oct 6, 2026 KOSPI Market Brief — What to Watch Before the Korean Open
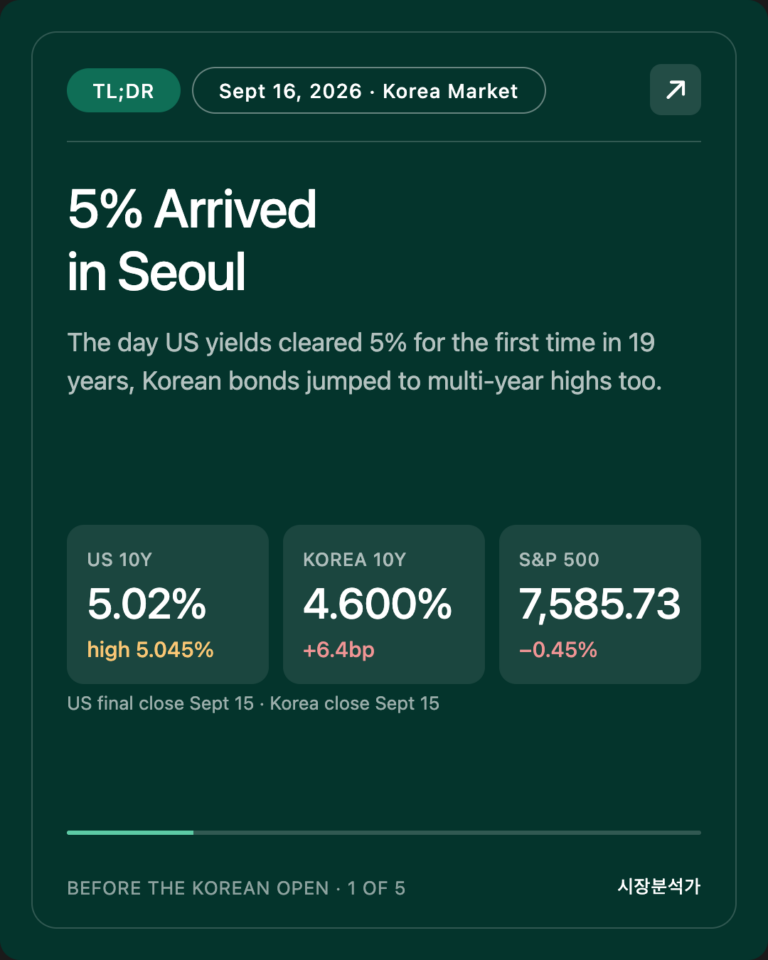
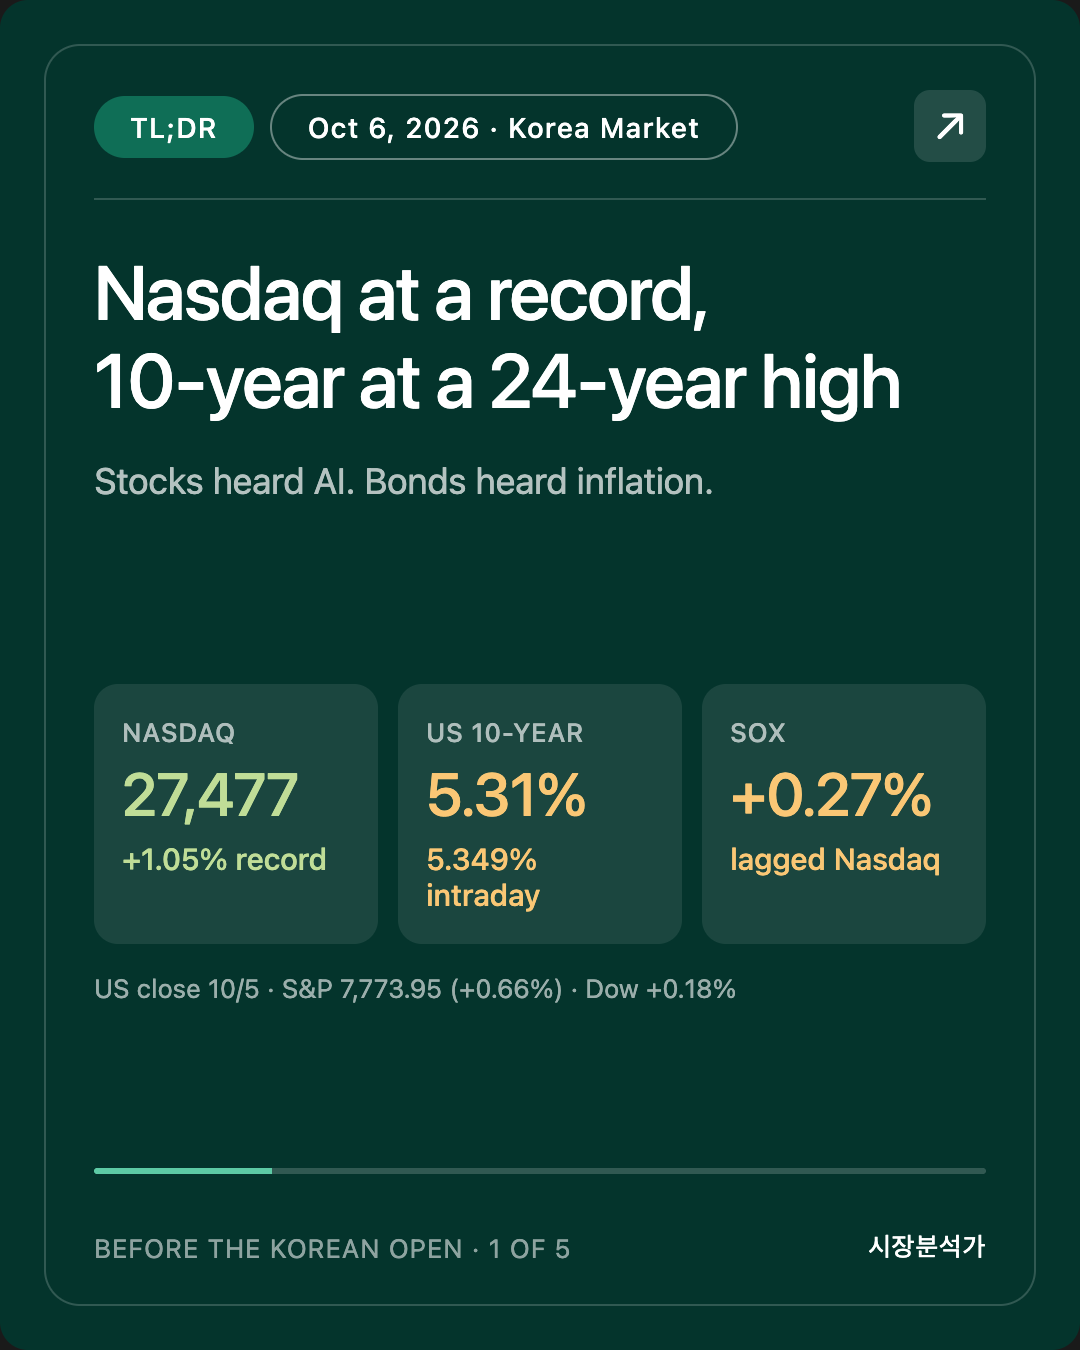
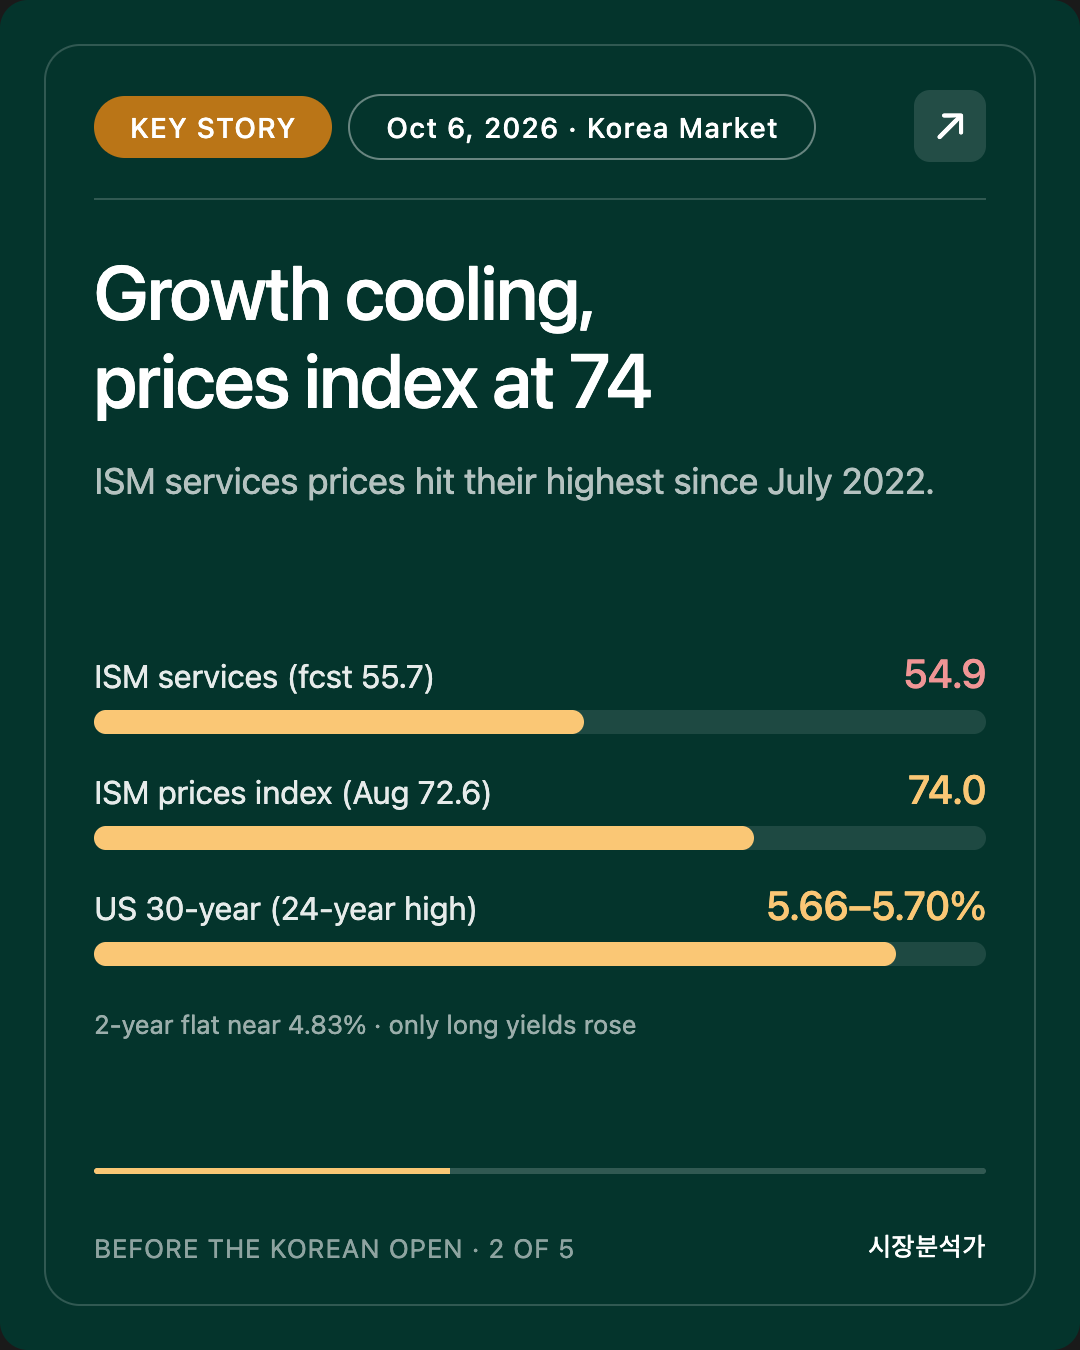
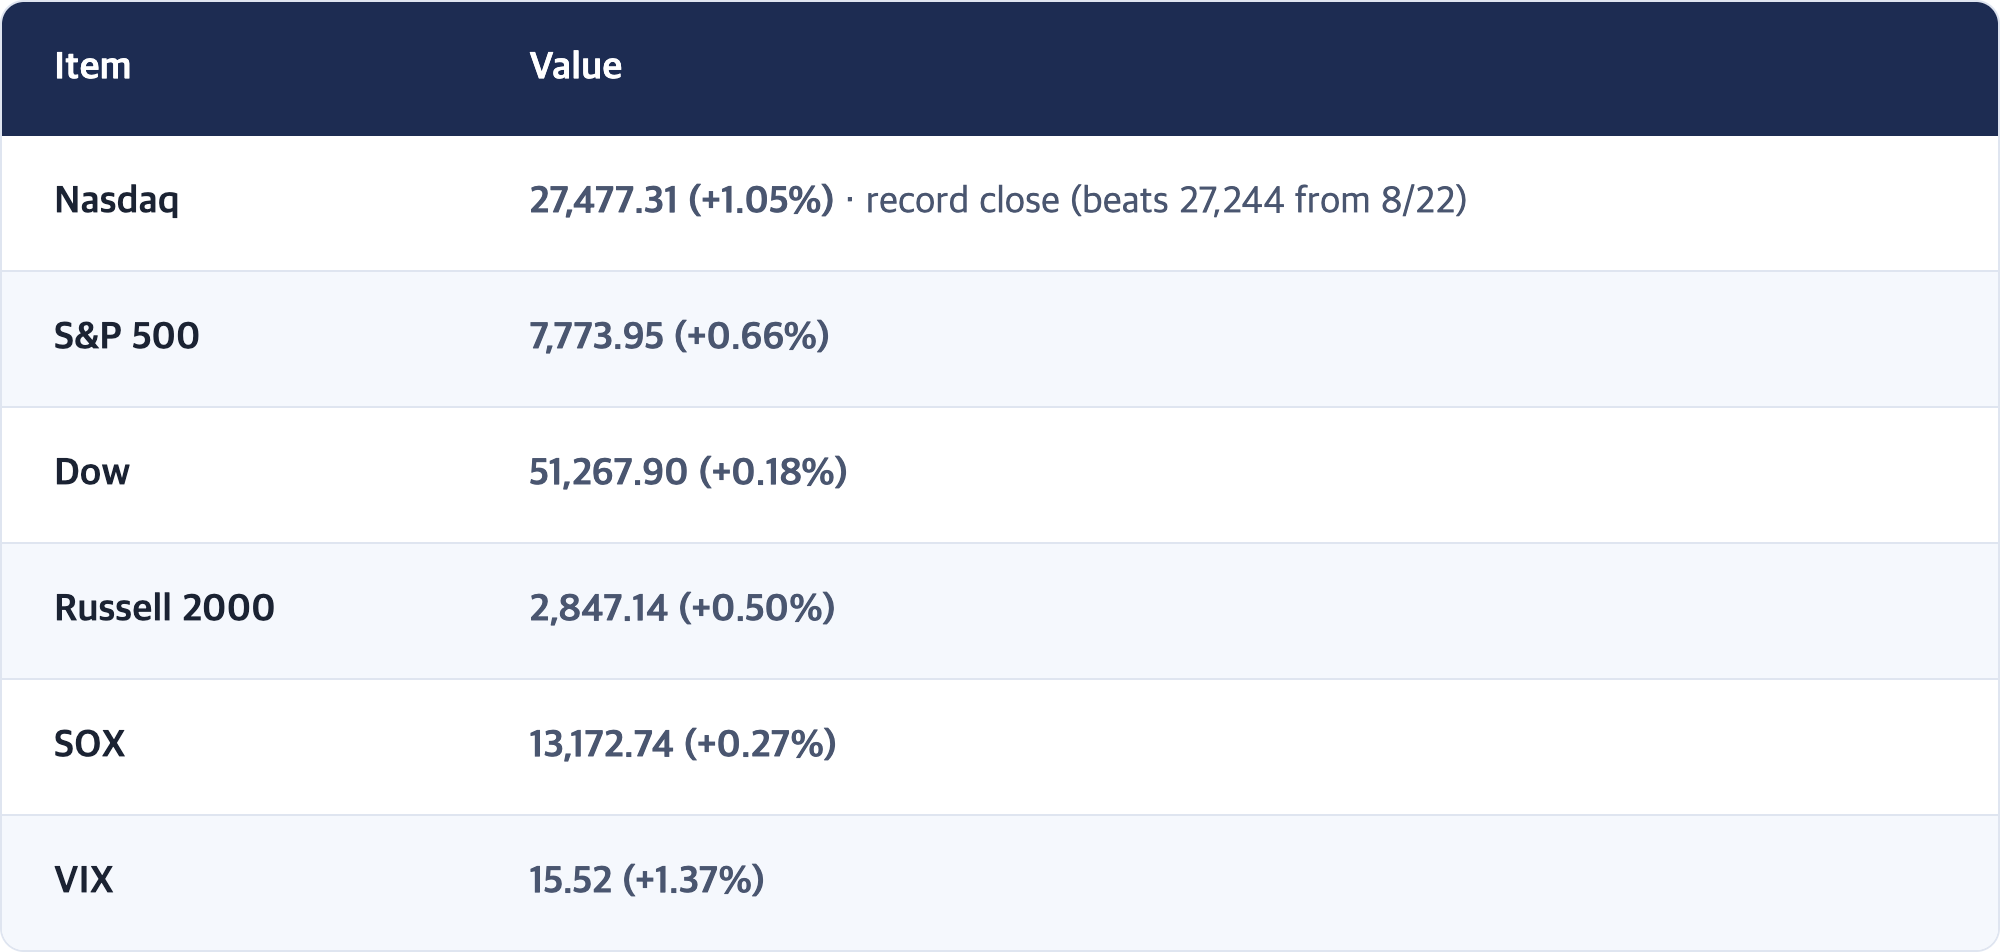
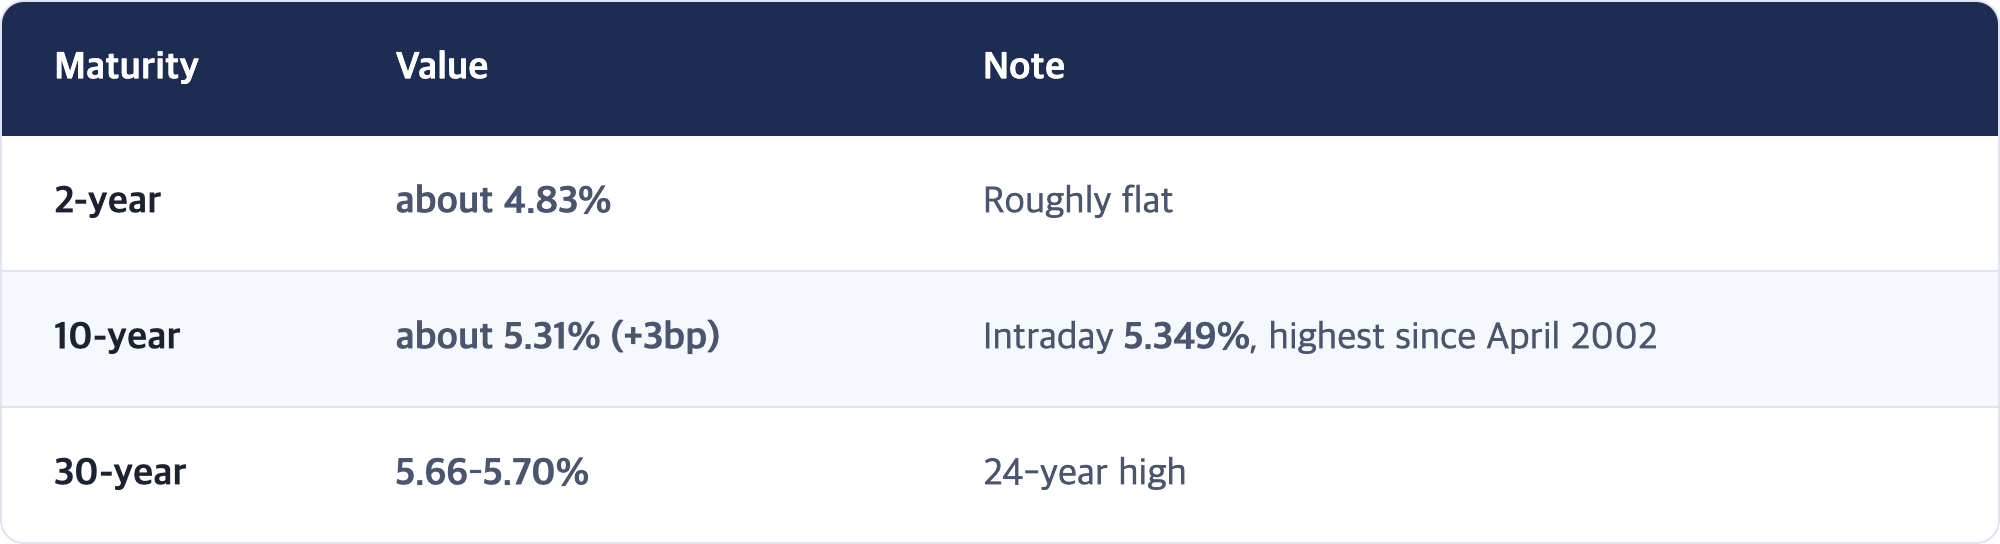
- ★ Stocks at a record, long yields at a record too. Nasdaq 27,477.31 (+1.05%, all-time high) · S&P 500 7,773.95 (+0.66%) · Dow 51,267.90 (+0.18%). Yet the 10-year closed near 5.31% (+3bp) after hitting 5.349%, the highest since April 2002. The 30-year: 5.66–5.70%.
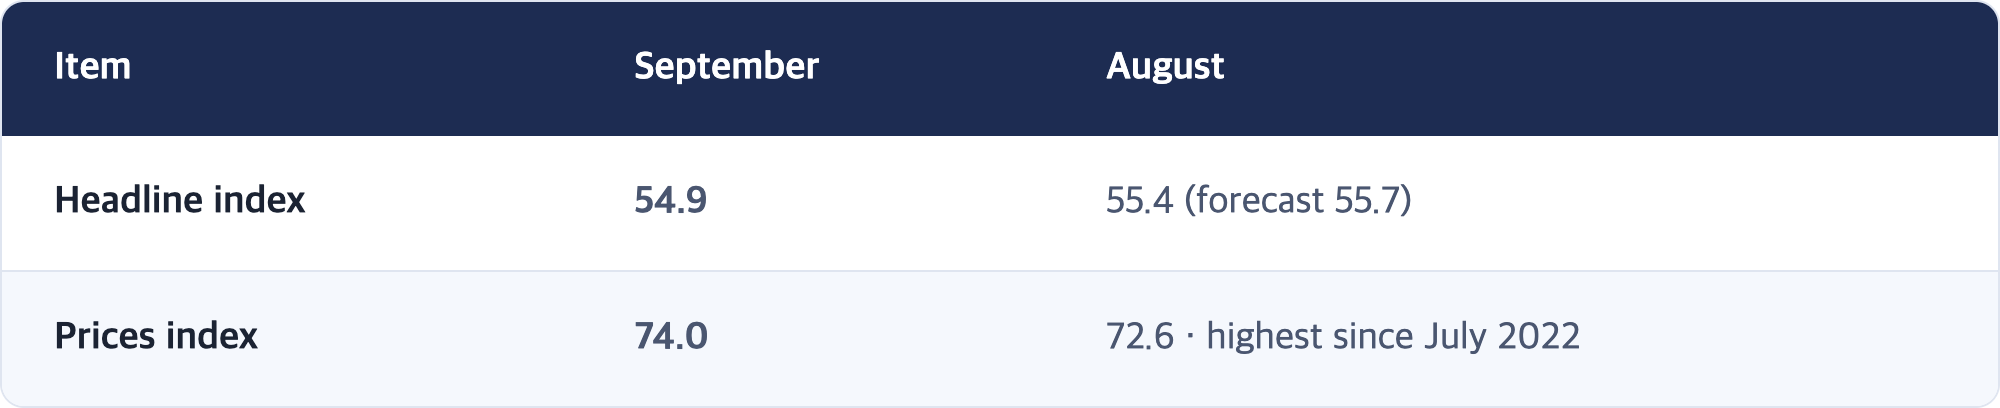
- ★ Bonds were listening to the ISM prices index. The September ISM services index slipped to 54.9 (August 55.4, forecast 55.7), but the prices index jumped to 74.0 (from 72.6), the highest since July 2022. Growth cooling, cost pressure building.
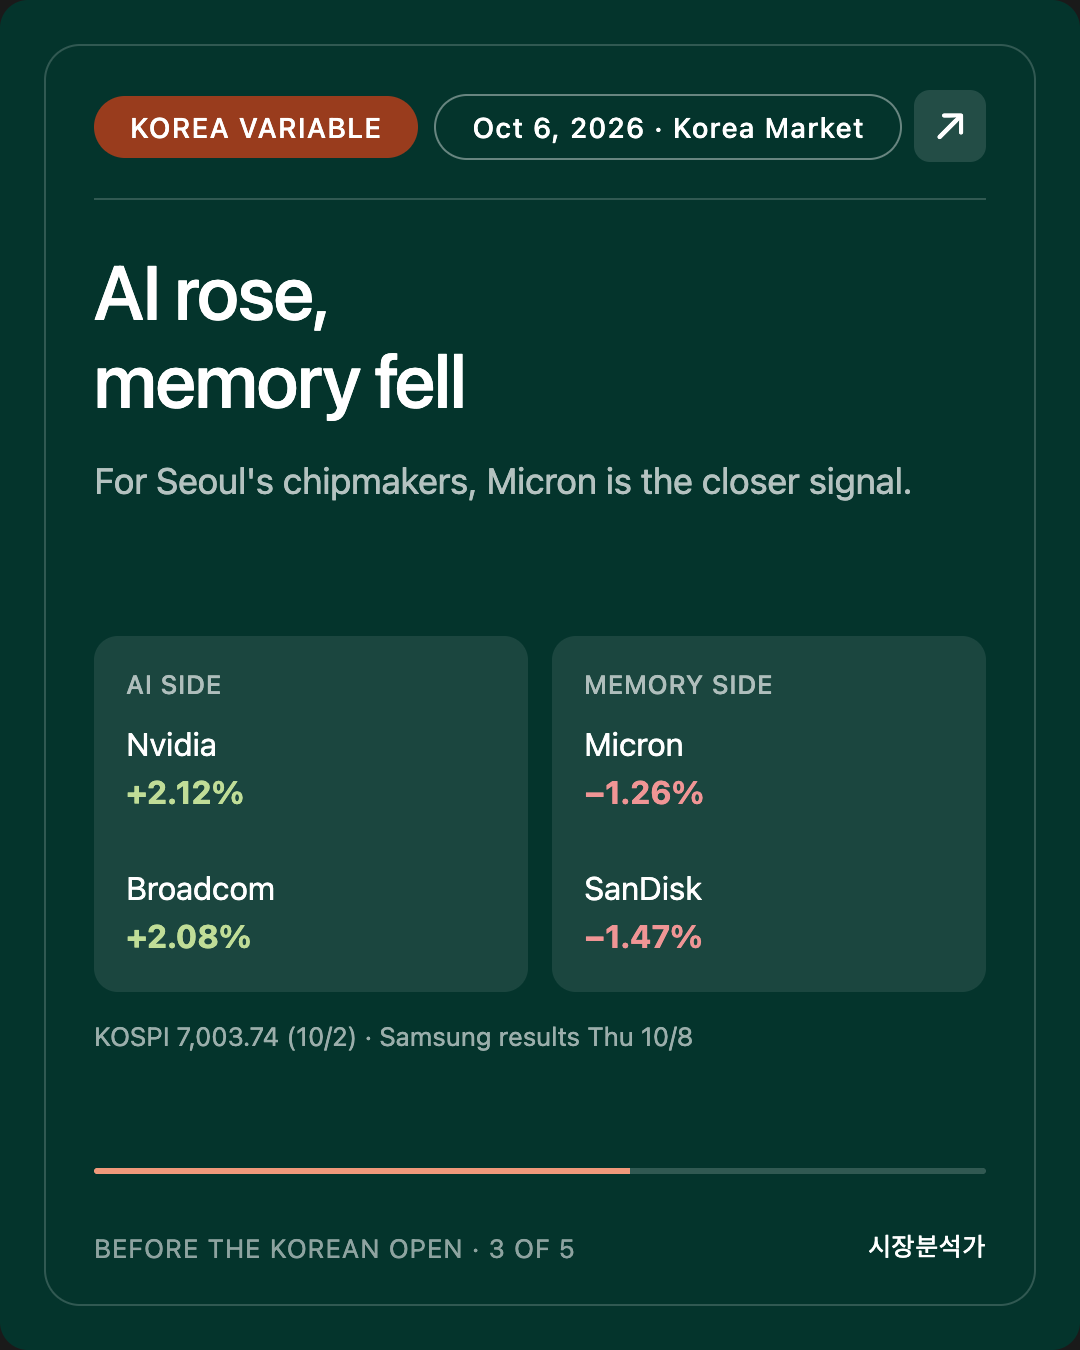
- ★ The chip sector split. Nvidia +2.12% (record) and Broadcom +2.08% versus Micron −1.26%, SanDisk −1.47% and Intel −2.63%. SOX closed at 13,172.74 (+0.27%), far behind the Nasdaq. For Korea's memory-heavy chip sector, that is a mixed signal.
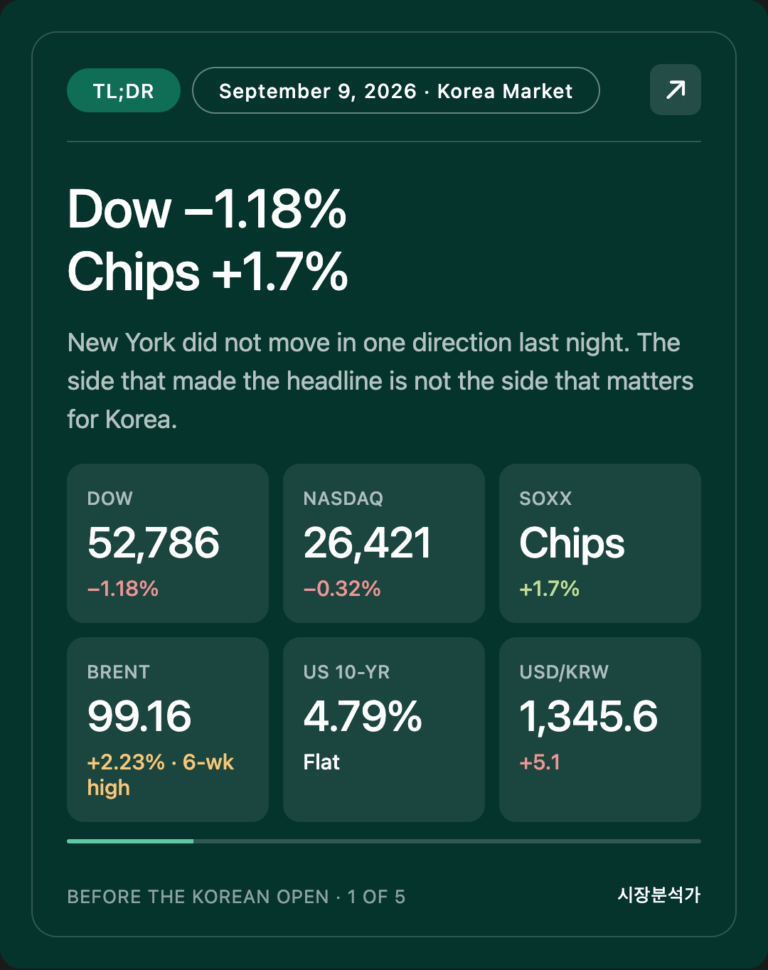
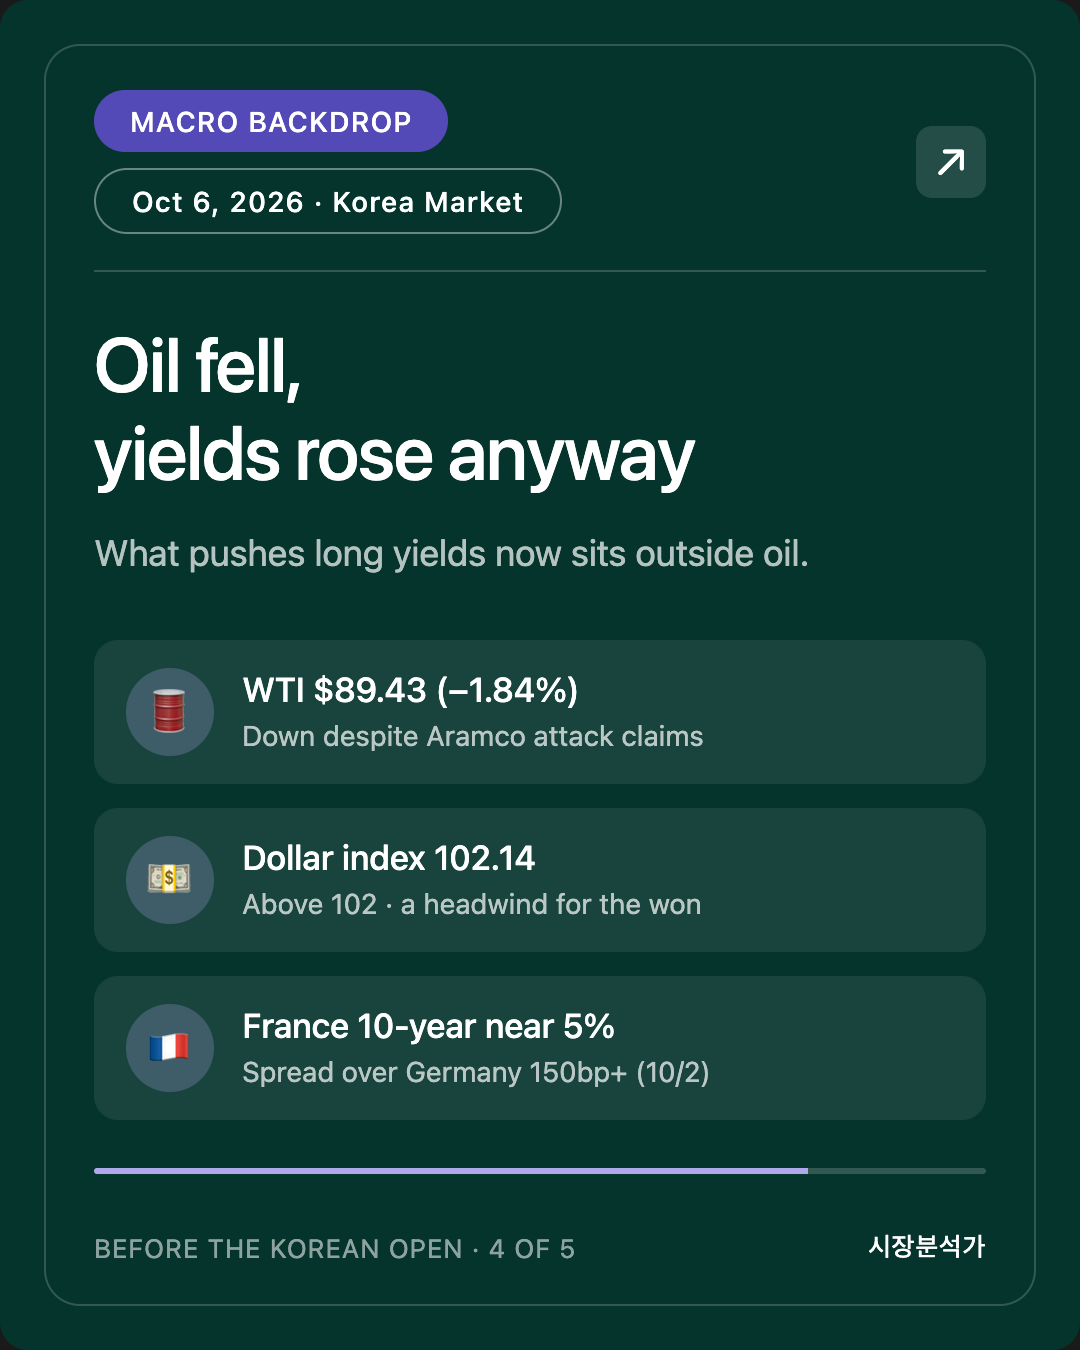
- Oil fell anyway. Despite Houthi claims of strikes on Saudi Aramco sites, WTI settled at $89.43 (−1.84%) and Brent fell about 1.8% (reported), near $100. The G7 reserve release and Aramco's price cut for Asian buyers outweighed the attack headlines. The dollar index rose to 102.14 (+0.20%).
- Seoul's question is unchanged, with one addition. Does foreign selling stop? And with Samsung's results due Thursday (operating-profit consensus about ₩108.1 trillion, per WiseReport), does Seoul follow Wall Street's memory weakness?
This is Mr. Can. Here is the Oct 6, 2026 brief ahead of the Korean market open.
Written: 2026-10-06 08:15 KST (Vancouver 10/5 16:15 PDT)
Basis: US regular-session close for Mon 10/5 + ISM September services survey (10/5, 10:00 a.m. ET) + oil futures settlements on 10/5 + Seoul close for Fri 10/2 + Tokyo close for 10/5
🟢 Scheduled 16:00 PDT, started 16:01 PDT. On time.
🟡 Seoul reopens today after four days. Korea was closed Monday for the National Foundation Day substitute holiday and closes again Friday 10/9 for Hangul Day. That leaves a three-day week (Tue–Thu), and Samsung Electronics reports preliminary Q3 results on the last of those days, Thursday 10/8.
SEO Intro
Wall Street set two records on Monday, and they pointed in opposite directions. The Nasdaq closed at an all-time high of 27,477.31 (+1.05%), and Nvidia logged a record close. At the same time the 10-year Treasury yield touched 5.349% intraday, the highest since April 2002, and the 30-year traded around 5.66–5.70%, also a 24-year high.
Stocks and bonds were listening to different news. Stocks heard Friday's jobs miss (just 29,000 payrolls) and concluded there will be no October rate hike. Bonds heard Monday's ISM services prices index of 74.0, the highest since July 2022. Even inside the chip sector the market split: Nvidia and Broadcom rose more than 2%, while memory names Micron (−1.26%) and SanDisk (−1.47%) fell, leaving the Philadelphia Semiconductor Index (SOX) up only 0.27%. Seoul, home to the world's two largest memory makers, absorbs all of this at once this morning.
1. Checkpoint Scorecard
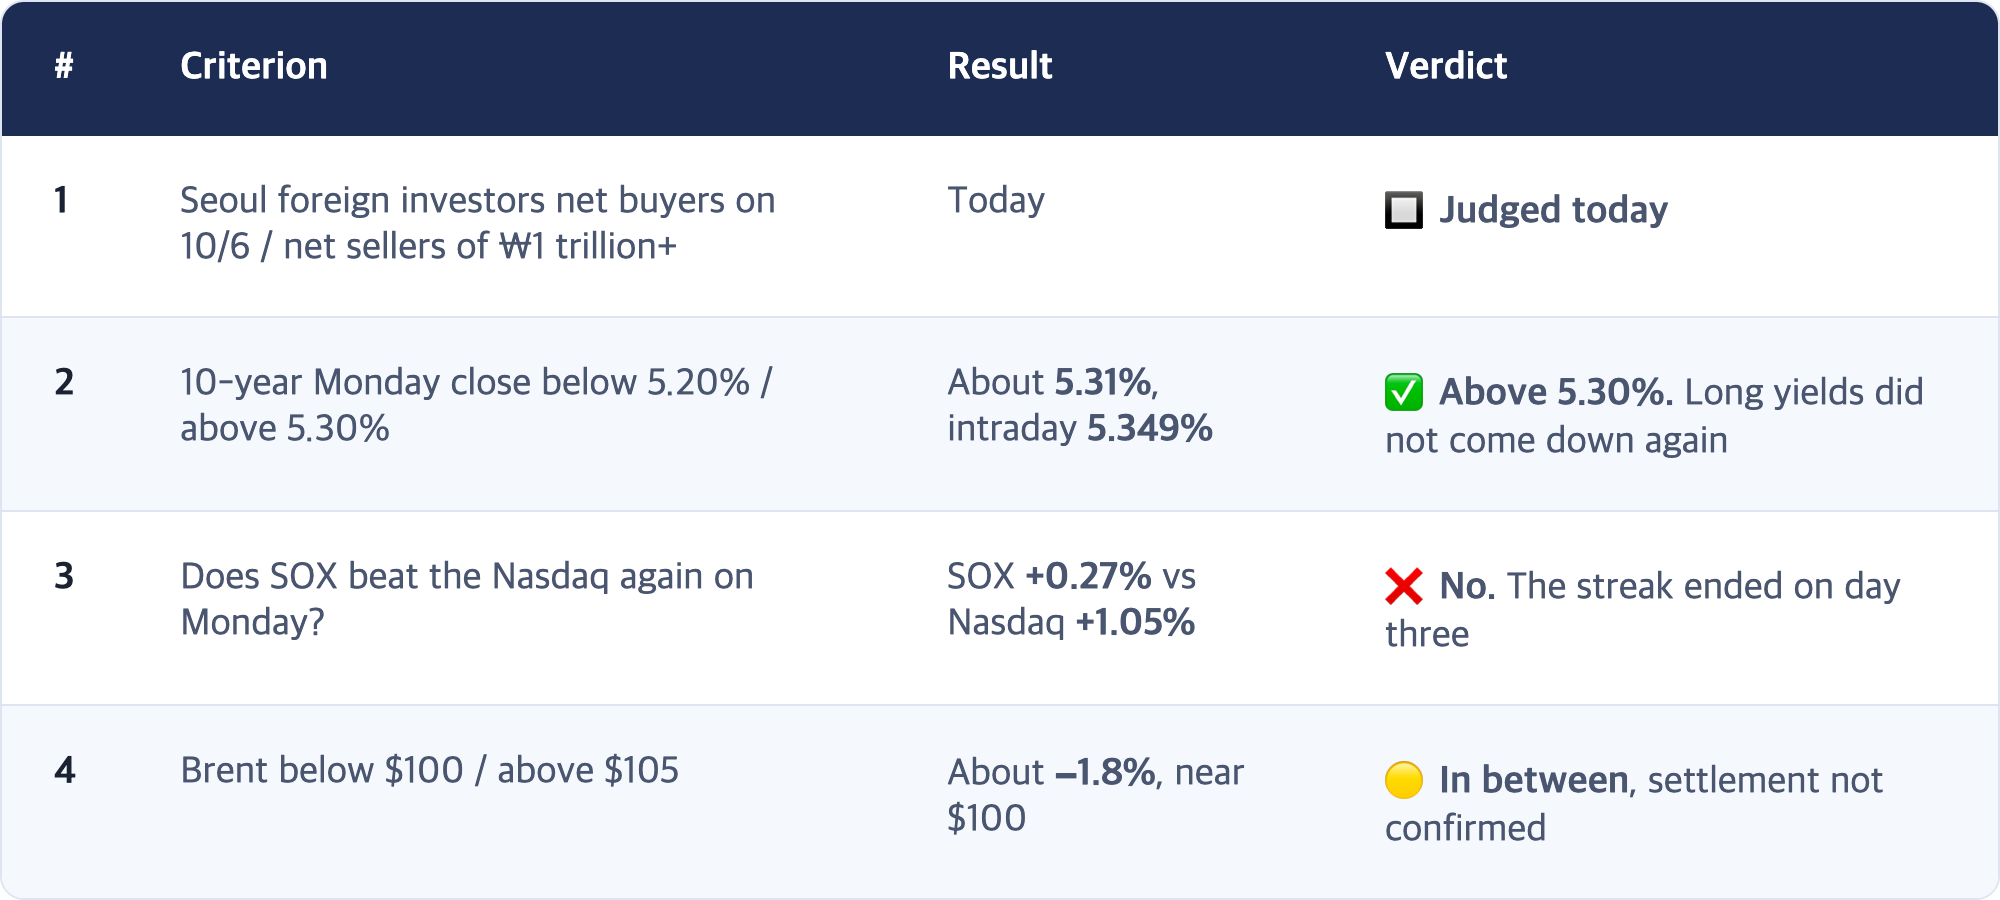
The four set in the 10/4 PM brief (No. 1 is judged at today's Seoul close)
The question was: "Does the jobs shock finally pull long yields down, or does it again move only the short end?"
The four set in the 10/5 AM brief (US close on 10/5)
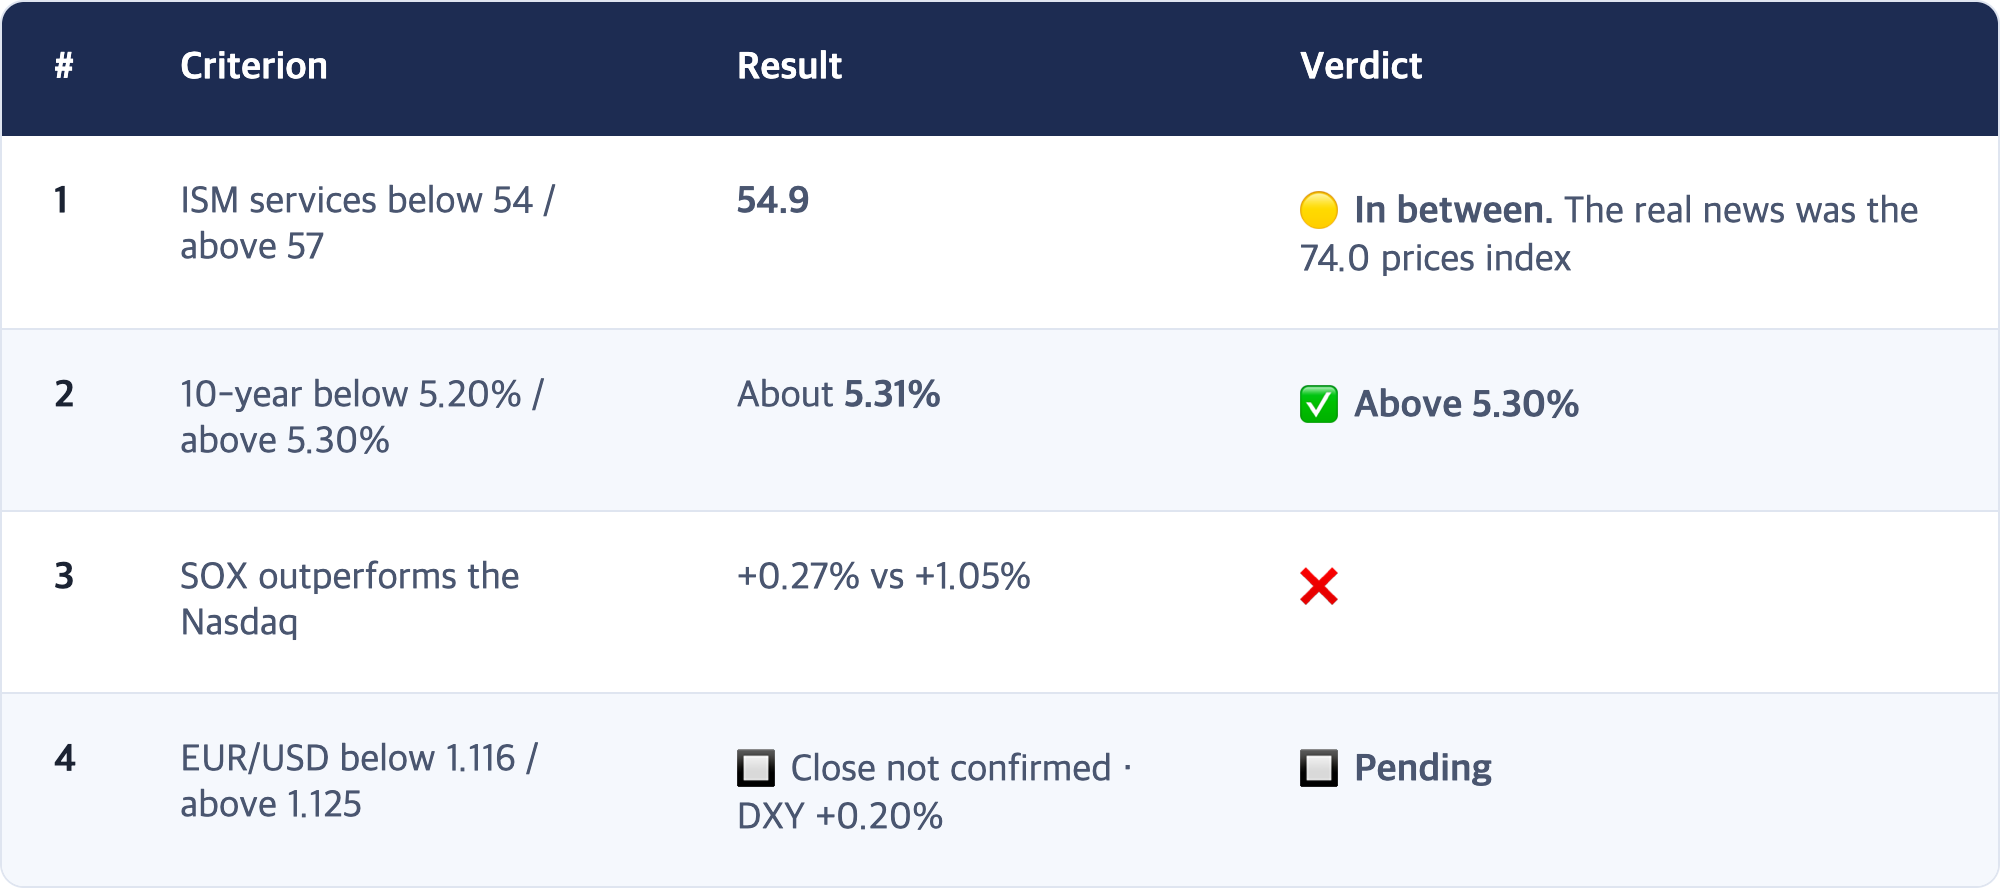
[Interpretation] No. 2 gave the same answer for the fourth time
Weak consumer confidence on 9/29, soft inflation on 9/30, a jobs miss on 10/2, and now the ISM on 10/5. Four straight days that "should" have pulled long yields lower, and each time the 10-year rose. This time the reason was clearer: a 74.0 prices index. If cost pressure persists while growth cools, the Fed can delay a hike from October to December but not cancel it. The 10/4 PM brief's read, "the hike was postponed, not removed", got a number to back it up within a day.
2. Today's Key Story: Stocks Heard AI, Bonds Heard Inflation
[Fact] US close, Monday 10/5 (05:00 KST Tuesday)
[Fact] Treasuries (around the 10/5 close)
[Fact] ISM September services (10/5, 10:00 a.m. ET)
★ [Interpretation] Two markets in one day
The equity story: hiring has slowed, so no October hike, so buy AI megacaps. Nvidia +2.12%, Meta +1.90%, Microsoft +1.48%, Tesla +2.20%. SpaceX jumped more than 7%.
The bond story: growth has cooled a little, but service businesses are paying higher prices at the fastest pace in more than three years, so inflation will not fade easily, so investors want more yield to lend for ten or thirty years. That is why the 2-year (a proxy for near-term Fed expectations) barely moved while the 10- and 30-year rose. The short end believed "the Fed won't hike right away"; the long end worried that "inflation and deficits will last."
[Interpretation] A rule from our 9/18 brief applies again: when stocks and bonds are reacting to different variables, score them separately. Reading the Nasdaq record as "rate fears are over" captures only half the day. As one strategist told Yahoo Finance, the market "has had every reason to sell off, and it hasn't sold off yet."
[Observation] When a handful of AI megacaps carry the Nasdaq, the index overstates market breadth. The Dow's +0.18% and SOX's +0.27% are the other side of that picture.
3. The Korea Variable: Four Days of News, a Three-Day Week
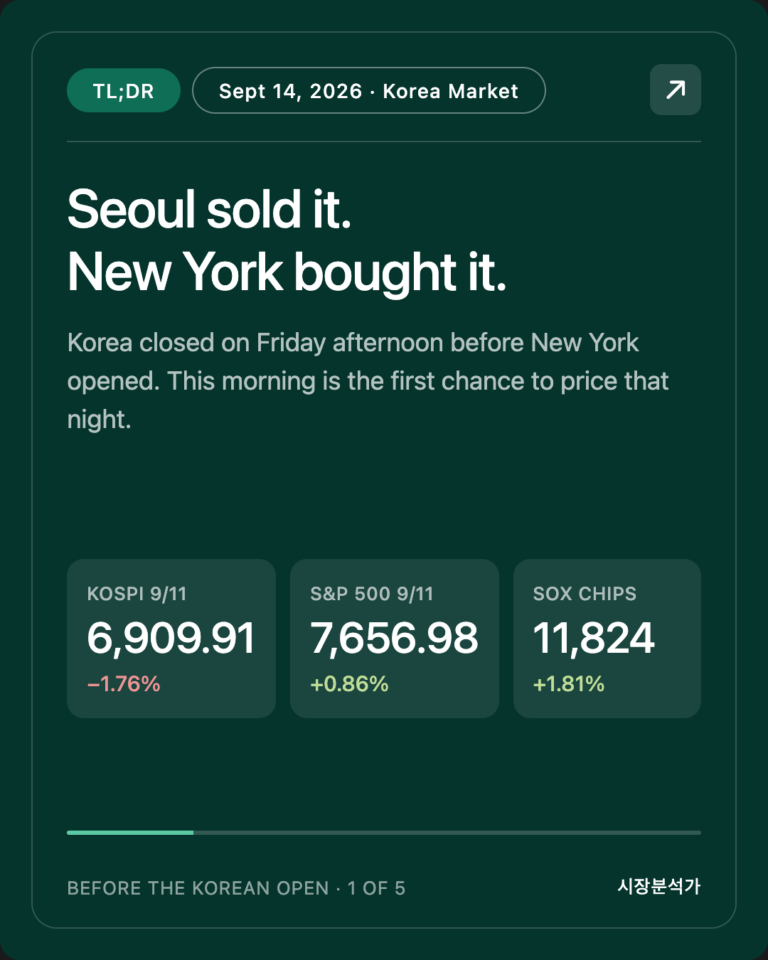
[Fact] Seoul's last close (Fri 10/2)
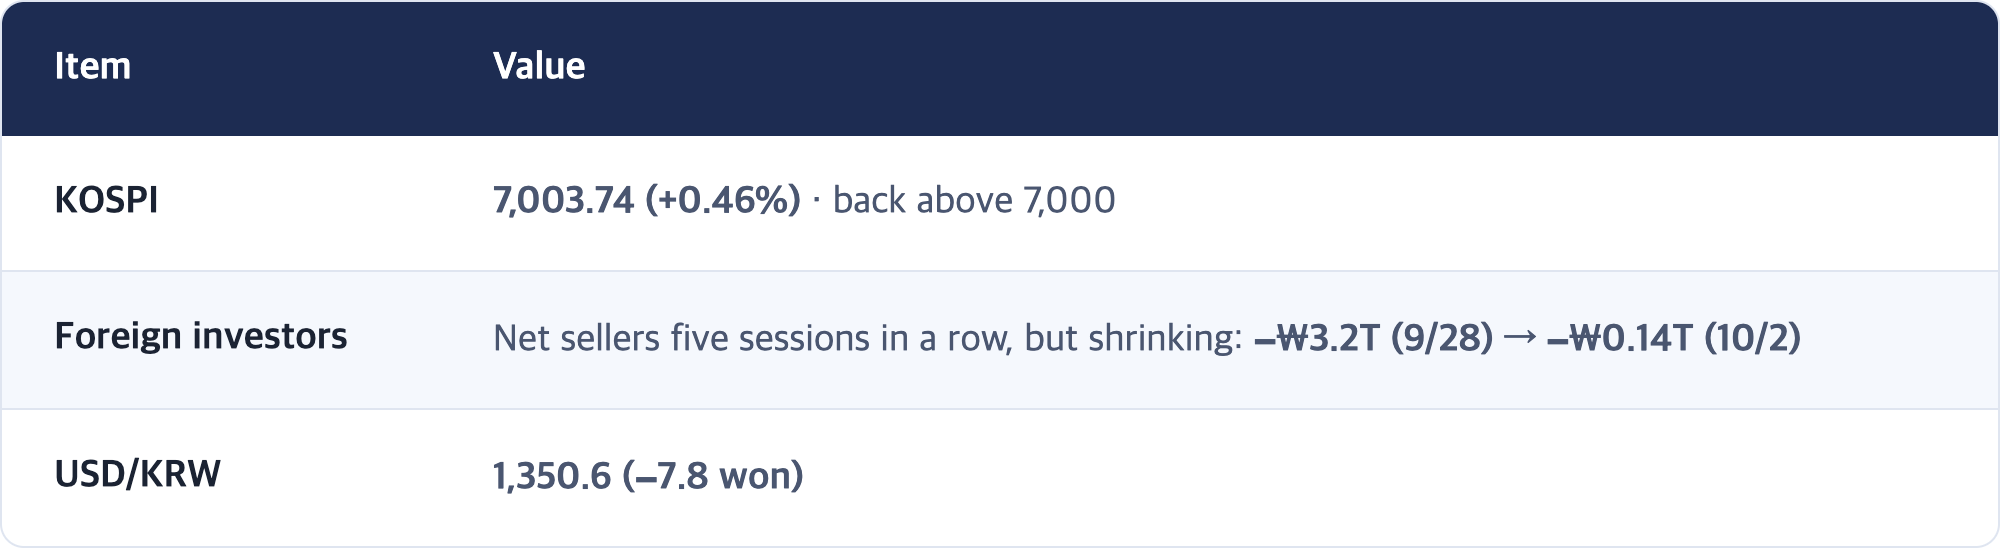
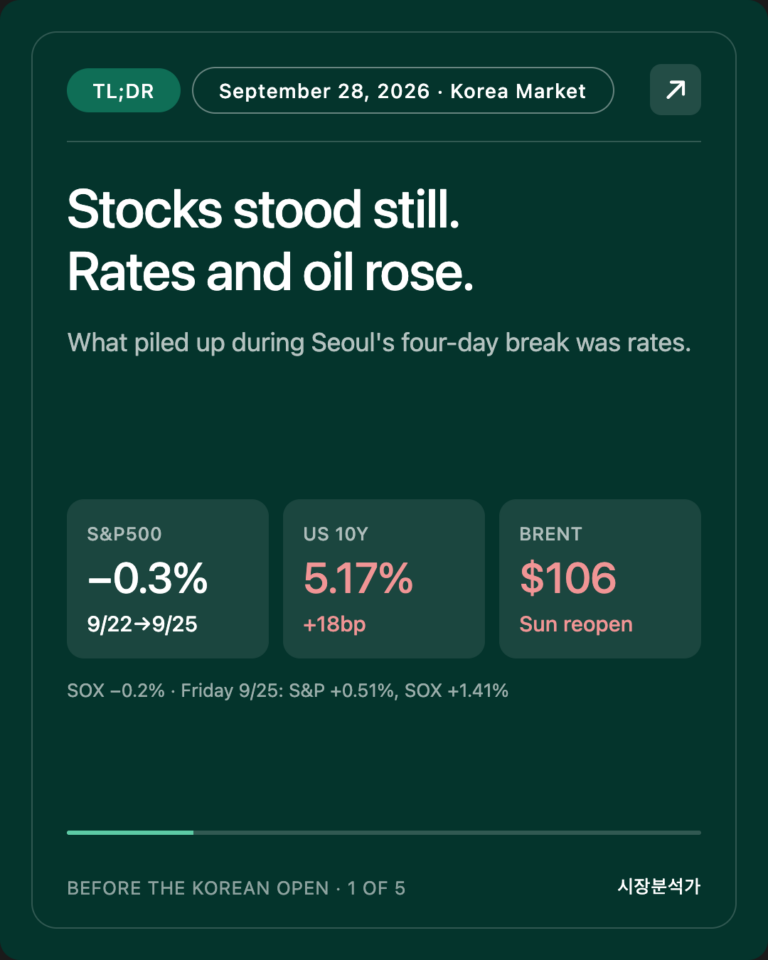
[Fact] What piled up while Seoul was closed
- Tokyo 10/5: Nikkei 69,946.86 (+2.40%), briefly above 70,000 on AI and chip megacaps
- New York 10/5: Nasdaq record · Nvidia record · memory stocks lower
- Dollar index 102.14 (+0.20%), above 102 · offshore USD/KRW NDF 🔲 not confirmed
- Samsung Electronics preliminary Q3 results due Thu 10/8 (reports). Consensus: revenue about ₩201.7 trillion, operating profit about ₩108.1 trillion (WiseReport). That would be the first ₩100 trillion quarterly operating profit by a Korean company.
★ [Interpretation] Two conflicting signals for Seoul's chipmakers
The positive side: Tokyo rallied to 70,000 on AI and chip megacaps, and Nvidia hit a record in New York. AI demand shows no sign of cracking.
The catch: inside that AI rally, only memory fell. Micron −1.26%, SanDisk −1.47%. Korea's two chip heavyweights, Samsung Electronics and SK hynix, are memory businesses at heart, so the signal closer to home is Micron, not Nvidia. With Samsung's numbers two days away, this looks like profit-taking on the question "is the good news already priced in?" [Observation] The 9/28 session, when foreign investors dumped Korean chip stocks heavily, started from a similar split.
Currency: the won strengthened to 1,350.6 on Friday, but the dollar index has since pushed above 102. If the won weakens again today, the bar for foreign investors to turn net buyers (Checkpoint 1) gets a little higher.
[Interpretation] The Korean commentators our readers follow tend to share one big-picture view: a long-term KOSPI uptrend built around semiconductors. Samsung's results this week will test that view with hard numbers. Today, though, is about positioning before the results, not the results themselves. Keeping the big picture and one day's flows separate is the trick this week.
4. Macro Backdrop: Oil Fell, and Long Yields Are Being Pushed From Outside Oil
[Fact] (10/5 close)
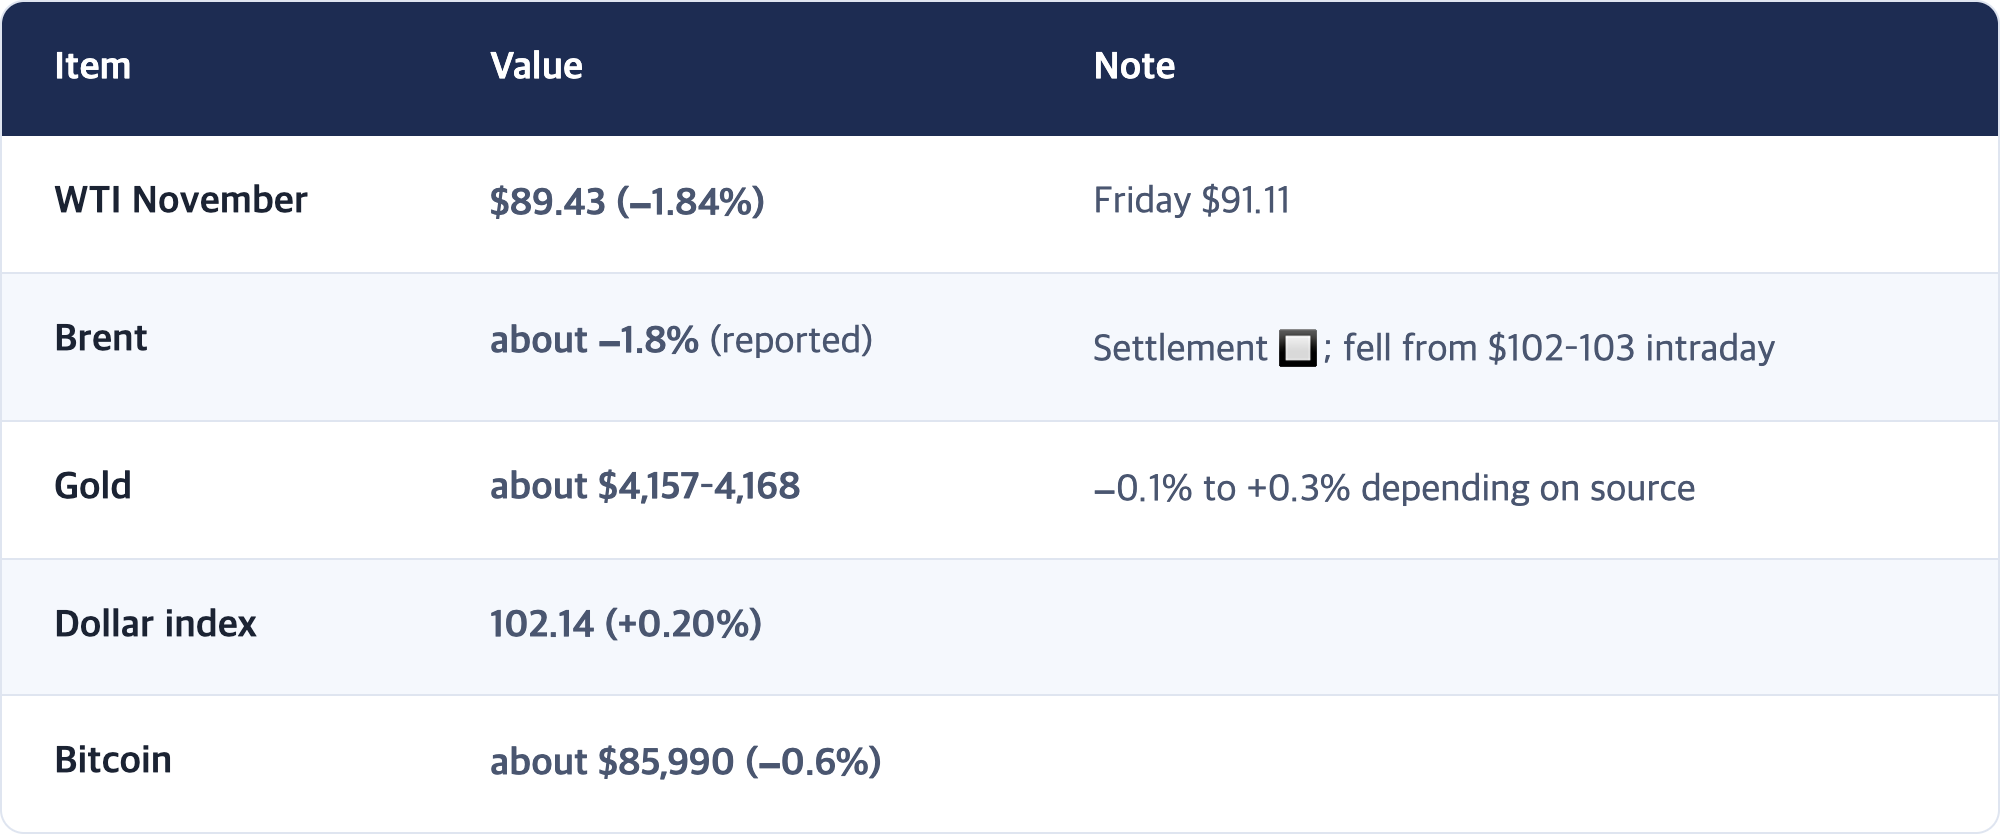
[Fact] What pushed oil down, and what held it up
- Down: the G7's 100-million-barrel reserve release (agreed 10/2), rising Middle East crude exports, and Aramco's November price cut for Asian buyers (Arab Light at the lowest premium since 2020, reported).
- Up: Houthi claims of attacks on Aramco sites in Riyadh and Khurais (10/4). Iran still says the Strait of Hormuz stays shut. Aramco's CEO said oil "would have hit $200" without the East-West pipeline (reported).
[Interpretation] Oil was not the culprit for higher yields
Oil fell nearly 2% on Monday while the 10-year rose. Through mid-September, "oil up, yields up" worked well; this week that link broke. The force pushing long yields is outside oil: service-sector inflation (ISM prices 74.0) and fiscal worries, in the US and in France, whose 10-year we flagged near 5% in the 10/5 AM brief. [Observation] France's 10-year briefly topped 5% on 10/2, with the spread over Germany above 150bp, the widest since late 2011 (Trading Economics). The 10/5 close is not confirmed.
5. Today's Korean Session (Tue 10/6 KST) Preview
The question
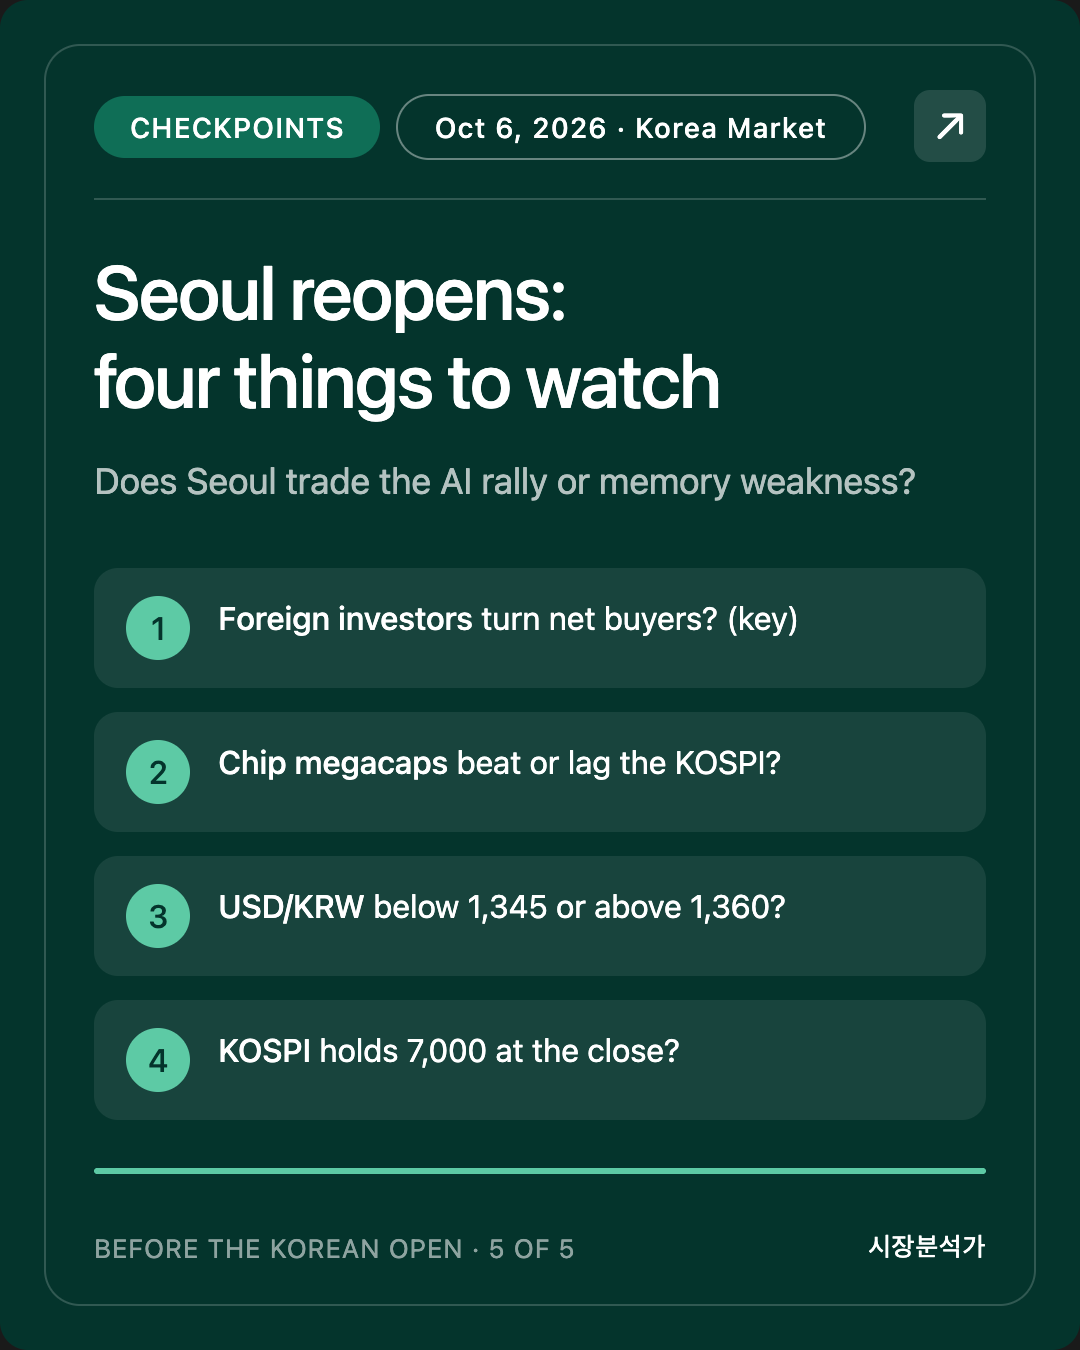
These four decide whether Seoul trades the Nasdaq's AI record, or memory weakness plus a 24-year high in long yields. The answer sets Seoul's starting line for Samsung's results on Thursday.
✅ Four checkpoints (judged at today's Seoul close)
- Foreign investors net buyers / net sellers of ₩1 trillion+. The question carried since the 10/4 PM brief. (Most important)
- Do chip megacaps beat or lag the KOSPI? Beat means Seoul listened to Nvidia; lag means it listened to Micron.
- USD/KRW below 1,345 / above 1,360. Below means Friday's won strength held; above means the dollar's push past 102 reached Seoul.
- Does the KOSPI hold 7,000 at the close? The level failed three times in September and was reclaimed on 10/2.
[Interpretation] The most informative pairing is 1 and 2. Foreign buying plus chips beating the index reads as pre-earnings positioning for upside; foreign selling plus chips lagging reads as pre-earnings profit-taking. If they disagree, it is better to wait for Thursday's numbers.
6. Study Note: What Is the ISM "Prices Index," and Why Did Bonds Care?
The concept
The ISM services index is a monthly survey asking purchasing managers at US service companies whether conditions improved or worsened versus the prior month. Above 50 means more said "better." Within it, the prices index asks whether the goods and services the company buys got more expensive. A reading of 74.0 means an overwhelming share answered "yes."
An analogy
Imagine asking a hundred restaurant owners two separate questions: "How's business?" and "How are your ingredient costs?" Monday's answer was: "Business is a bit slower (54.9), but ingredients are rising faster than at any time in three years (74.0)." Owners like that eventually raise menu prices. That next step, consumer inflation, is what bond investors are worried about.
Real examples
- Summer 2022: with the ISM services prices index near 80, US CPI climbed above 9% and the Fed raised rates 0.75 points at a time.
- October 2026: 74.0 is the highest since July 2022. Unlike then, hiring is slowing, so the Fed must weigh slowing growth against price pressure at the same time. The next checkpoint is US September CPI on 10/14.
In one line
A survey's headline number shows the economy; its prices component previews inflation. On Monday, stocks read the headline and bonds read the prices line.
7. Corrections and Open Items
Corrections
- Samsung Q3 operating-profit consensus: the 10/5 AM brief cited about ₩106.9 trillion. This edition uses WiseReport's about ₩108.1 trillion (reported 10/4). We attribute the gap to different compilation dates.
- Samsung results date: the 10/5 AM brief gave a range of 10/7–10/8 KST. Most reports point to Thursday 10/8, which we adopt (one outlet says 10/7).
Source differences (value used in the text)
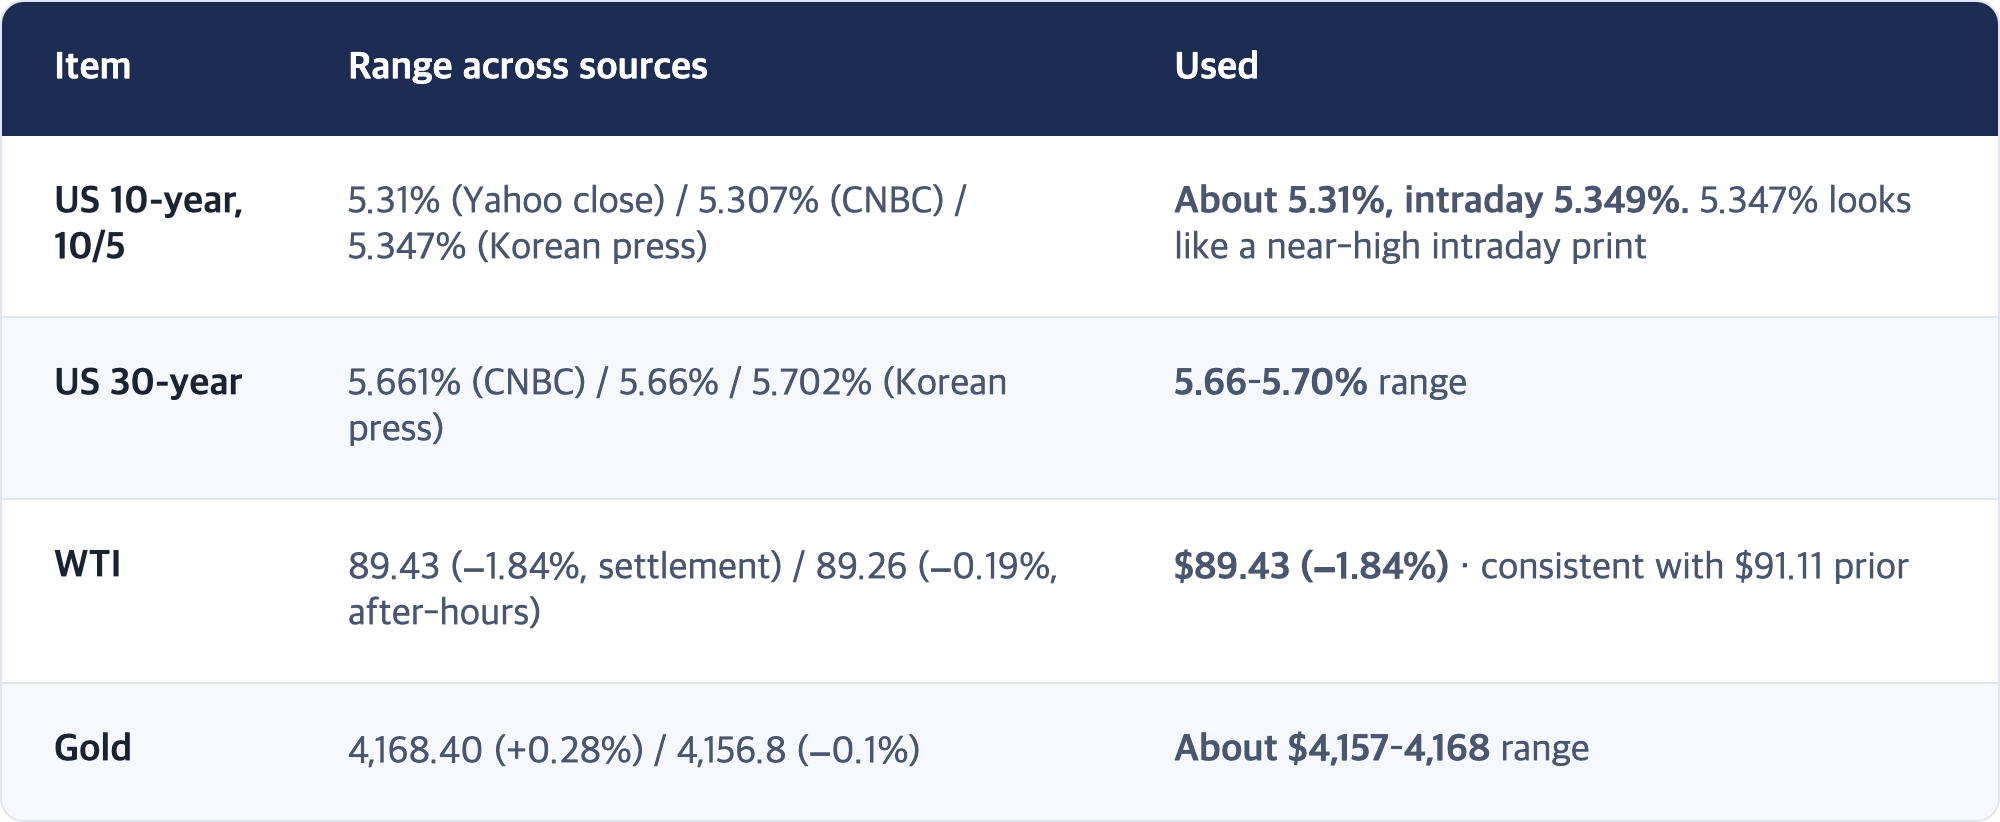
🔲 Not yet confirmed
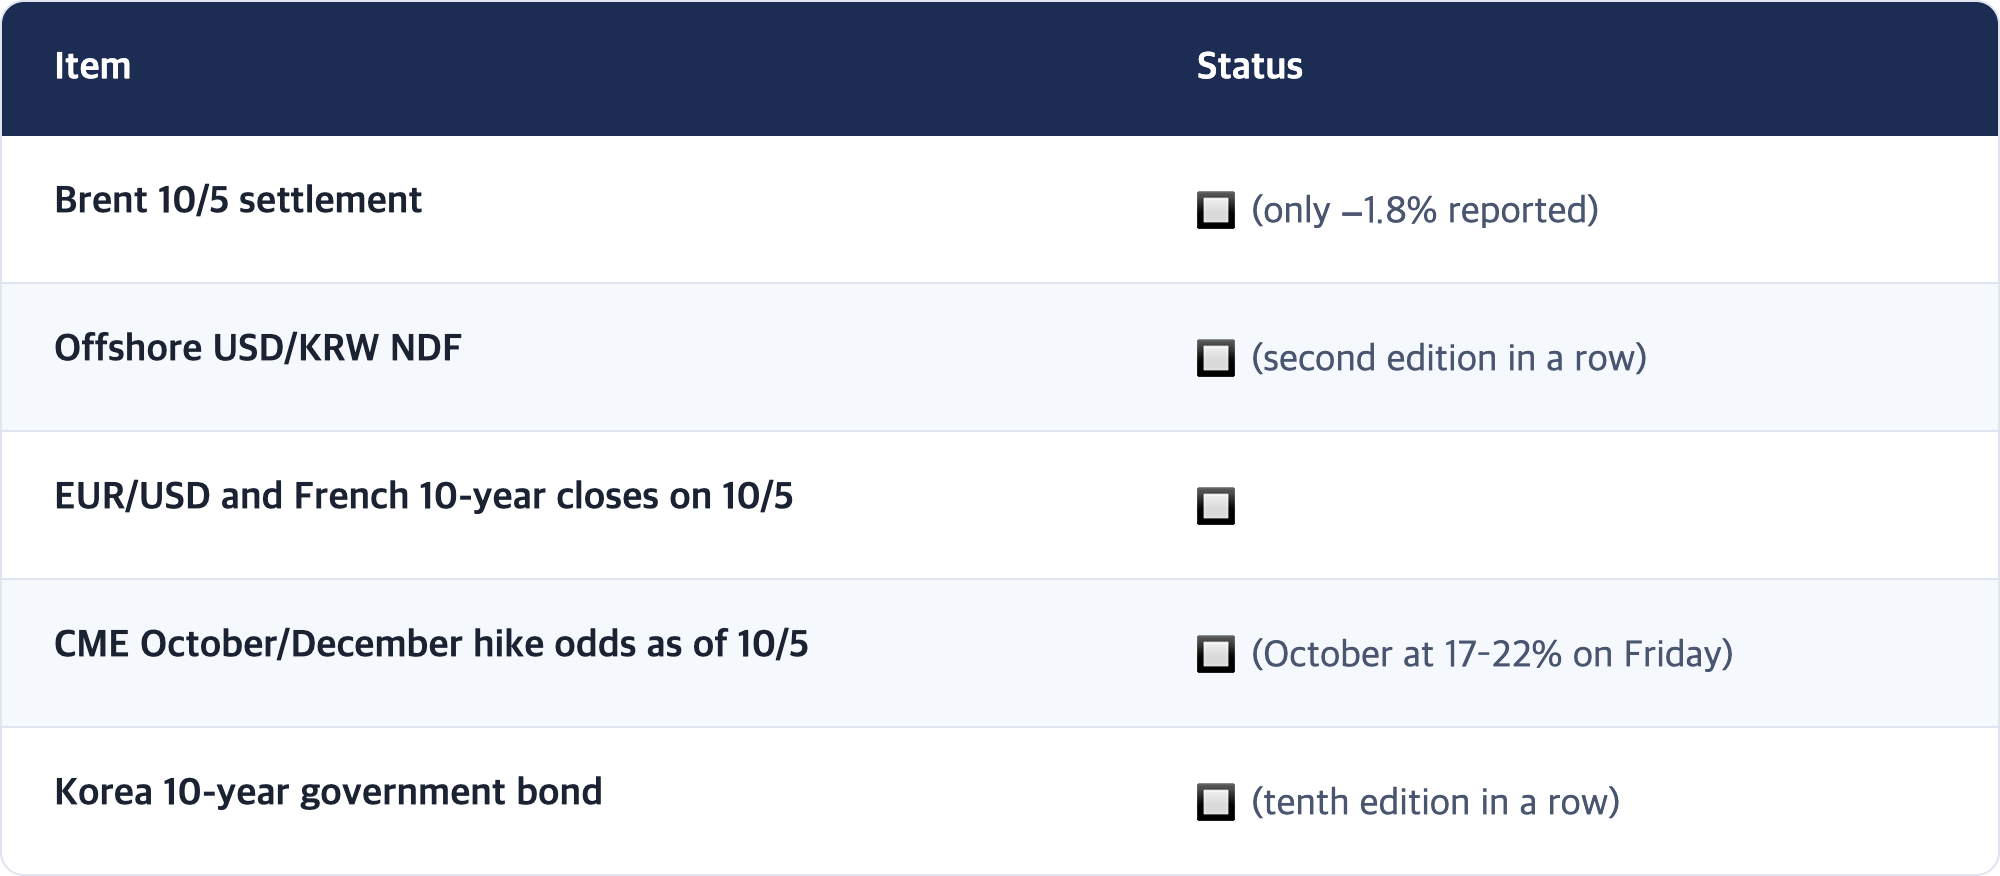
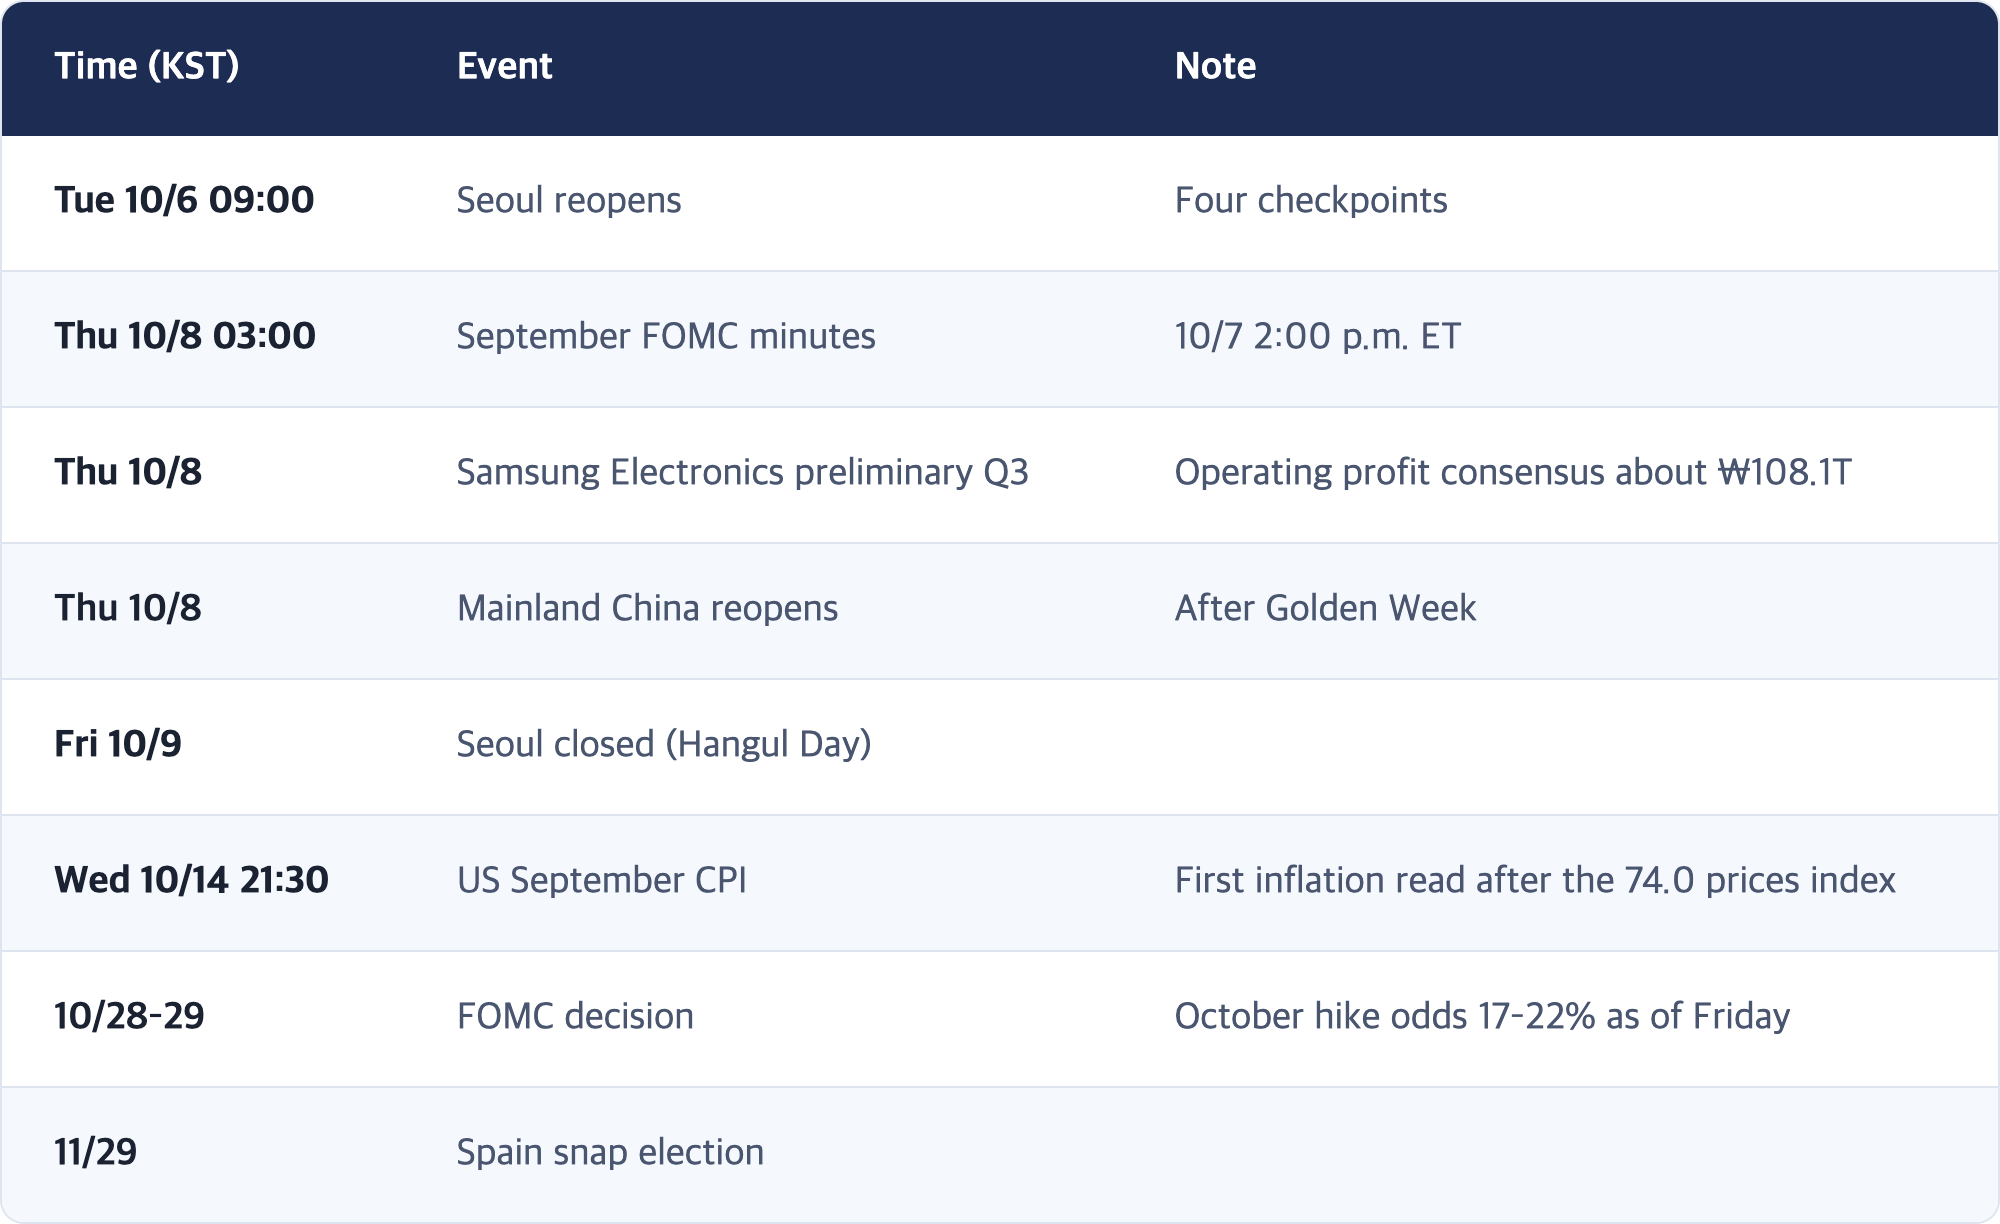
8. Event Calendar (KST)
Sources
- Stock market today: Nasdaq, Nvidia post record highs as tech strength outshines bond weakness | Yahoo Finance
- Stock Market Today (Oct. 5, 2026): S&P 500 moves higher, yields higher after ISM data | TheStreet
- 10-year Treasury yield rises to fresh 2002 high to start the week | CNBC
- US Treasury yields scale multi-year highs as inflation fears return | FXStreet
- AI rally eases rate fears; chip stocks diverge | Seoul Finance (Korean)
- Nasdaq hits record despite higher Treasury yields | Korea Economic TV (Korean)
- Oil prices split as Brent tops $102, Murban hits $110 per barrel on Oct. 5, 2026 | Gulf News
- Oil slips toward $102 as G7 stock release and rising Gulf exports offset Houthi attacks | investingLive
- Oil prices would have hit $200 a barrel if not for East-West pipeline, Aramco chief says | The National
- Brent oil | Trading Economics
- French 10-Year Bond Yield Briefly Tops 5% | Trading Economics
- Samsung set for ₩100 trillion quarterly profit; Q3 results this week | Daum News (Korean)
- Samsung Q3 results D-3 | Money Today (Korean)
- Asian stocks rise as US October hike bets fade; Nikkei +2.4% | eToday (Korean)
Market Analyst · We do not make buy or sell recommendations on individual stocks. This brief offers macro context and interpretation.
📌 More market briefs
※ This post is market observation and organization intended to support your own judgment. It is not a recommendation to buy or sell any security. Figures are as of the time of writing and may differ between sources.
If this was useful, bookmark it or pass it along. It genuinely helps me write the next one.
I can survive. We can survive.