October 5, 2026 US Market Brief — Nasdaq and S&P 500 Before the Open
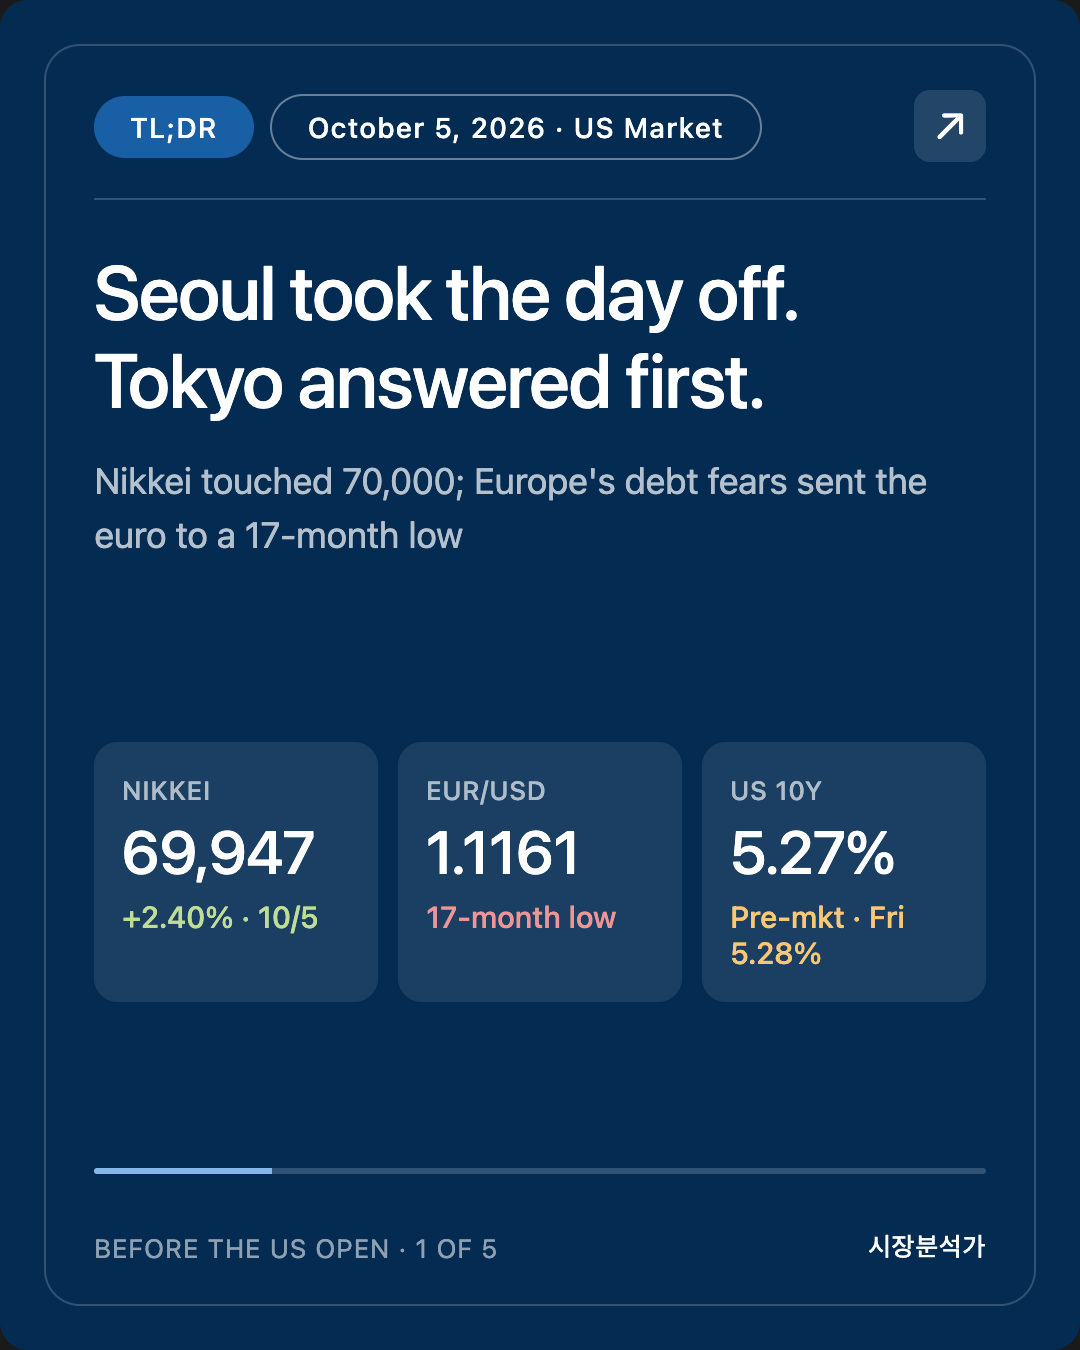
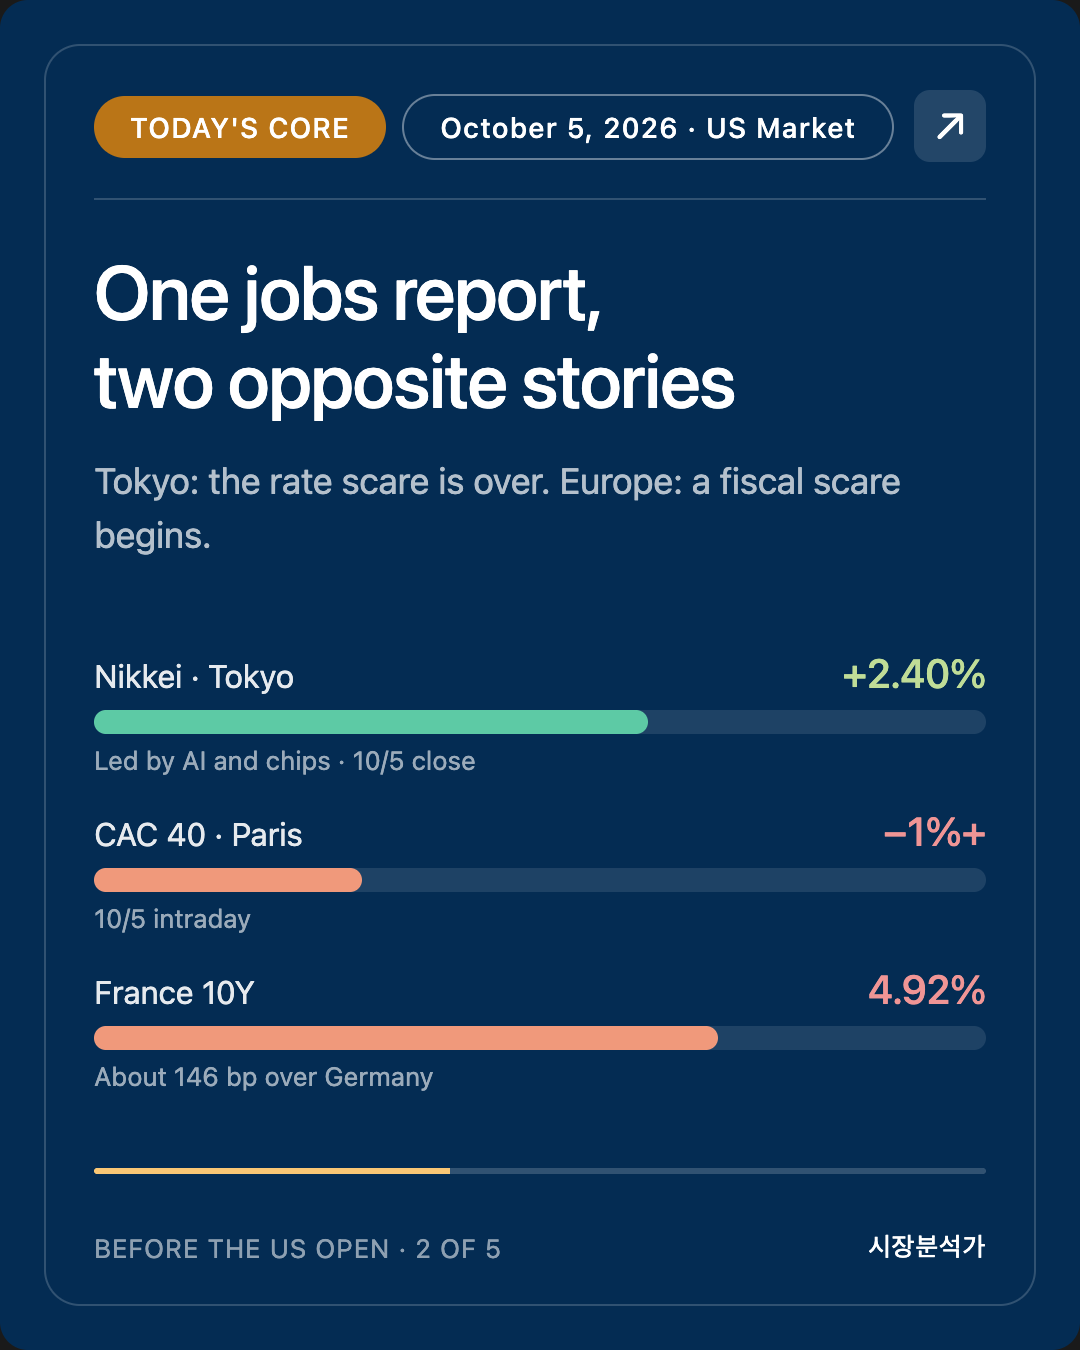
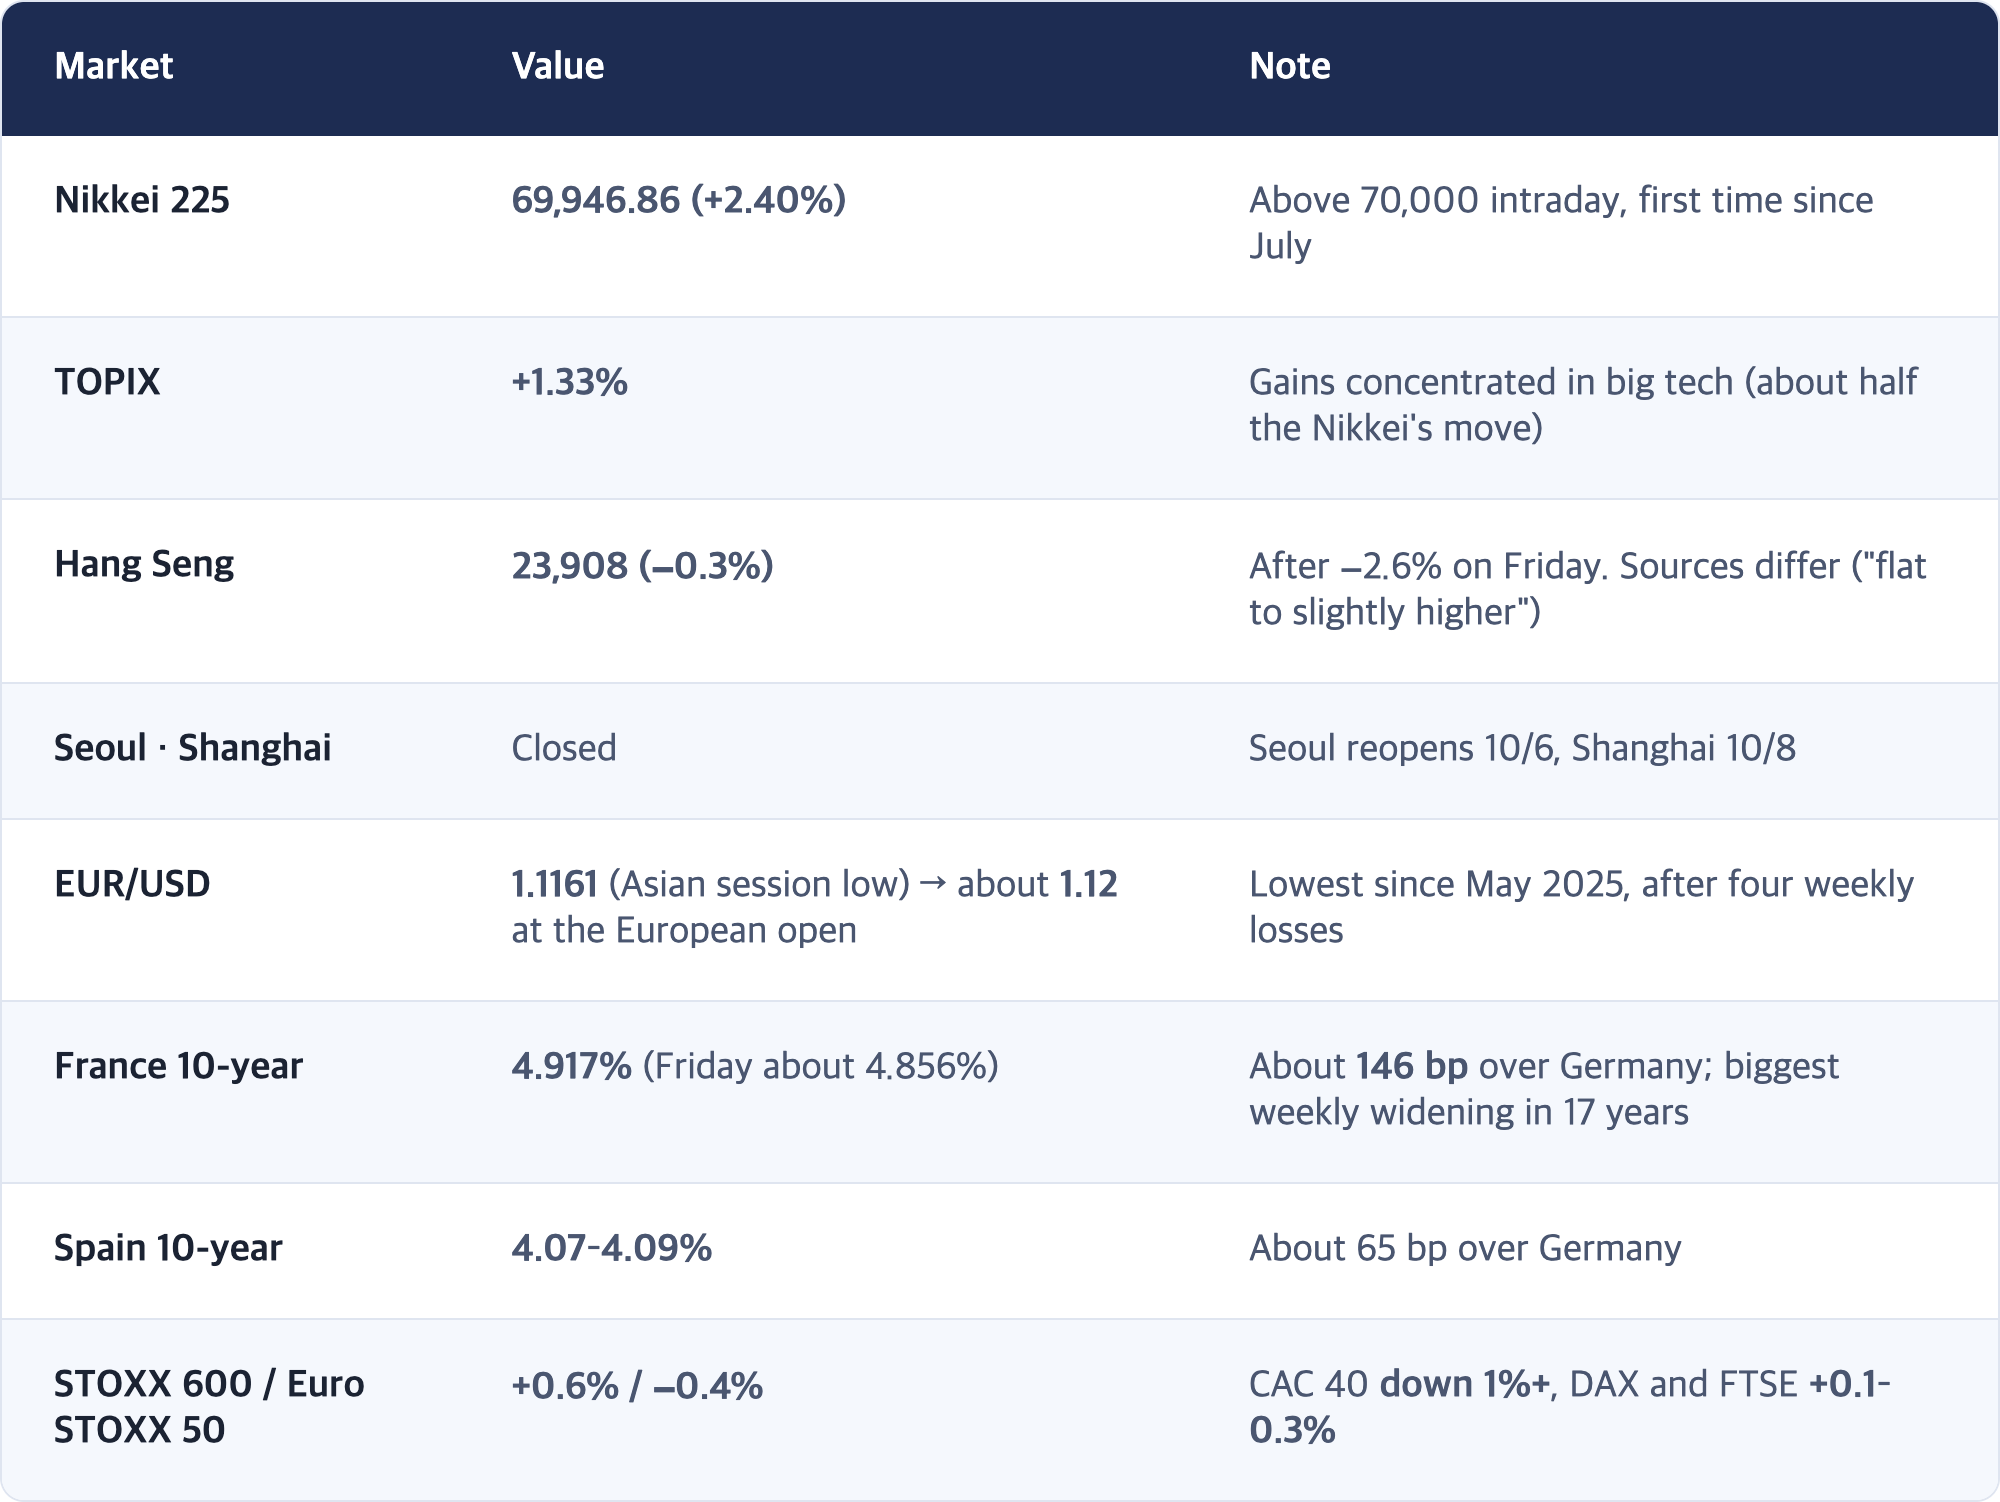
- ★ Tokyo bought on Seoul's behalf. Nikkei 69,946.86 (+2.40%), briefly above 70,000. TOPIX +1.33%. The driver: October Fed hike odds below 20% (CME, versus 64% a week earlier) plus AI and semiconductor megacaps.
- ★ Europe has a new problem. EUR/USD 1.1161 (17-month low), French 10-year 4.92%, spread over Germany about 146 bp. Spain calls a snap election for 11/29. CAC 40 down more than 1%, while the broader STOXX 600 is +0.6%.
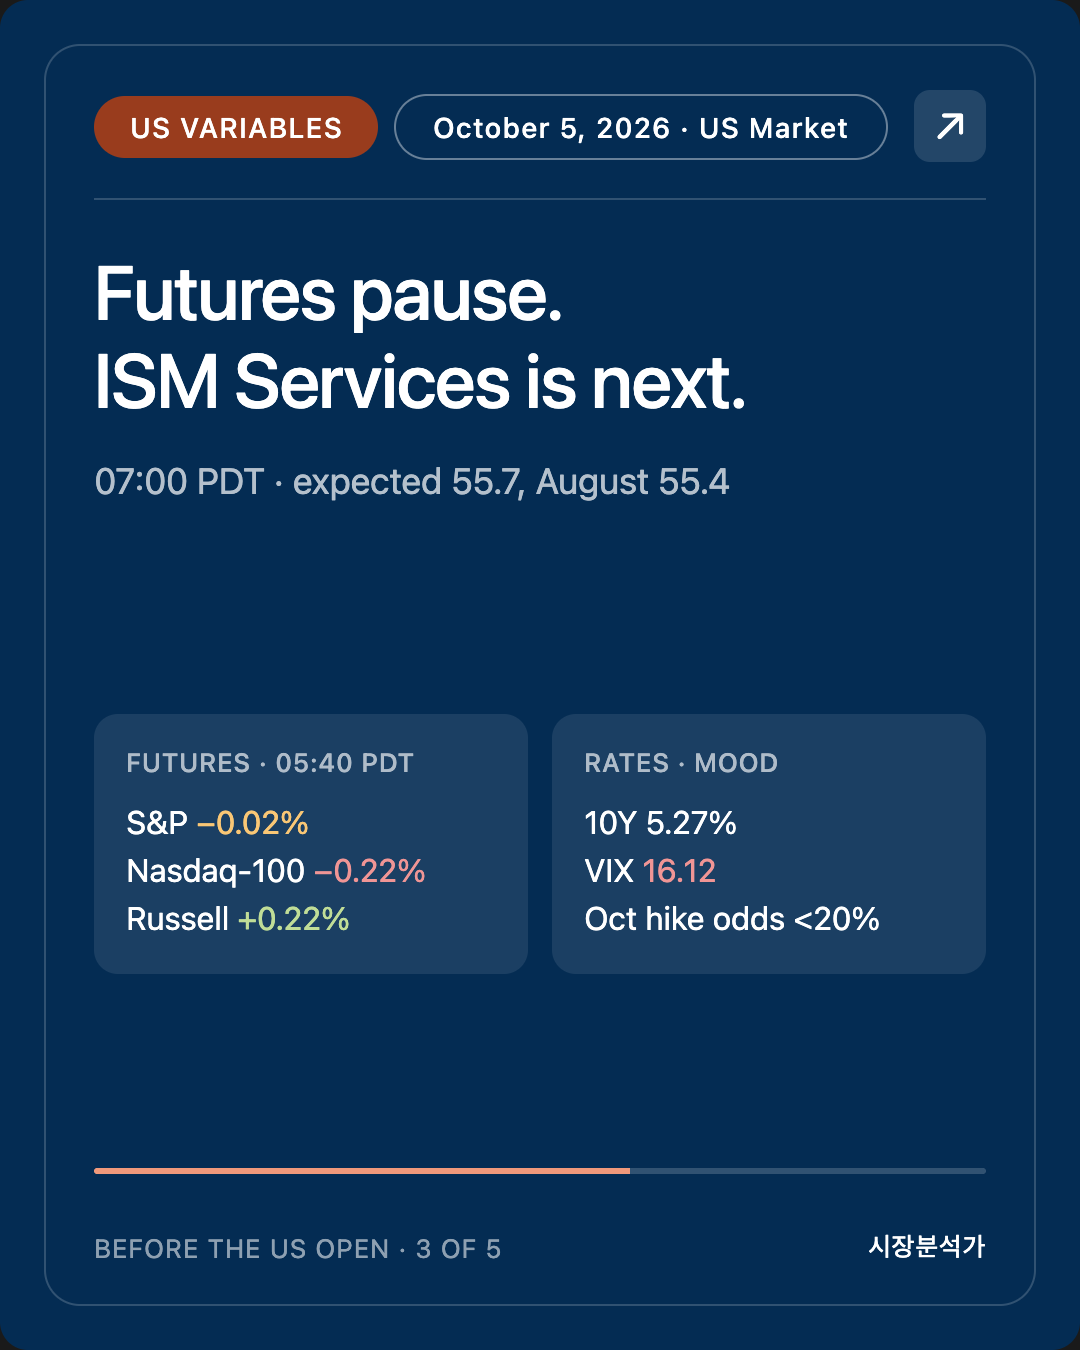
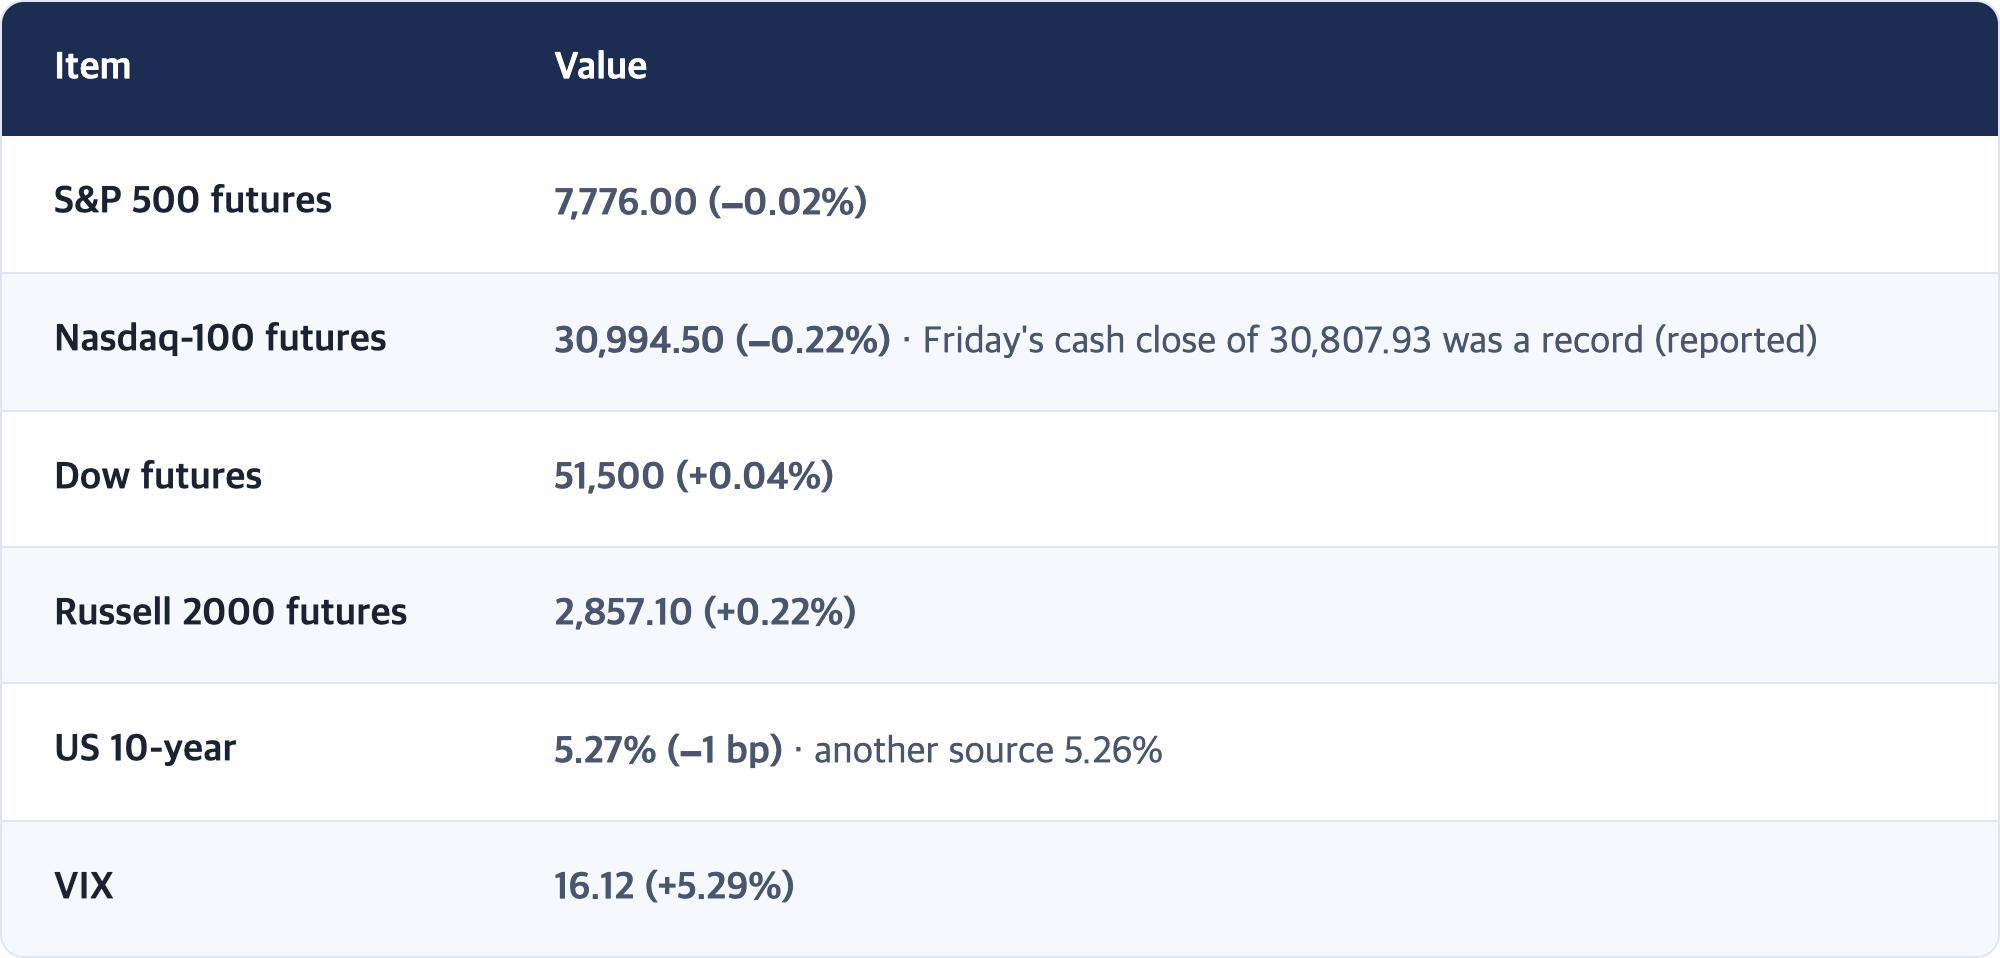
- US futures are catching their breath. S&P futures 7,776 (−0.02%), Nasdaq-100 −0.22%, Dow +0.04%, Russell +0.22%. 10-year 5.26–5.27% (Friday 5.28%). VIX 16.12 (+5.3%).
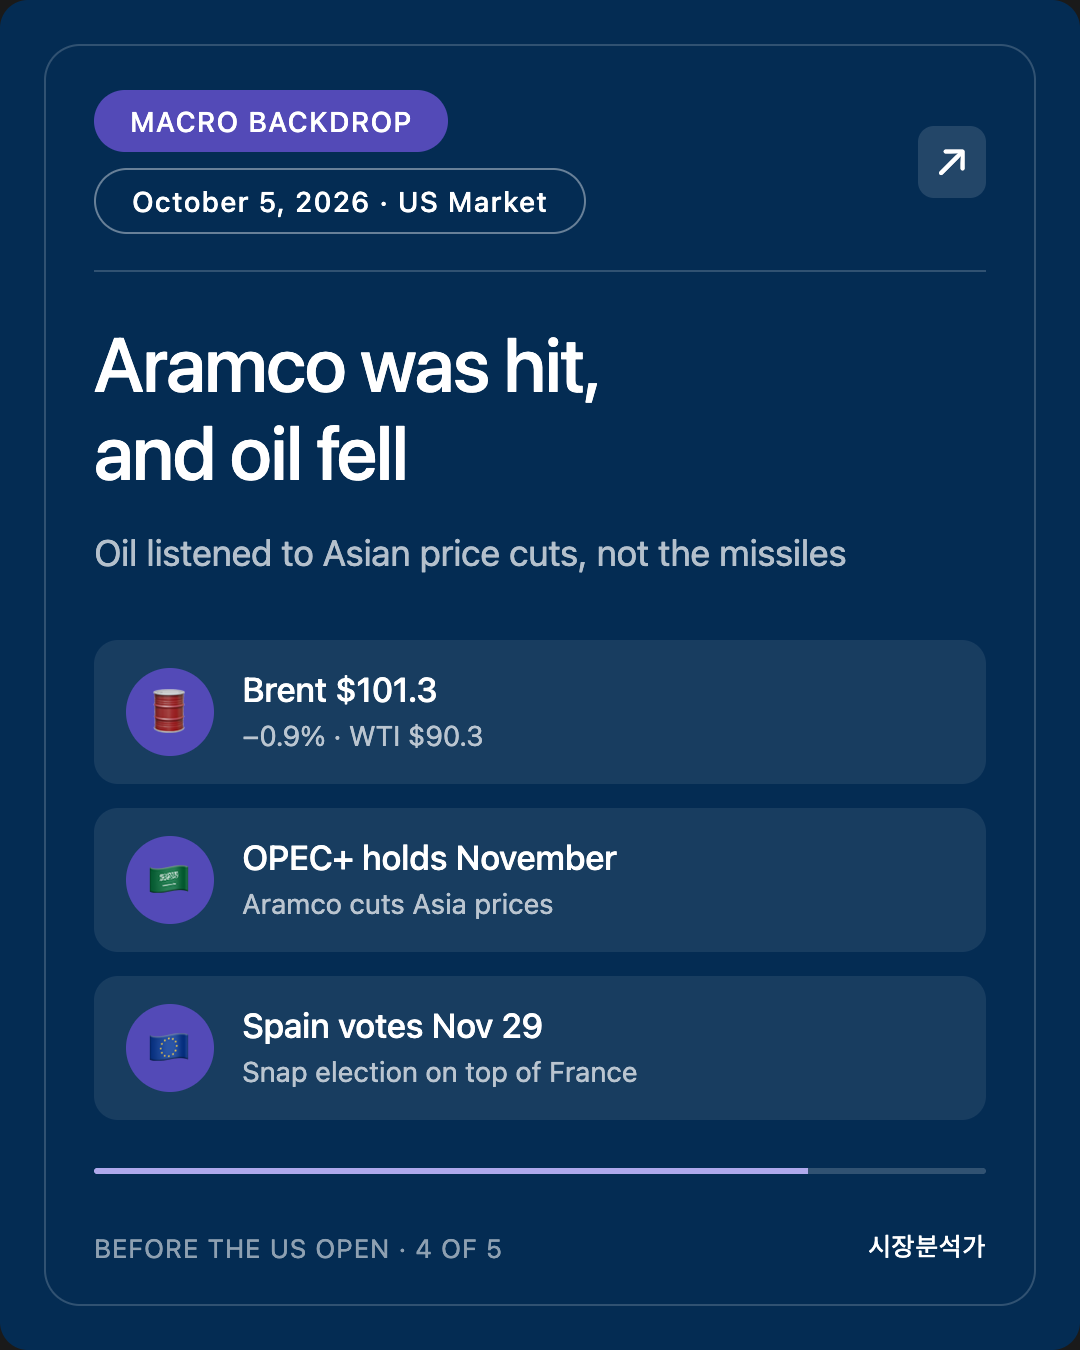
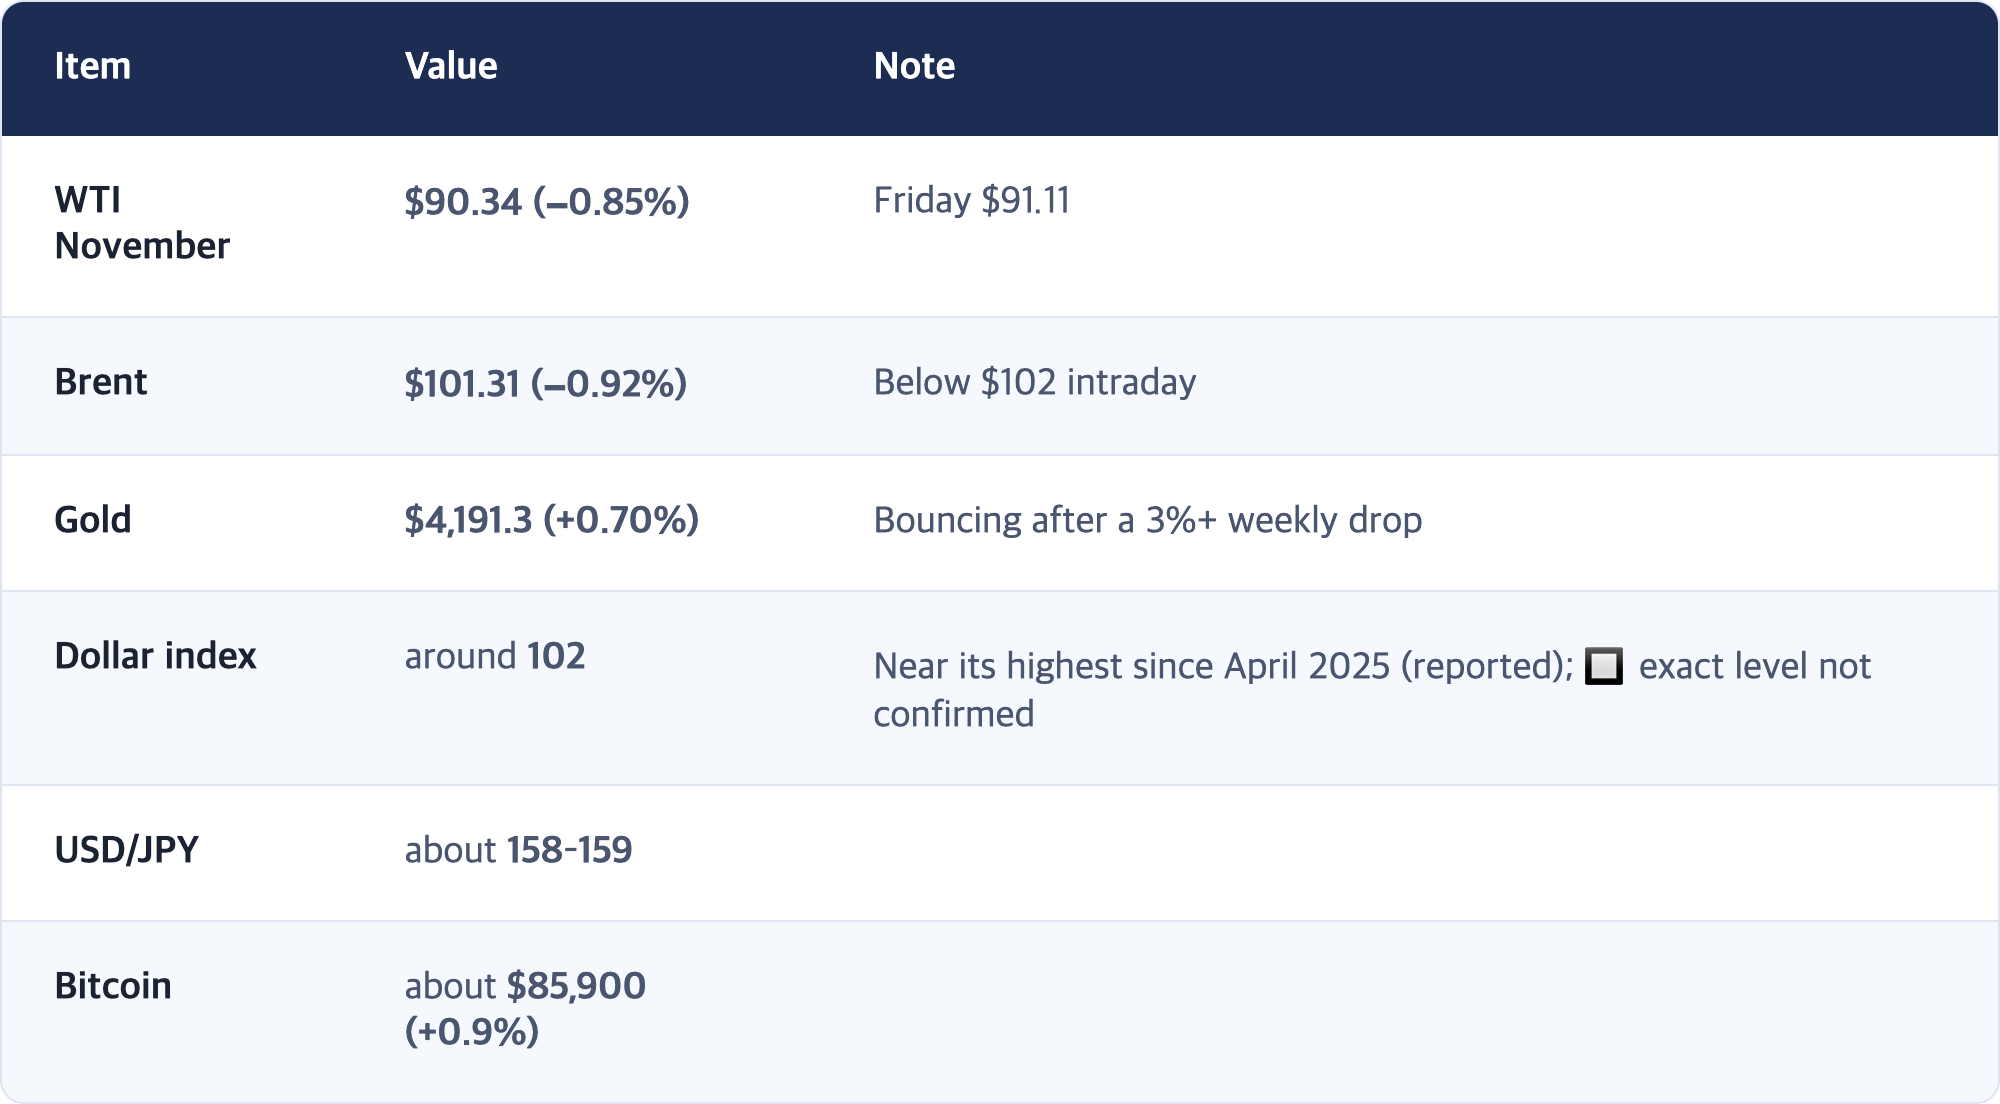
- The Houthis hit Aramco over the weekend, and oil fell. Despite claimed strikes on facilities in Riyadh and the Khurais field, WTI is $90.3 (−0.9%) and Brent $101.3 (−0.9%). OPEC+ held November output steady; Aramco cut its prices for Asian buyers.
- 07:00 PDT: US September ISM Services (expected 55.7, August 55.4). The first test of whether Friday's jobs shock is a one-month blip. Seoul reopens tonight at 17:00 PDT (09:00 KST Tuesday) and will absorb all of this at once.
This is Mr. Can. Here is the October 5, 2026 brief ahead of the US market open.
Written: 2026-10-05 05:55 PDT (Seoul 10/5 21:55 KST)
Basis: US 10/2 (Fri) final closes + Tokyo and Hong Kong 10/5 closes (Seoul closed for a substitute public holiday; mainland China closed for the National Day holiday) + Europe 10/5 intraday + US 10/5 pre-market
🟢 Scheduled for 05:30 PDT, started 05:43 PDT. US figures are pre-market.
🟡 Korea's stock market did not open today. Tokyo stands in for the "Asia close" in this edition. The four checkpoints set in the 10/4 evening brief are scored at Seoul's close on Tuesday 10/6, so today we only give an interim read on the two that overlap with the US session.
SEO Intro
With Seoul closed, Tokyo answered first. Japan's Nikkei 225 crossed 70,000 intraday for the first time in about three months and closed at 69,946.86 (+2.40%). Friday's weak US jobs report (only 29,000 jobs added in September) pushed the odds of an October Fed rate hike below 20%, and investors piled back into AI and chip heavyweights.
Europe, meanwhile, lit a different fire. French budget worries, now joined by a snap election in Spain (November 29), pushed the euro to $1.1161, a 17-month low. France's 10-year yield is at 4.92%, flirting with 5% for the first time since 2002. US futures are pausing: S&P flat, Nasdaq-100 −0.2%. Today's question for Wall Street: will Europe's fiscal scare push back up the yields that Friday's jobs shock was supposed to bring down?
1. Checkpoint Interim Read
The four set in the 10/4 evening brief (judged at Seoul's 10/6 close; #2–4 at today's US close)
The axis: does the jobs shock finally pull long yields down, or does only the short end move again?
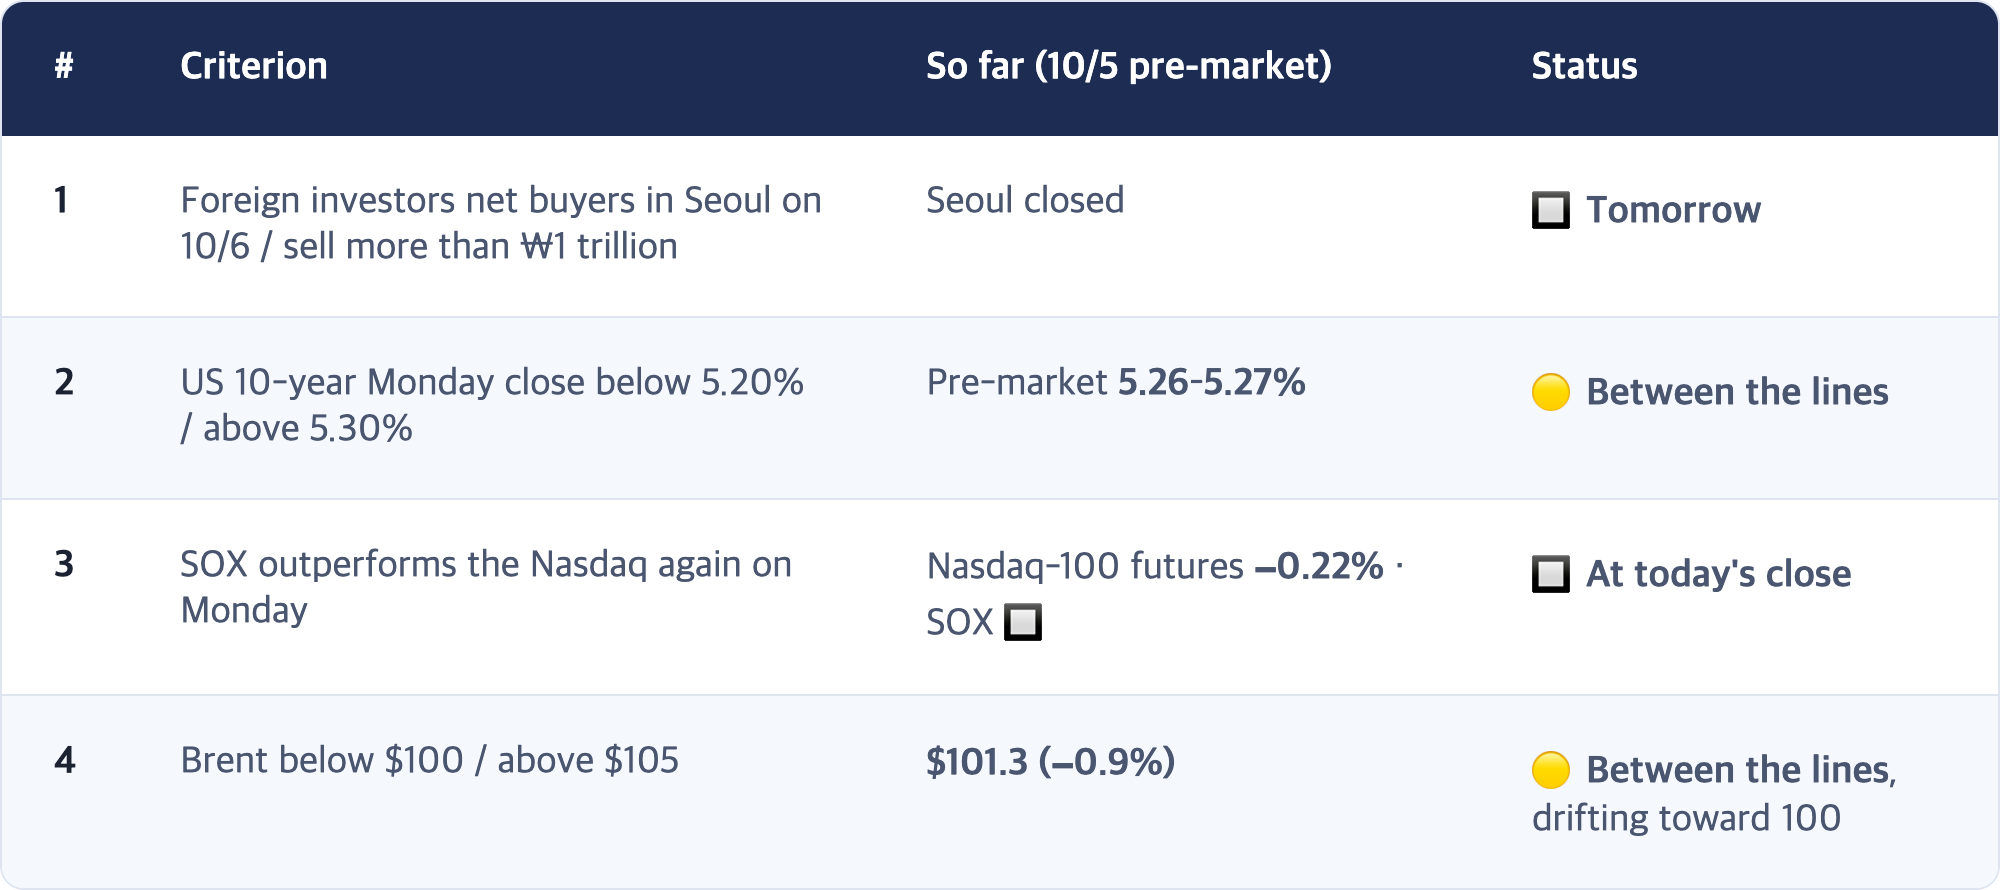
[Interpretation] Tokyo offered a preview of #1
Checkpoint 1 is scored tomorrow, but Tokyo received the same news first. The Nikkei read Friday's jobs report as "the rate-hike scare is over" (as Korean media put it), led by AI and chip stocks. If Seoul follows that reading, foreign selling is more likely to stop. One caveat: Tokyo also had a weak yen (about ¥158–159 per dollar) helping exporters, while the Korean won actually strengthened to 1,350.6 on Friday. The translation is not one-to-one.
2. Today's Core: Tokyo says the rate scare is over; Europe opens a new one
[Fact] Asia and Europe on 10/5 (local time)
★ [Interpretation] One jobs report, two opposite stories
Tokyo's story is simple: US hiring slowed → the Fed won't hike in October → rate pressure eases → buy growth. Asia picked up, a day late, the Nasdaq's +1.19% and the chip index's two-day +3.7% from last week.
Europe's story has nothing to do with Friday's payrolls. The gap between French and German government bond yields is the widest since the 2011–2012 euro crisis. In ECB President Christine Lagarde's words, when debt is close to 120% of GDP and not on course to be brought under control, "it's a serious matter." On top of that, Spain's parliament rejected two housing decrees, triggering a snap election.
[Interpretation] What matters for the US is that both stories meet at the 10-year Treasury. As the 10/4 evening brief noted, the 10-year rose to 5.28% despite the jobs shock. Three times last week, good news for rates failed to bring long yields down. One reading: behind that stubbornness is not only US fiscal policy but a broader loss of confidence in developed-market public finances. If French yields break 5%, the pressure may not stay in Europe. [Observation] For now, the US 10-year is slightly lower pre-market at 5.26–5.27%, so there is no clear sign yet of European stress spilling into Treasuries.
3. US Variables: futures pause, ISM Services today
[Fact] US pre-market (around 05:40 PDT 10/5, Yahoo Finance)
[Fact] Friday (10/2) US close, recap
Dow 51,176.96 (+0.49%) · S&P 500 7,722.72 (+0.73%) · Nasdaq 27,190.86 (+1.19%) · 10-year 5.28% (+5 bp) · CME October hike odds 17–22%.
[Observation] Today's schedule (PDT)
- 06:45 S&P Global September services and composite PMI (final)
- 07:00 ISM September Services: expected 55.7, August 55.4
- Earnings this week: PepsiCo, Delta Air Lines, Levi Strauss and others (Q3 season gets going mid-month)
[Interpretation] Friday's payrolls said hiring slowed. ISM Services measures business conditions in the service sector, roughly 70% of the US economy. A print well below 55.7 would suggest the jobs shock is more than a one-month blip and lock in an October pause. A beat, especially with a hot prices-paid sub-index, could partly undo Friday's "no October hike" trade. Given last week's pattern, the first scenario to keep in mind is that either way, only the short end reacts and the 10-year holds.
4. Macro Backdrop: Aramco was hit, and oil fell
[Fact] (10/5 pre-market)
[Fact] Middle East over the weekend
- 10/4: Yemen's Houthis said they hit Aramco facilities in Riyadh and the Khurais oil field with ballistic missiles and drones; fires were reported. The strike was framed as retaliation after a Saudi-backed Yemeni government offensive to retake Houthi-held areas.
- Seven core OPEC+ producers kept November output targets at September levels. Several Gulf producers are already pumping below quota because of shipping disruptions.
- Aramco cut November official selling prices for Asia, some grades to six-year lows.
- Hormuz: Iran said on 10/4 the strait stays closed until the US accepts its conditions.
[Interpretation] Oil listened to the price cut, not the missiles
On 9/8, a Houthi strike on Aramco sent Brent up to the $99 area intraday. Today it fell. Two differences: the G7's 100-million-barrel stock release (agreed 10/2) is already in the background, and Aramco lowered its prices to Asia. A seller cutting prices signals "we have the barrels; we're worried about buyers." [Observation] This read comes before any damage assessment. If follow-up reports show serious damage at Khurais, the direction could flip within a day.
5. Today's US Session (Mon 10/5, PDT) Preview
The axis
Do the "rate relief" effects of the jobs shock continue, or does Europe's fiscal scare override them? The answer shapes what Seoul gets tomorrow: Tokyo-style relief, or renewed rate pressure.
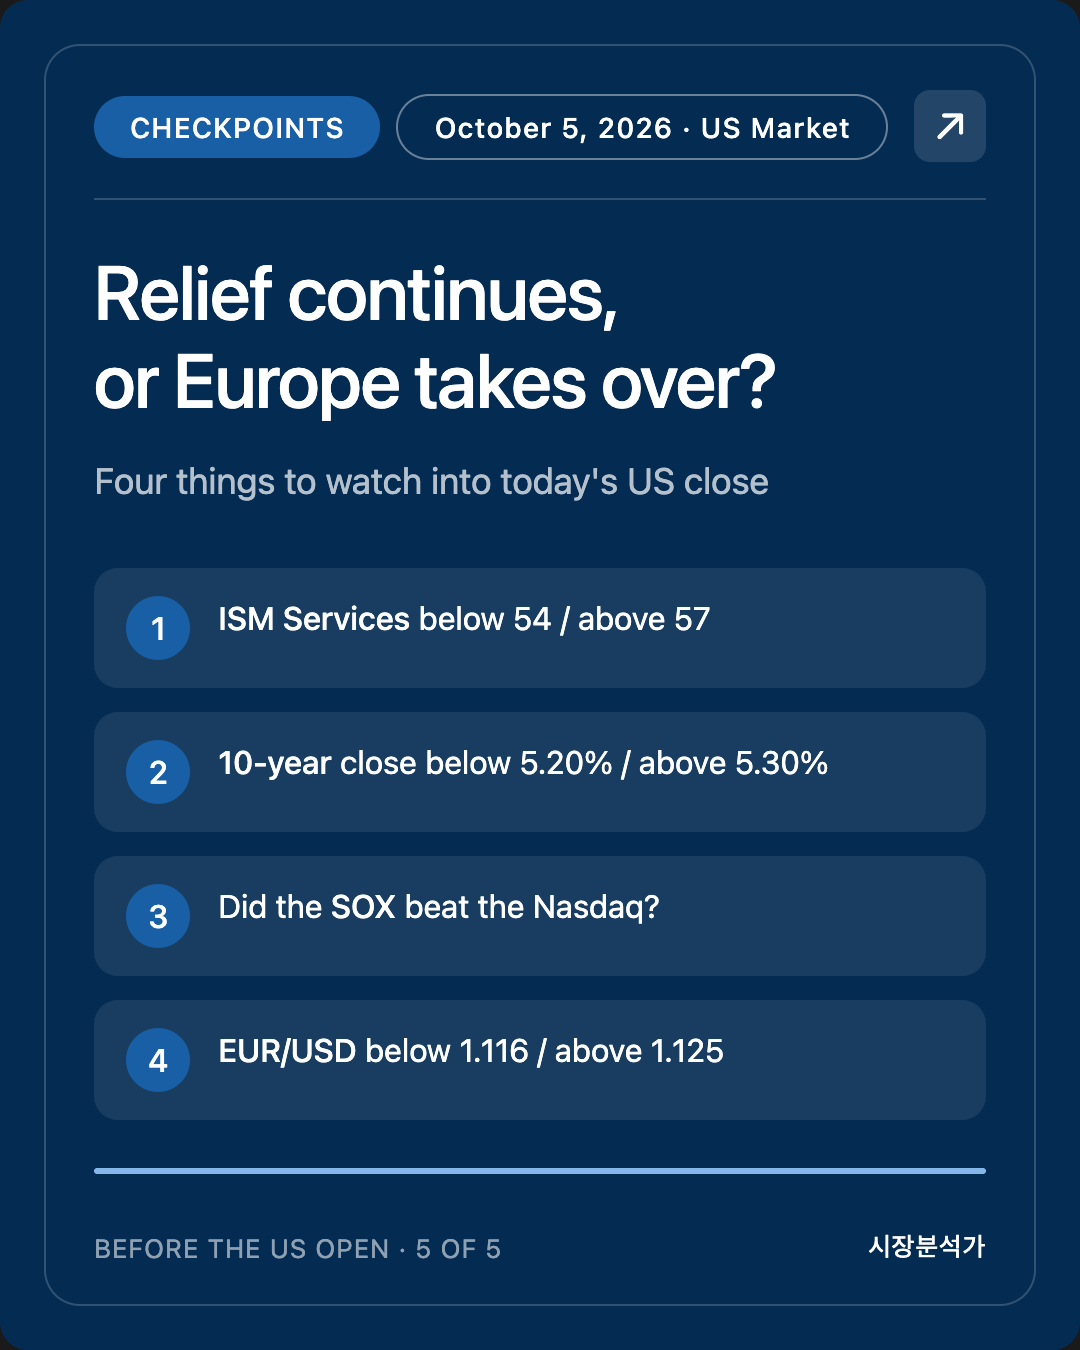
✅ Four checkpoints (through today's US close)
- ISM Services below 54 / above 57. Below: the slowdown has spread to services. Above: an argument that Friday's jobs report was a blip. (Most important)
- US 10-year close below 5.20% / above 5.30%. Same lines as #2 in the 10/4 evening brief. Below: the jobs shock finally reached long yields, three sessions late. Above: a fourth data point withstood, with Europe adding pressure.
- Did the SOX outperform the Nasdaq? #3 from the 10/4 brief: does Tokyo's chip buying carry over to New York?
- EUR/USD new low below 1.116 / recovery above 1.125. Below: Europe's fiscal scare is not a one-day story. Above: the Asian-session panic was overdone.
[Interpretation] The most informative combination is #1 with #2. If ISM is weak and the 10-year still can't break 5.20%, that is one more confirmation of this week's thesis: the force pushing long yields up lies outside the US business cycle, in fiscal policy, Europe and oil.
6. Study Note: Why government bond spreads are a crisis thermometer
Concept
France and Germany share the euro, so there is no currency risk between them. Yet France's 10-year yields about 4.92% and Germany's about 1.46 percentage points less. That gap is the spread. Same currency, same central bank, different interest rate: what's left is essentially one thing, how worried investors are that the country will pay its debts on time.
Analogy
Two people borrow from the same bank. One has a steady income and pays 4%; the other has heavy debts and irregular income and pays 5.5%. The gap the bank charges is the price of credit worry. If that gap suddenly widens, the bank has started to see the second borrower as riskier.
Real examples
- 2011–2012 euro crisis: Italian and Spanish spreads over Germany widened to around 5 percentage points and only calmed after ECB President Mario Draghi's "whatever it takes" (July 2012).
- October 2026: France's spread is about 146 bp, with the largest weekly widening in 17 years (reported). Debt is about 117.5% of GDP (Q1), with a deficit around 5.4%.
One-line summary
The level of bond yields reflects inflation and central banks; the gap between countries reflects trust. When you look at the US 10-year at 5.27% today, ask whether it carries only the US economy, or also a broader worry about rich-country public finances.
7. Corrections and Open Items
Corrections
- None. The US September CPI date that the 10/4 brief flagged for re-checking is confirmed as Wednesday 10/14, 08:30 ET (BLS schedule).
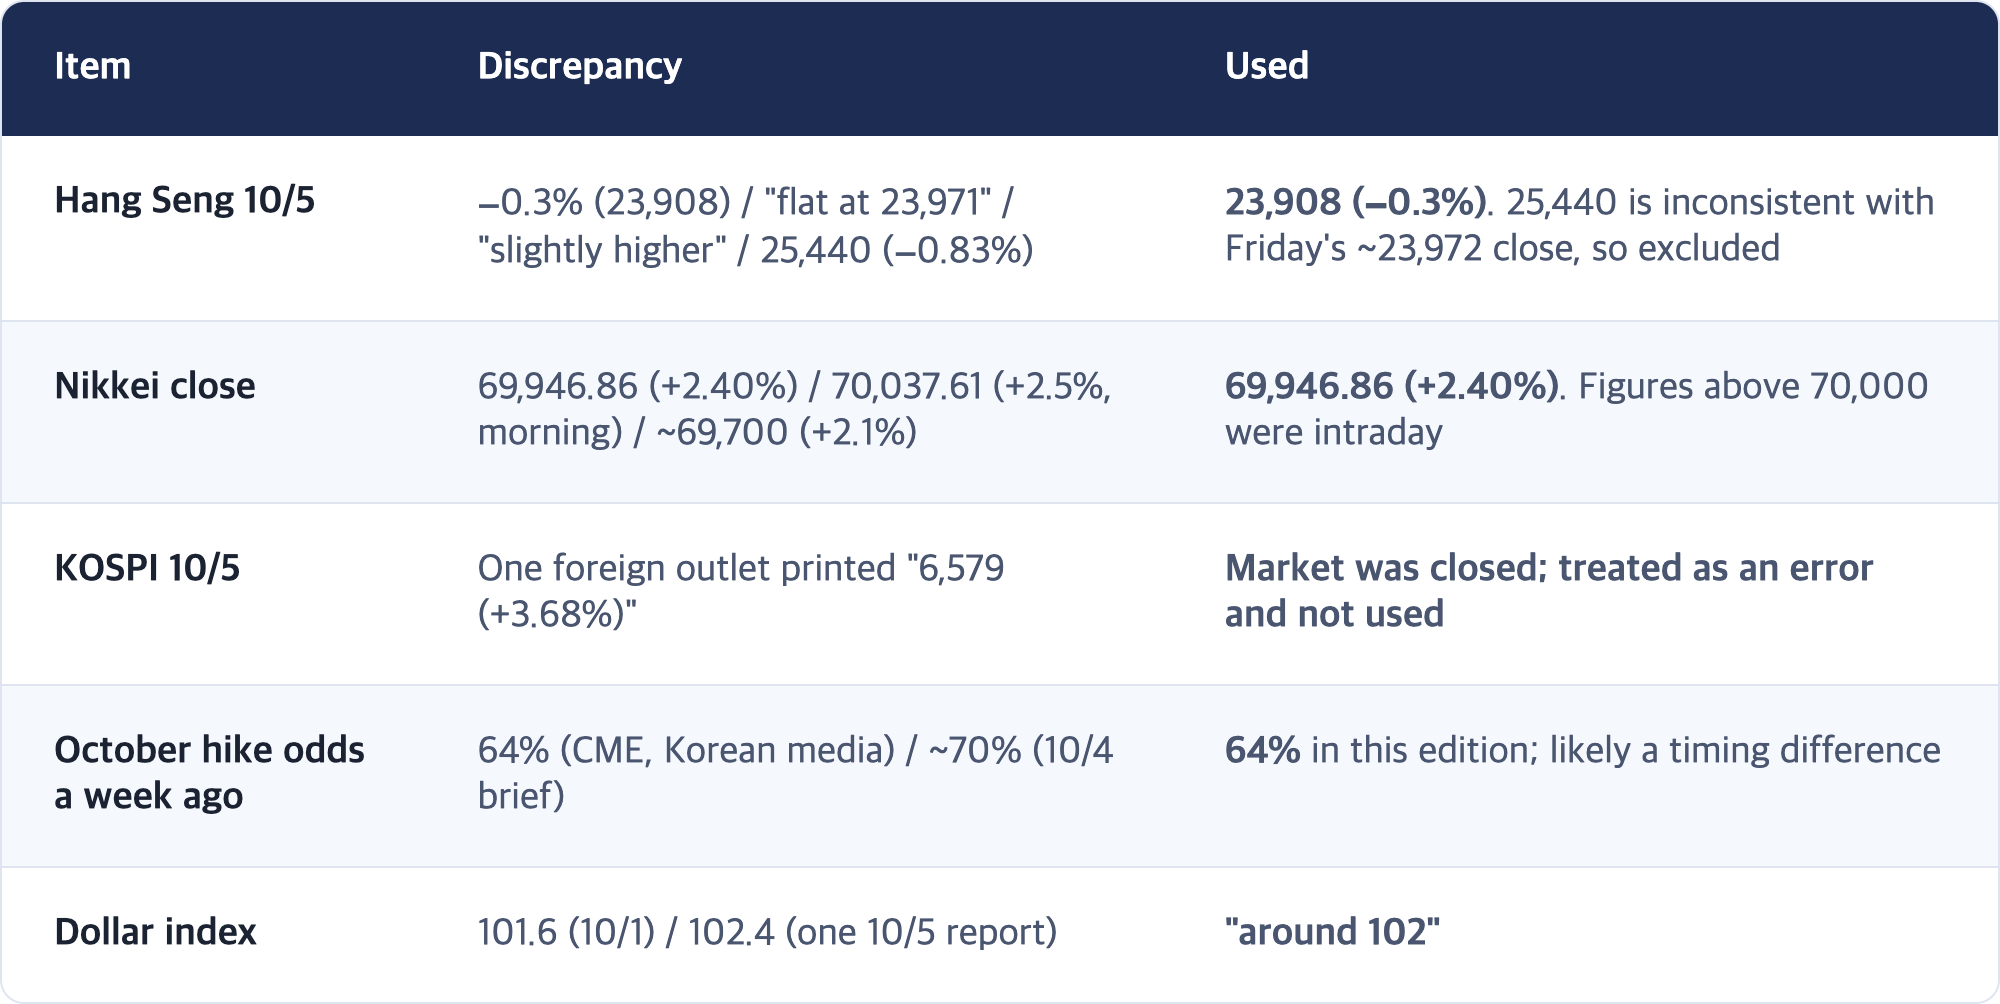
Source discrepancies (value used in the text)
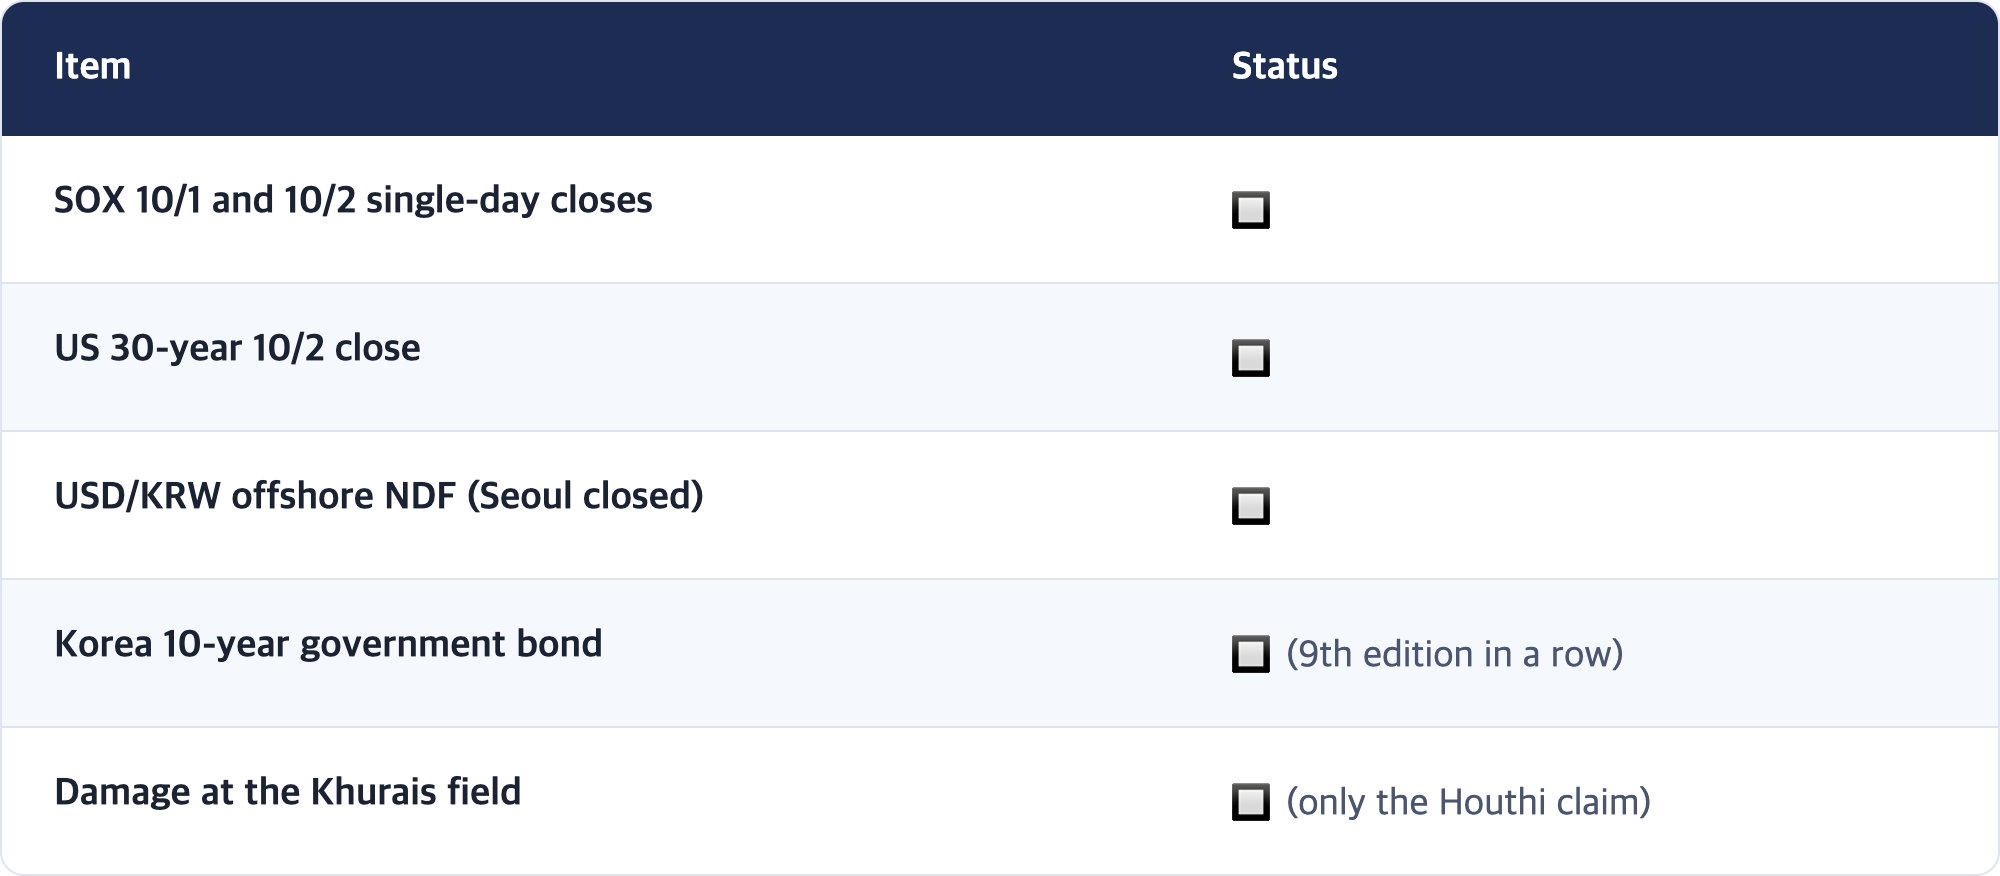
🔲 Unconfirmed
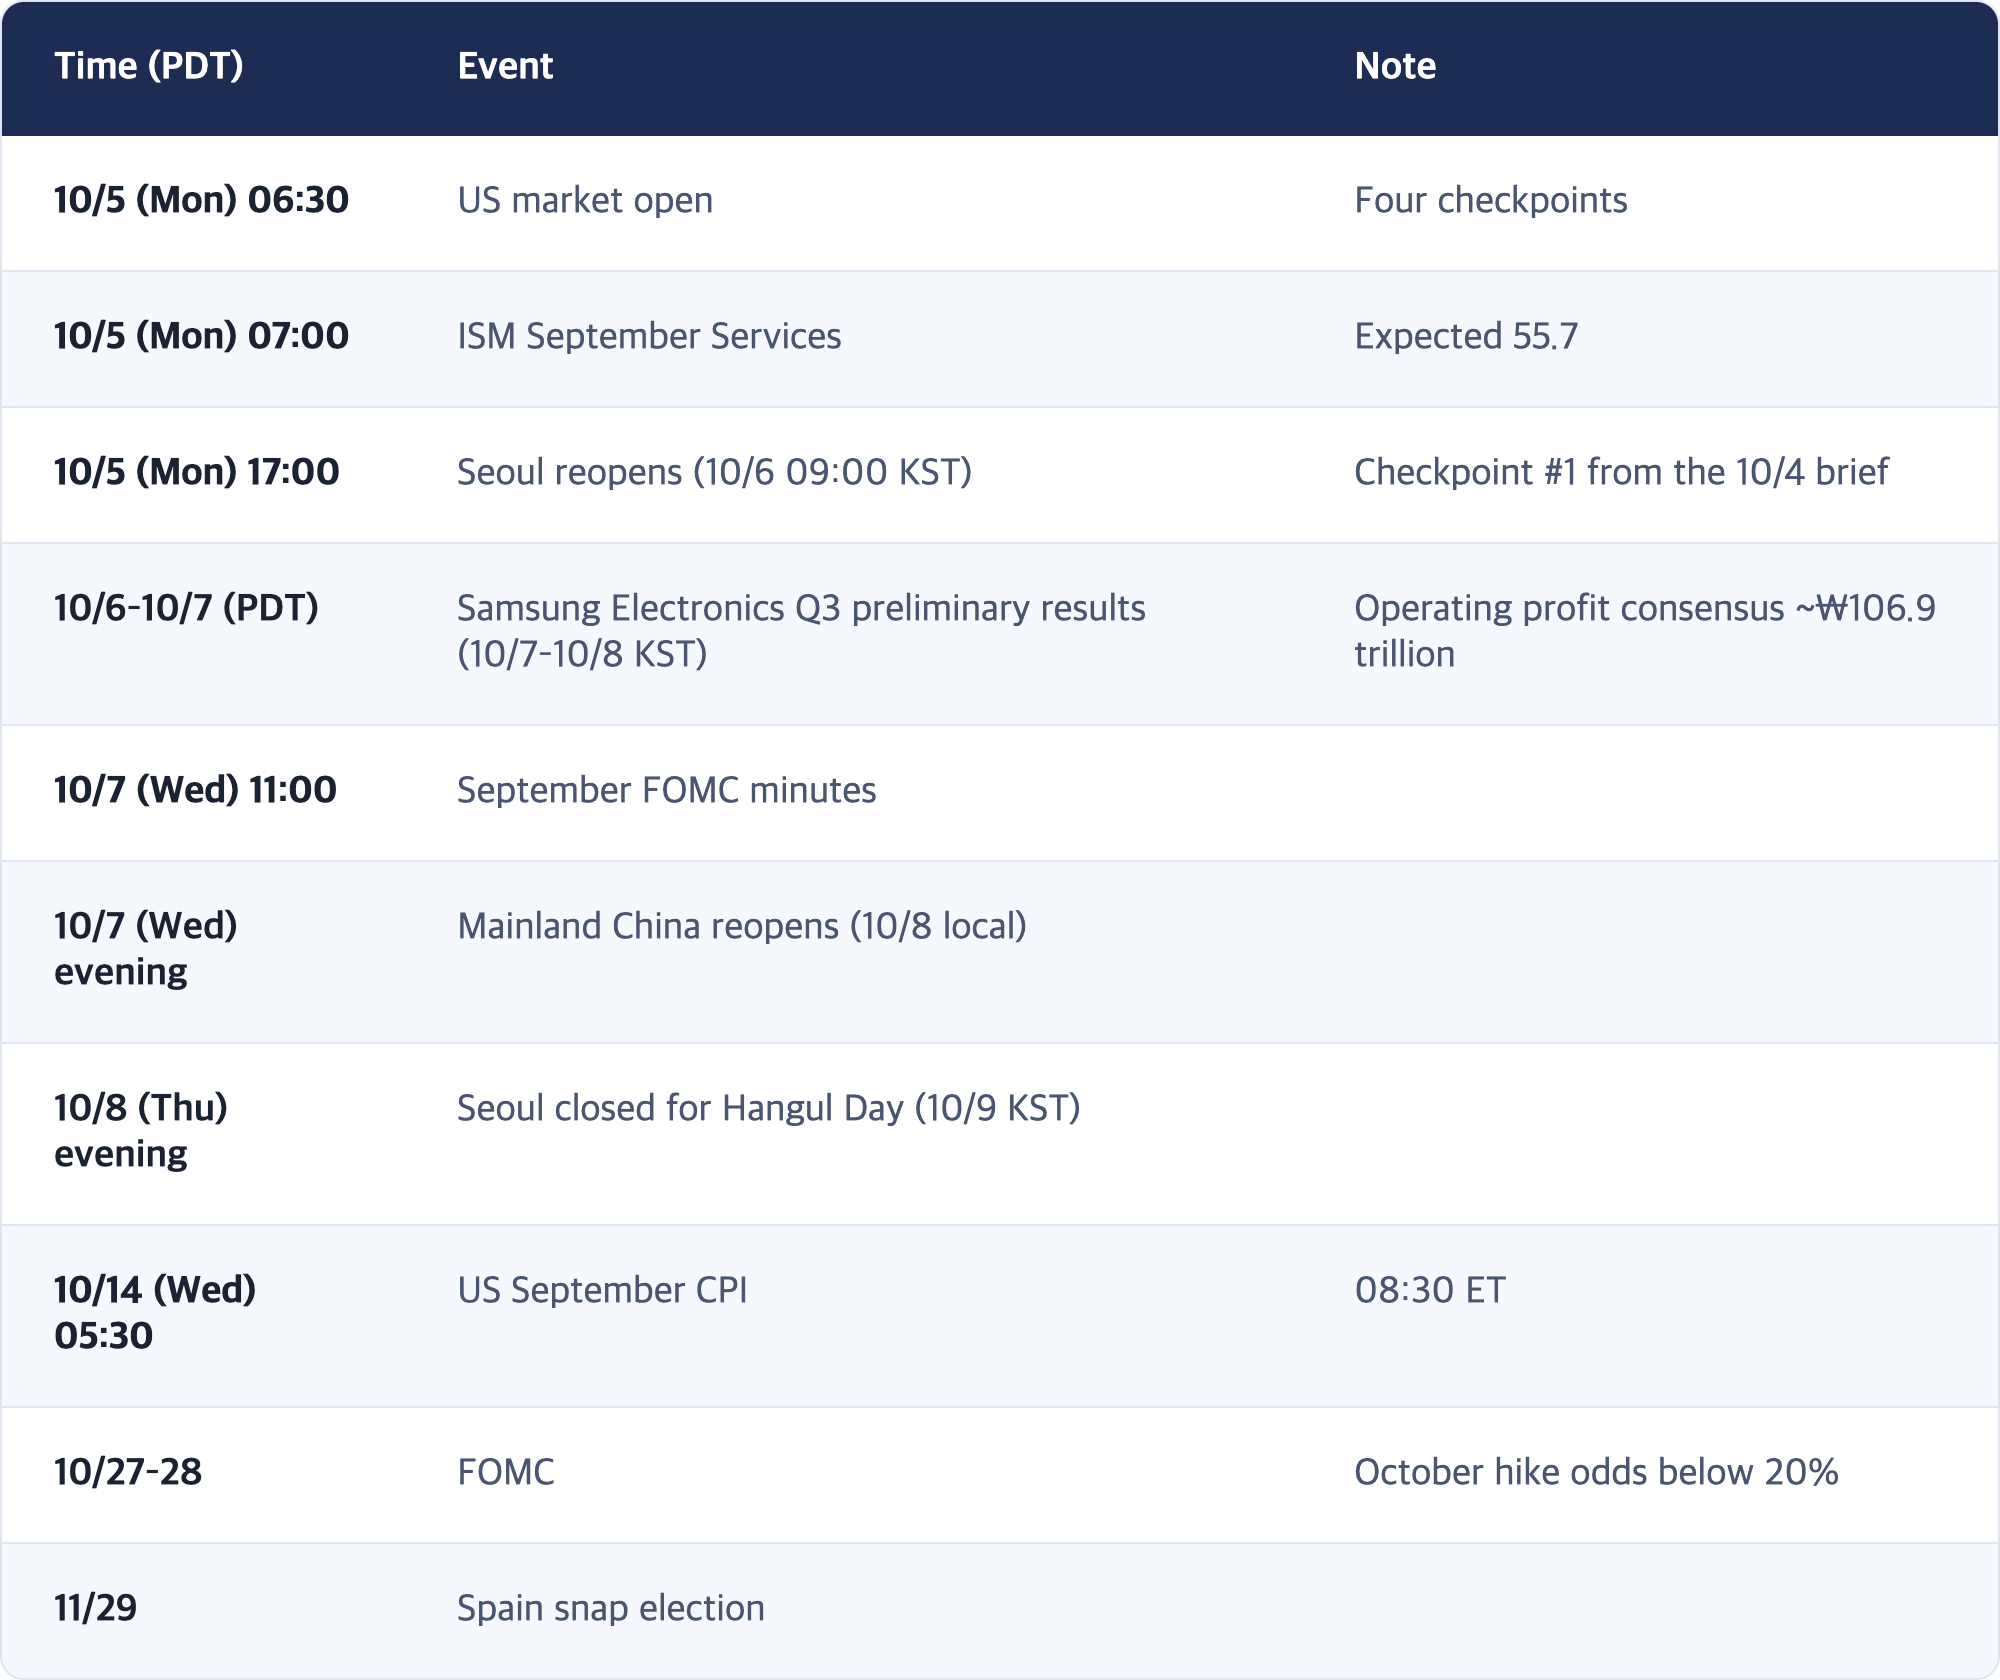
8. Event Calendar (PDT)
Sources
- Stock market today: Dow, S&P 500, Nasdaq futures edge lower amid bond market, tech caution | Yahoo Finance
- Asian stocks rise as US October hike bets fade; Nikkei +2.4% | eToday (Korean)
- Nikkei touches 70,000 as US rate fears fade | Global Economic (Korean)
- Asia Intelligence Brief: Monday, October 5, 2026 | Rio Times
- Hong Kong Stock Market Index | Trading Economics
- Euro hits 17-month low as French debt fears mount and Spain heads for snap election | Euronews
- European Stock Markets Open Mixed as French Fiscal Fears Hit CAC 40 | Eurasia Business News
- France debt crisis: Bond investors have rendered a 'guilty' verdict | Fortune
- France's borrowing costs near 5% | EU Insider
- Market Pulse October 05, 2026 | NordFX
- US 10 Year Treasury Note Yield | Trading Economics
- Brent oil | Trading Economics
- Houthis claim strike on Aramco site as Yemen fighting intensifies | Al Jazeera
- Yemen's Houthis say they attacked Aramco facility in Riyadh | NBC News
- Saudi-led coalition pledges support for Yemeni offensive against Houthis | CNN
- Daily Report October 4, 2026: Lebanon, Yemen, Hormuz and Oil | Profile News
- US ISM Services PMI September 2026 | financecalendar.com
- Consumer Price Index release | BLS
Market Analyst · This brief does not recommend buying or selling individual securities. It provides macro context and interpretation.
📌 More market briefs
※ This post is market observation and organization intended to support your own judgment. It is not a recommendation to buy or sell any security. Figures are as of the time of writing and may differ between sources.
If this was useful, bookmark it or pass it along. It genuinely helps me write the next one.
I can survive. We can survive.