Oct 8, 2026 KOSPI Market Brief — What to Watch Before the Korean Open
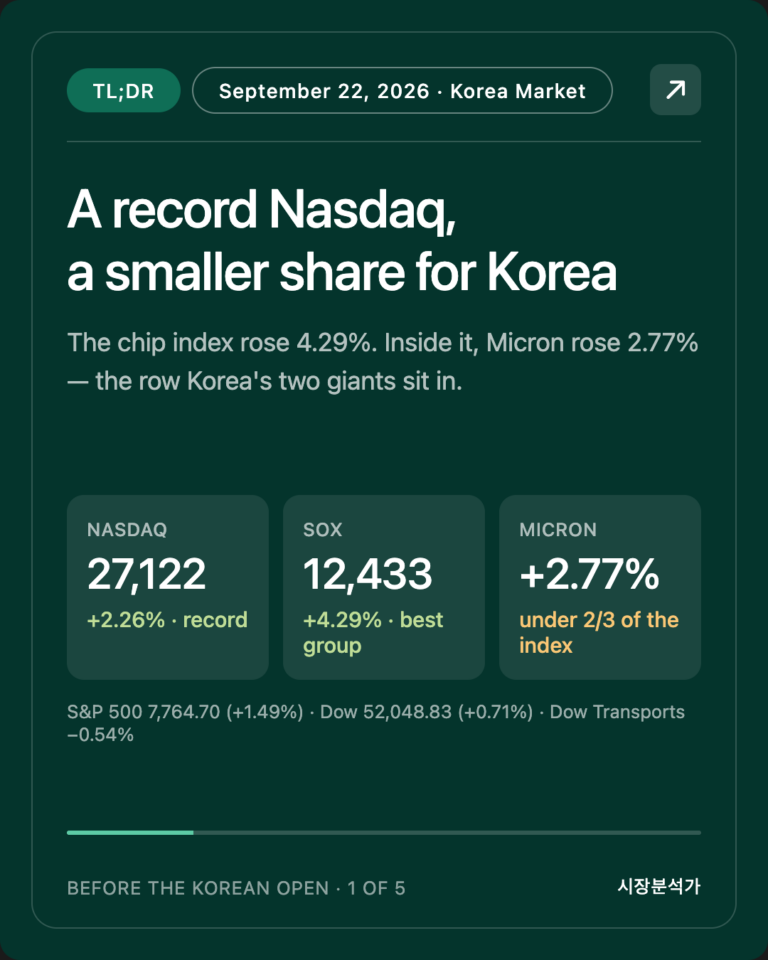
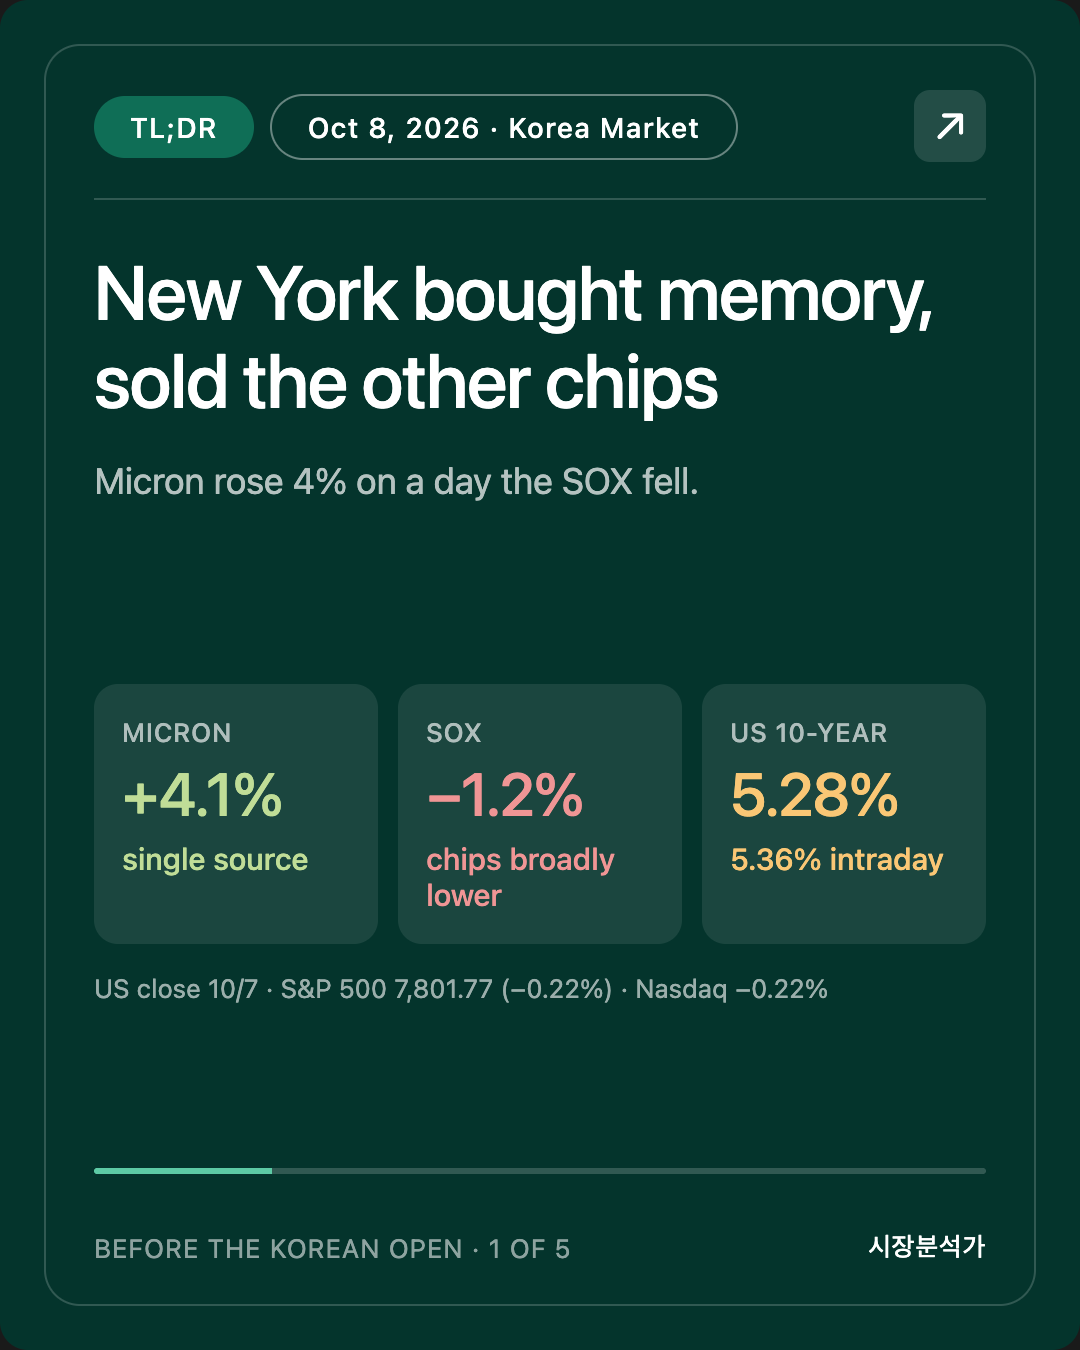
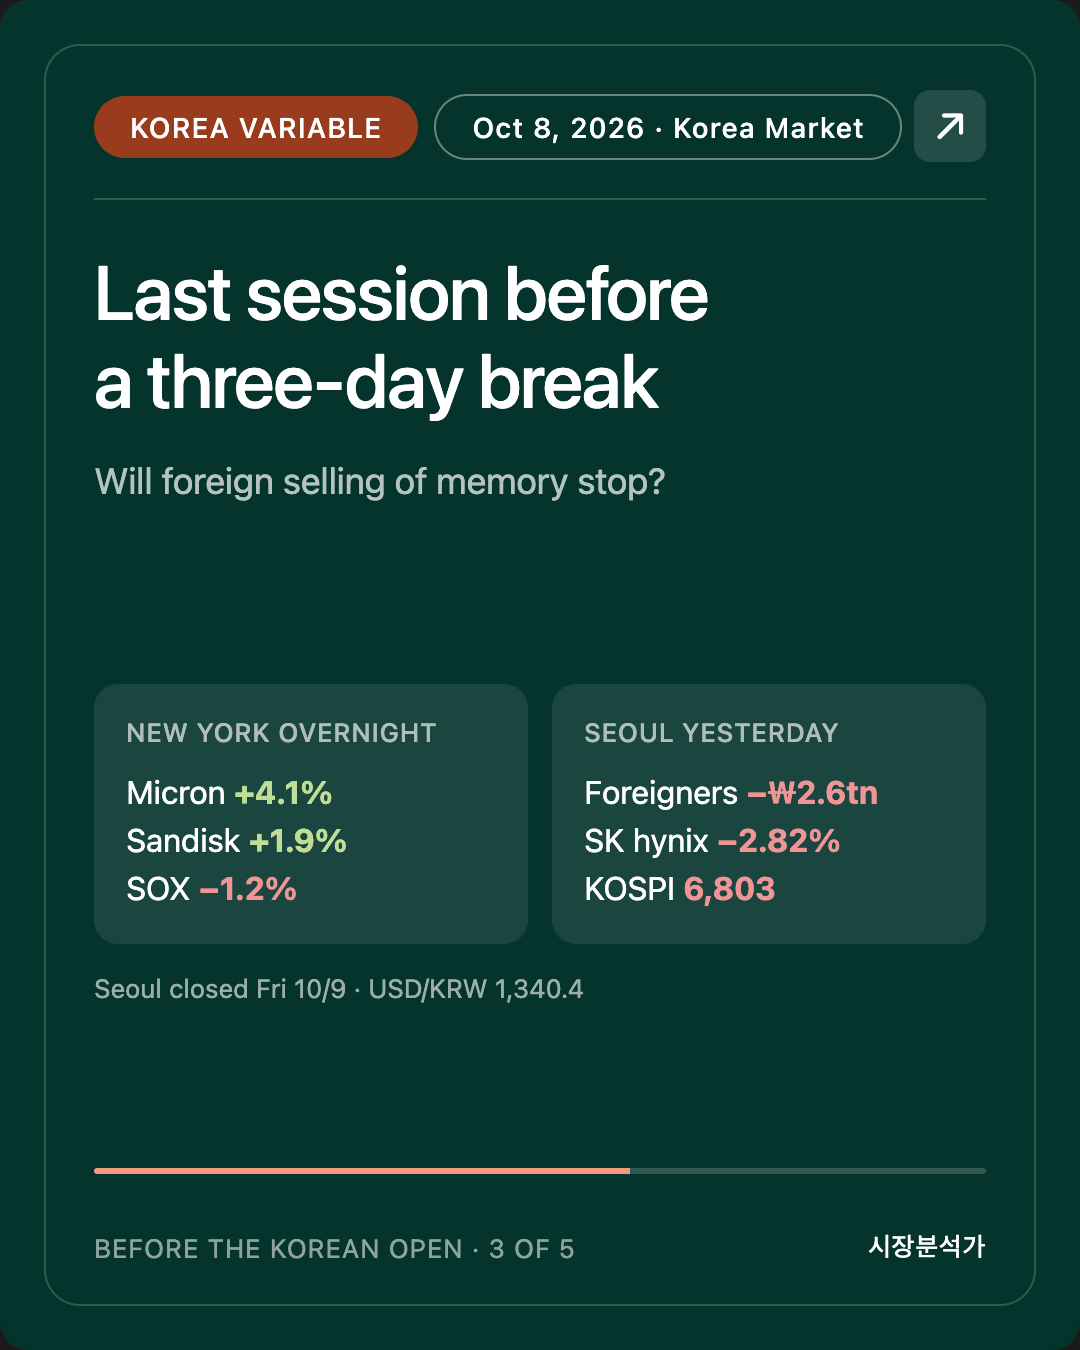
- ★ New York bought memory and sold the rest of the chip sector. Micron +4.1%, Sandisk +1.9% (TheStreet) vs SOX −1.2%. The exact reverse of two days ago, when AI networking and compute names led.
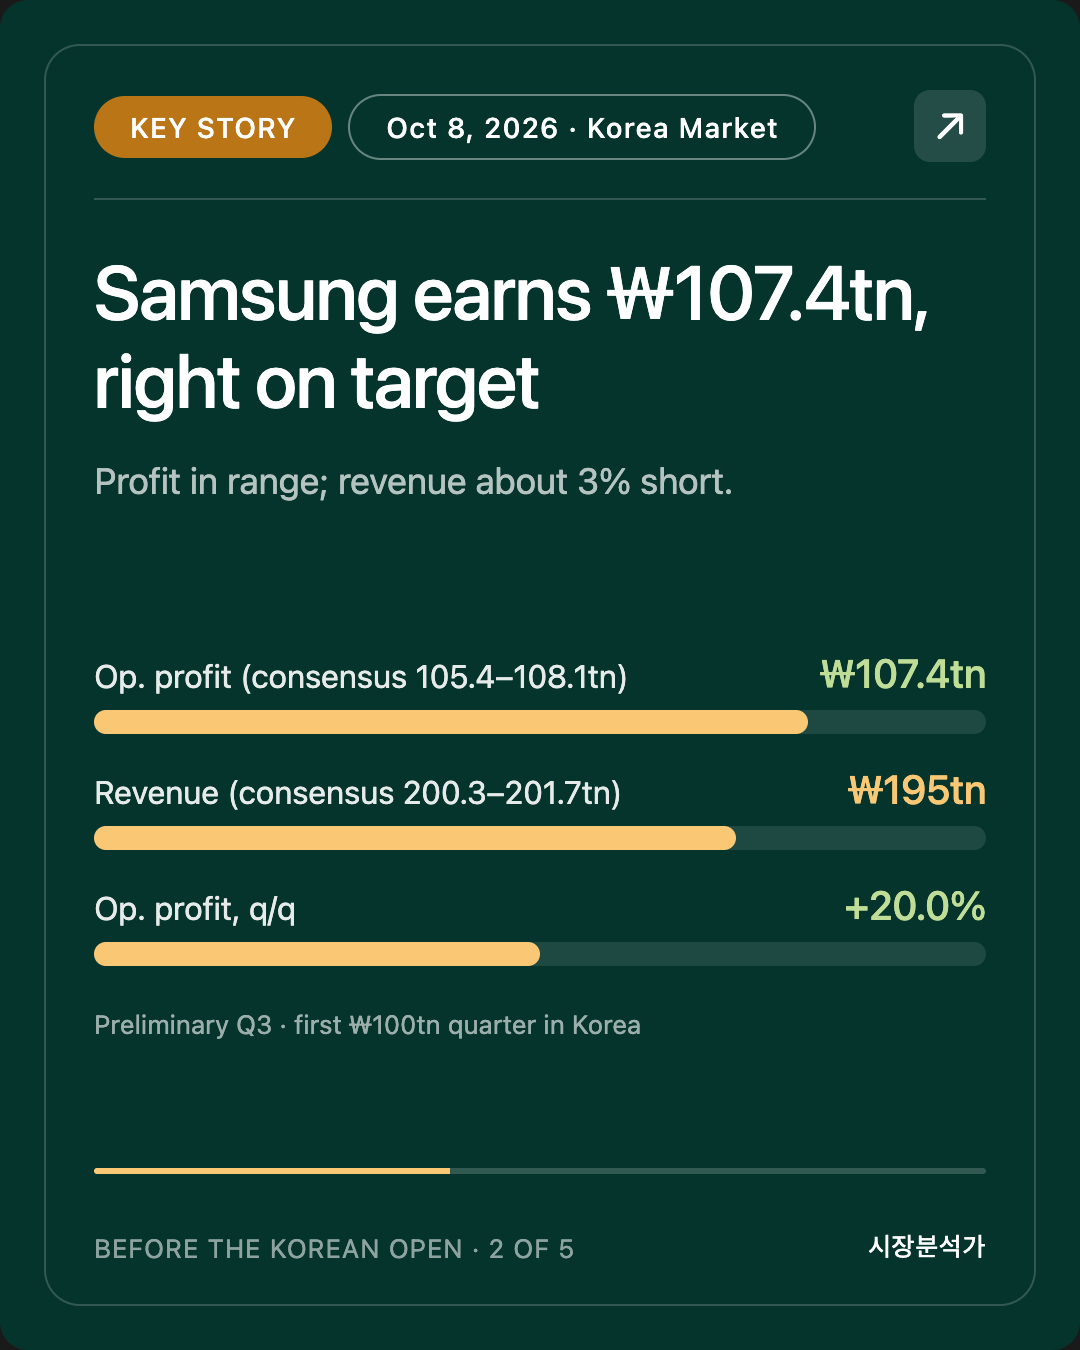
- ★ Samsung's Q3 operating profit of ₩107.4 trillion met expectations. Consensus ranged from ₩105.4 trillion (Yonhap Infomax) to ₩108.1 trillion (FnGuide). Revenue of ₩195 trillion was about 3% below the ₩200.3–201.7 trillion consensus.
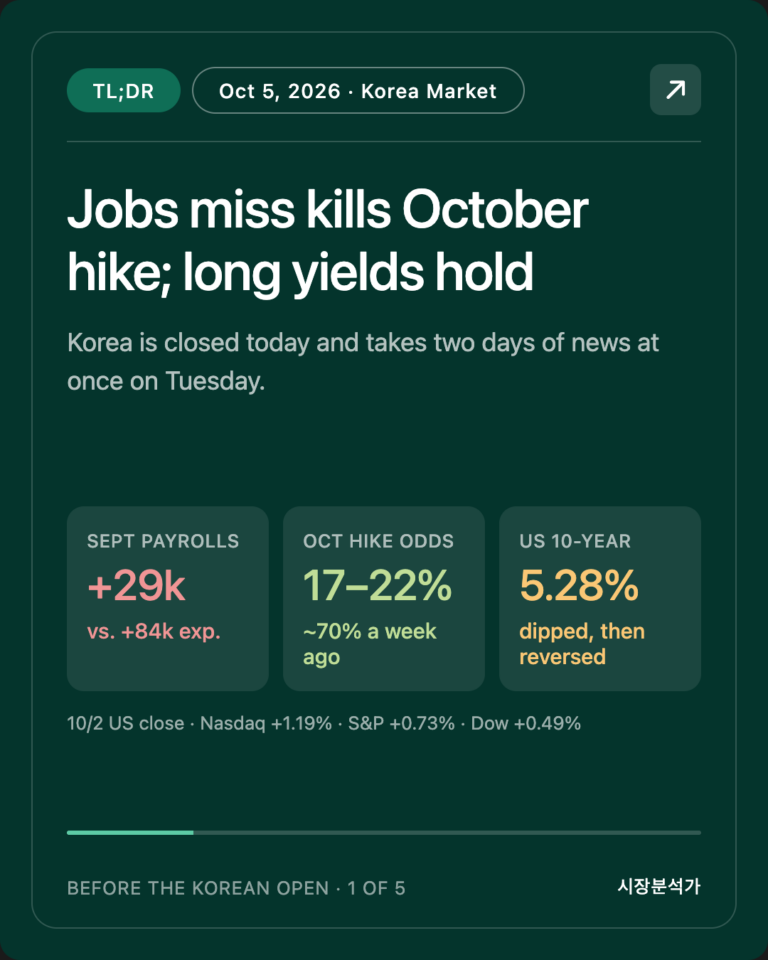
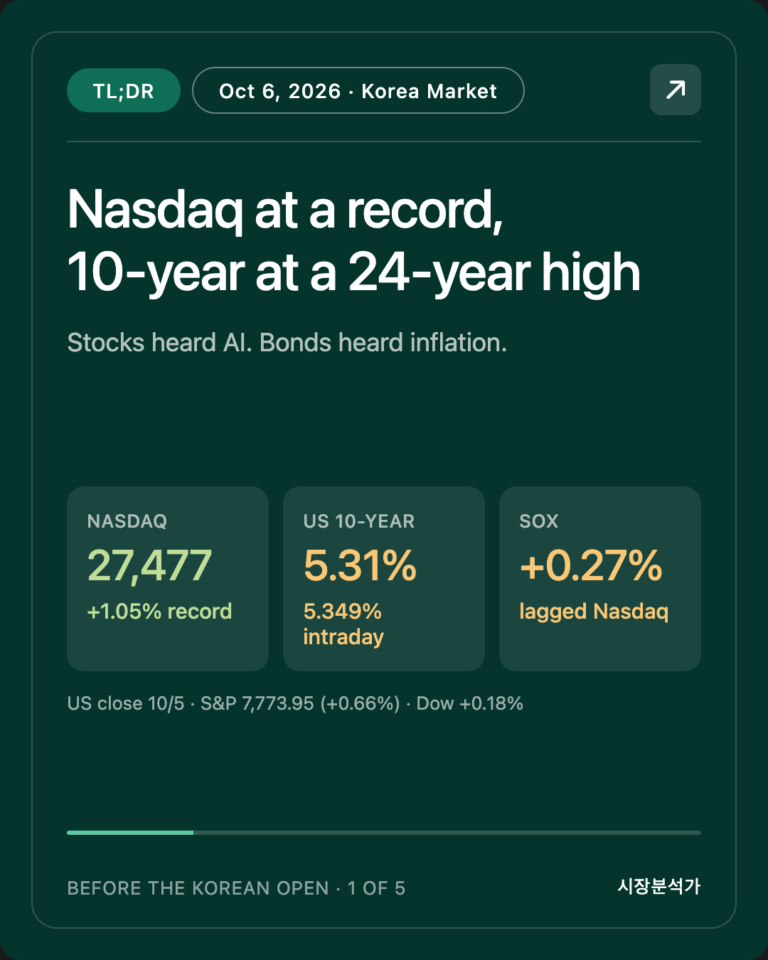
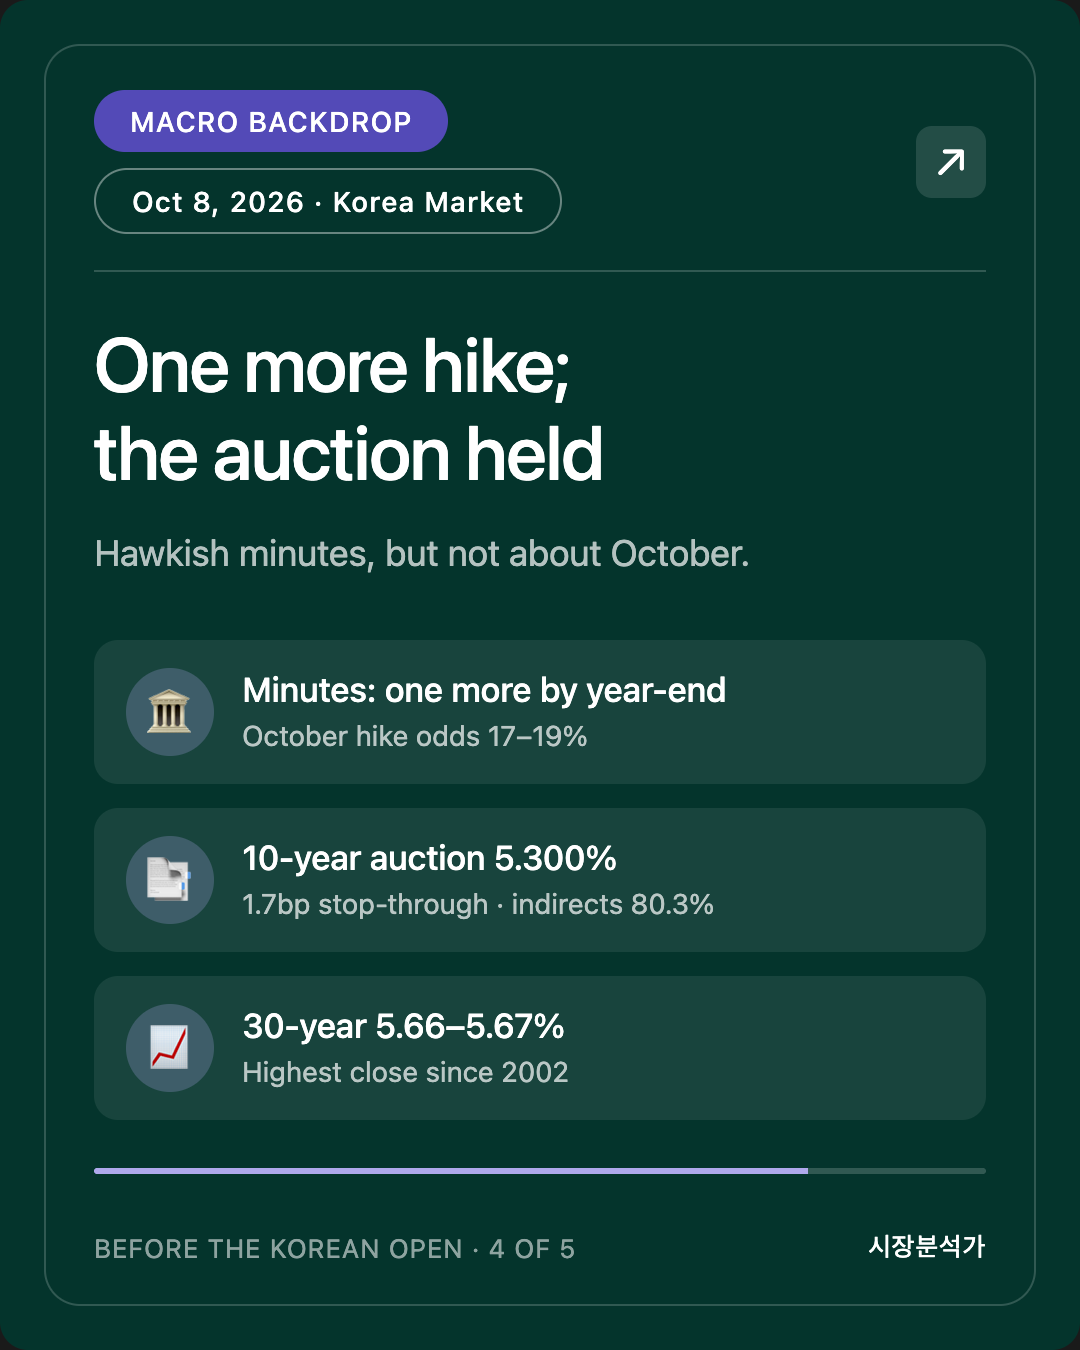
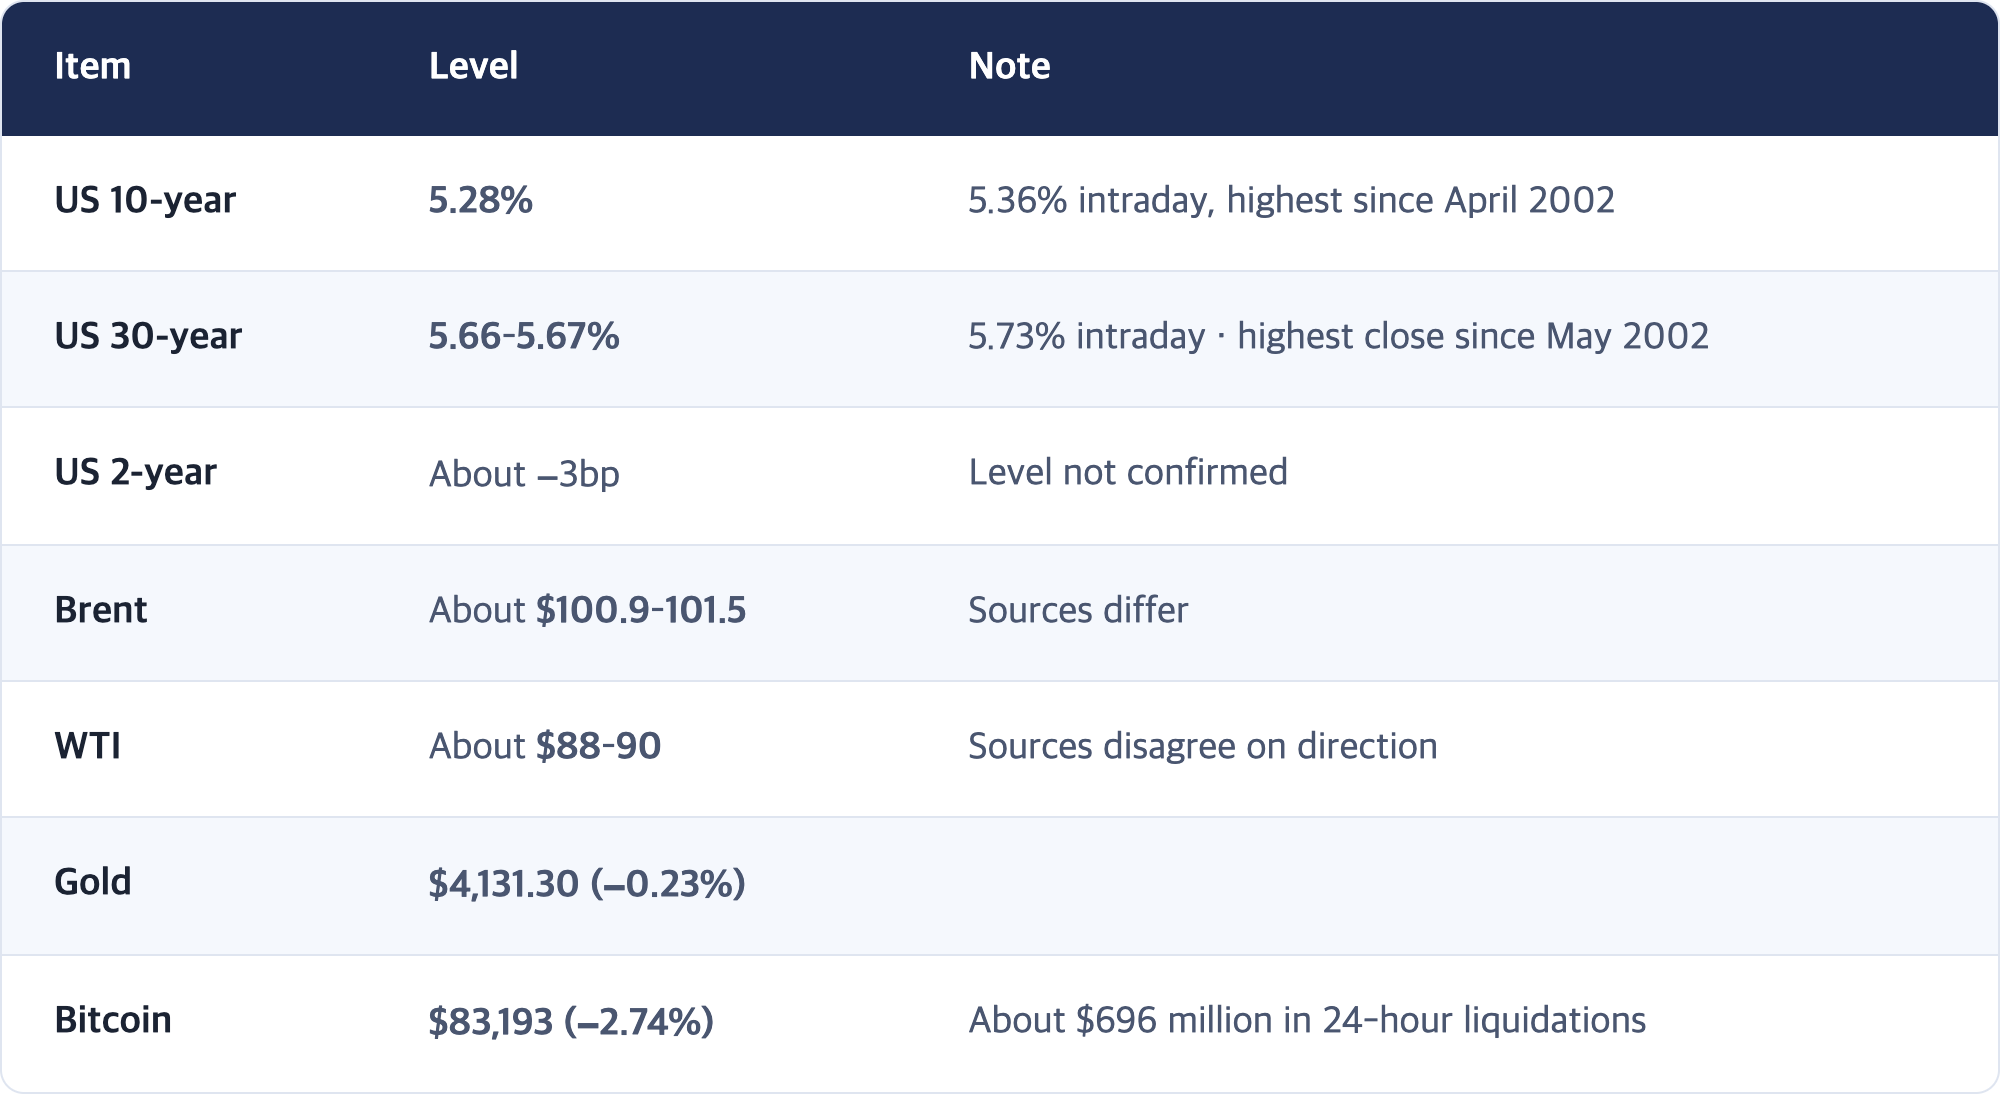
- ★ The 10-year auction was strong. High yield 5.300% (highest since November 2000), a 1.7bp stop-through, bid-to-cover 2.77x, indirect bidders (a proxy for foreign and institutional demand) 80.3%. The 10-year closed at 5.28% after a 5.36% intraday high.
- The minutes were hawkish, but not about "next month." "Most" see one more hike by year-end. Odds of an October hike stayed around 17–19% (as reported). The 30-year closed at 5.66–5.67%, its highest close since May 2002.
- Seoul's question today: ahead of a three-day break, does foreign selling of memory stop? On 10/7 foreigners sold a net ₩2.6 trillion (about $1.9 billion); the KOSPI closed at 6,803.90 (−1.98%); USD/KRW 1,340.4 (single source).
This is Mr. Can. Here is the Oct 8, 2026 brief ahead of the Korean market open.
Written: 2026-10-08 08:10 KST (Vancouver 10/7 16:10 PDT)
Basis: US regular-session close for Wed 10/7 + US 10-year note auction results + FOMC minutes (Sept 15–16 meeting) + Samsung Electronics' preliminary Q3 results (filed the morning of 10/8 KST) + Seoul close for Wed 10/7
🟢 Scheduled 16:00 PDT, started 16:02 PDT. On time.
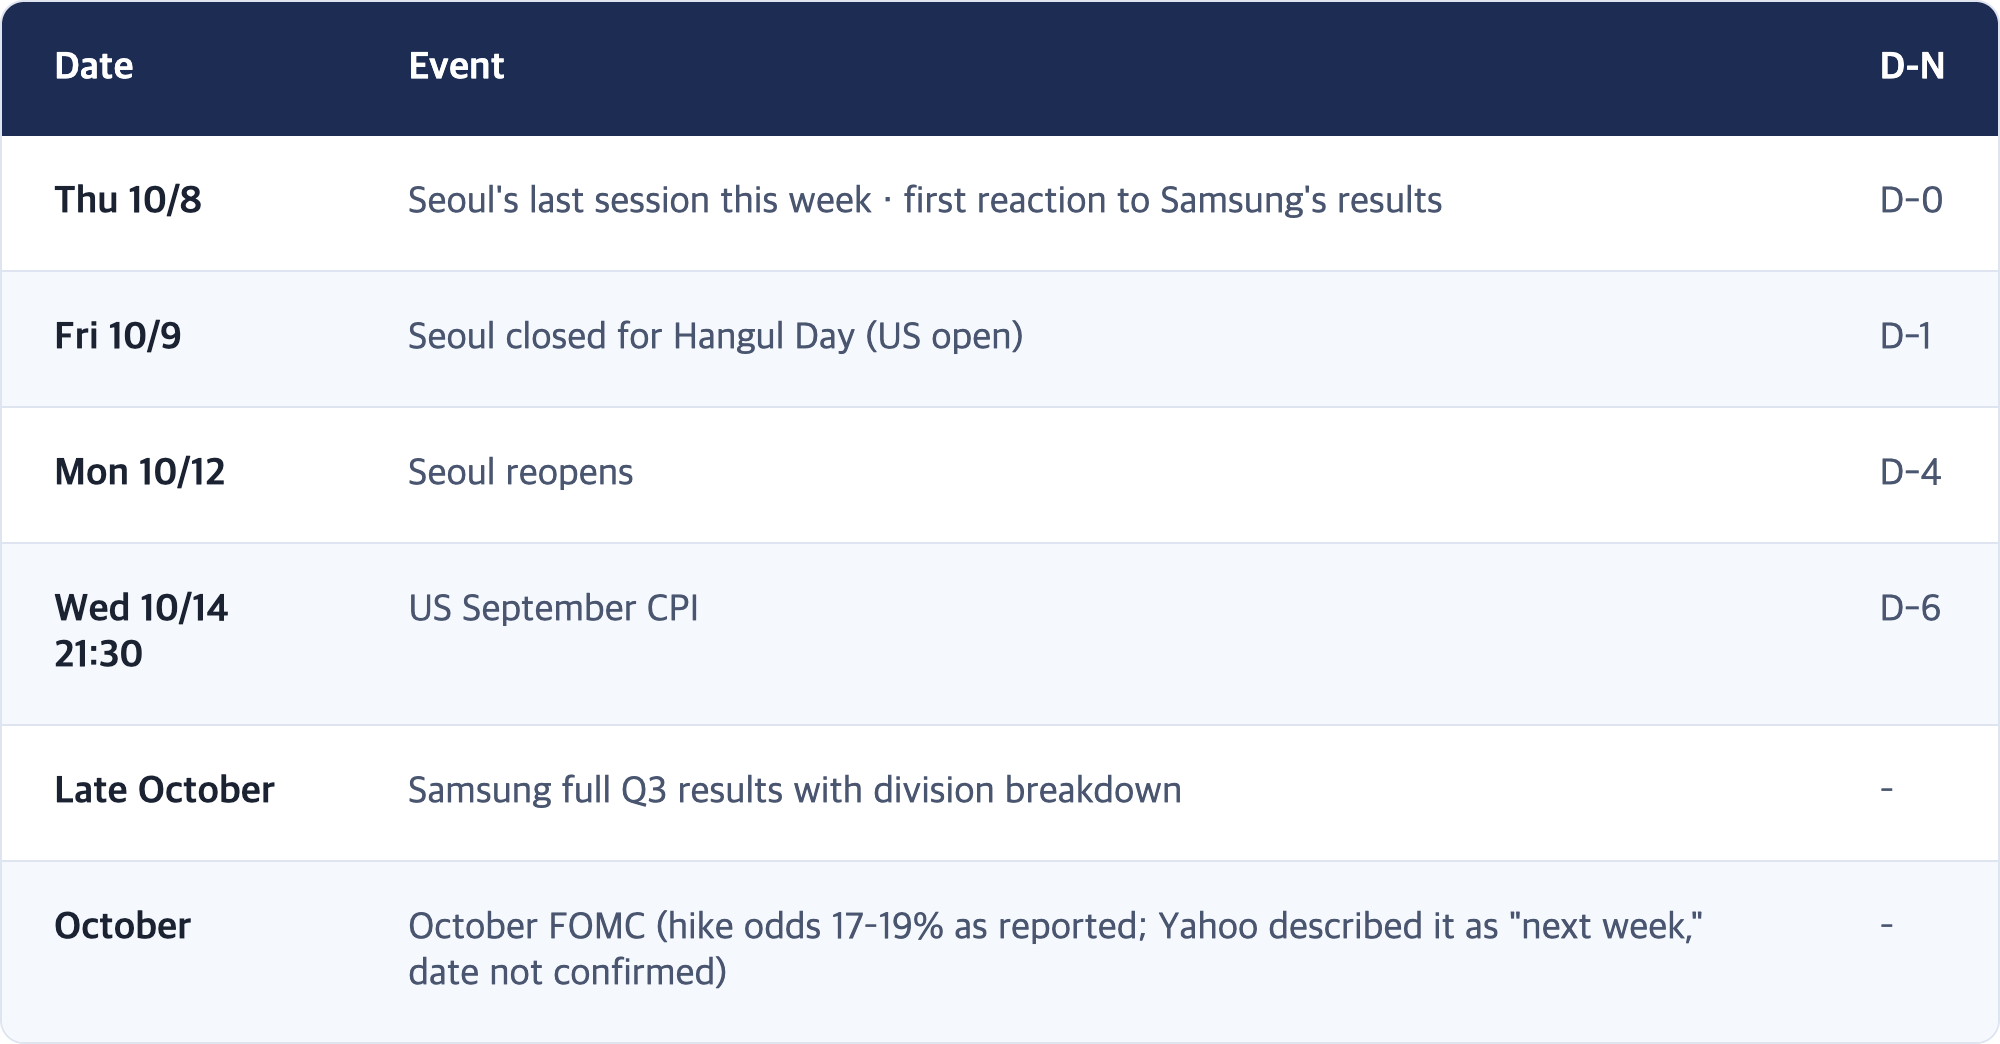
🟡 Today (Thu 10/8) is Seoul's last trading day of the week. Friday 10/9 is Hangul Day, a Korean holiday, so after today's close Seoul is shut for three days while New York trades two more sessions. Samsung's preliminary results came out this morning before the open.
SEO Intro
Wall Street stepped back from its records. The S&P 500 closed at 7,801.77 (−0.22%), the Nasdaq Composite at 27,538.69 (−0.22%) and the Dow at 51,179.87 (−0.66%), while the small-cap Russell 2000 fell 1.31%. The 10-year Treasury yield touched 5.36% intraday, its highest since April 2002, then fell back to 5.28% after a $39 billion 10-year auction drew strong demand. The September FOMC minutes said "most participants" saw another rate hike as likely appropriate by year-end.
Yet on that soft day, Micron rose 4.1% (single source) while the Philadelphia Semiconductor Index (SOX) fell 1.2%. Memory went the opposite way from the rest of the chip complex. On the same night that Seoul's foreign investors were dumping SK hynix for a second day, New York bought memory for the first time this week. Then, this morning, Samsung Electronics reported preliminary Q3 operating profit of ₩107.4 trillion (about $80 billion), the first ₩100-trillion quarter ever for a Korean company and inside the consensus range of ₩105–108 trillion. Revenue of ₩195 trillion, however, came in about 3% below expectations of ₩200–202 trillion.
1. Checkpoint Scorecard
The four from the 10/7 pre-US-open brief (US close 10/7)
The question was: "Is today's drop about rates or about memory?"
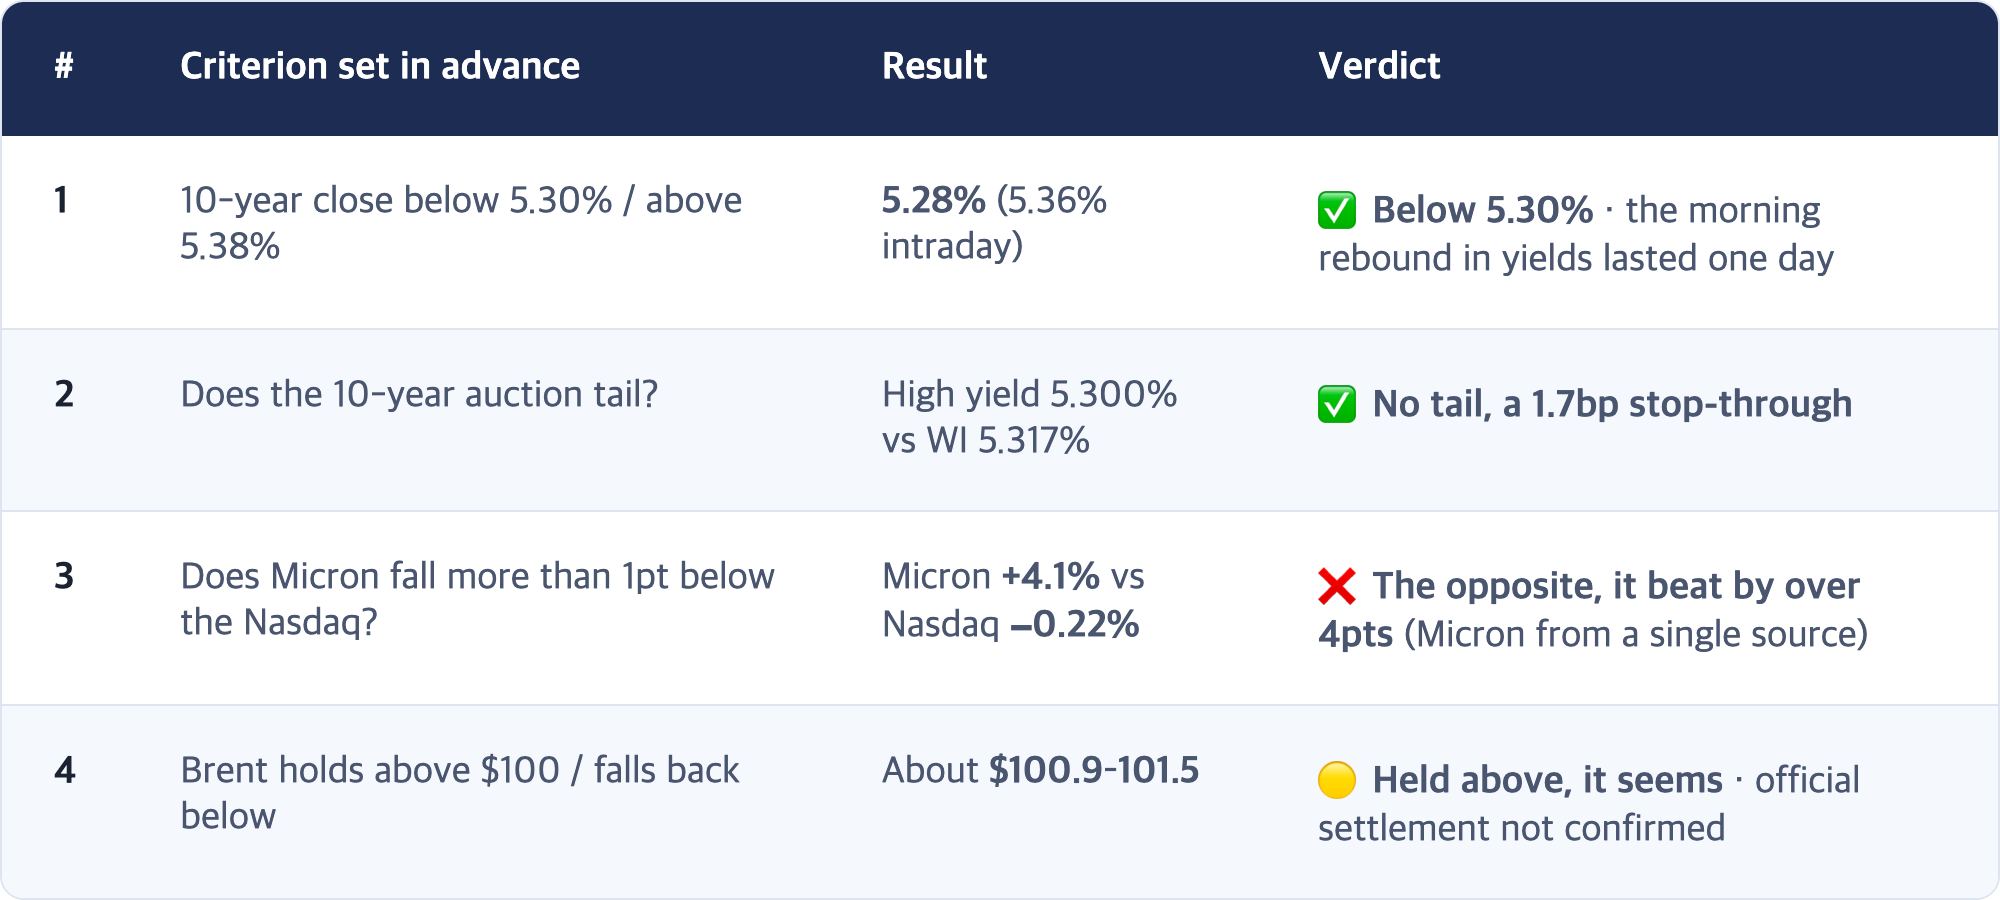
★ [Interpretation] The result fell into neither box we had drawn
The morning brief offered two pictures. If only Micron was weak, "Seoul's memory worry has spread to New York." If chips fell evenly, "it is still a rates story." What happened was a third picture: chips fell broadly (SOX −1.2%) while memory rose (Micron +4.1%).
So the morning's framing, "New York is following Seoul in selling memory," flipped within a day. Overnight, New York did the opposite of Seoul: it bought memory and sold AI chip designers. It is the same lesson this project wrote down on 9/28: if you frame a day as a choice between two options, the day a third variable shows up your verdict can be right while your explanation is wrong.
The four Seoul checkpoints from the 10/6 Korea brief were already scored in the 10/7 morning brief
Foreign flows ❌ (−₩2.6 trillion) · SK hynix vs KOSPI ❌ · USD/KRW 🟡 (1,340.4) · KOSPI ❌ (broke below 6,900).
2. Today's Key Story: New York Bought Memory, and Samsung Delivered "As Expected"
[Fact] US close, Wed 10/7 (05:00 KST Thu)
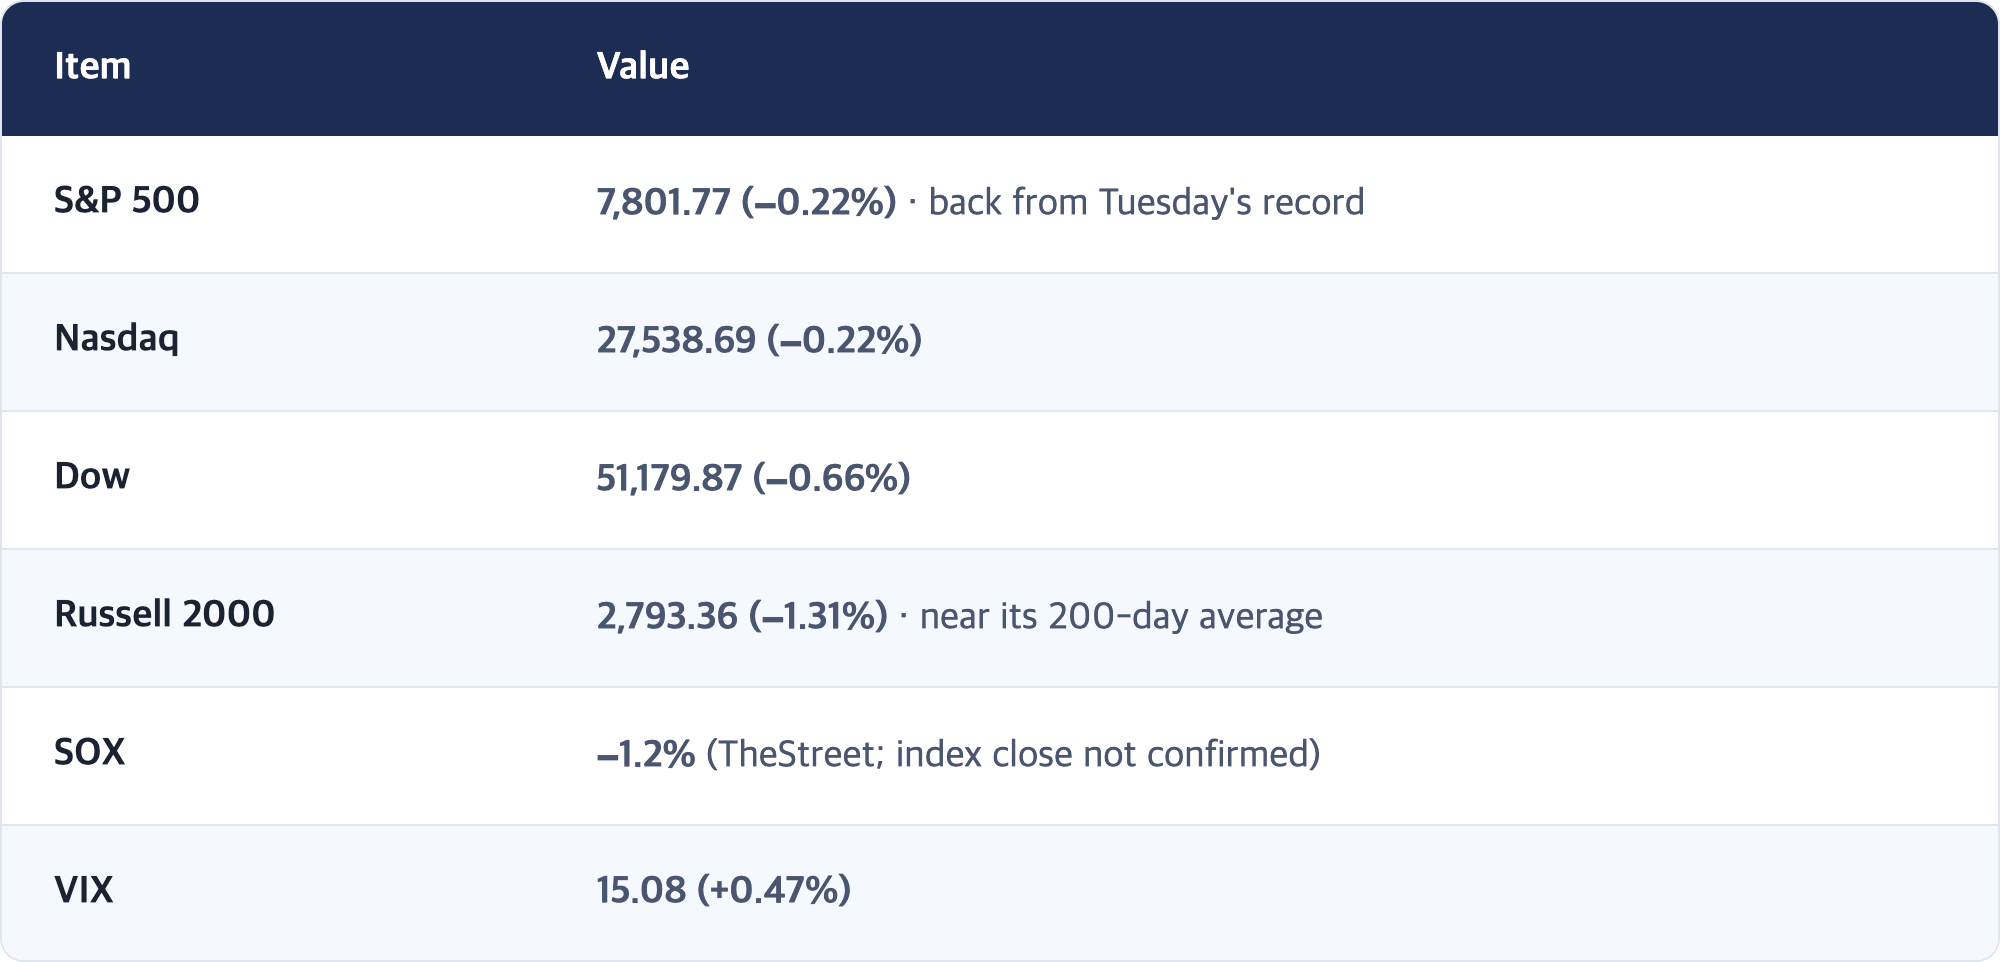
[Fact] Memory up, the rest down
- Micron +4.1%, Sandisk +1.9% (TheStreet closing commentary). Google Finance showed Micron +3.76% at 12:59 p.m. ET, the same direction.
- Nvidia −0.74%, AMD down less than 1% (Yahoo Finance). The leaders of the day before took a rest.
- Constellation Brands fell about 5% despite beating estimates.
[Fact] Samsung Electronics preliminary Q3 results (filed morning of 10/8 KST, consolidated)
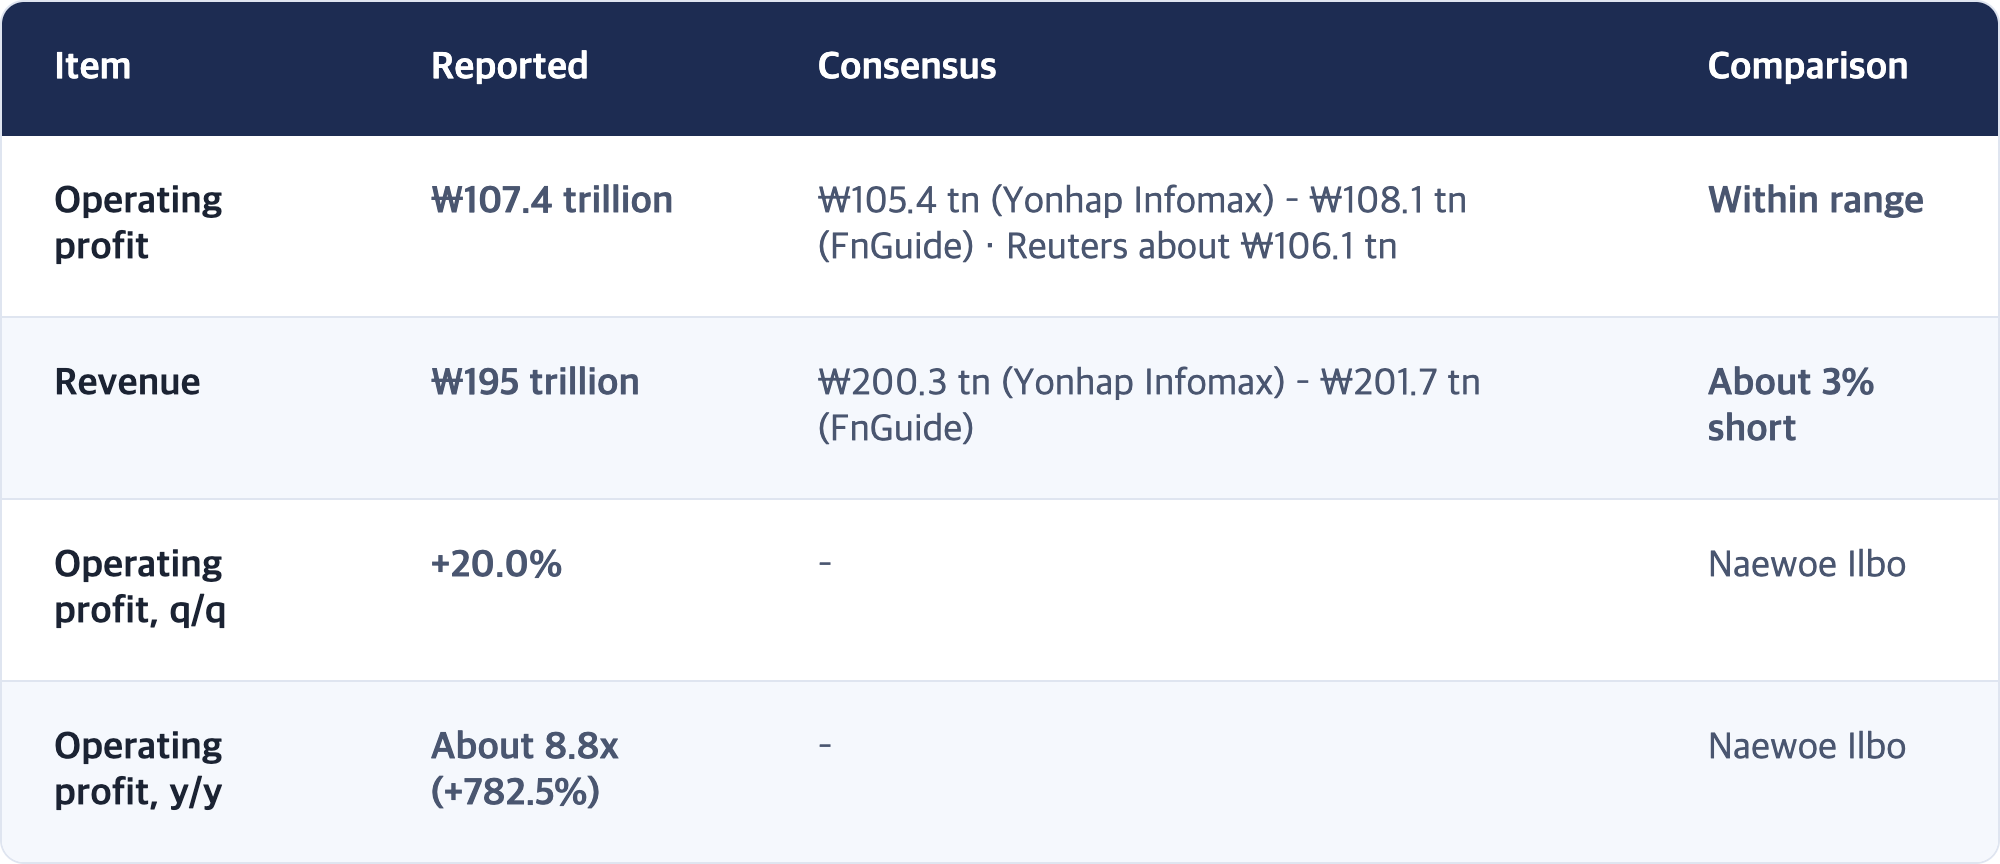
- It is the first quarter in which any Korean company has earned ₩100 trillion in operating profit.
- Preliminary results carry no division breakdown. The split between memory (DS) and finished devices (DX), and any comment on memory prices next quarter, come with the full results later this month.
★ [Interpretation] Seoul gets two numbers this morning
The first is Micron. The 10/6 Korea brief argued that the memory selloff was not about rates but about the market repricing memory itself. Last night pointed the other way. On a day when long yields hit a 24-year intraday high and chips fell broadly, Micron rose 4%. For at least one day, New York treated memory as a place to buy, not a place to hide from.
The second is Samsung. Operating profit landed inside the expected range, so no surprise there. What stands out is that revenue fell short while profit did not, which implies margins were higher than expected. Before the release Goldman Sachs had flagged a stronger won (Q3 average about 1,418 per dollar versus an assumed 1,460) as a drag, and that would shrink dollar sales once converted into won. That is an interpretation; the cause will be clearer when full results arrive.
Put together, Seoul's memory stocks open with a good signal from abroad (Micron +4%) and a "no surprise" from home (Samsung in line). How foreign investors, who sold more than ₩4 trillion over two days, read that combination is today's key question.
3. The Korea Variable: The Last Session Before a Three-Day Break
[Fact] Seoul close, Wed 10/7
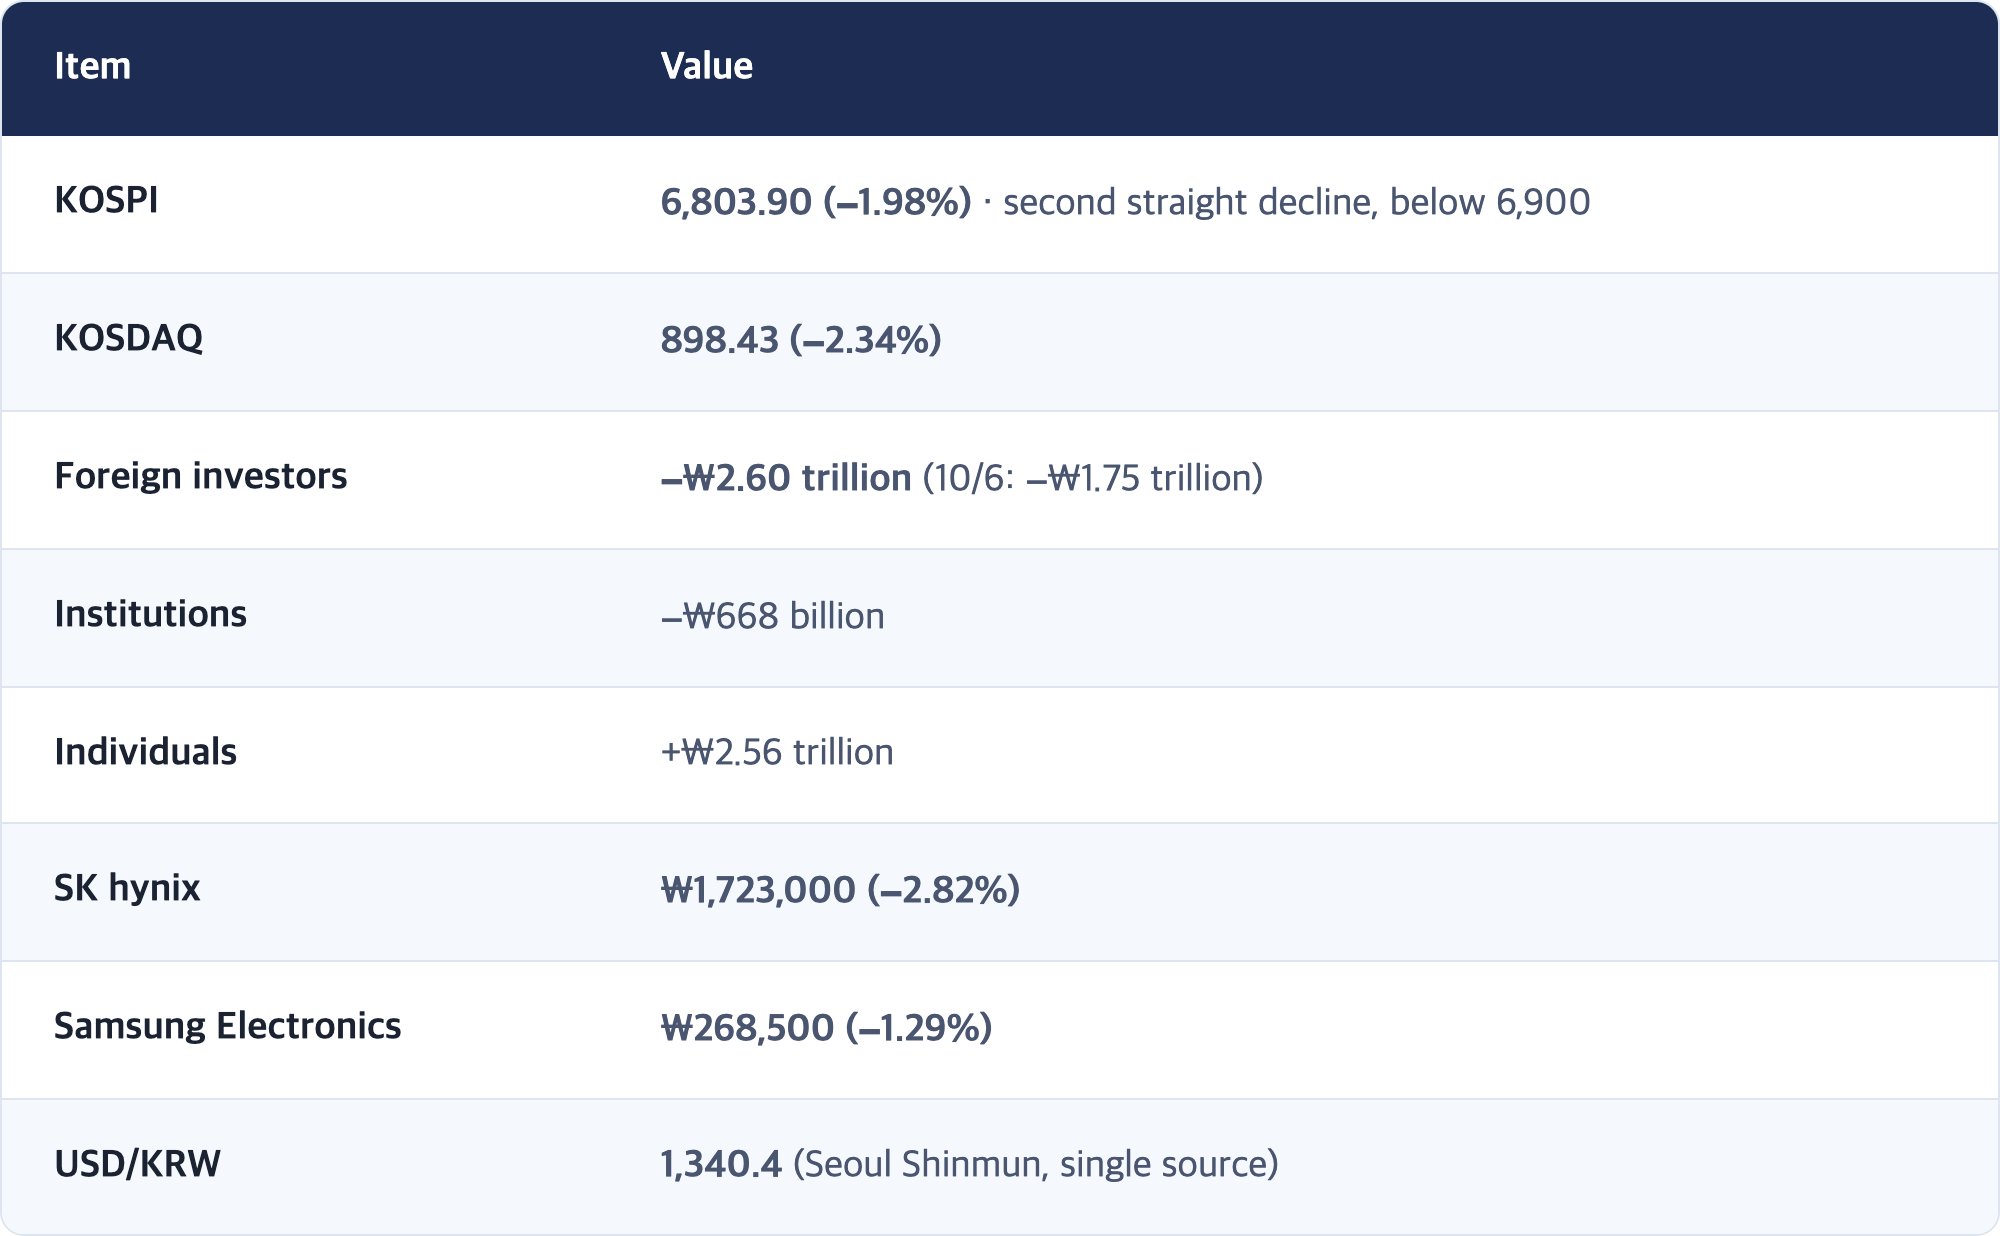
[Fact] Rest of the week (KST)
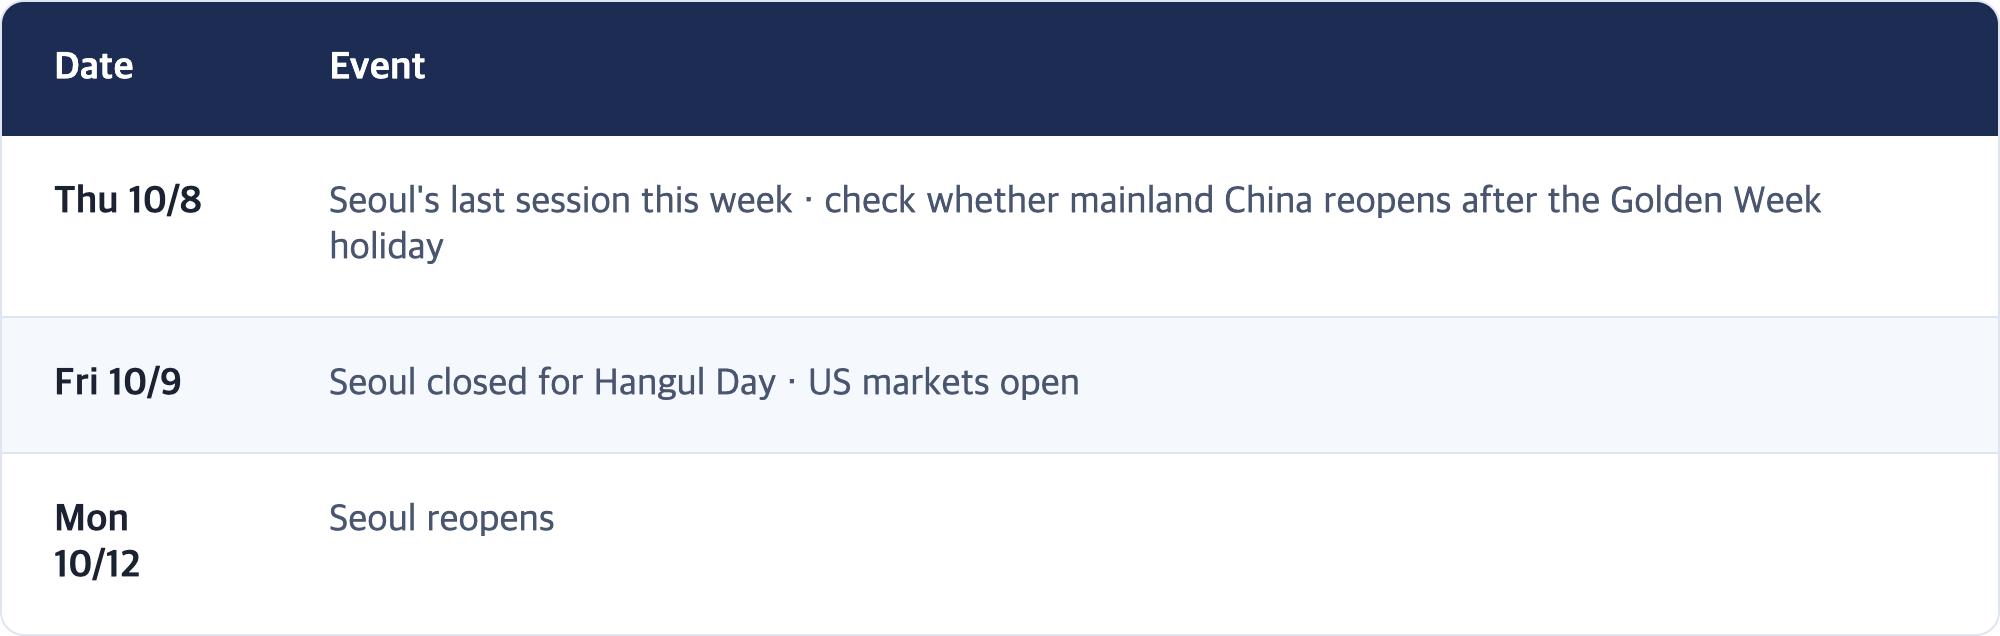
★ [Interpretation] Today is also about pre-holiday positioning
Seoul is shut Friday through Sunday while US markets trade Thursday and Friday, and the US September consumer price index (CPI) lands next Wednesday (10/14). So foreign flows today mix two things: how investors read Samsung's numbers, and how much risk they want to cut before three days in which they cannot trade in Seoul. A smaller sell figure would not prove an earnings reaction, and a continued big sell figure would not prove an earnings disappointment.
The single most informative comparison is this: does SK hynix pick up Micron's 4% gain? If it fails again and lags the KOSPI, the weight shifts toward "Seoul's memory selling is a Seoul-only flow story, unrelated to New York."
4. Macro Backdrop: The Fed Says "One More by Year-End," and the Auction Held Yields
[Fact] Treasuries and commodities (10/7)
[Fact] FOMC minutes (Sept 15–16 meeting, released 03:00 KST 10/8)
- All participants, including the seven non-voters, supported raising the target range to 3.75–4.00%.
- "Most participants assessed that another increase … would likely be appropriate by year end." No specific meeting named.
- Inflation risks tilted to the upside; labor market risks "diminished" and "broadly balanced."
- Some saw policy as "not restrictive or only mildly restrictive"; a couple raised their neutral-rate estimates.
- Staff estimated August PCE inflation at 3.8% headline and 3.4% core, and do not see inflation back at 2% until 2029.
- Upside risks cited: energy prices, inflation expectations and AI-driven demand.
[Fact] 10-year note auction ($39 billion, 02:00 KST 10/8)
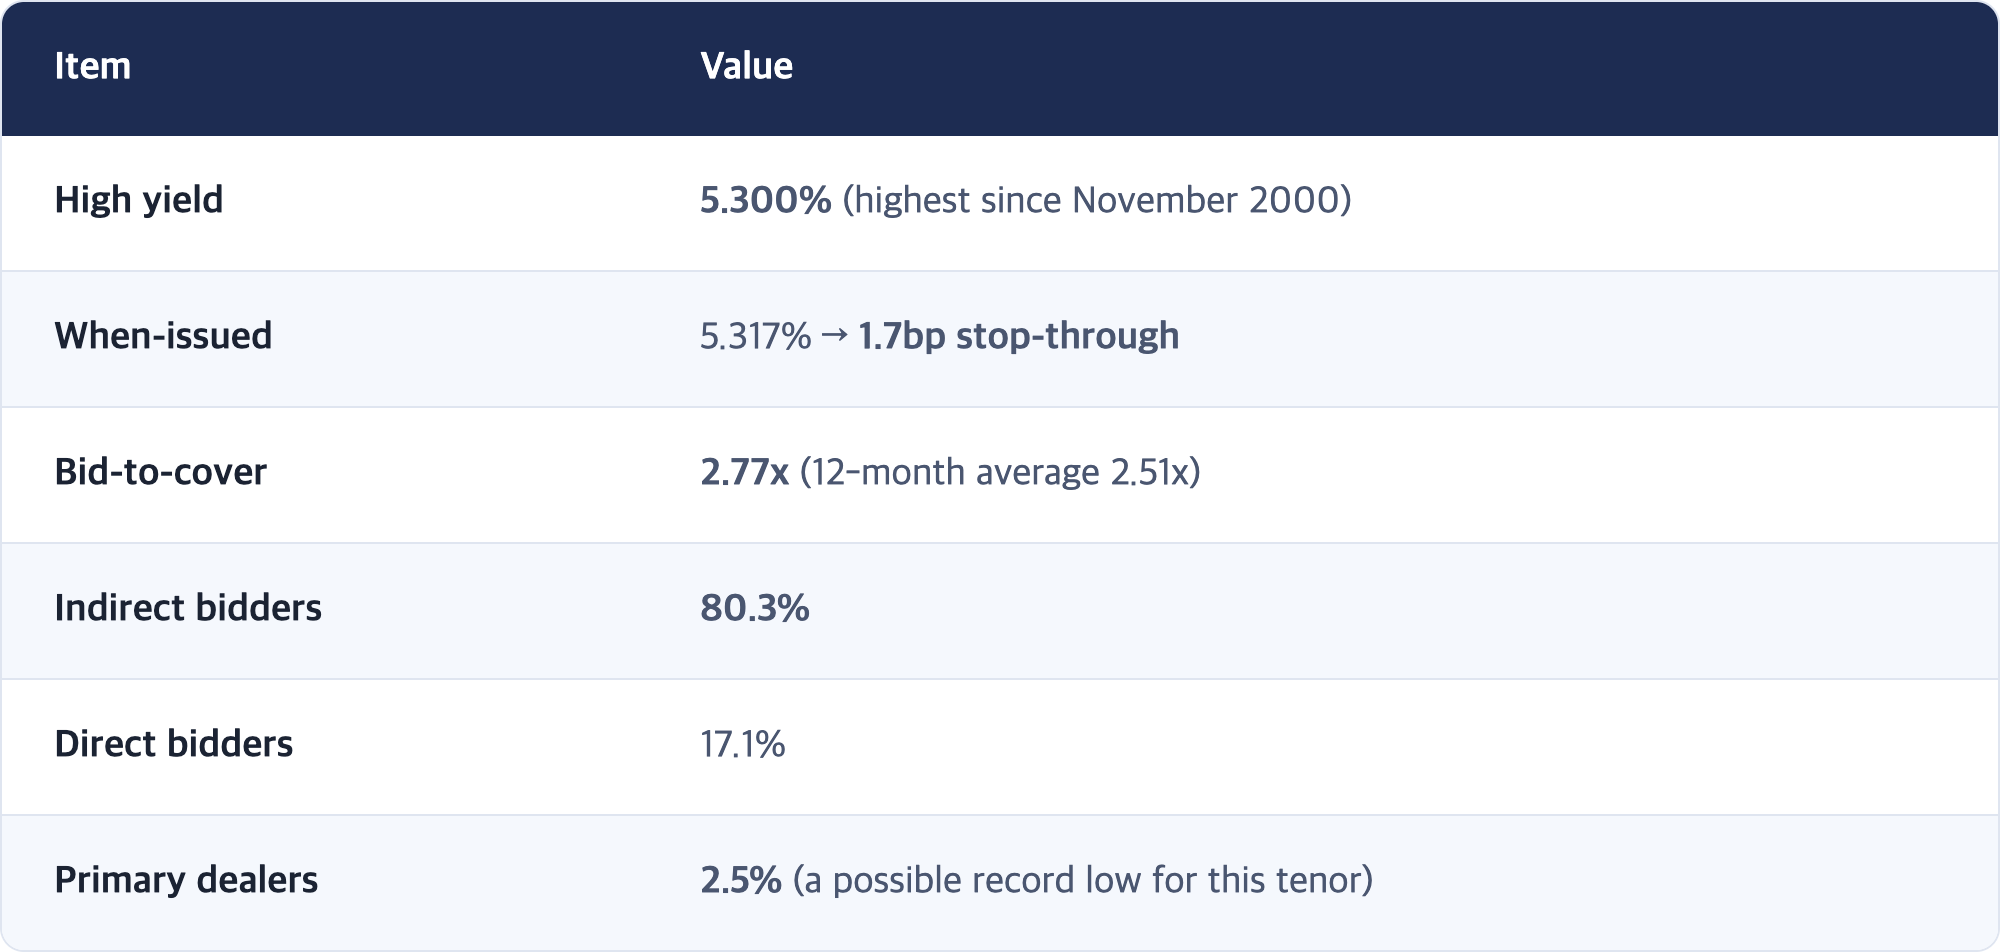
★ [Interpretation] The issue was never only how high yields are, but whether anyone buys at that level
Both this week's 3-year (10/6) and 10-year (10/7) auctions stopped through. In the 10-year, indirect bidders took over 80% and the dealers who absorb unsold supply were left with only 2.5%. At 5.3%, there was plenty of money willing to buy.
The minutes were hawkish, but they said "by year-end," not "in October," and October hike odds barely moved. So yesterday in rates can be summed up as "the minutes pushed yields up and the auction pulled them back." The 30-year, however, still posted its highest close in 24 years. It is too early to say the upward pressure on long yields has eased.
5. Today's Korean Session (Thu 10/8 KST) Preview
The question
The four checkpoints ask: "On the night New York bought memory, does Seoul also stop selling it, or does a Seoul-only flow continue?"
✅ Four checkpoints (Seoul close today)
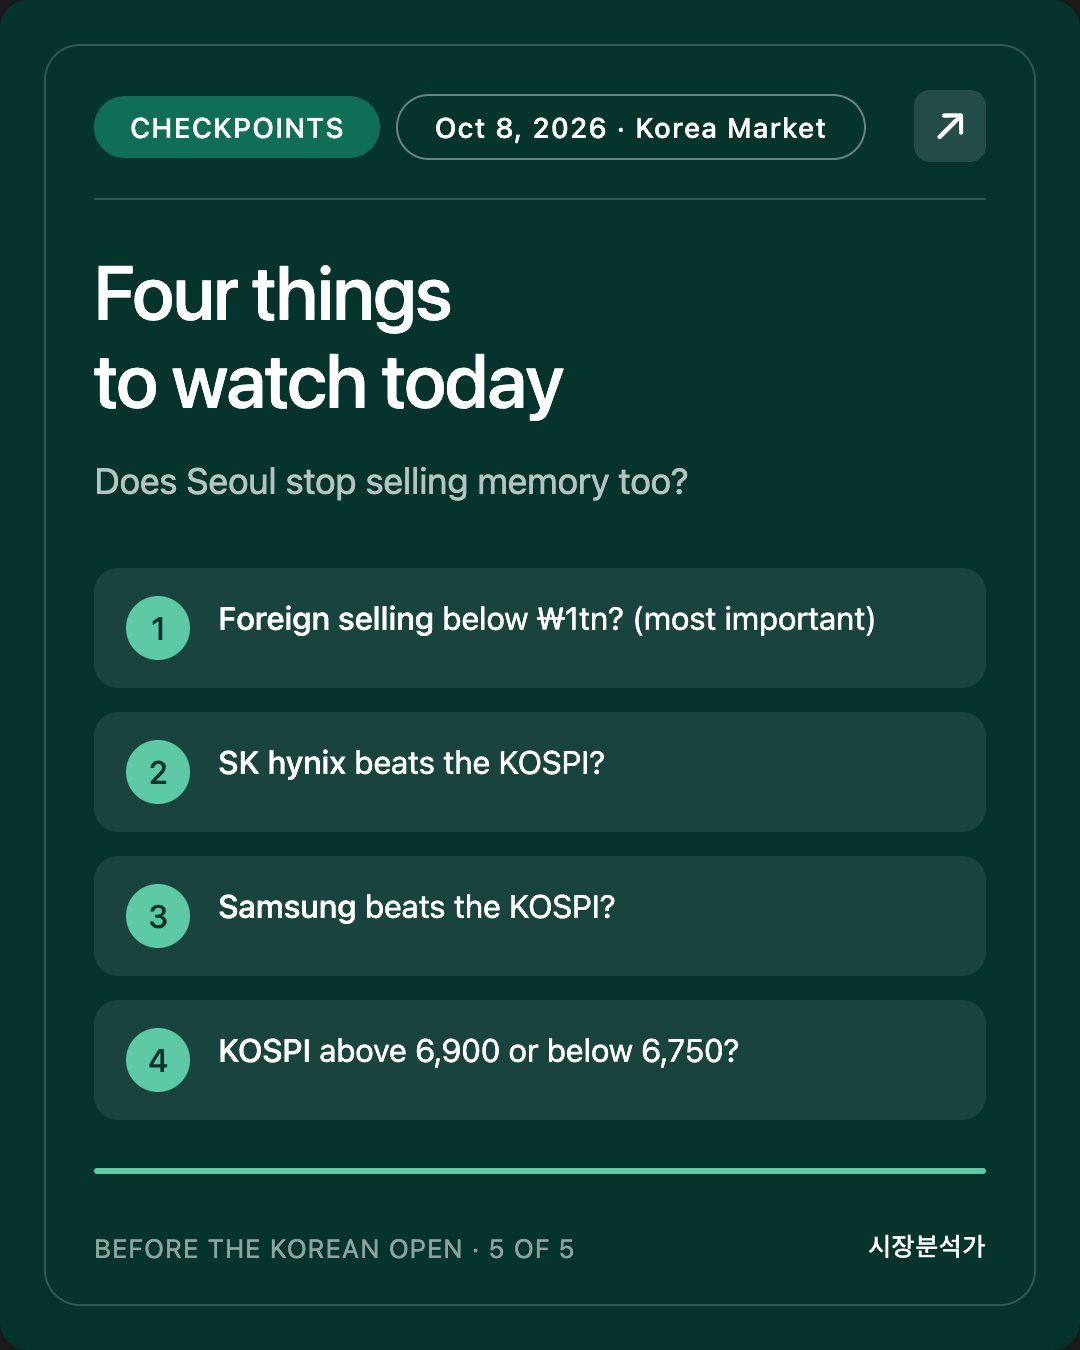
- Does net foreign selling shrink below ₩1 trillion, or turn to buying? A third day in the ₩2 trillion range would point to selling unrelated to earnings or Micron. (Most important)
- Does SK hynix beat the KOSPI? The most direct test of whether Micron's 4% carries over.
- Does Samsung Electronics beat the KOSPI? Is "in line" read as "nothing left to buy on," or as relief?
- KOSPI back above 6,900 / below 6,750. The close going into a three-day break.
[Interpretation] The most informative pair is #1 and #2. If foreign selling shrinks sharply and SK hynix beats the index, "Seoul's memory selling was waiting for New York." If foreigners keep selling ₩2 trillion-plus and SK hynix lags again, "this is Seoul's own repricing, or pre-holiday de-risking, unrelated to New York."
6. Study Note: What Are "Preliminary Results," and Why Can "In Line" Be Boring for a Stock?
Concept
Preliminary results are a filing in which a company announces just two or three headline numbers, revenue and operating profit, shortly after a quarter ends and before the audit is complete. Samsung publishes them about a week after quarter-end, and the division breakdown and commentary follow roughly three weeks later with the full results.
Analogy
It is like getting a text with only your total exam score, with the subject-by-subject report card to follow. If the total is about what you expected, the real questions become "which subjects did well, and how will next term go?"
Real example
Samsung's ₩107.4 trillion operating profit sits inside the consensus range of ₩105.4–108.1 trillion. Stocks usually react to how far results differ from expectations, so an in-line number has little force on its own. That is why today's market is likely to watch Micron overnight, foreign flows, and the memory-price commentary due with full results later this month more than the headline number. It extends a rule this project wrote down on 9/11: measure a surprise against what prices had already assumed, not just against the consensus.
One-line takeaway
Preliminary results are a report card showing only the total; when the total is as expected, the market immediately asks about next term.
7. Corrections and Open Items
Corrections
- None. (The 10/7 morning brief's framing for checkpoint #3 missed, which is recorded in Section 1 as a verdict, not a correction.)
Source discrepancies (value used stated)
- 10-year close: 5.28% (Treasury par yield, TheStreet) vs 5.28–5.32% depending on time. 5.28% used. Intraday high 5.35% (CNBC summary) vs 5.36% (Yahoo). 5.36% used.
- 30-year close: 5.66% (Yahoo) vs 5.67% (TheStreet, incl. after-hours). Range shown.
- WTI: −1.3% to about $88 (TheStreet) vs +0.46% to $89.85 (Trading Economics) vs $90.09 (Investing.com). Directions conflict, so only a range is shown.
- Brent: $100.87 (Trading Economics) to $101.50 (Investing.com). Range shown.
- Samsung consensus: ₩105.4 tn (Yonhap Infomax) · ₩106.1 tn (Reuters) · ₩108.1–108.7 tn (FnGuide, by date). Range shown.
- October hike odds: 17% (Yahoo) vs 19% (investingLive). CME FedWatch not checked directly. Range shown.
🔲 Not yet confirmed
- Micron +4.1% and SOX −1.2% come from a single source (TheStreet). This matters because checkpoint #2 rests on it.
- SOX index close, dollar index close, 2-year level and the overnight USD/KRW non-deliverable forward not obtained.
- USD/KRW 10/7 close of 1,340.4 is still single-sourced.
- Korean 10-year government bond yield not obtained (13th straight brief).
8. Event Calendar (KST)
Sources
- Yahoo Finance: Dow falls, S&P 500 and Nasdaq retreat from records amid bond market jitters (10/7)
- TheStreet Pro: Stocks slip from records but pare losses after strong 10-year auction
- TheStreet: Stock Market Today (Oct. 7, 2026)
- CNBC: 10-year Treasury yield backs off from 24-year high after solid bond auction
- Helious: 10-Year Treasury Auction Results, Oct 7, 2026
- TFTC: 10-Year Treasury Auction 5.300% Yield
- Federal Reserve: Minutes of the FOMC, September 15-16, 2026
- investingLive: FOMC Minutes, most participants assessed another hike would likely be appropriate by year end
- Money Today: Samsung Electronics Q3 operating profit ₩107.4 trillion, meets expectations (10/8, Korean)
- Naewoe Ilbo: Samsung Electronics Q3 2026 preliminary results (Korean)
- Electronic Times: Goldman Sachs trims Samsung estimate ahead of results (Korean)
- Trading Economics: Brent crude oil
- Investing.com: Crude Oil WTI Historical Data
- Seoul Shinmun: KOSPI falls for a second day (10/7, Korean)
📌 More market briefs
※ This post is market observation and organization intended to support your own judgment. It is not a recommendation to buy or sell any security. Figures are as of the time of writing and may differ between sources.
If this was useful, bookmark it or pass it along. It genuinely helps me write the next one.
I can survive. We can survive.