October 7, 2026 US Market Brief — Nasdaq and S&P 500 Before the Open
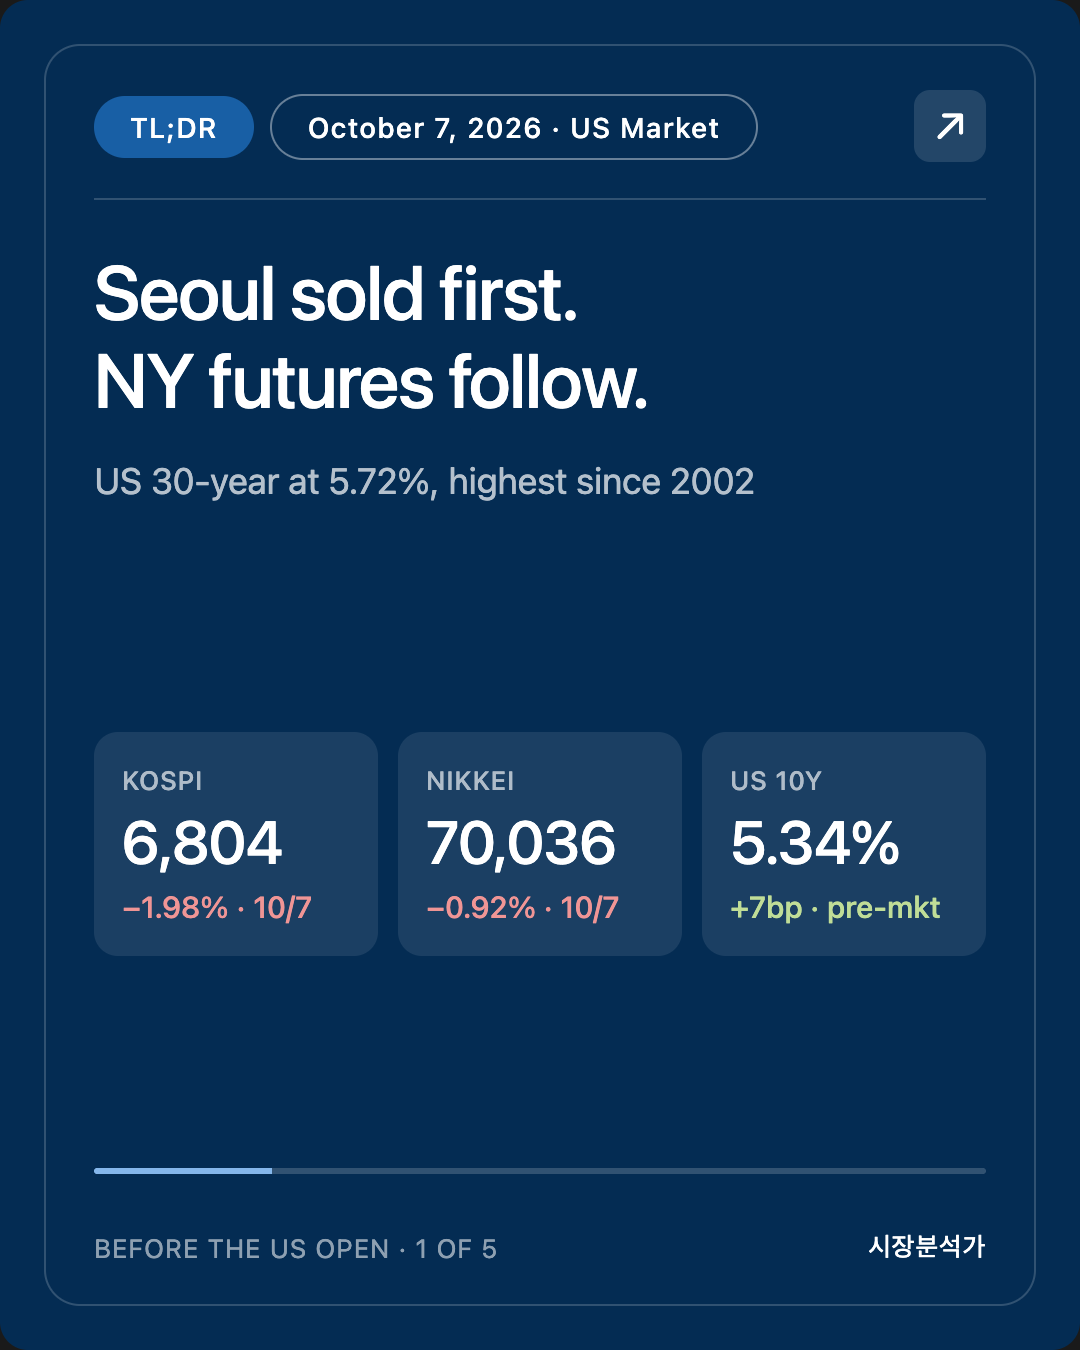
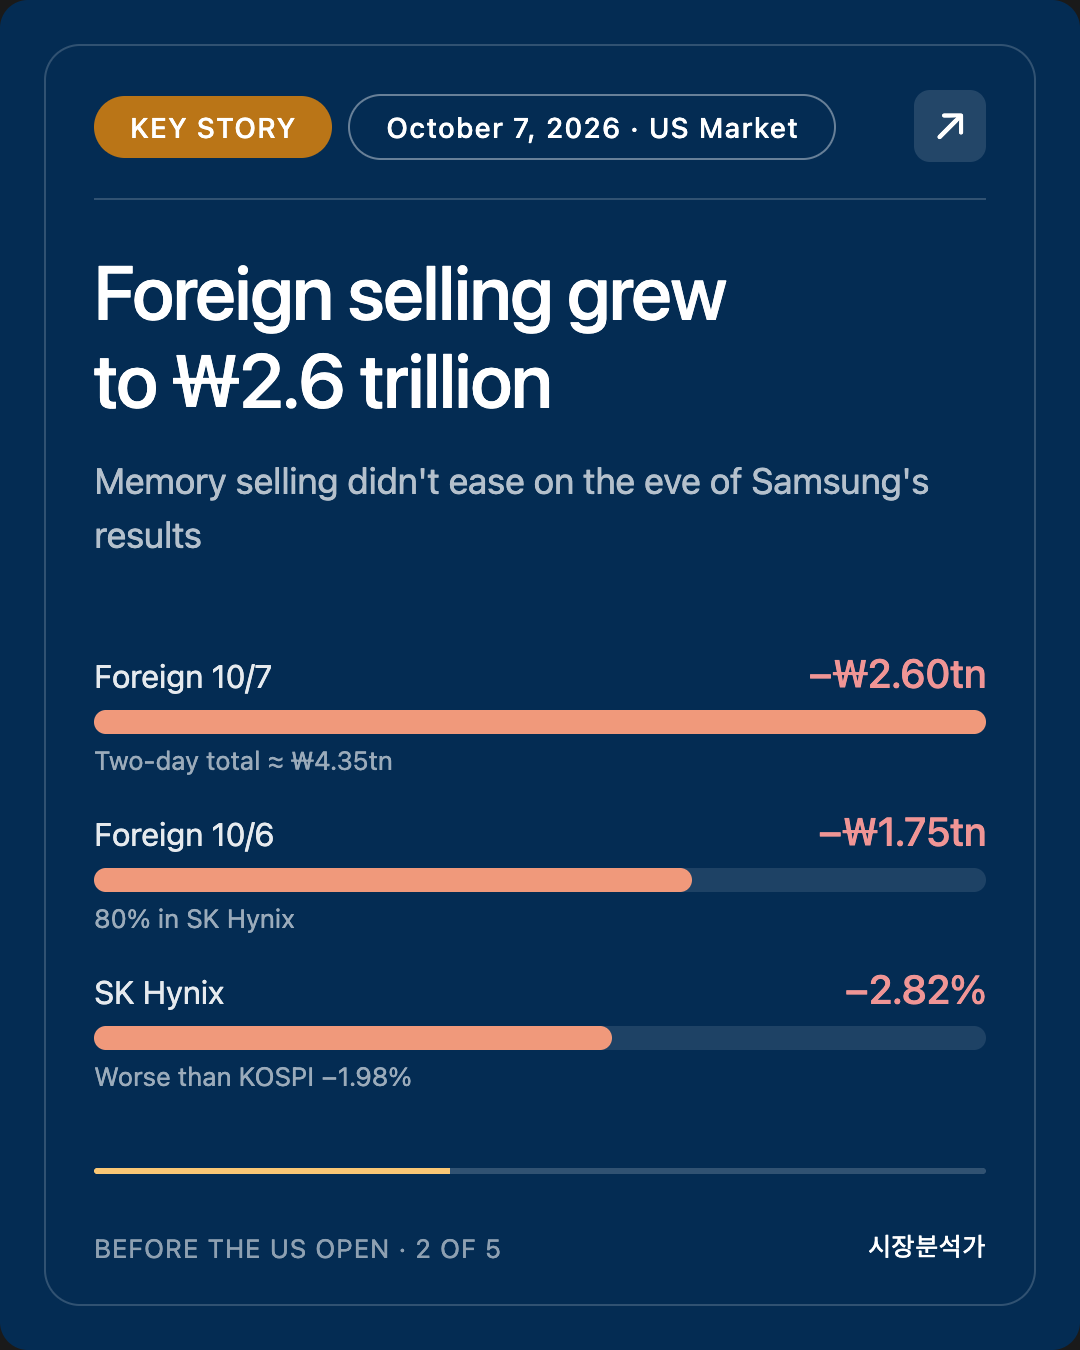
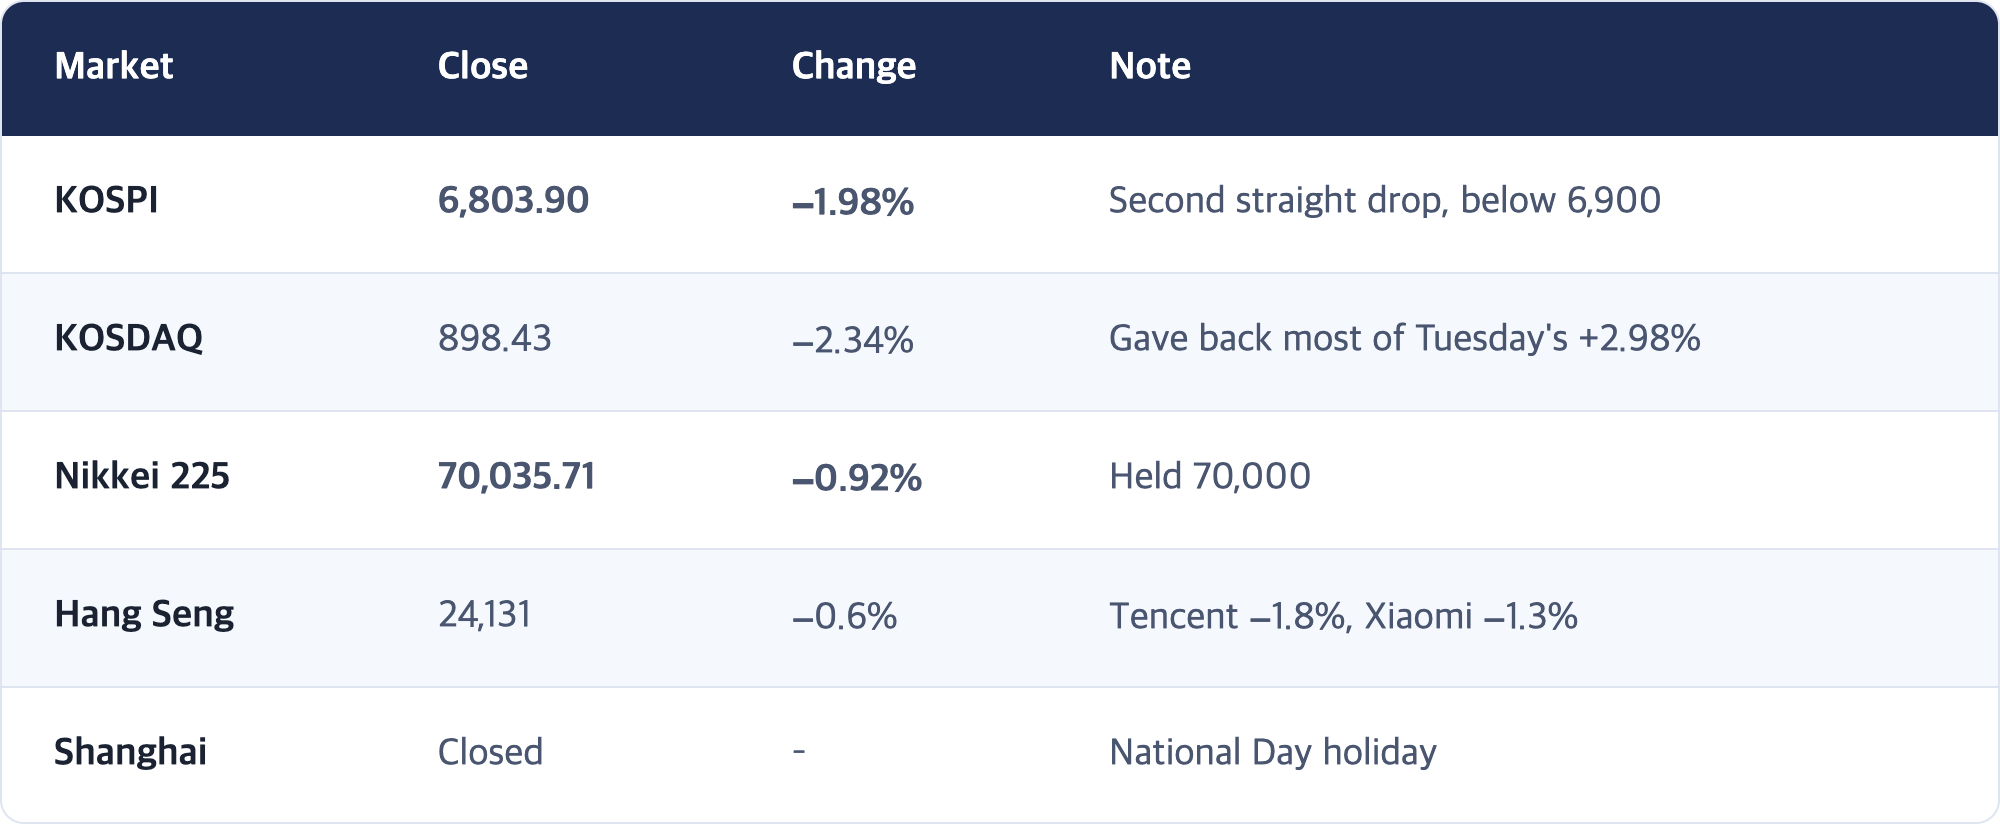
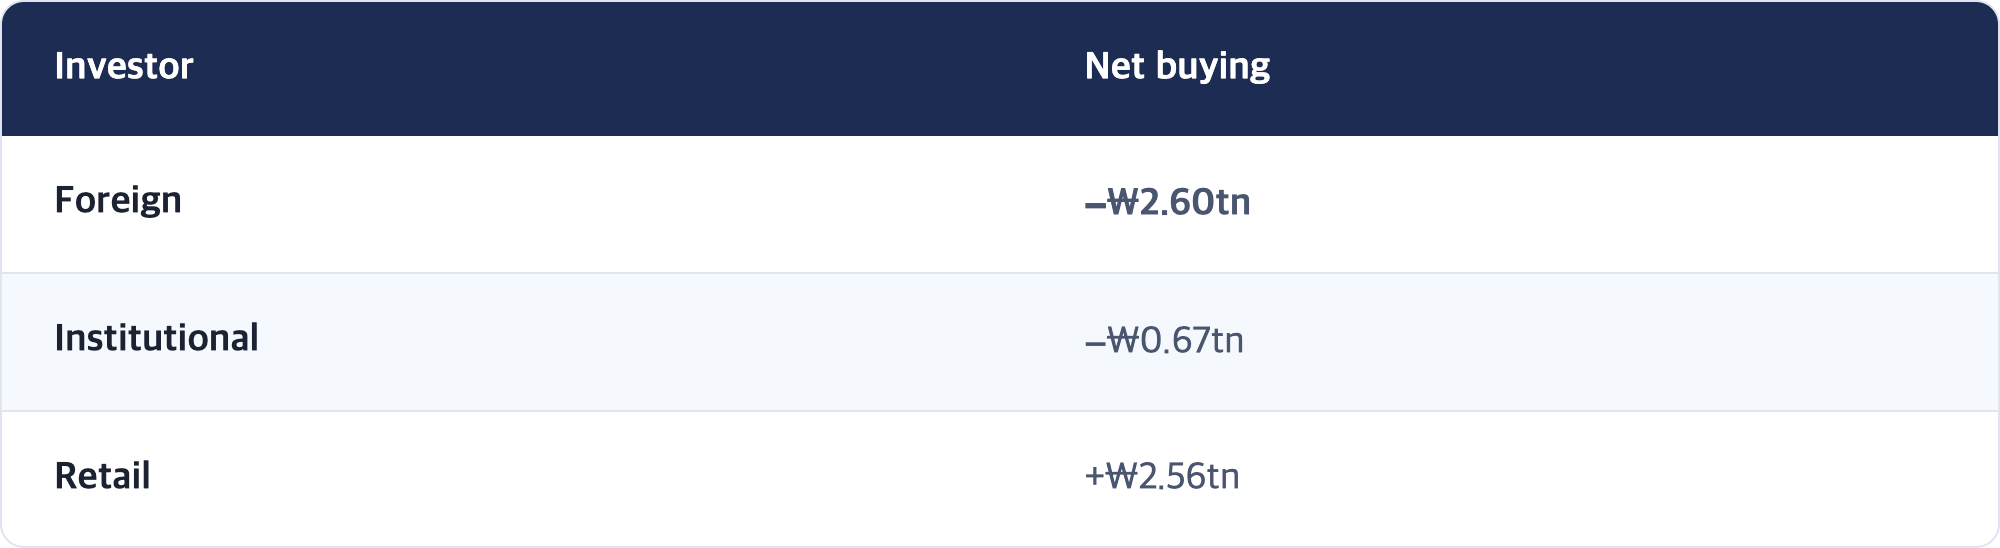
- ★ Seoul sold more memory, not less. KOSPI 6,803.90 (−1.98%). Foreigners −₩2.60tn (prior day −₩1.75tn), institutions −₩0.67tn, retail +₩2.56tn. SK Hynix −2.82%, Samsung Electronics −1.29%. KOSDAQ −2.34%.
- ★ Tokyo took profits in chips too. Nikkei 70,035.71 (−0.92%), first drop in three sessions, led by Advantest and Tokyo Electron. Hang Seng 24,131 (−0.6%). Mainland China closed.
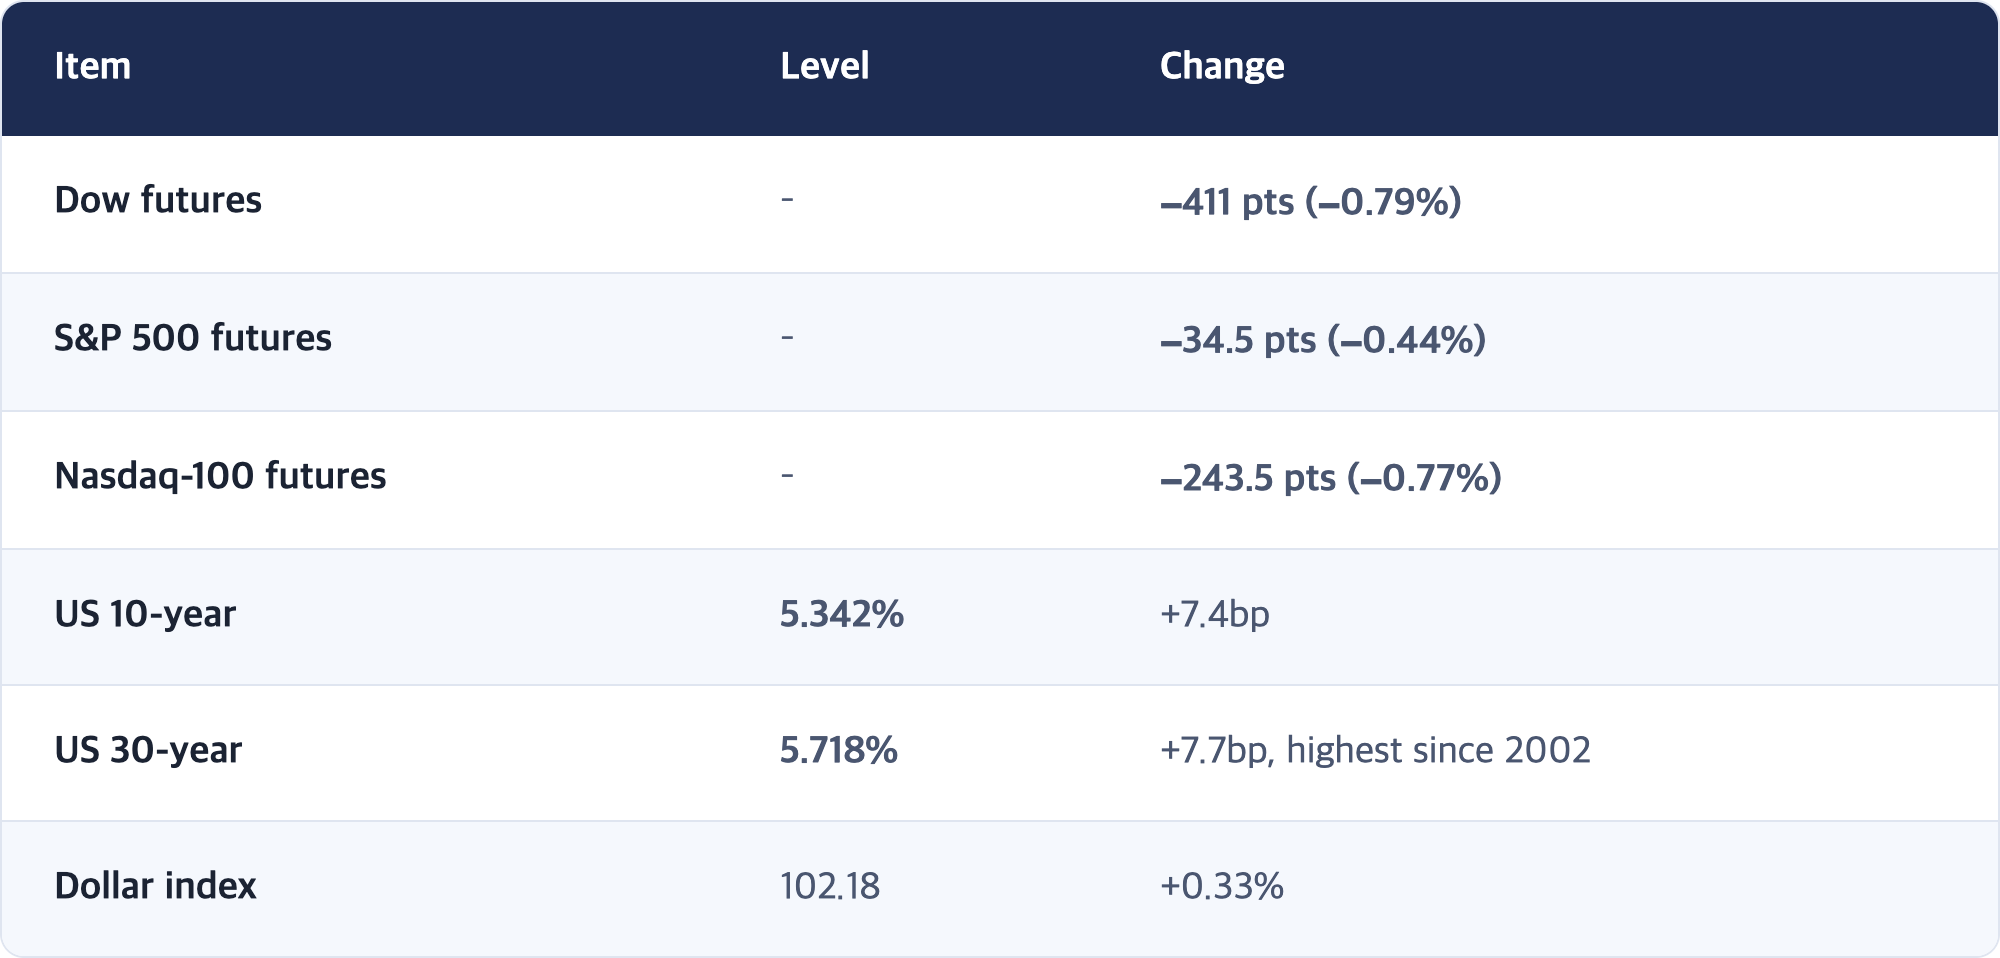
- ★ US long yields erased yesterday's relief in one night. 10-year 5.34% (+7bp), 30-year 5.72%, highest since 2002.
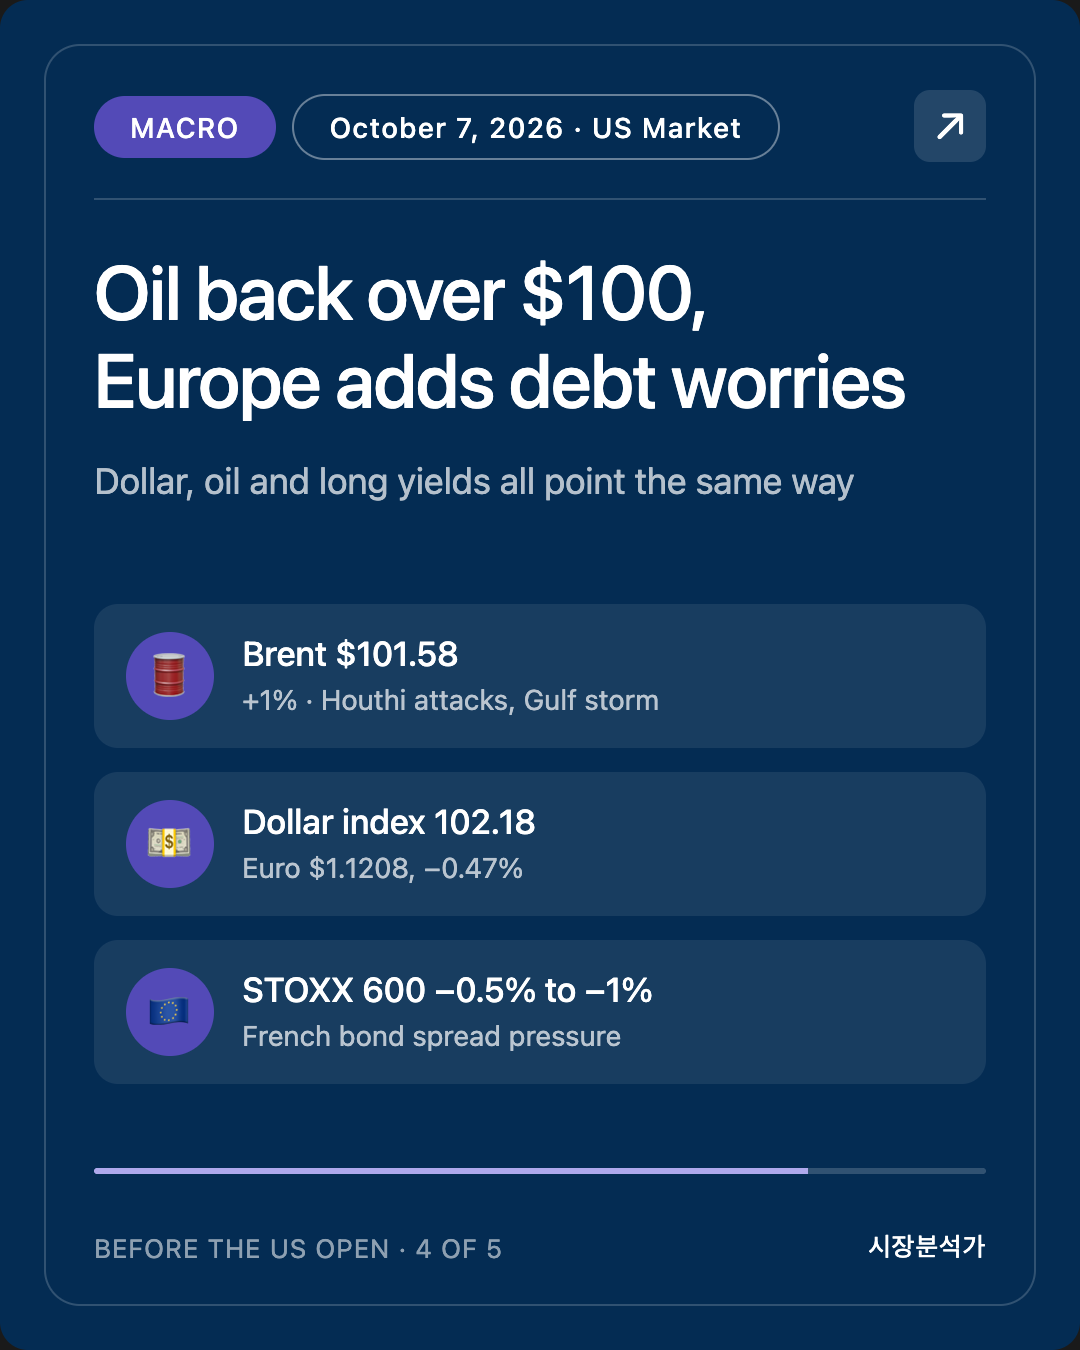
- Oil back above $100. Brent $101.58 (+1%) on Houthi attacks on Saudi Arabia and a storm heading toward US Gulf oil facilities. Dollar index 102.18, euro $1.1208 (−0.47%), STOXX 600 −0.5% to −1%.
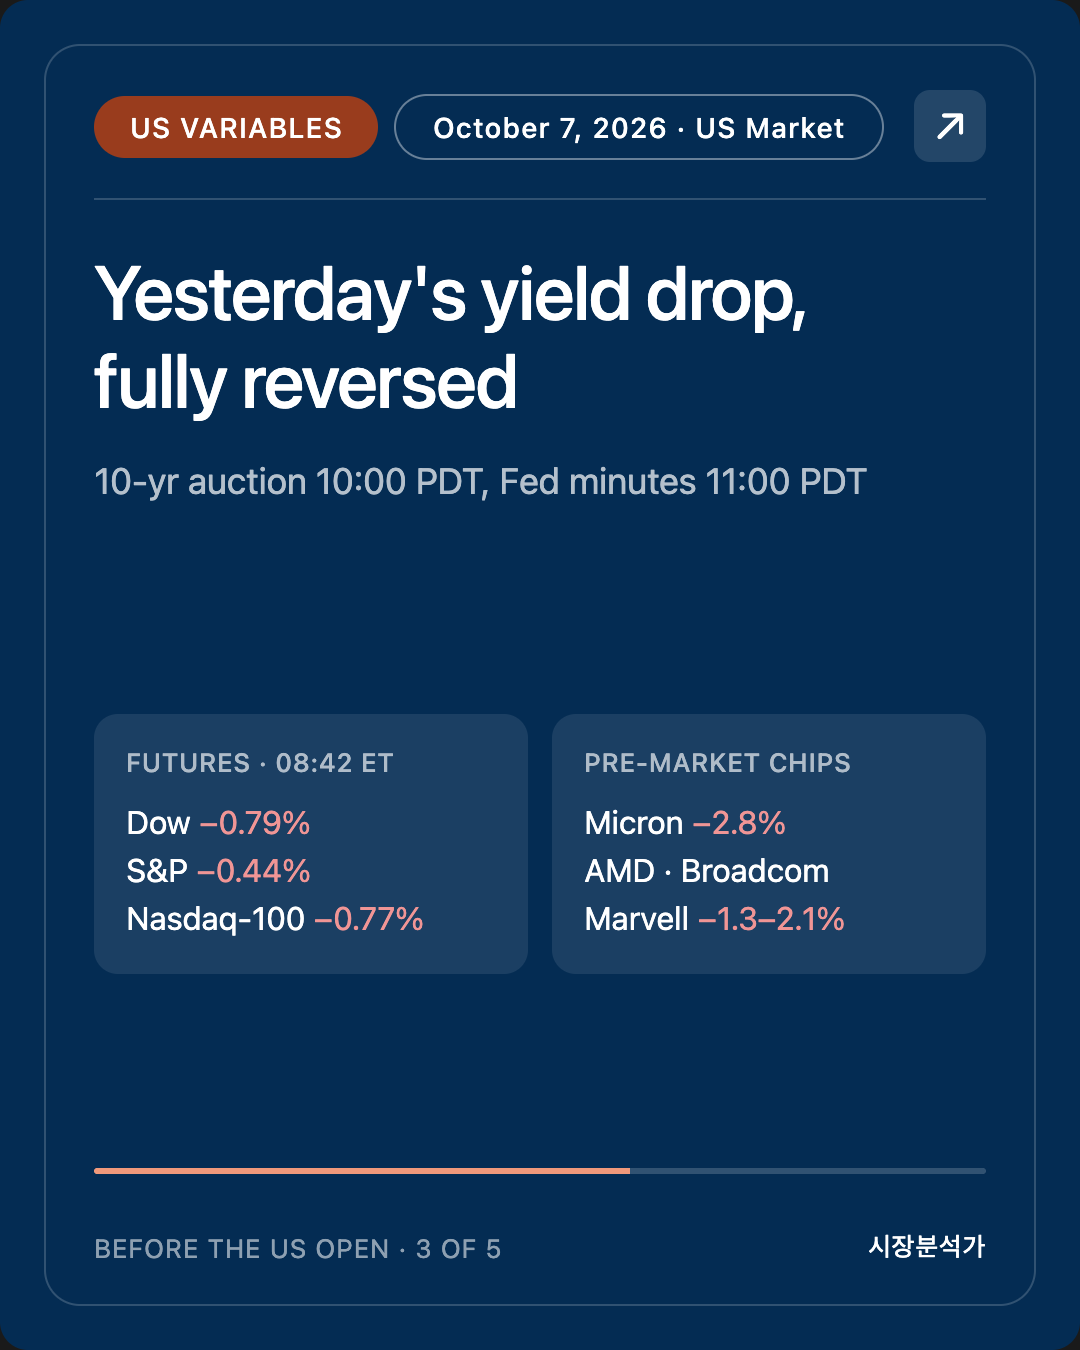
- Futures lower, yesterday's leaders lower still. Micron −2.8%, AMD/Broadcom/Marvell −1.3% to −2.1%. CME FedWatch puts the odds of an October hike at 22% (via FXStreet).
This is Mr. Can. Here is the October 7, 2026 brief ahead of the US market open.
Written: 2026-10-07 05:50 PDT (Seoul 10/7 21:50 KST)
Basis: Seoul close 10/7 + Tokyo and Hong Kong close 10/7 (mainland China shut for the National Day holiday) + Europe intraday 10/7 + US pre-market as of 08:42 ET
🟢 Scheduled 05:30 PDT, started 05:43 PDT. US figures are pre-market.
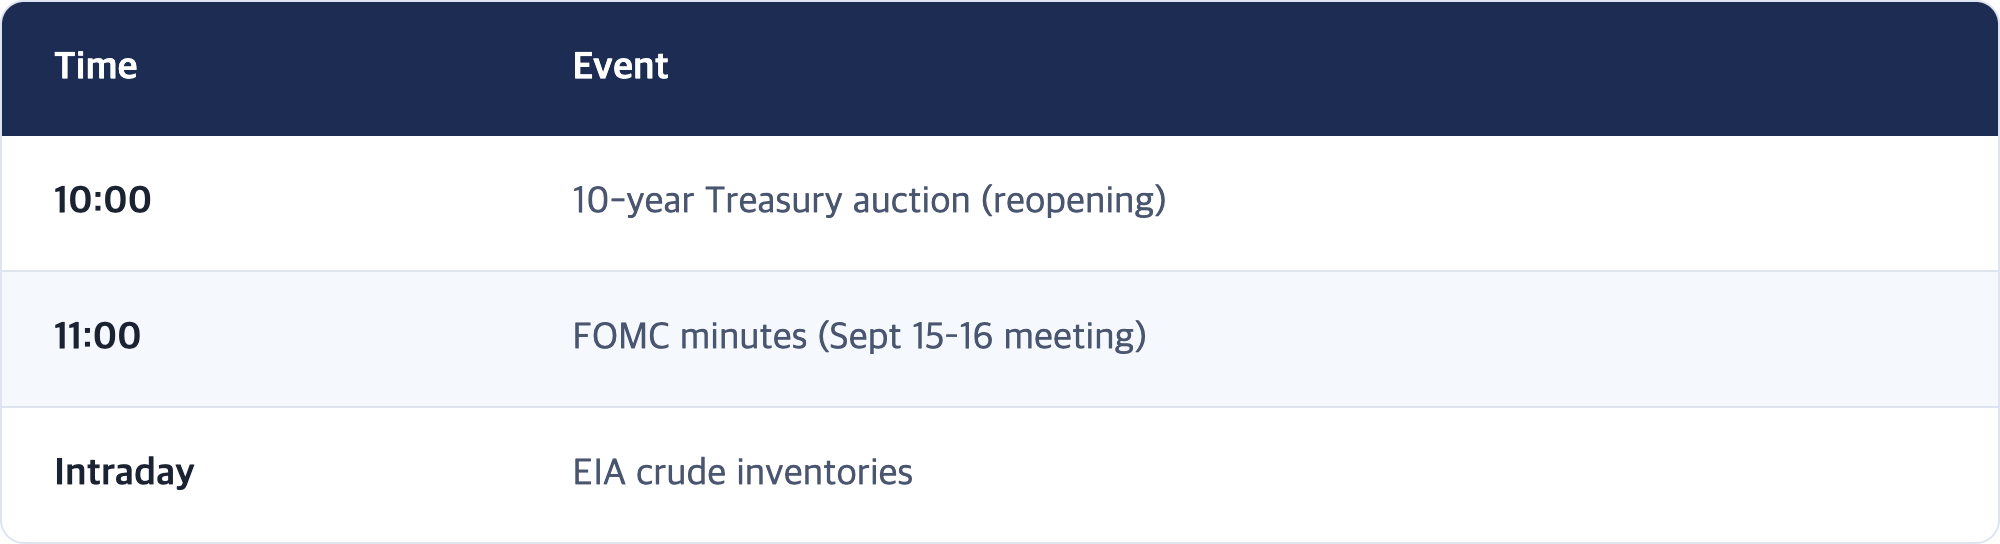
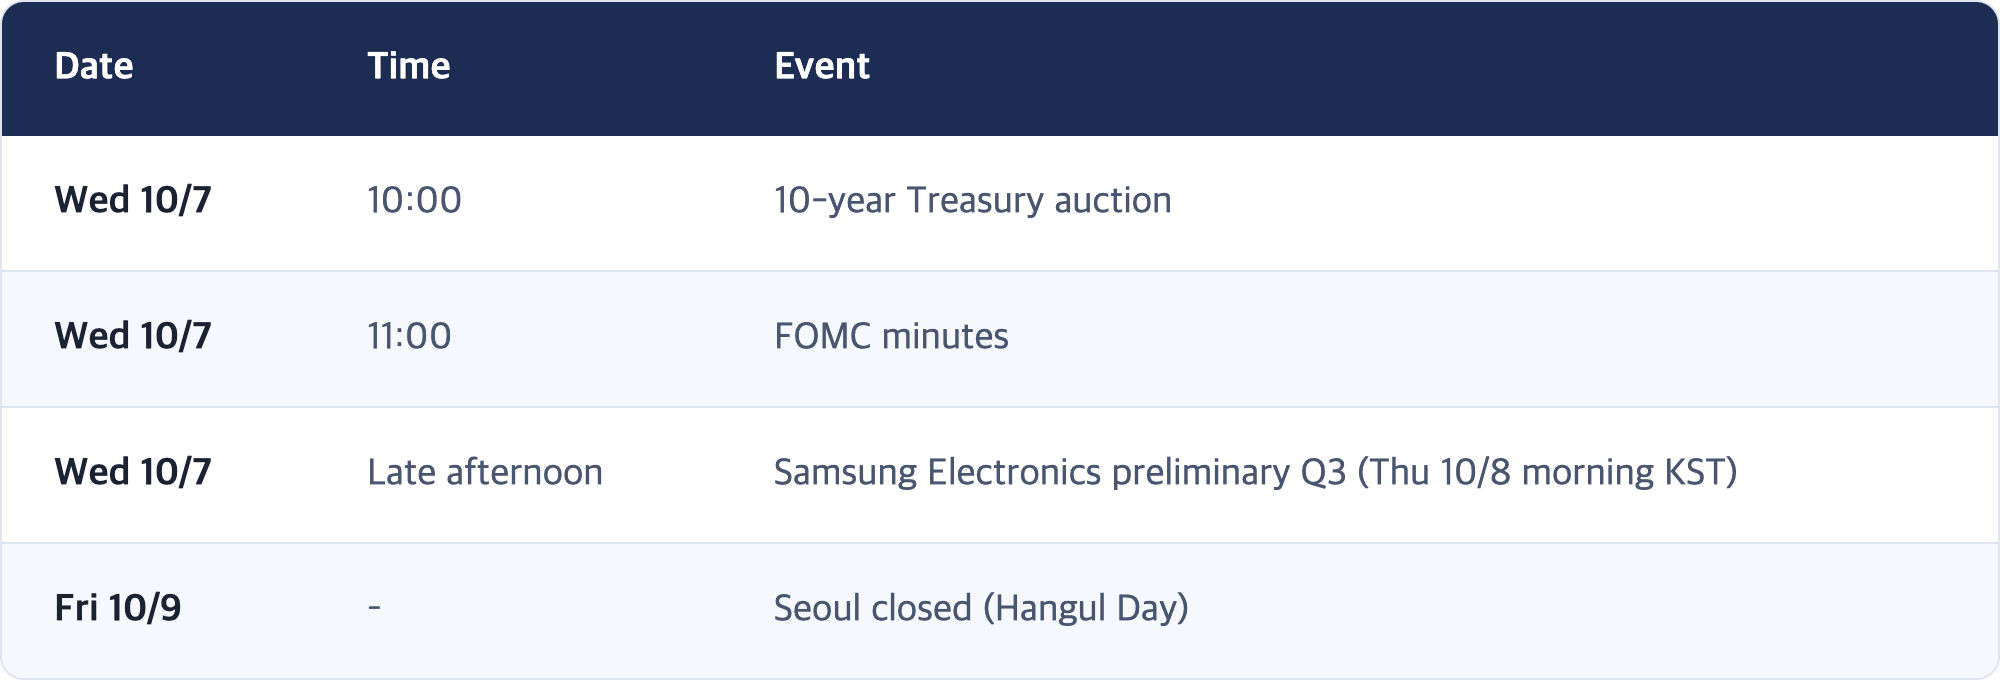
🟡 Two events land an hour apart today: the 10-year Treasury auction (10:00 PDT) and the minutes of the September FOMC meeting (11:00 PDT). Seoul gets Samsung Electronics' preliminary Q3 results tomorrow morning (10/8 KST) and is closed on 10/9 for Hangul Day.
SEO Intro
Korea's stock market fell for a second straight day while Wall Street sat at record highs. The KOSPI closed at 6,803.90 (−1.98%), below 6,900, as foreign investors stepped up their selling to ₩2.60 trillion (about $1.9 billion), more than the ₩1.75 trillion they sold the day before. Memory-chip maker SK Hynix fell 2.82%, again worse than the index.
Overnight, it was New York that moved toward Seoul. The 10-year Treasury yield climbed back to 5.34%, and the 30-year hit 5.72%, the highest since 2002. Brent crude is back above $101. US futures are down: Dow −0.79%, S&P 500 −0.44%, Nasdaq-100 −0.77%. In pre-market trading Micron is off 2.8%, and yesterday's rally leaders (AMD, Broadcom, Marvell) are down 1.3–2.1%. Today's question: with long-term yields rising again, does this afternoon's 10-year auction and the Fed minutes add fuel to the move or cool it down?
1. Checkpoint Scorecard
The four Seoul checkpoints set in the 10/6 PM brief
The question was: "With rate pressure easing, does foreign selling of Korean memory stocks stop, or does it continue regardless of earnings?"
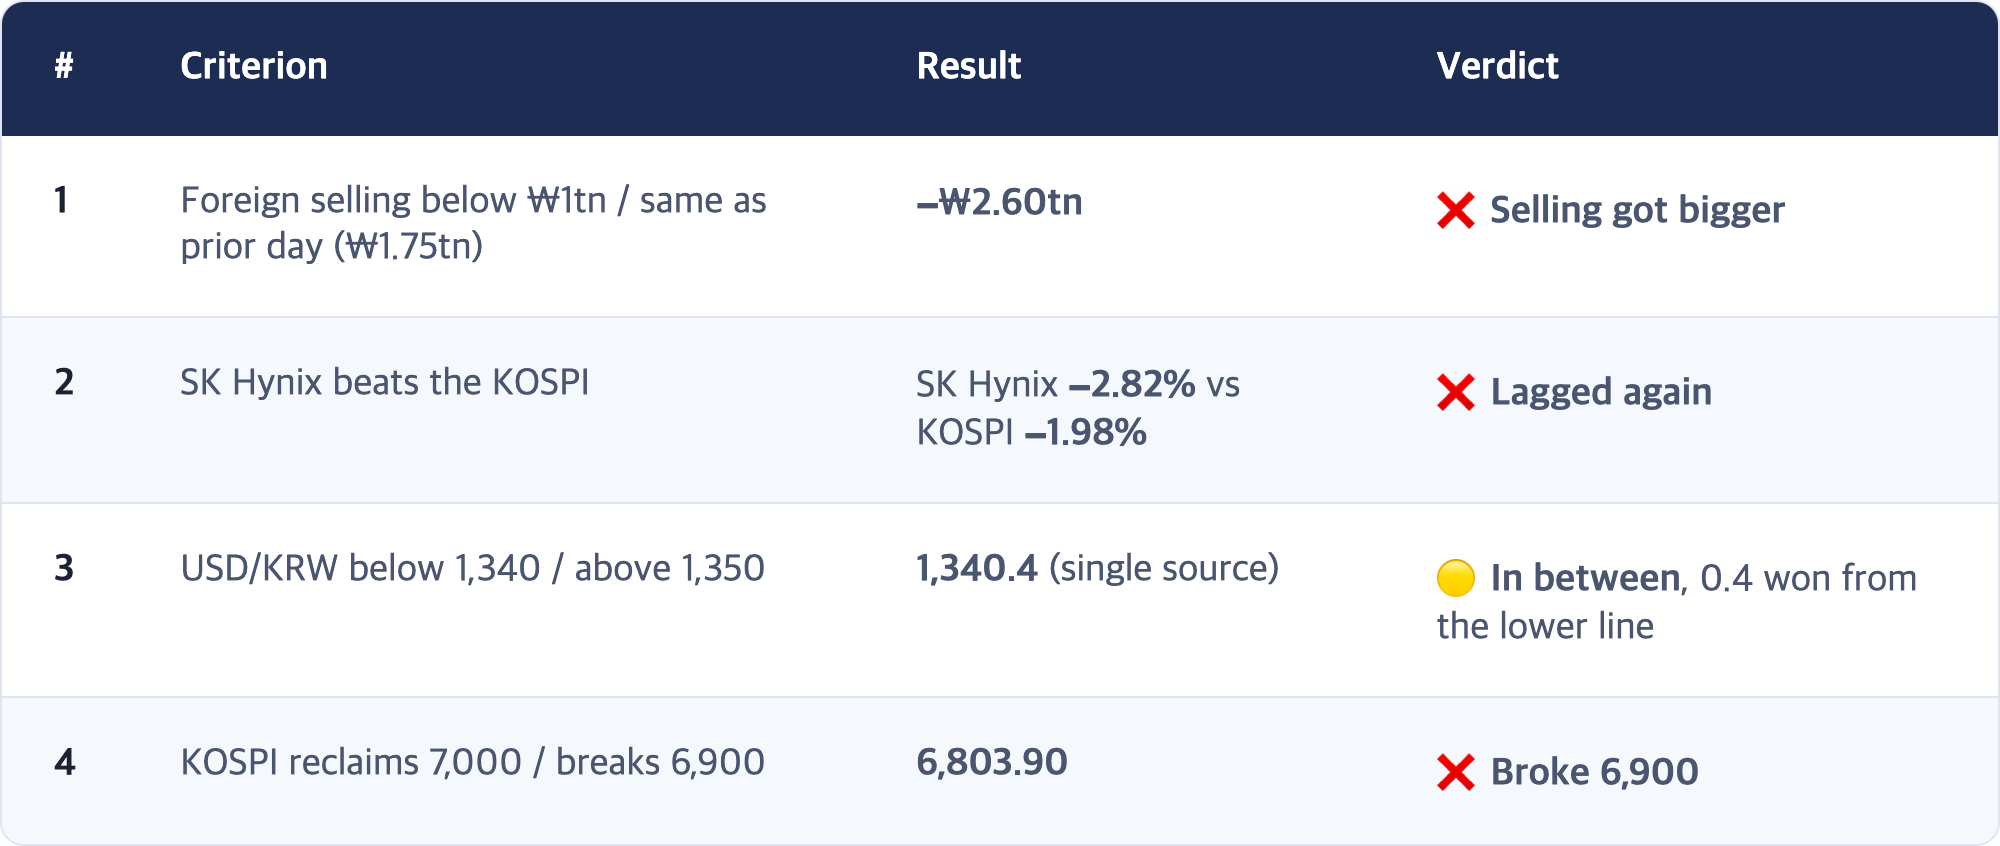
[Interpretation] It landed in the box we labelled "memory is being repriced"
The 10/6 PM brief said that if foreign selling continued and SK Hynix lagged again, it would mean memory stocks were being repriced regardless of the numbers. That is exactly what happened. Two-day foreign selling totals roughly ₩4.35 trillion, and it did not shrink on the eve of Samsung's results.
One number still doesn't fit: despite ₩2.6 trillion of foreign selling, the won strengthened slightly (1,343.6 → 1,340.4 per dollar). That figure comes from one outlet, so we hold judgement. If accurate, the sale proceeds may not have been converted straight back into dollars. We have not confirmed why.
2. Today's Key Story: New York futures are now selling what Seoul sold two days ago
[Fact] Asia close, 10/7
[Fact] Seoul flows, 10/7
★ [Interpretation] Same direction, different reason
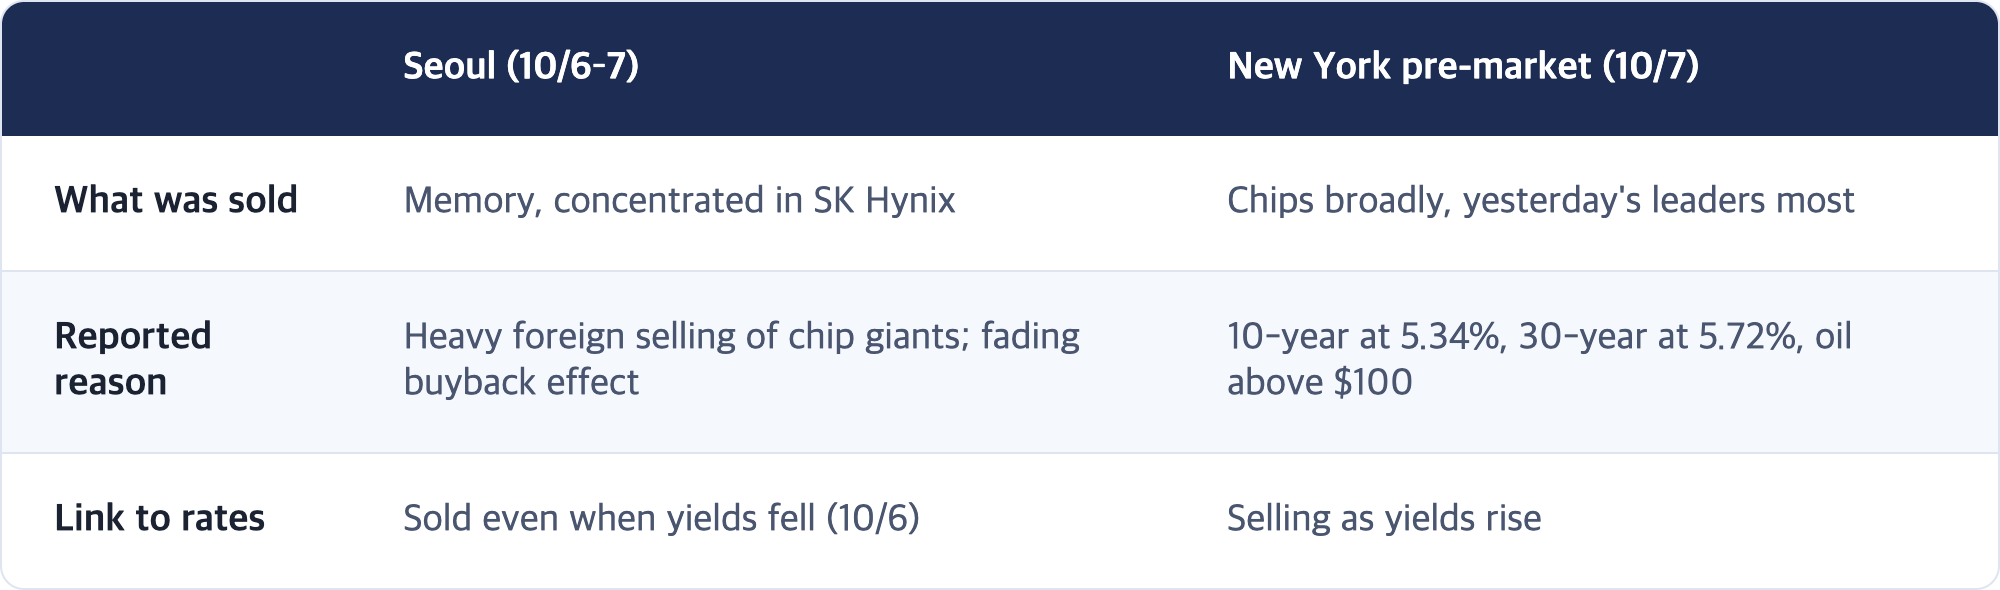
So reading this morning as "Seoul's memory worries spread to New York" goes too far. On the reporting so far, New York is watching rates, Seoul is watching memory. They may simply point the same way on the same day.
The tell is Micron versus the Nasdaq today. If it's about rates, chips should fall roughly together. If Micron underperforms the Nasdaq by more than 1 percentage point, the memory repricing Seoul started two days ago is likely spreading to New York.
3. US Variables: yesterday's drop in yields, fully reversed
[Fact] US pre-market (08:42 ET, Reuters)
[Fact] Today's US schedule (PDT)
★ [Interpretation] What a one-day reversal tells us
Yesterday the 10-year fell 4bp and the 3-year auction "stopped through," the first sign of real buyers at these yields. This morning all of that move is gone and the 30-year is at a new high. Yesterday looks more like a pause than a turn. Today brings two tests: the 10-year auction asks directly who will buy long-dated debt, and the minutes show how strongly officials argued for another hike when they raised rates 25bp in September. A weak auction plus hawkish minutes would push yields higher; the opposite could make this morning's jump a one-day affair.
4. Macro Backdrop: oil back over $100, and Europe adds fiscal worries
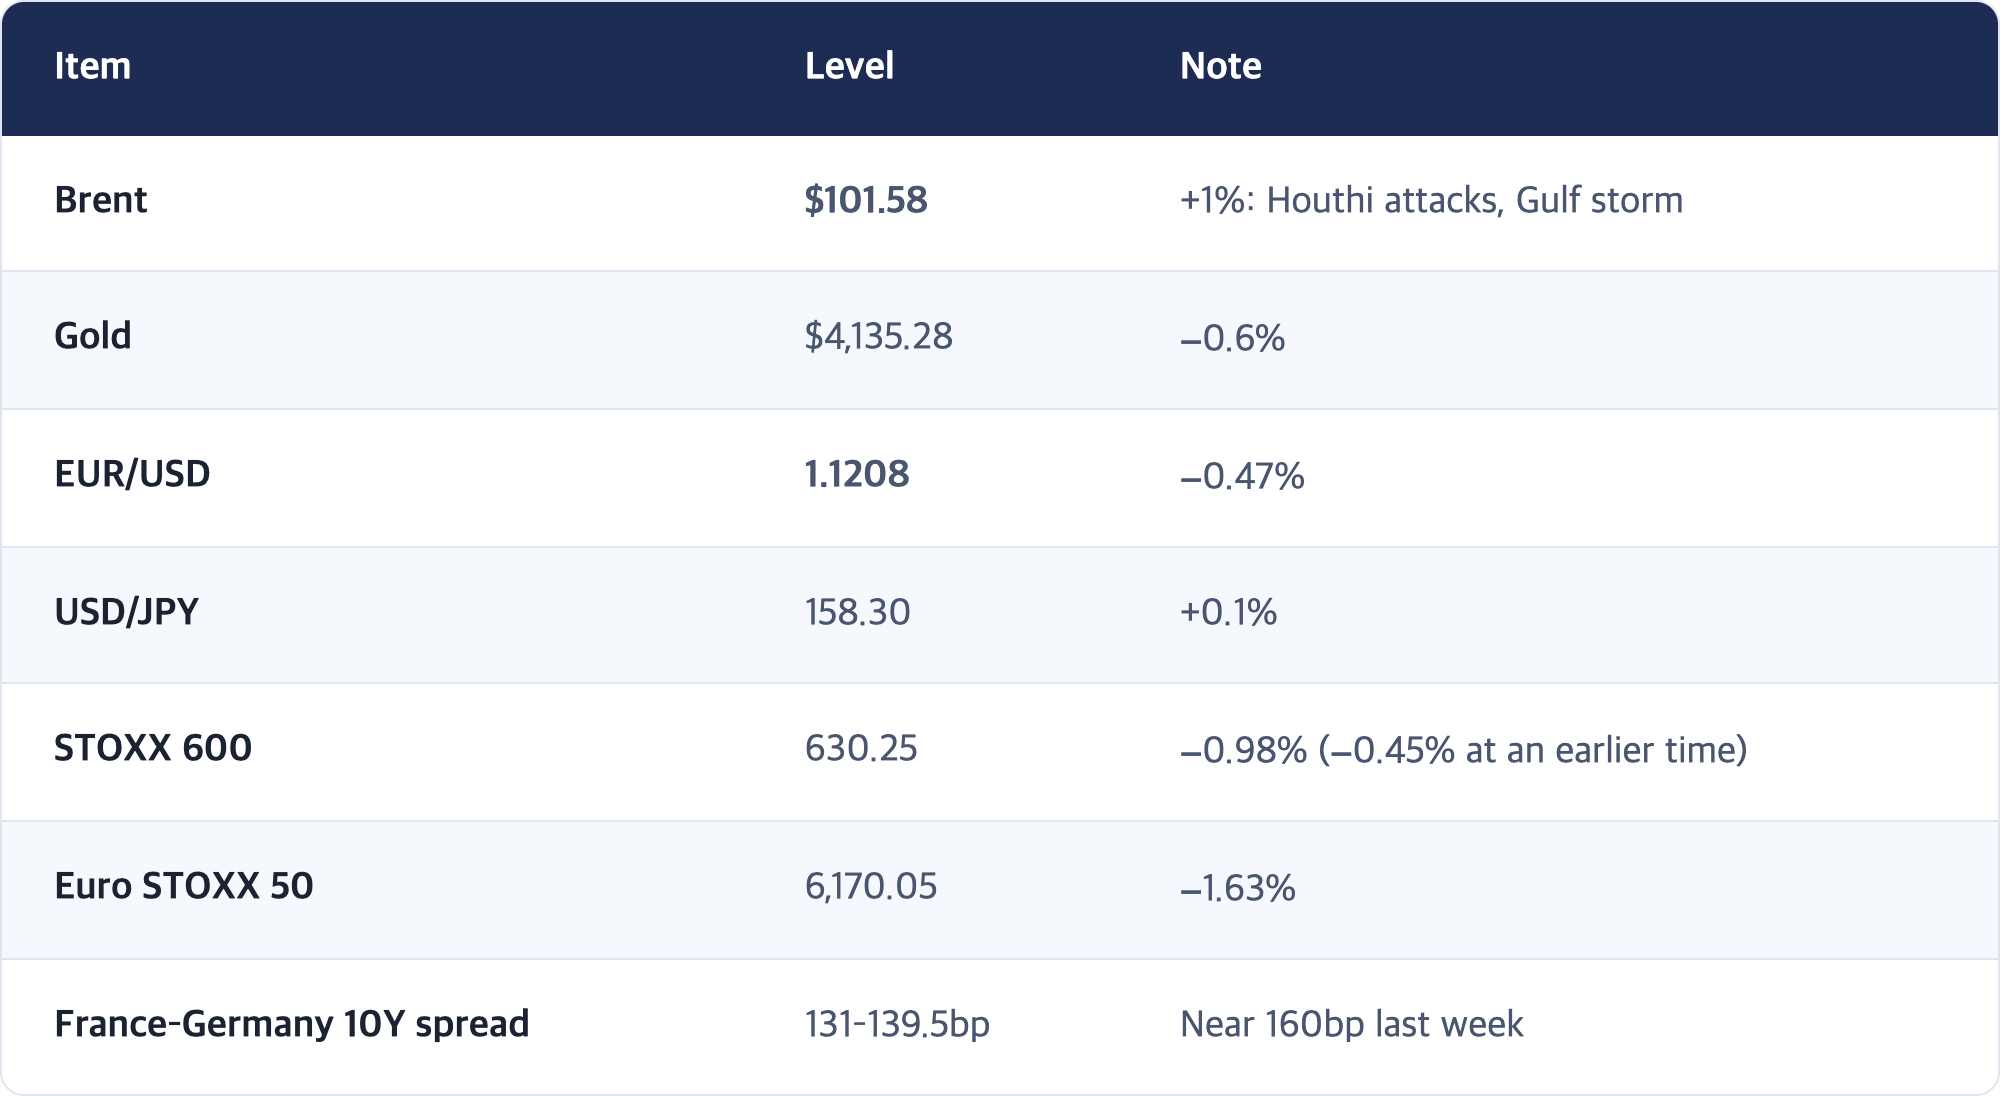
[Interpretation] Higher oil means more imported inflation for Europe, which raises expectations of further ECB tightening, which in turn presses on already-stretched French debt. For the US, it adds up to a morning where a stronger dollar, higher oil and higher long yields all point the same way.
5. US Session Preview (Wed 10/7, PDT)
The question
Is today's drop a rates story or a memory story? The answer frames how Seoul receives Samsung's numbers tomorrow.
✅ Four checkpoints (US close)
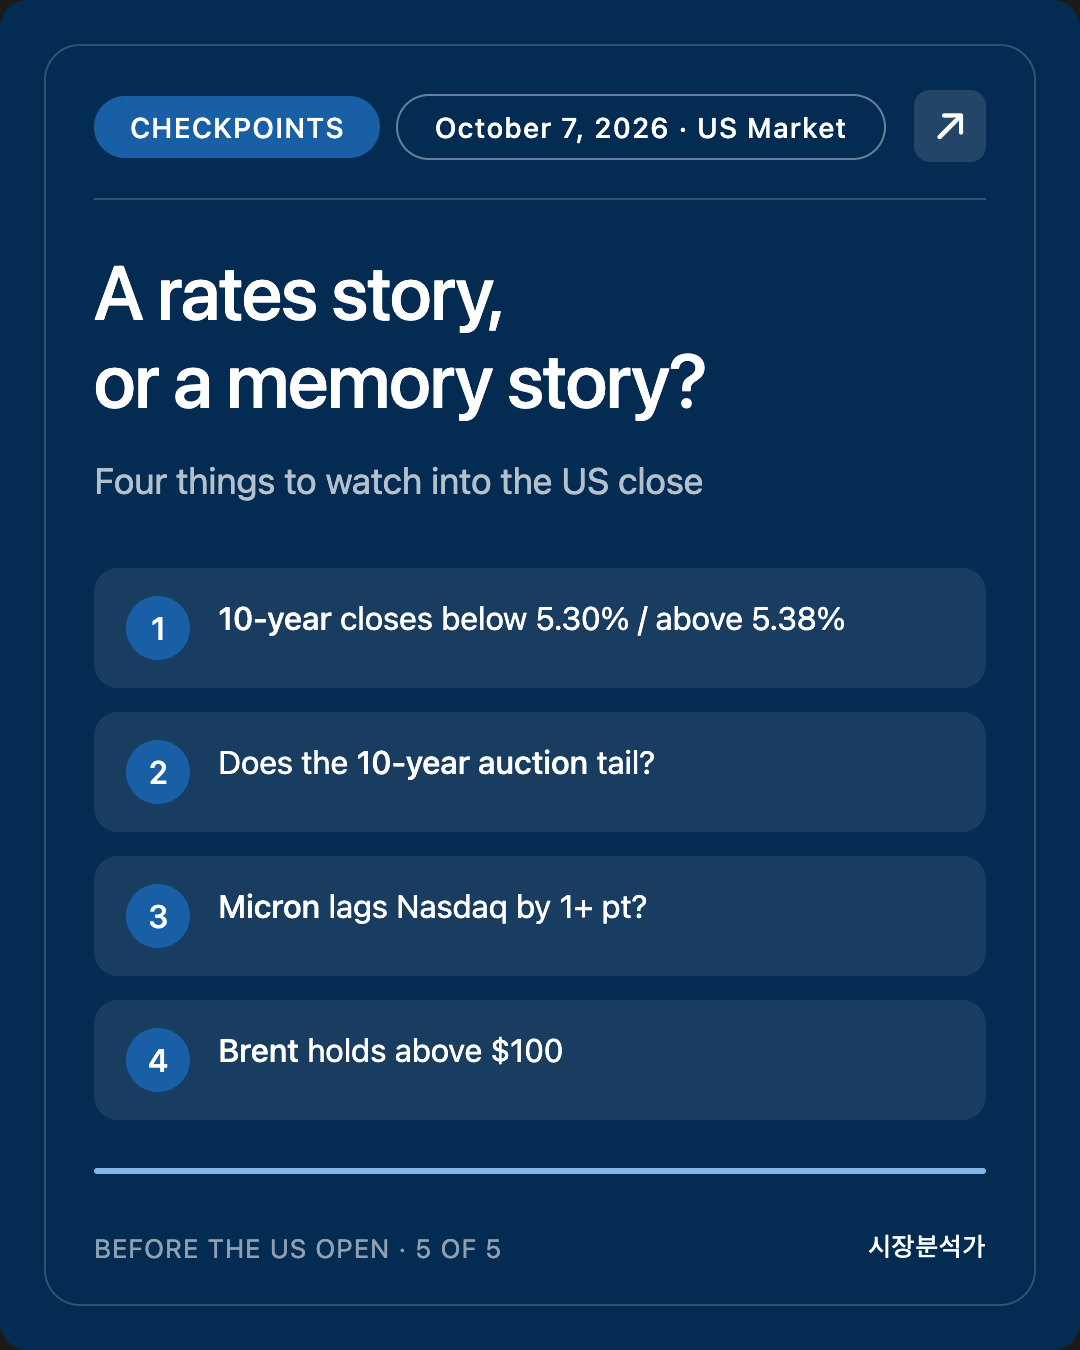
- 10-year closes below 5.30% / above 5.38%.
- Does the 10-year auction tail? A yield above the pre-auction market level signals thin demand for long debt. (Most important)
- Does Micron lag the Nasdaq by more than 1 point? Yes = memory story; roughly in line = rates story.
- Brent holds above $100 / slips back below.
[Interpretation] The most telling pair is #2 and #3. A clean auction with Micron lagging alone means New York is starting to see what Seoul saw. A tailing auction with chips falling evenly means it's still a rates story.
6. Study Note: What is a Treasury "reopening"?
Concept. The Treasury doesn't issue a brand-new 10-year note every month. It launches a new one in the first month of each quarter, then for the next two months sells more of that same note (same maturity, same coupon). Today's auction is one of those reopenings.
Analogy. It's like a second or third print run of a popular book: same content, more copies, and a bigger supply makes it easier to trade.
In practice. Yesterday's 3-year sold at 4.932%, 0.2bp below the market rate: buyers were eager. If today's 10-year tails instead, it says "three years is fine, ten years is a stretch," meaning investors are demanding a bigger premium to lend for longer (the term premium).
One line. A reopening asks whether buyers will still show up for more of the same bond, and today it's being asked with the 30-year at a 24-year high.
7. Corrections & Open Items
- Corrections: none.
- Source differences: US futures (FXStreet early read Dow −0.14% vs Reuters 08:42 ET Dow −0.79%; later Reuters figure used). STOXX 600 −0.45% to −0.98% by time of day. Dollar index +0.33% vs +0.63%.
- Unconfirmed: USD/KRW close (single source), foreign net selling of SK Hynix, Samsung Q3 consensus, Taiwan close, 10-year auction size.
8. Event Calendar (PDT)
Sources
- Seoul Shinmun: KOSPI falls for second day (10/7)
- Nikkei: Nikkei average closes 648 yen lower (10/7)
- Trading Economics: Hong Kong Stock Market
- Reuters via Investing.com: Wall St futures slip as yields and oil rebound
- MarketScreener: European shares, euro fall as energy shock, fiscal worries bite
- FXStreet: Dow Jones futures fall as US Treasury yields rebound
- TFTC: 10-year note auctions
📌 More market briefs
※ This post is market observation and organization intended to support your own judgment. It is not a recommendation to buy or sell any security. Figures are as of the time of writing and may differ between sources.
If this was useful, bookmark it or pass it along. It genuinely helps me write the next one.
I can survive. We can survive.