October 13, 2026 KOSPI Market Brief — What to Watch Before the Korean Open
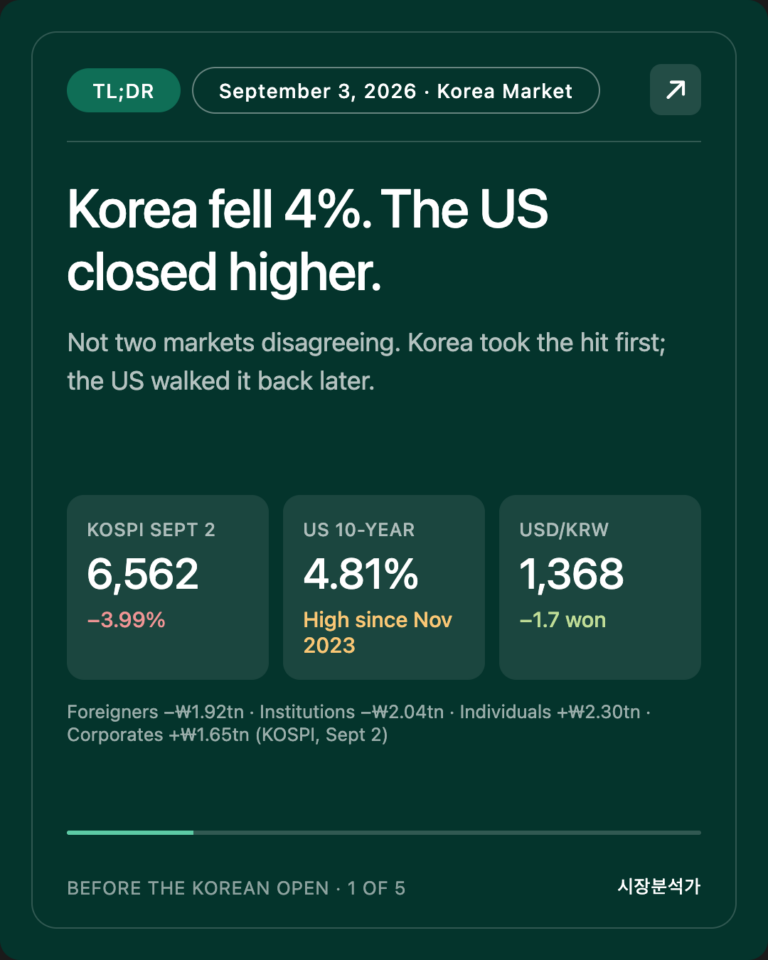
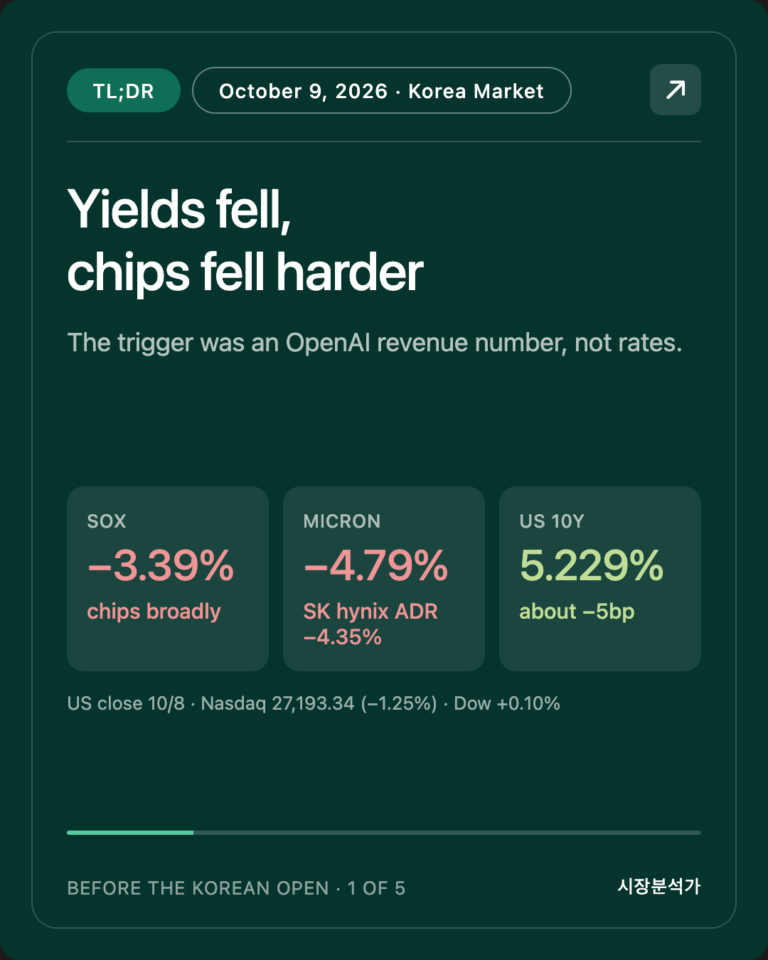
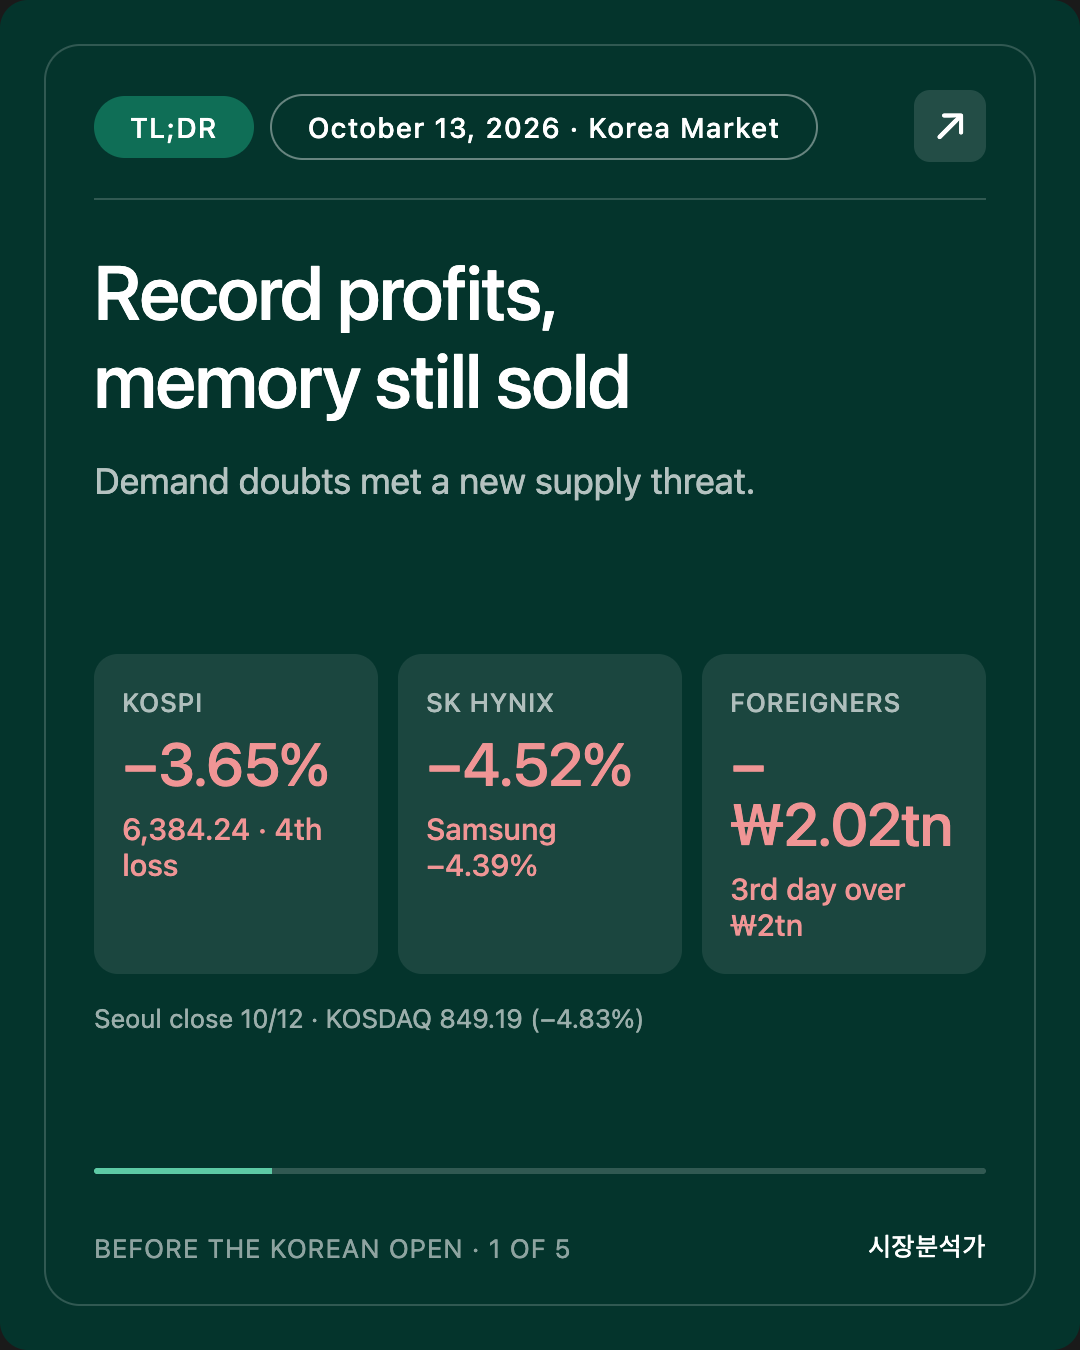
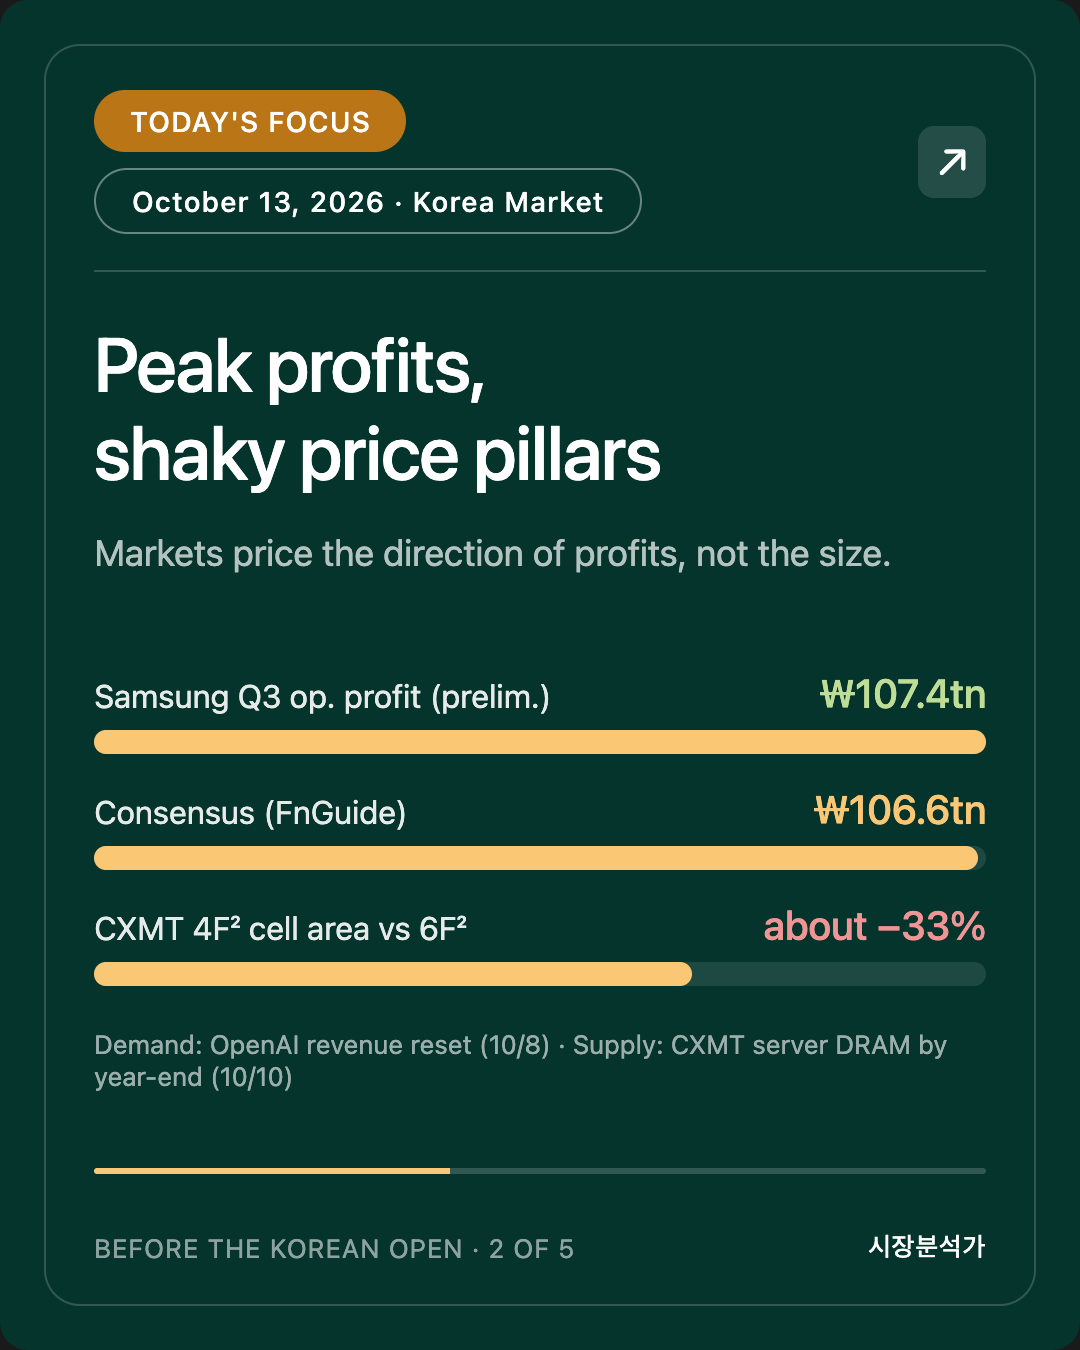
- ★ Memory fell on top of record earnings. Samsung's Q3 preliminary operating profit was ₩107.4tn (consensus ₩106.6tn), yet on 10/12 Samsung fell 4.39% and SK hynix 4.52%. KOSPI 6,384.24 (−3.65%), a fourth straight loss.
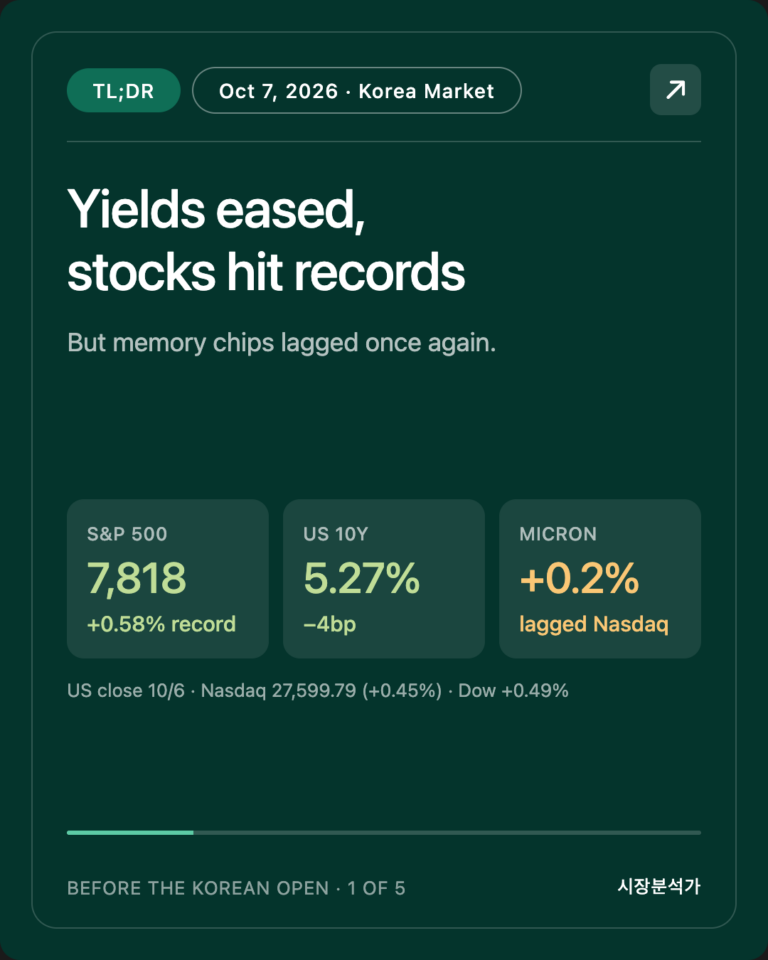
- ★ Two hands are now on memory. Demand: OpenAI's revenue reset (10/8). Supply: CXMT's 4F² DRAM (10/10). New York agreed on 10/12: SOX −2.67%, Micron −3.87%, SanDisk −6.98%.
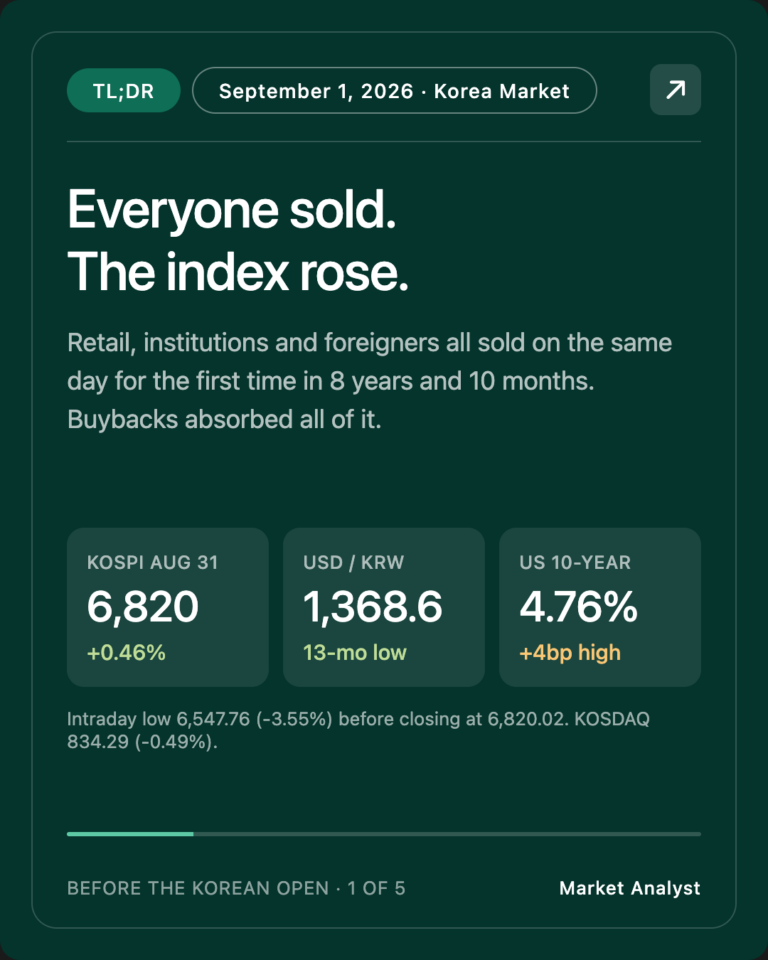
- Foreigners sold over ₩2tn for a third day. 10/7 −₩2.60tn, 10/8 −₩2.43tn, 10/12 −₩2.02tn. Yet the won actually strengthened, to ₩1,335.0 per dollar (−7.0).
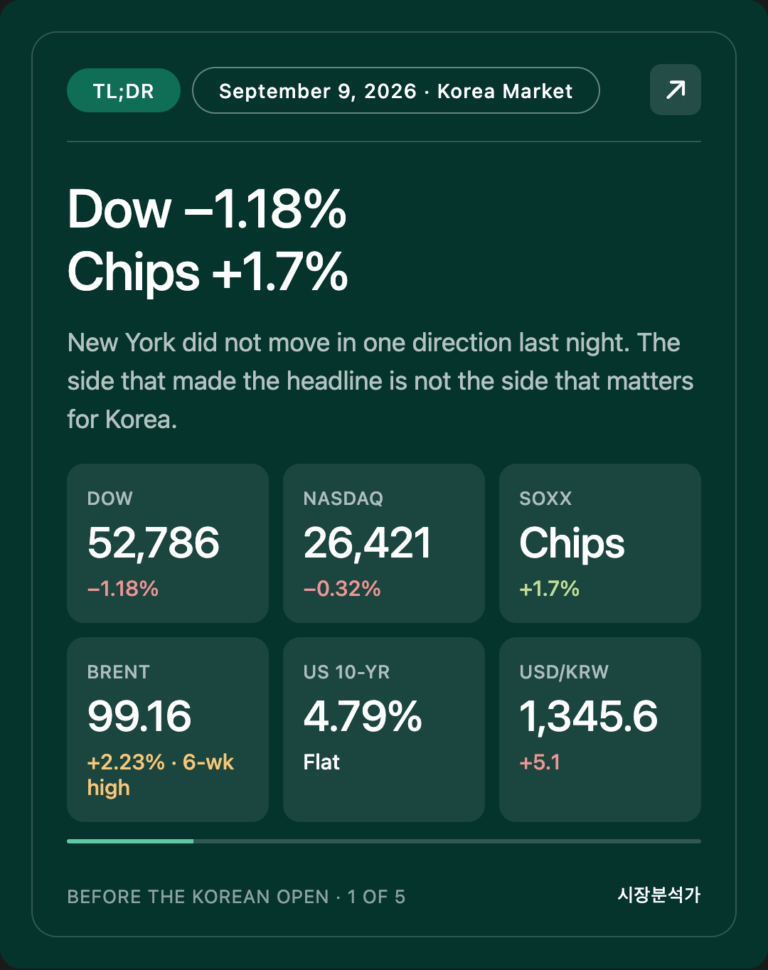
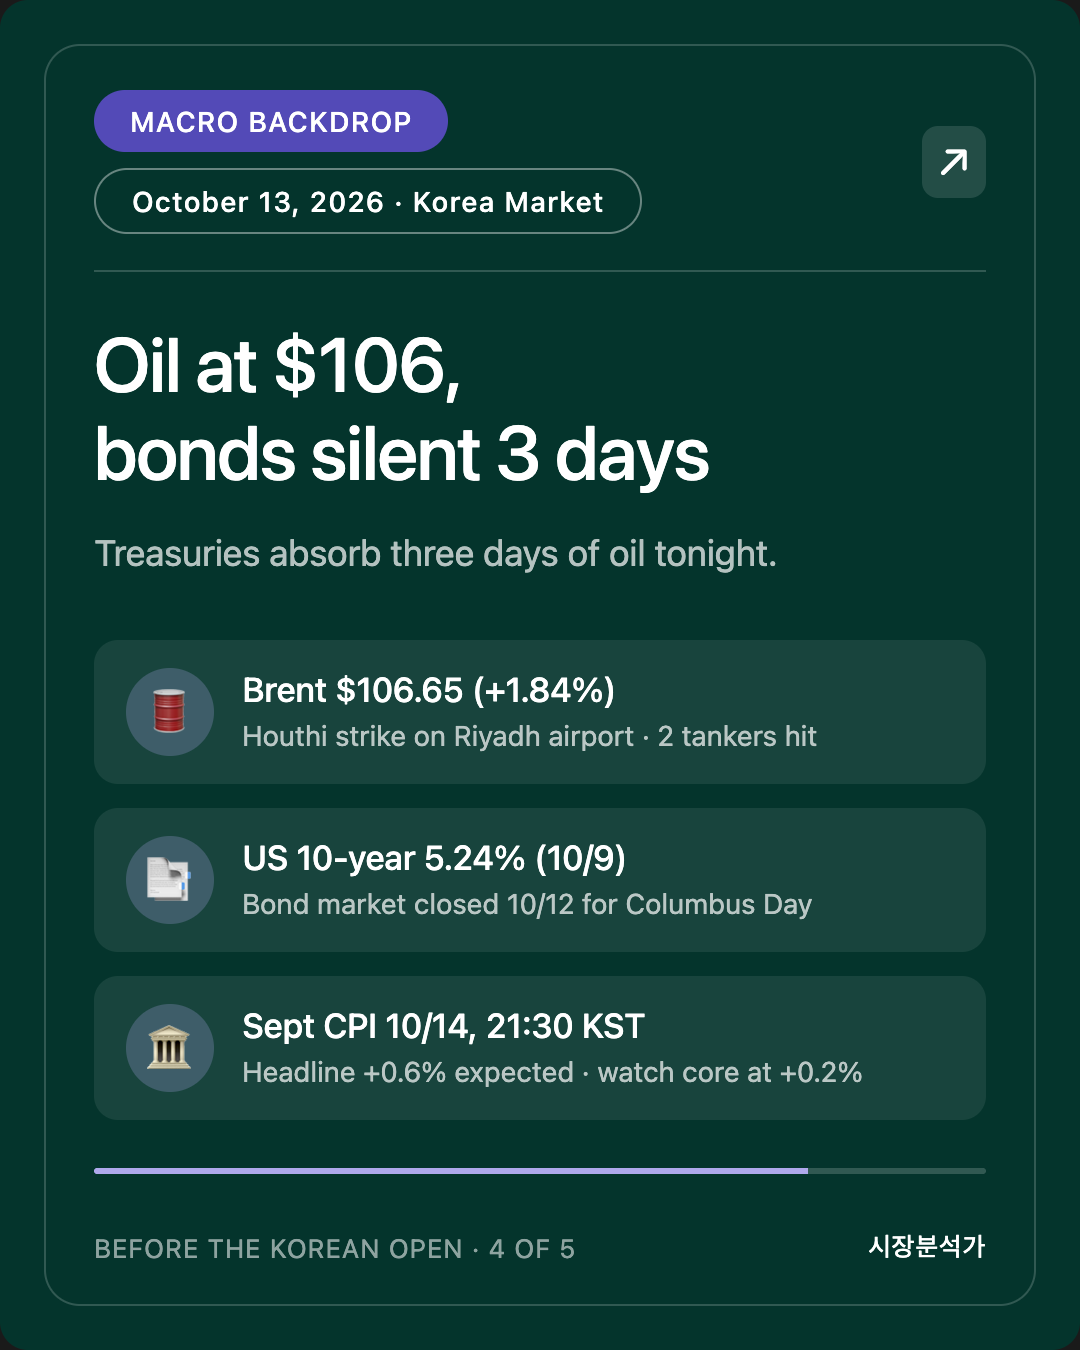
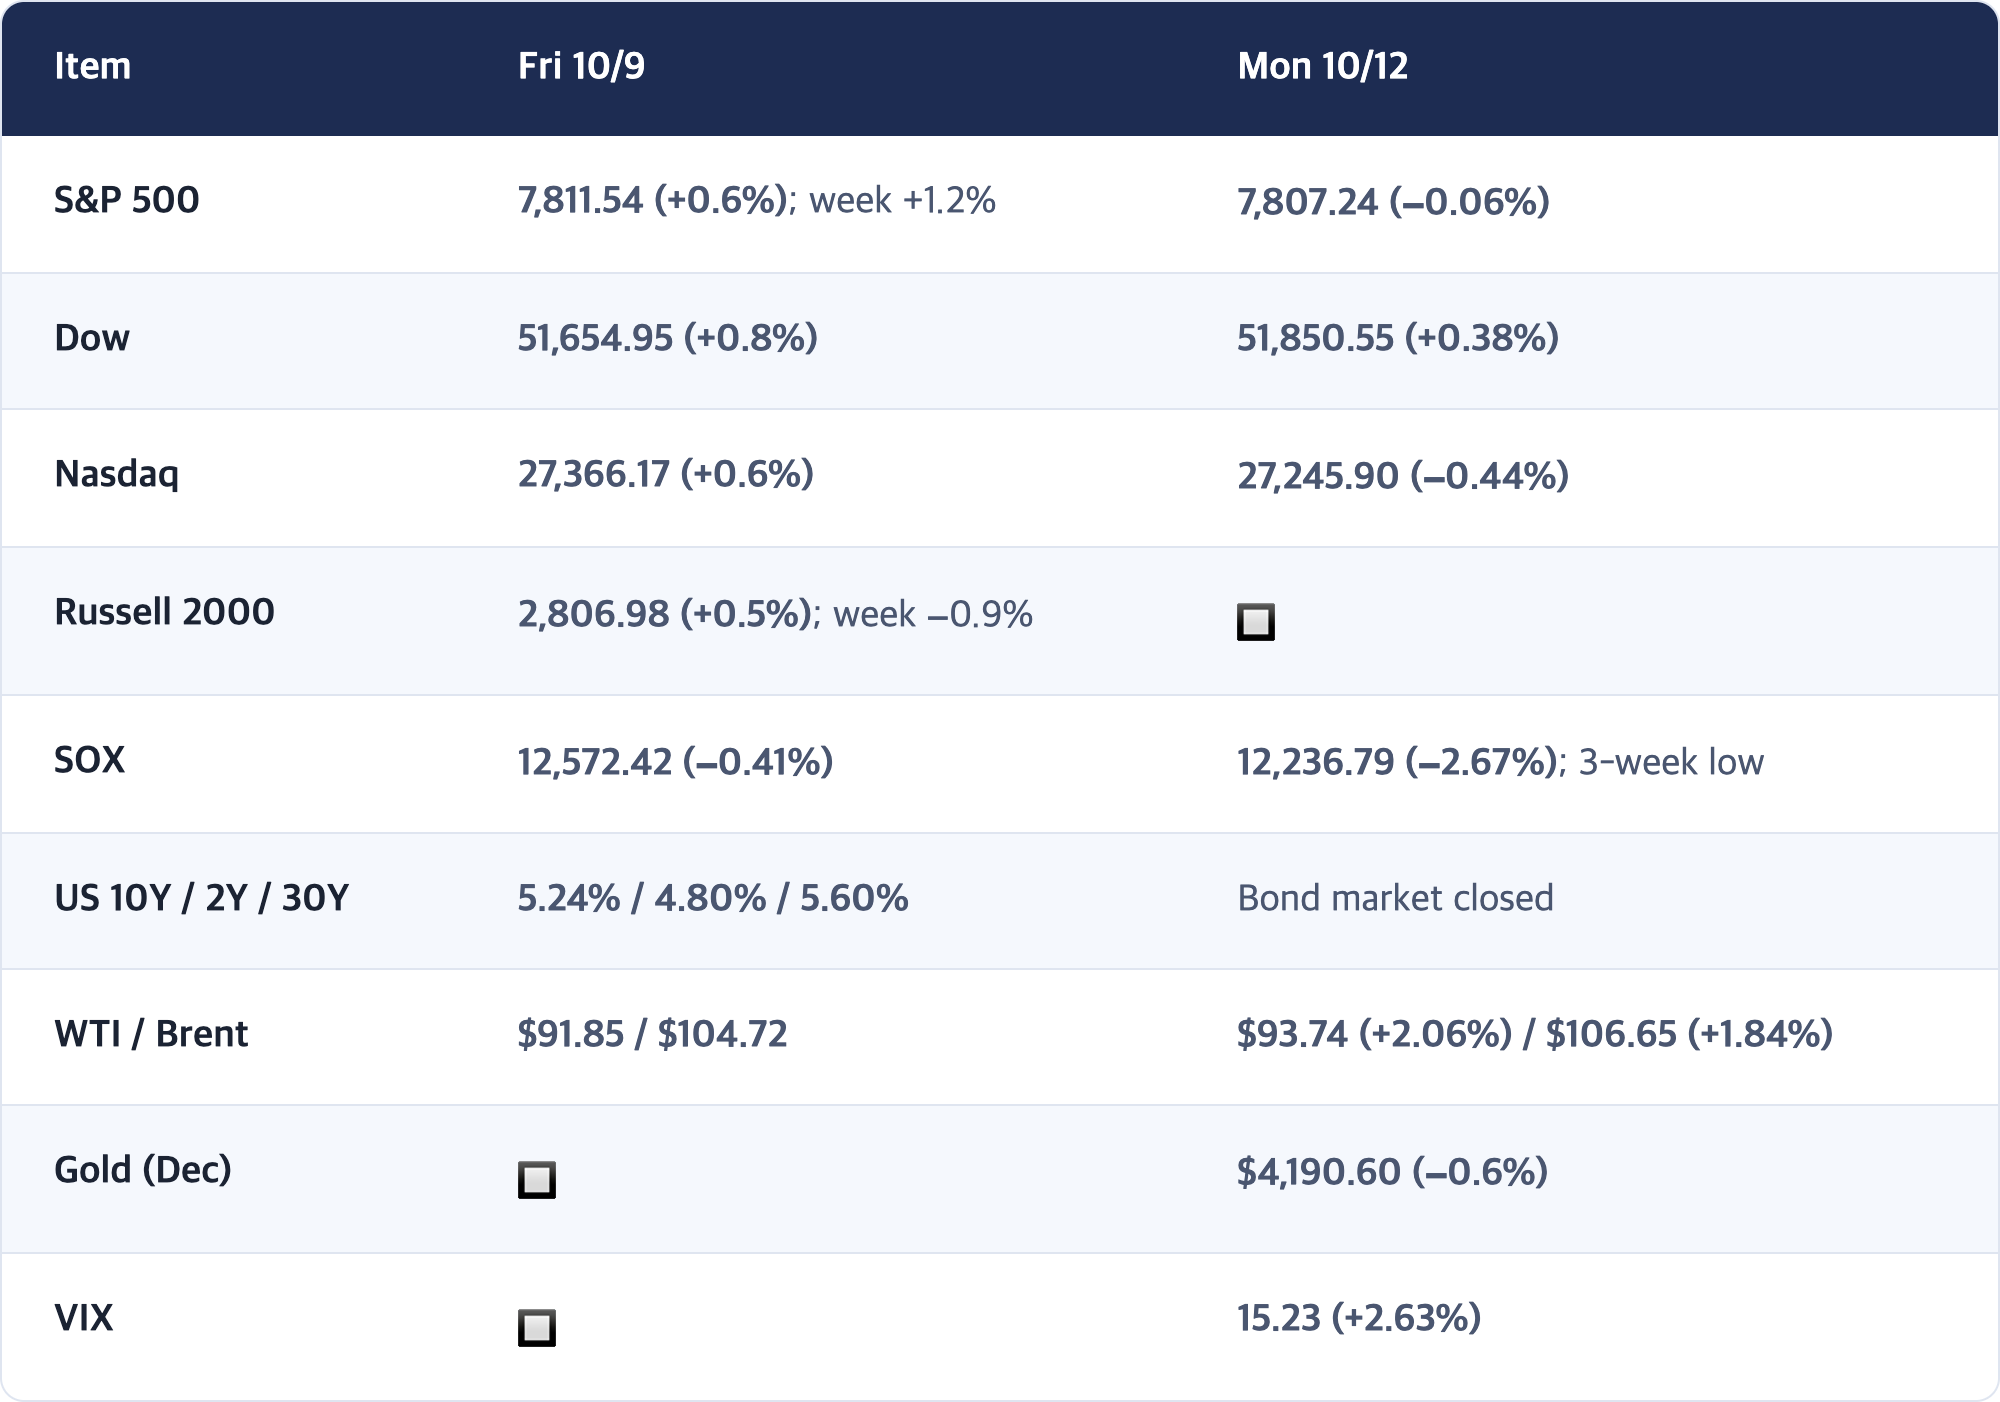
- Oil is climbing again. Brent $106.65 (+1.84%), the highest since 9/15, after Yemen's Houthi rebels struck Riyadh's airport (10/10) and two tankers were hit. Friday's Brent close was $104.72.
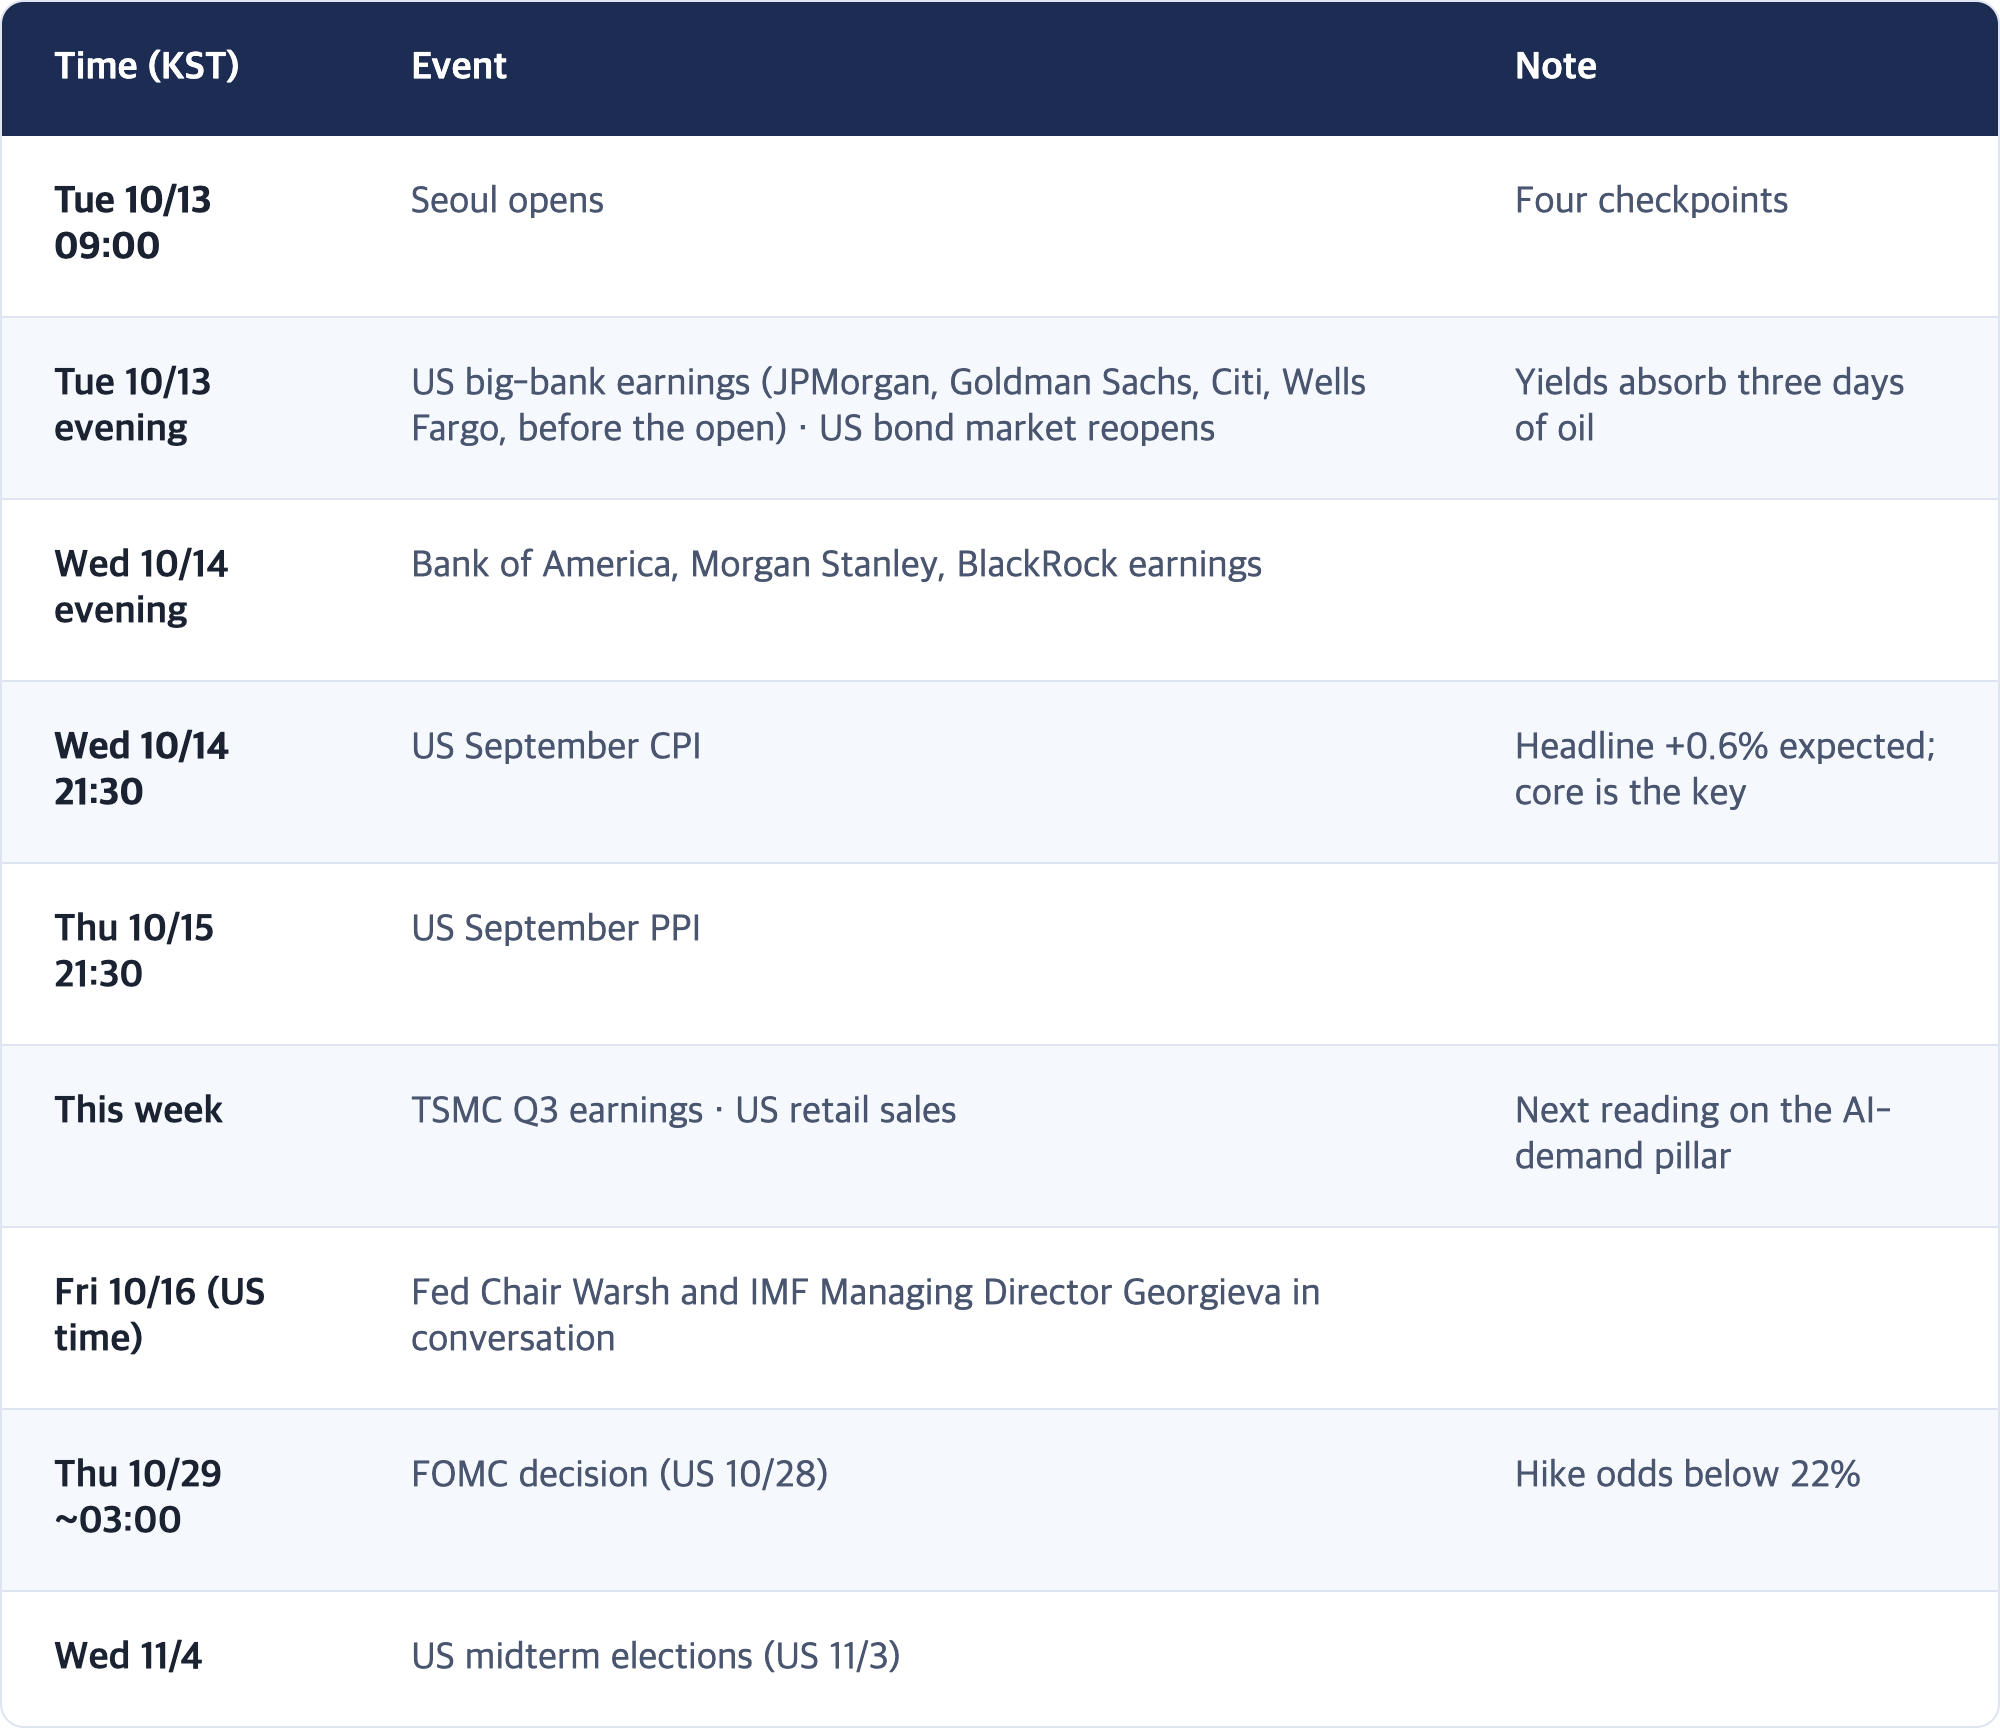
- Two US numbers this week: big-bank earnings tonight (JPMorgan, Goldman Sachs, Citi, Wells Fargo), and September CPI on Wed 10/14 at 21:30 KST (headline +0.6% m/m expected). Odds of an October Fed hike are below 22% (17.7% on Friday).
This is Mr. Can. Here is the October 13, 2026 brief ahead of the Korean market open.
Written: 2026-10-13 08:08 KST (Vancouver 10/12 16:08 PDT)
Basis: US regular-session close for Mon 10/12 (05:00 KST 10/13) + US close for Fri 10/9 + crude futures settlement 10/12 + Seoul close for Mon 10/12
🟢 Scheduled 16:00 PDT, started 16:01 PDT. On time.
🔴 Two missed issues. The Sunday 10/11 PM brief (Seoul 10/12 preview) and the Monday 10/12 AM brief (US 10/12 preview) were not published (both URLs return 404; cause not yet identified). This issue therefore covers three sessions at once: US Fri 10/9 · Seoul Mon 10/12 · US Mon 10/12.
🟡 The US bond market was closed Monday 10/12 for Columbus Day. The latest Treasury yields are Friday's.
SEO Intro
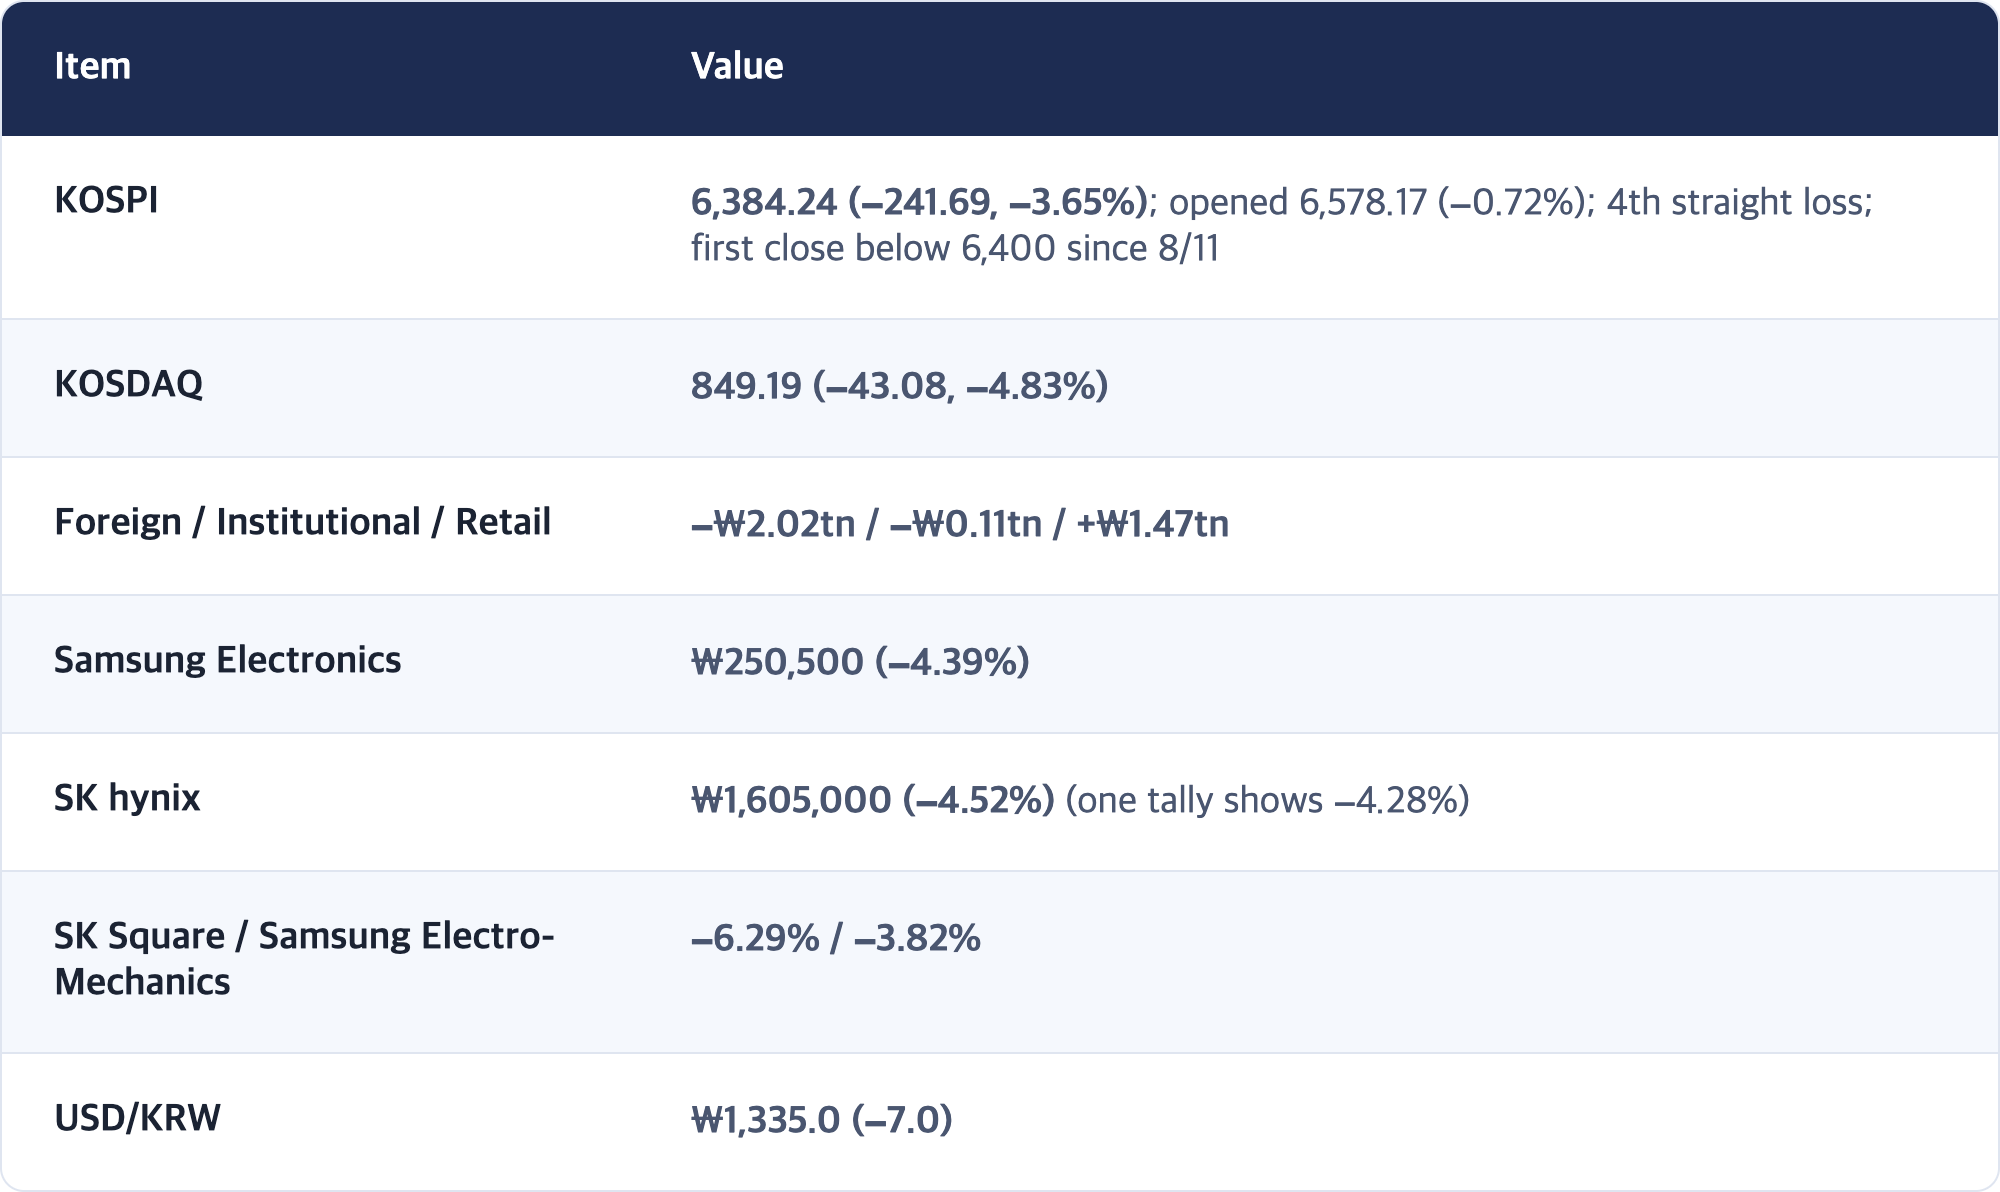
Samsung Electronics reported a record ₩107.4 trillion (about $80 billion) in quarterly operating profit, and its stock still fell 4.39%. When Seoul reopened on Monday 10/12 after a long holiday weekend, the KOSPI closed at 6,384.24 (−3.65%), below 6,400 for the first time in two months, and the tech-heavy KOSDAQ fell 4.83% to 849.19. Foreign investors sold a net ₩2.02 trillion, their third straight day above ₩2 trillion.
Two forces pressed on memory chips. On the demand side, last week's report that OpenAI's revenue run-rate was smaller than investors assumed. On the supply side, a weekend (10/10) announcement from China's CXMT that it will unveil 4F² server DRAM by year-end, a cell design about 33% smaller than today's industry standard.
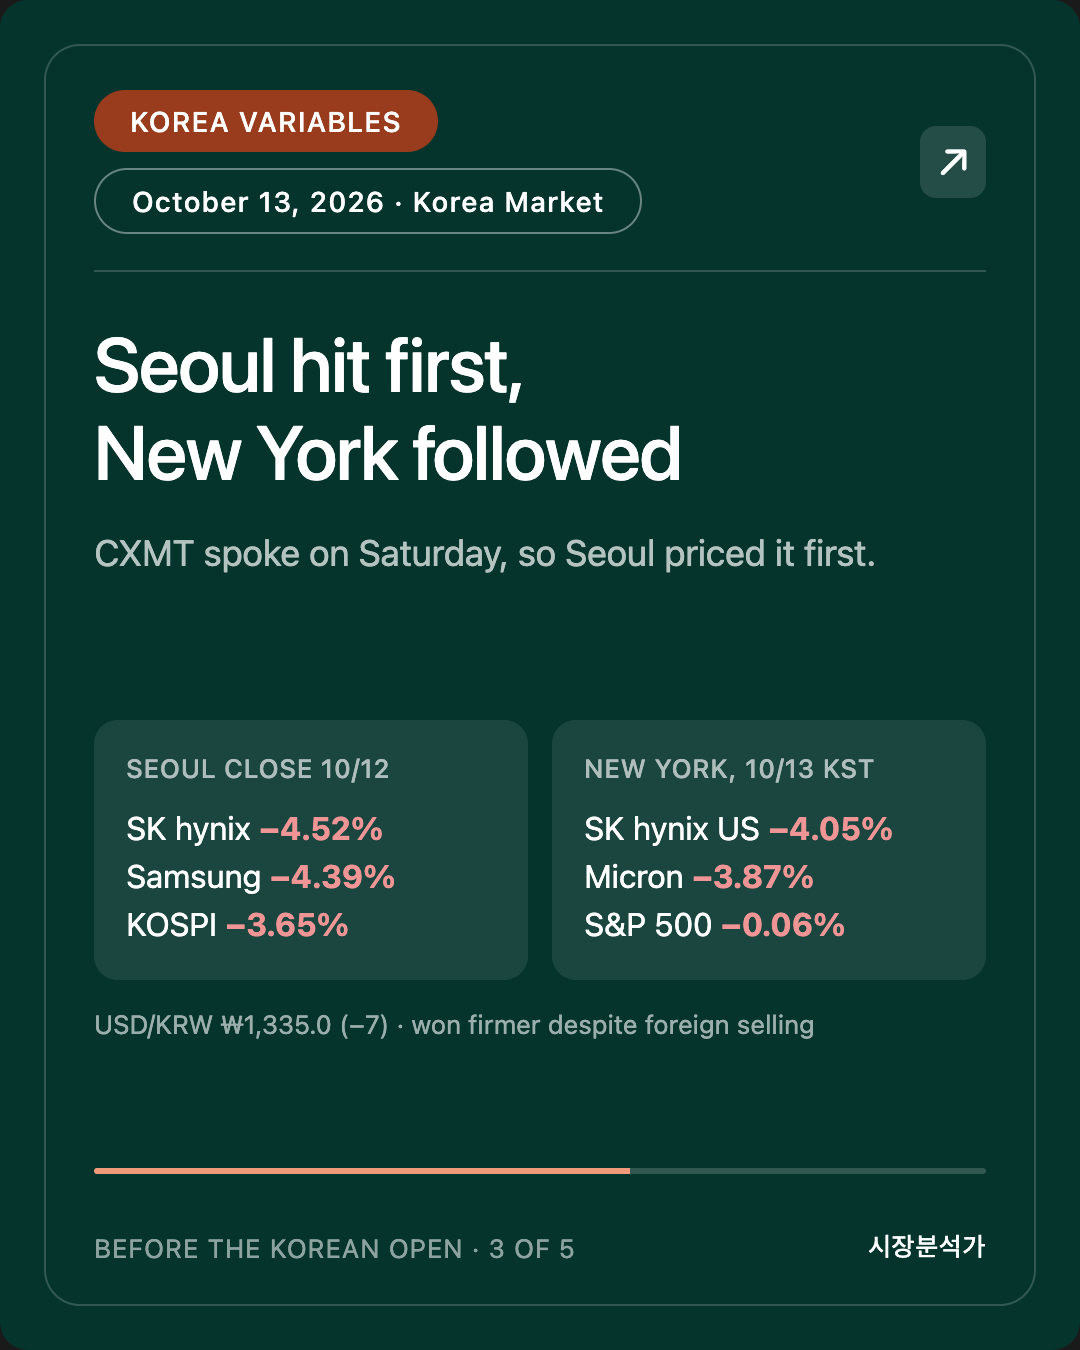
Seoul took the hit first; New York followed nine hours later. On 10/12 the Philadelphia Semiconductor Index (SOX) fell to 12,236.79 (−2.67%), Micron to $989.21 (−3.87%), and SK hynix's US-listed shares −4.05%. Today's question for Seoul: having already priced the news, does it take the same hit a second time now that New York has confirmed it?
1. Checkpoint Scorecard
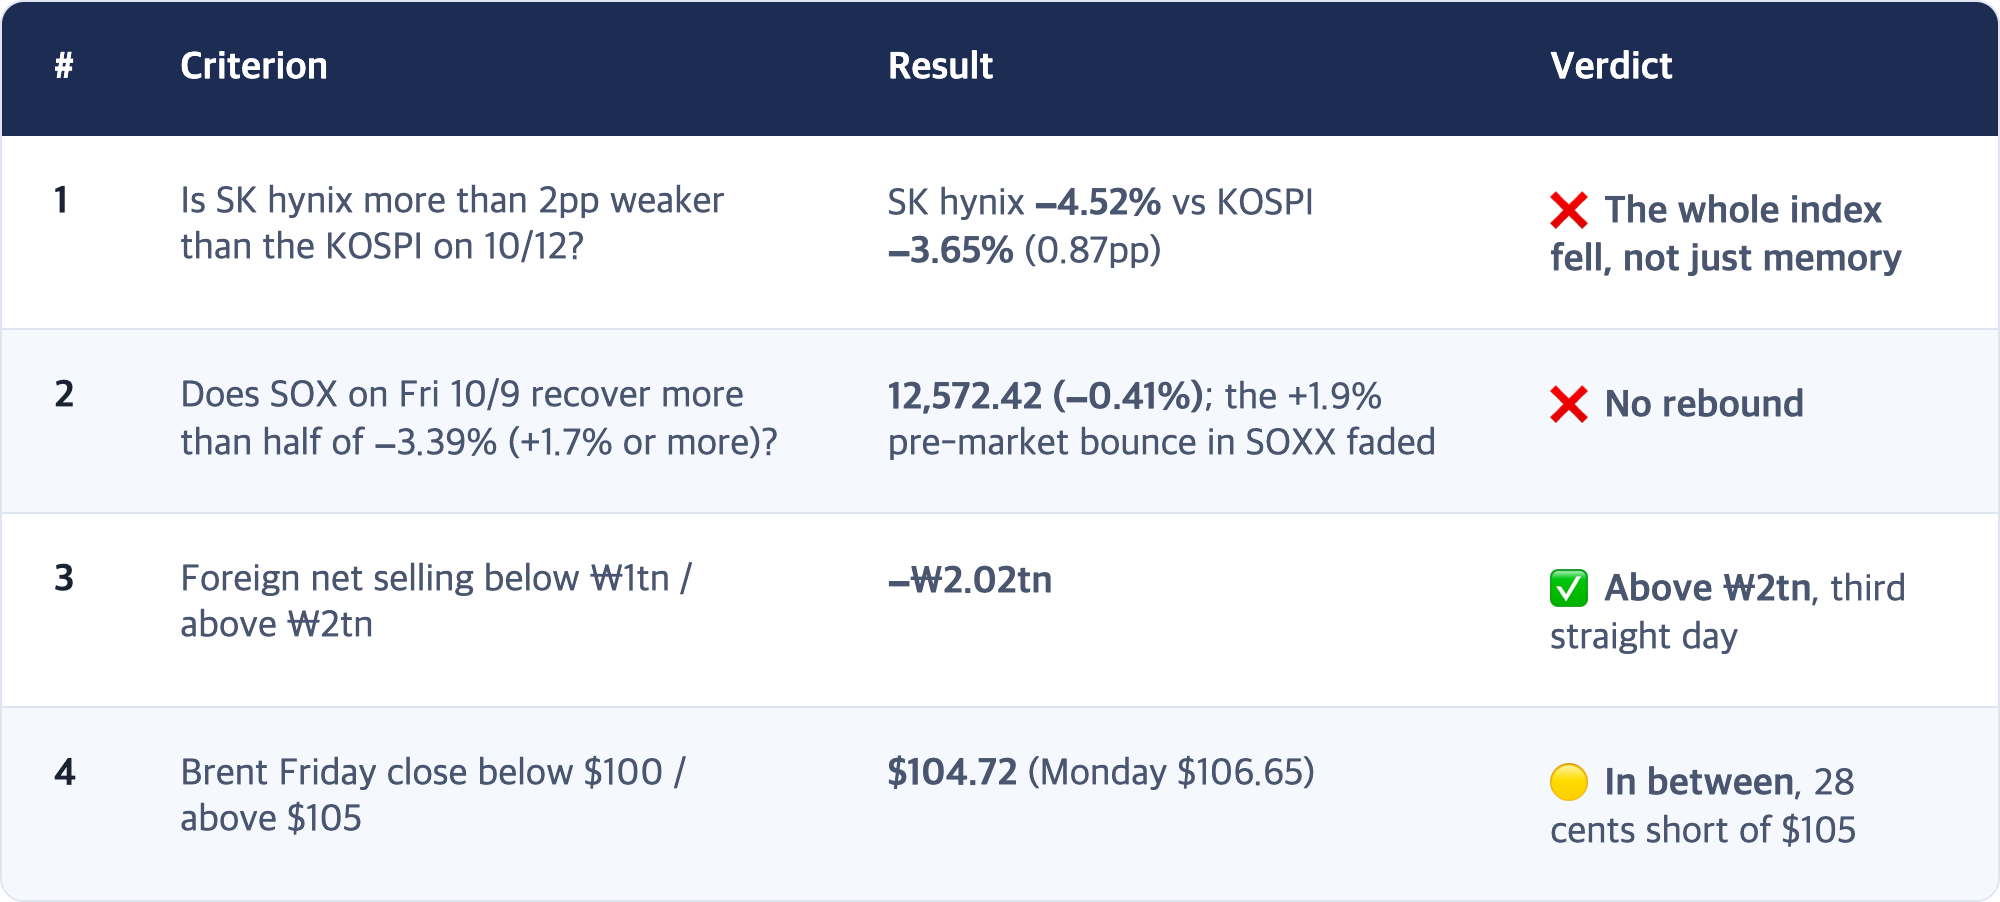
The four from the 10/8 PM brief (judged at Seoul's 10/12 close)
The axis was: "Does the AI-demand worry cross over into Seoul's memory stocks?"
The four from the 10/9 AM brief (US close 10/9)
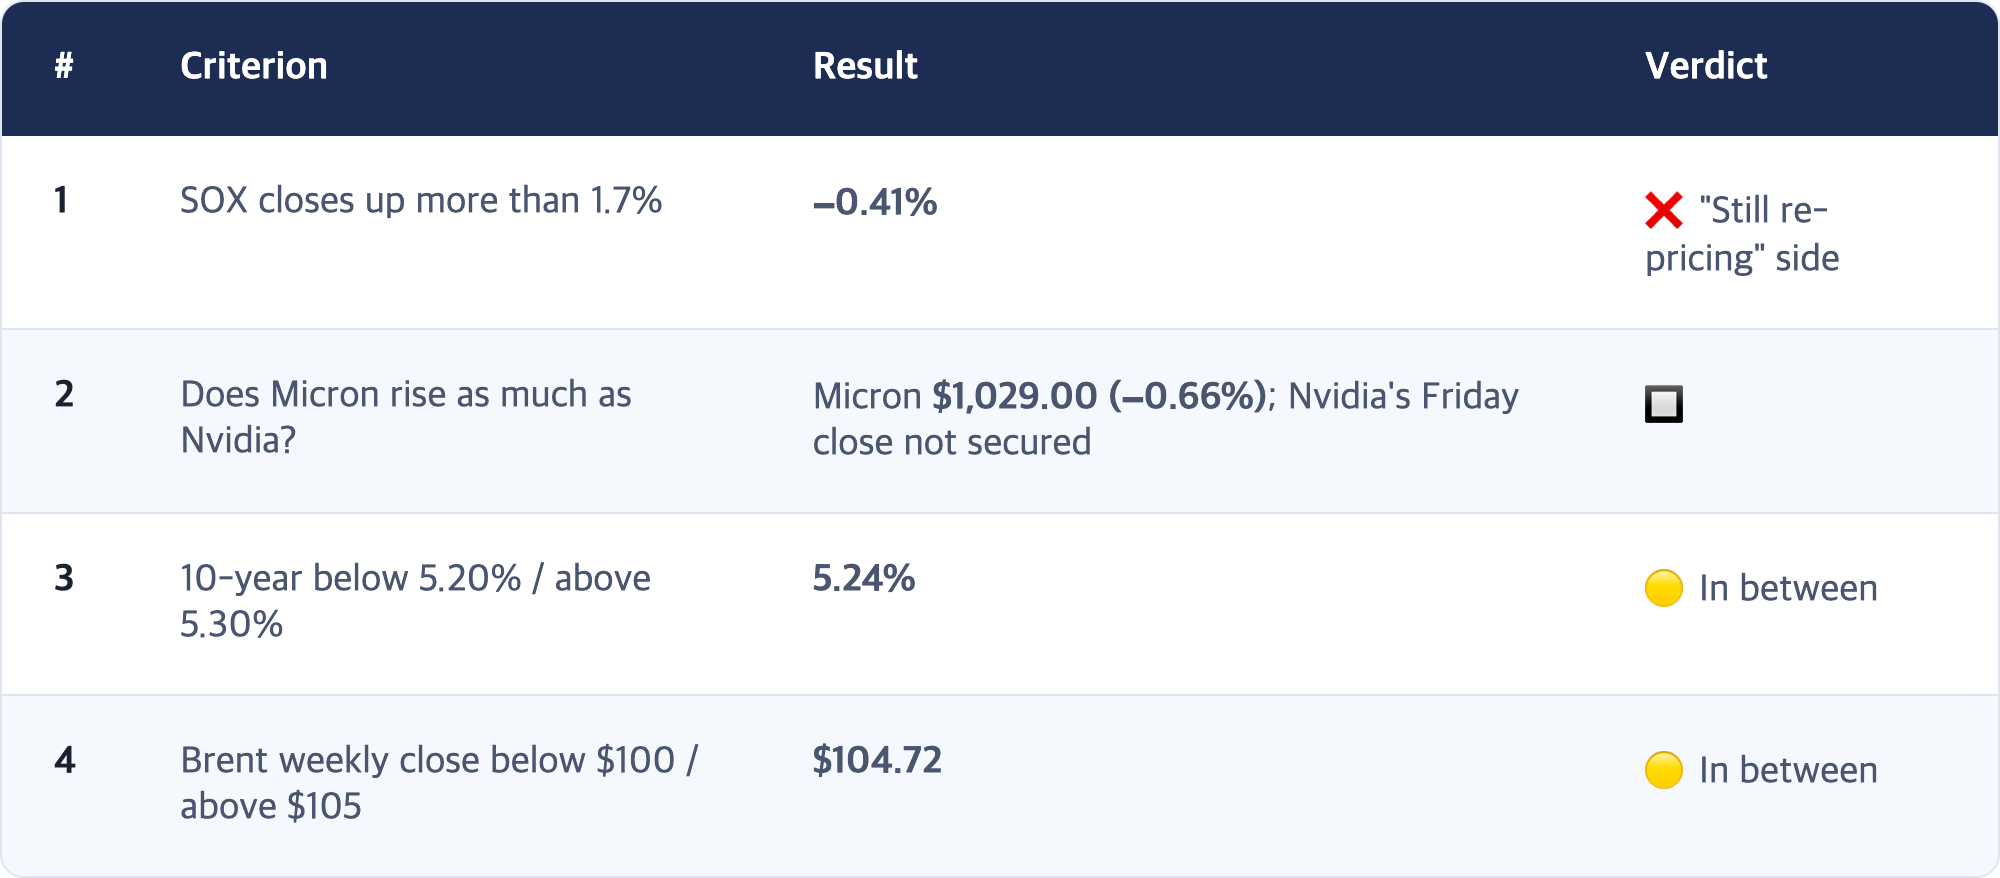
★ [Interpretation] #2 pointed to "still re-pricing," and Monday added new weight on top
Friday's chip rally failed to hold its pre-market gains and closed lower. OpenAI had said it expects an annualized run-rate above $70 billion by year-end, and the market still didn't buy back in. In the 10/9 AM brief's terms, this was not an overreaction to an apples-to-oranges comparison; investors were re-measuring AI capex expectations.
Then CXMT spoke over the weekend. Checkpoint #1 missed for an interesting reason: SK hynix didn't hold up better; everything else fell with it. KOSDAQ −4.83%, SK Square −6.29%, Samsung Electro-Mechanics −3.82%. In a market where chips drive half the index, a 2pp gap is too narrow to separate "memory" from "the index."
2. Today's Focus: ₩107 Trillion in Profit, and Still Sold
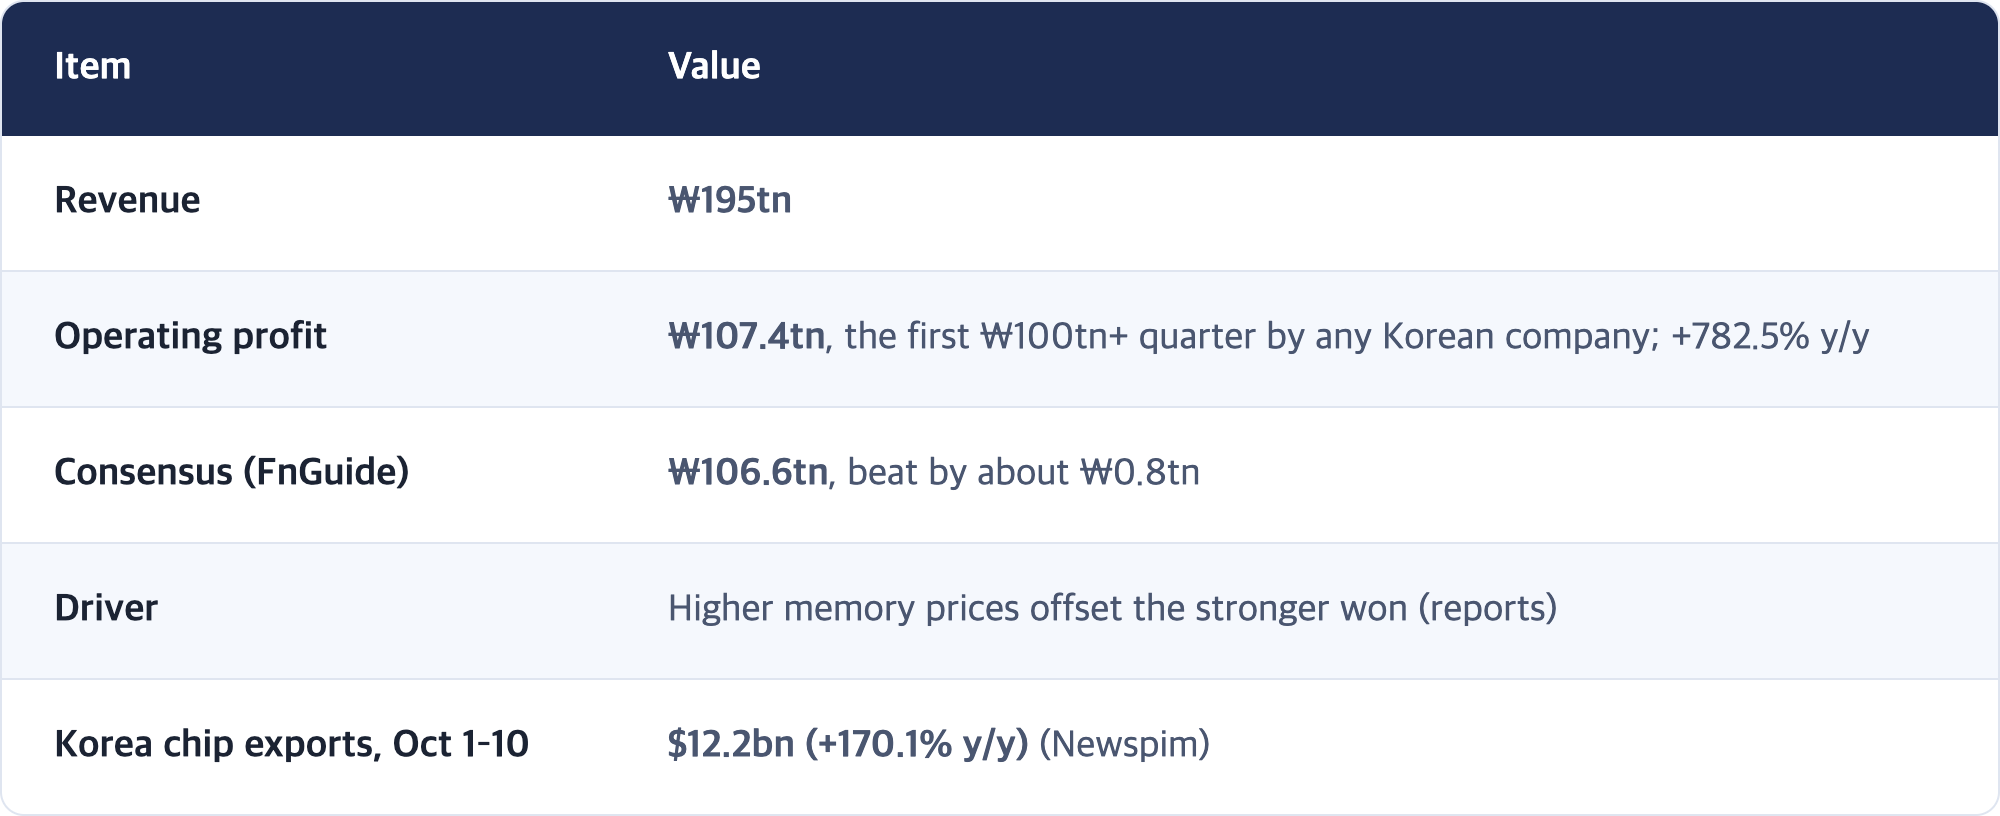
[Fact] Samsung Electronics Q3 preliminary results (filed 10/8)
[Fact] Seoul close, Mon 10/12
[Fact] The CXMT announcement (Shanghai, 10/10)
- China's ChangXin Memory Technologies (CXMT) said it will unveil DDR5 server memory modules (RDIMM) built on a 4F² cell architecture by year-end.
- 4F² cells take up about 33% less area than the industry-standard 6F² design, so more memory fits on each wafer.
- Industry observers note that unveiling is not mass production, and some analysts say CXMT still trails the leaders by two to three generations (reports).
★ [Interpretation] The market sold "how long these prices last," not "how much is being earned now"
₩107 trillion was already expected; with consensus at ₩106.6 trillion, the surprise was only ₩0.8 trillion. What the market actually received was doubt about the two pillars holding up those earnings:
- Demand pillar: Will AI companies earn enough to keep pouring money into data centers? (OpenAI report 10/8 → SOX failed to rebound 10/9)
- Supply pillar: Memory prices are high partly because only three companies can make leading-edge DRAM. Is a fourth entering the server market? (CXMT 10/10)
A memory maker's profit is price × volume, and today's record profit is mostly about price. When stories that threaten price show up on both the demand and supply side in the same week, the question "is this near the peak?" beats any earnings beat (see the study note).
[Observation] How much weight CXMT deserves is still unknown. There's no word on mass-production timing, yields, or customer adoption. We can't yet split Monday's drop between CXMT and a third straight day of foreign selling. One analyst quoted by Newspim said the biggest concern is "foreign flows, not chip earnings."
3. Korea Variables: Seoul Was Hit First; New York Followed
[Observation] Same news, different clocks
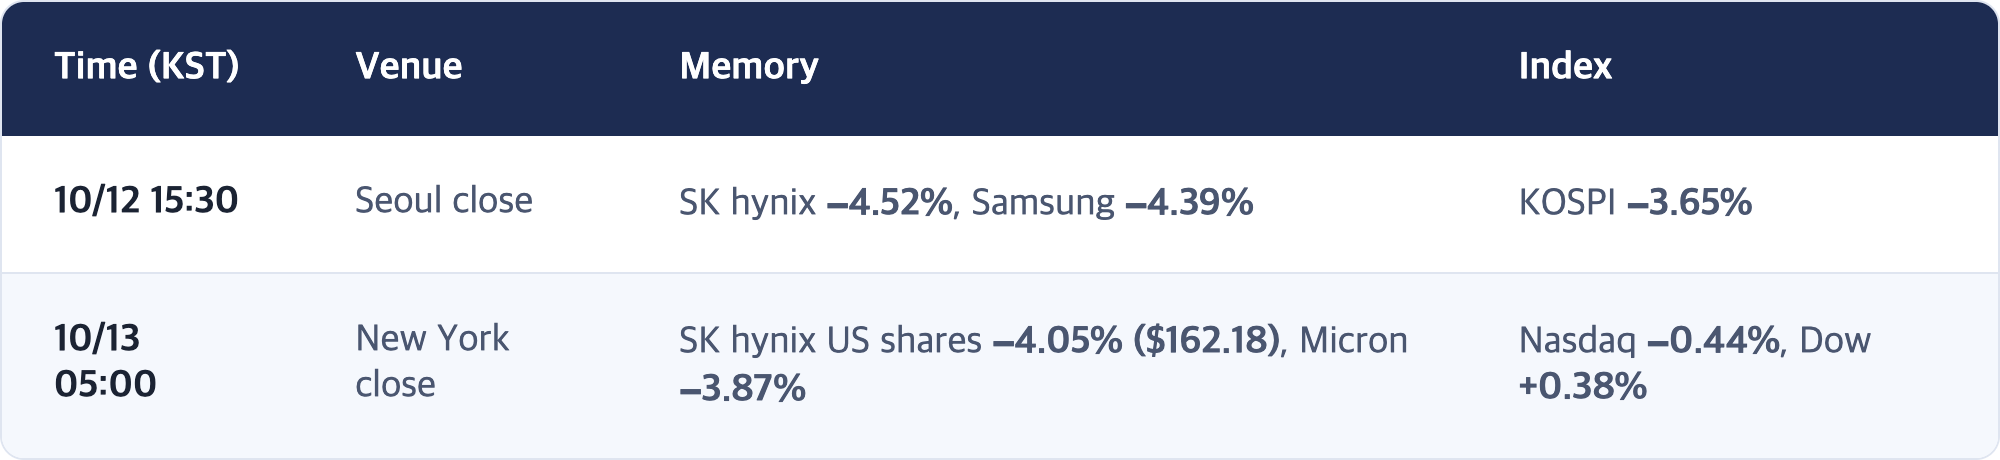
[Interpretation] On 10/8 the order was reversed: New York sold memory after Seoul had closed, leaving news Seoul "hadn't seen yet." This time CXMT spoke on a Saturday, so Seoul priced it first. SK hynix's −4.05% in New York is best read as New York catching up to Seoul's −4.52%.
So the genuinely new information for Seoul today is smaller than it looks. New York sold memory, but the broad market barely moved (S&P −0.06%), the Dow rose, and Microsoft and Meta were strong. New York singled out the memory group; it did not spread to the whole market.
[Observation] Foreigners are selling, yet the won is getting stronger
When foreign investors sell ₩2 trillion of Korean stocks, the proceeds usually get converted to dollars, pushing USD/KRW up. On 10/12 it fell ₩7 instead, and on 10/8 it was already at a one-month low of ₩1,338.5. We could not confirm the reason. We simply note that the currency is not telling the same "money leaving Korea" story as the equity flows.
4. Macro Backdrop: Oil at $106, Bonds Silent for Three Days, CPI on Wednesday
[Fact] US close, Fri 10/9 and Mon 10/12
[Fact] The University of Michigan's preliminary October consumer sentiment (released 10/9) came in at 46.3 (expected 47.6), the lowest since May, and the current-conditions index hit a record low of 44.7.
[Fact] Why oil climbed again
- Iran-backed Houthi rebels in Yemen attacked Riyadh's King Khalid International Airport on 10/10, killing 12 and injuring more than 300. Further attacks followed, and two tankers were struck near Oman and the Strait of Hormuz (Reuters, as reported).
- President Trump said he is considering US strikes on the Houthis alongside Saudi Arabia. A weekend Russia–Ukraine pause on energy-infrastructure attacks and more Russian diesel supply did not offset the move; Ukraine said Russia had already violated the deal.
- Goldman Sachs raised its December Brent forecast from $85 to $90 and puts the geopolitical risk premium at more than $20 a barrel.
[Interpretation] Bonds haven't seen this oil price yet
After Trump's 10/8 remark that there would be no strike on Iran before the midterms, the 10-year eased to 5.23–5.24%. Oil has since risen another $2, and the bond market was closed Monday. When Treasuries reopen tonight (KST), they absorb three days of oil in one go. CPI follows a day later.
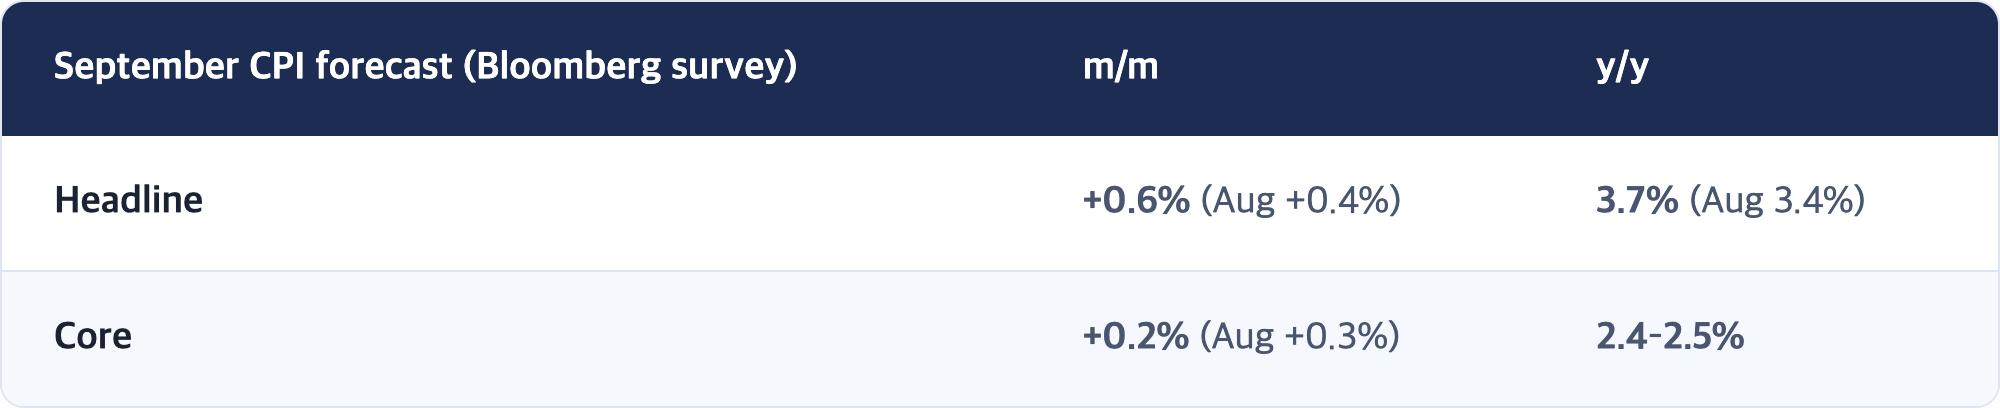
A four-month-high headline is already priced in; the market is watching core. If core holds at +0.2%, the read is "the oil shock hasn't spread to other prices yet." At +0.3% or more, the 9/11 story ("core is moving too") returns. CME odds of an October hike are below 22% (17.7% Friday). Cleveland Fed President Beth Hammack said the Fed should move toward a tighter stance "relatively soon" but did not back a hike this month.
5. Seoul Today (10/13): Checkpoints
The axis: "Was Monday's drop in Seoul a new judgment on memory prices, or a day driven by foreign flows?" And a third path: memory stabilizes, but foreign selling moves on to other large caps.
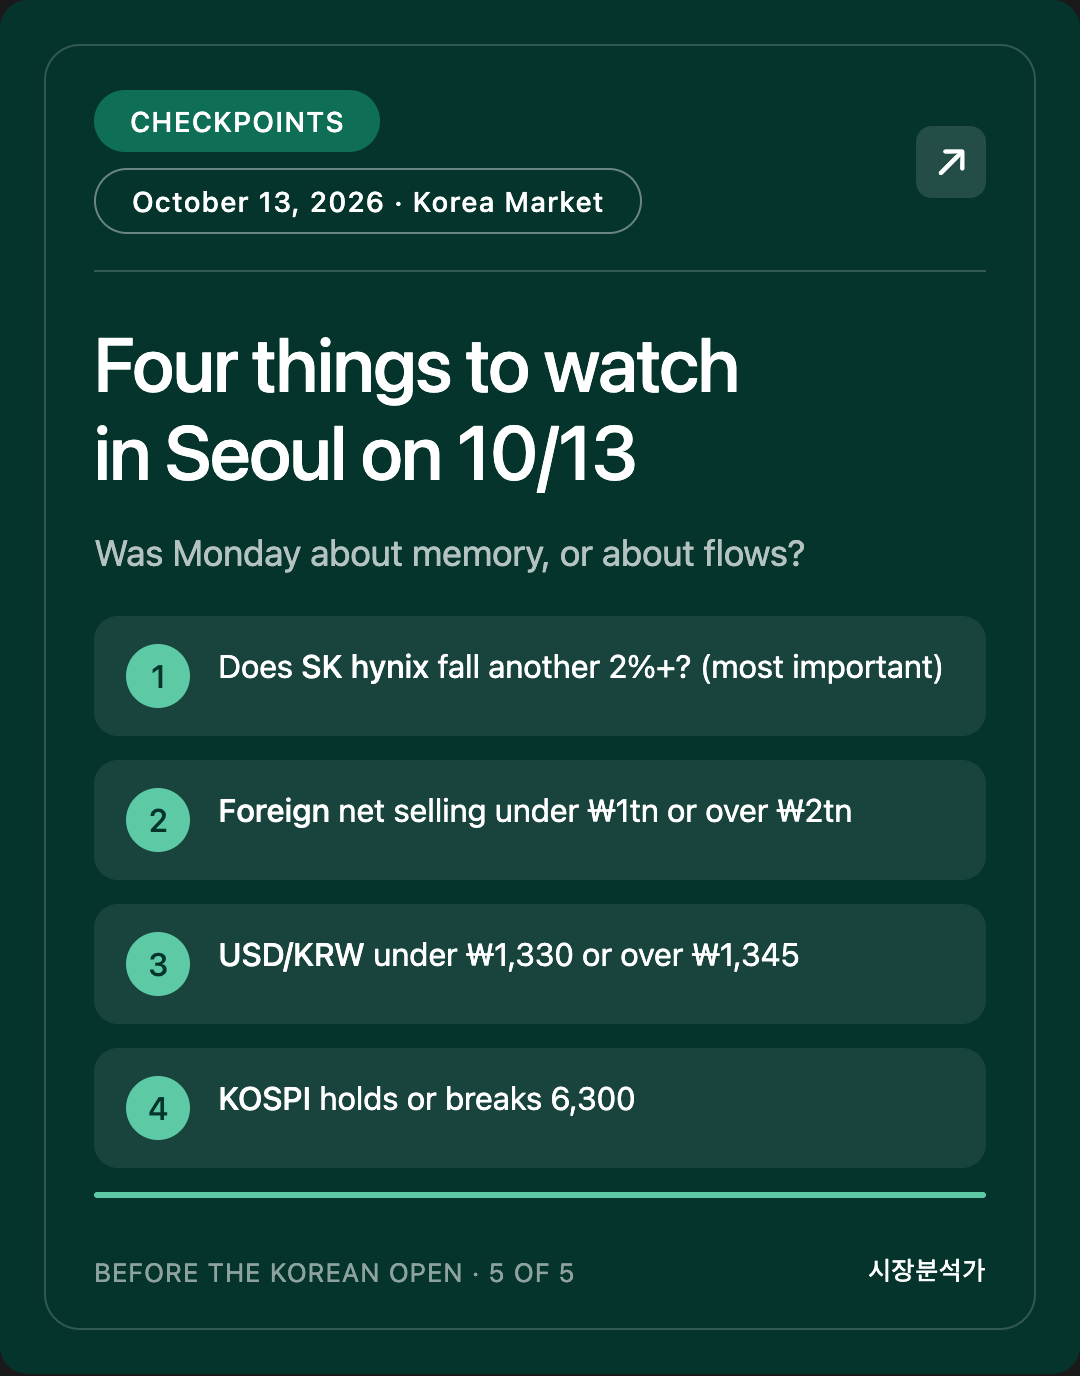
- Does SK hynix fall again by as much as its US shares did (−4.05%)? Another drop of more than 2% means Seoul is taking the same hit twice; flat or better means Monday already priced it. (Most important)
- Foreign net selling below ₩1tn / above ₩2tn. Above ₩2tn would be four days in a row, and then the flow itself is the story, more than earnings or CXMT.
- USD/KRW below ₩1,330 / above ₩1,345. Do foreign selling and a stronger won keep diverging?
- KOSPI holds / breaks 6,300, about 1.3% below Monday's close of 6,384.24.
[Interpretation] If #1 is flat or better while #2 is above ₩2tn, that's the third path. The question then shifts from "chip worries" to "are foreigners cutting their Korea weighting?"
US bank earnings and the bond-market reopening come tonight (KST), and CPI tomorrow night. Seoul closes today before seeing either.
6. Study Note: Why Do Shares Fall on Record Earnings?
The concept
Stocks in industries where prices swing hard, like memory chips, are called cyclical stocks. They react less to "how much is being earned now" and more to "are profits still rising, or about to roll over?" That's why the moment of peak profit can be a risky moment for the share price. Investors call this the peak-out worry.
An analogy
Picture an orchard owner. Apple prices are at a record and this year's harvest is a jackpot. Then word comes that a big new orchard next town over can grow apples more cheaply. This year's books are the best ever, but anyone buying the orchard is calculating next year's and the year after's apple prices. Everyone already knows about this year's jackpot.
The real case (10/8–10/12)
- This year's books: Samsung's ₩107.4tn quarterly operating profit; chip exports +170%.
- The new orchard: CXMT says it will unveil server DRAM with 33% smaller cells by year-end.
- News about the customers: a report that OpenAI's revenue was smaller than the market assumed.
- Result: Samsung −4.39% on the next trading day after its results.
One-line summary
Cyclical stocks are priced on the direction of profits, not their size. But "the direction has turned" is still a suspicion, not something the numbers have confirmed. Confirmation will come from memory price data and next quarter's guidance.
7. Corrections & Open Items
Correction
- Updating one call from the 10/9 AM brief. Seeing the pre-market chip bounce (SOXX +1.9%), that brief said pre-market was leaning toward the "different accounting basis" reading. SOX closed −0.41%; the pre-market gain disappeared. It's a textbook case of that brief's own study note: treat pre-market numbers only as a midpoint check.
Source discrepancies (value used in text)
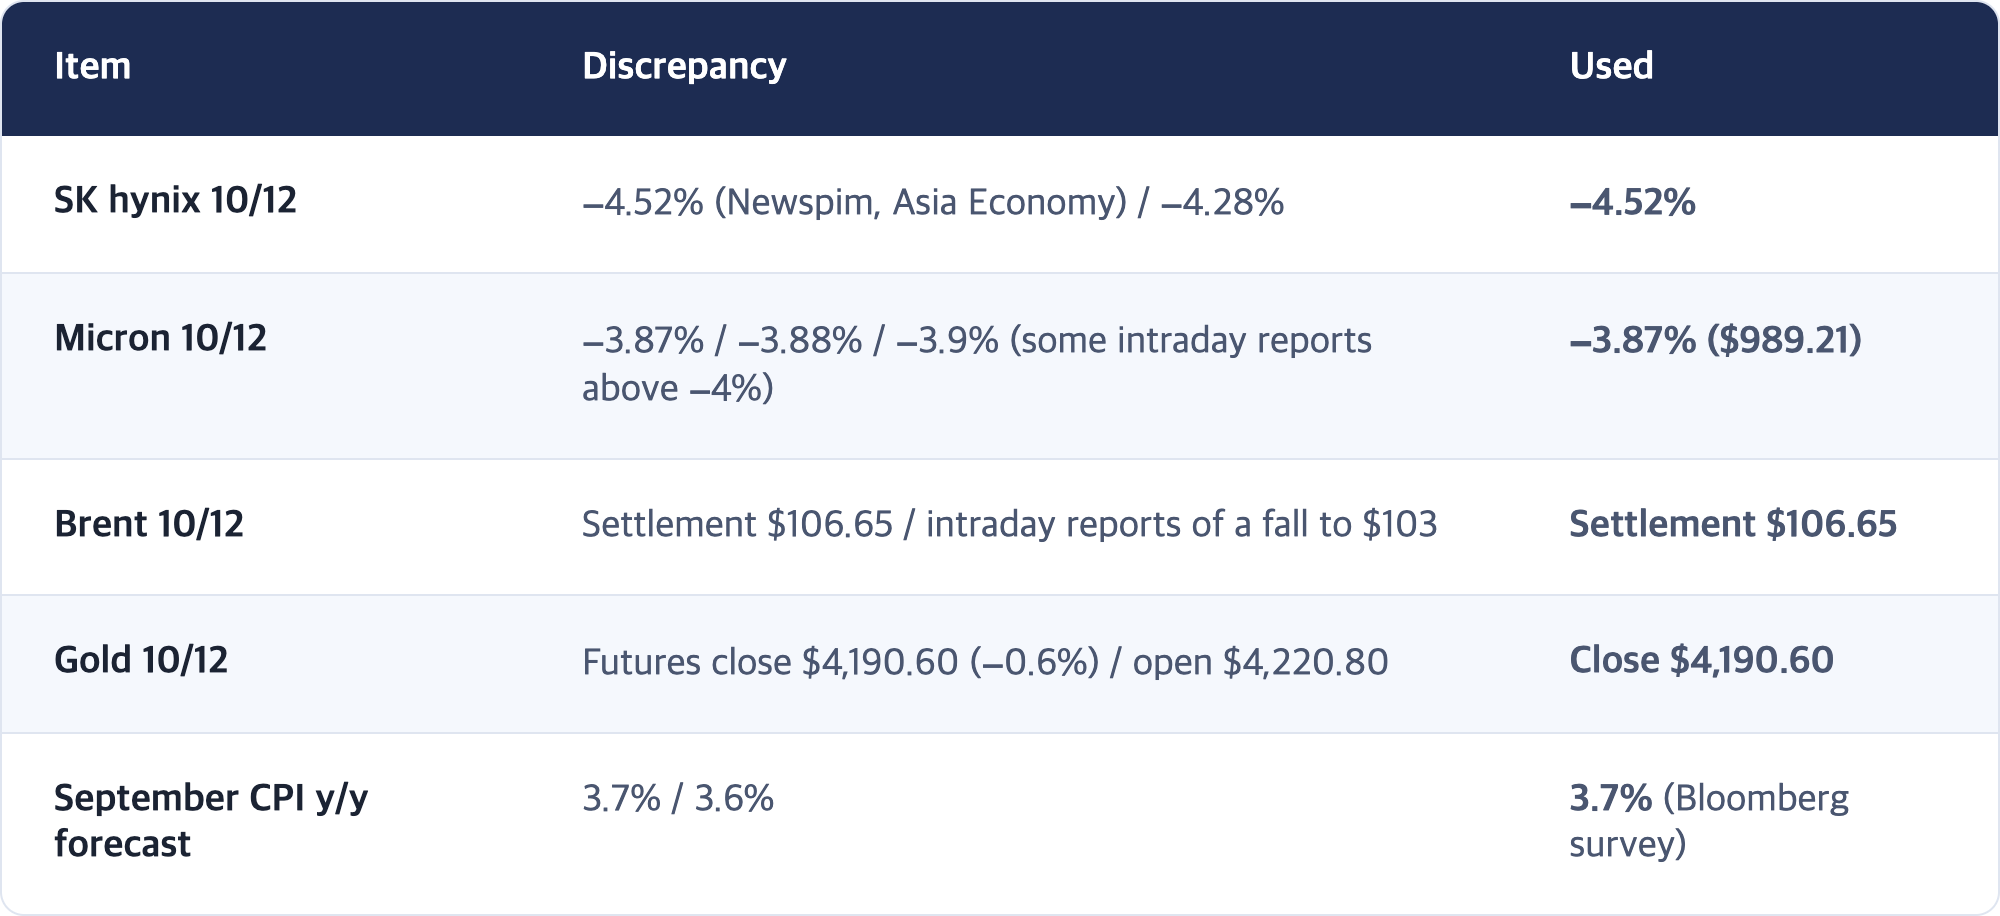
🔲 Not confirmed
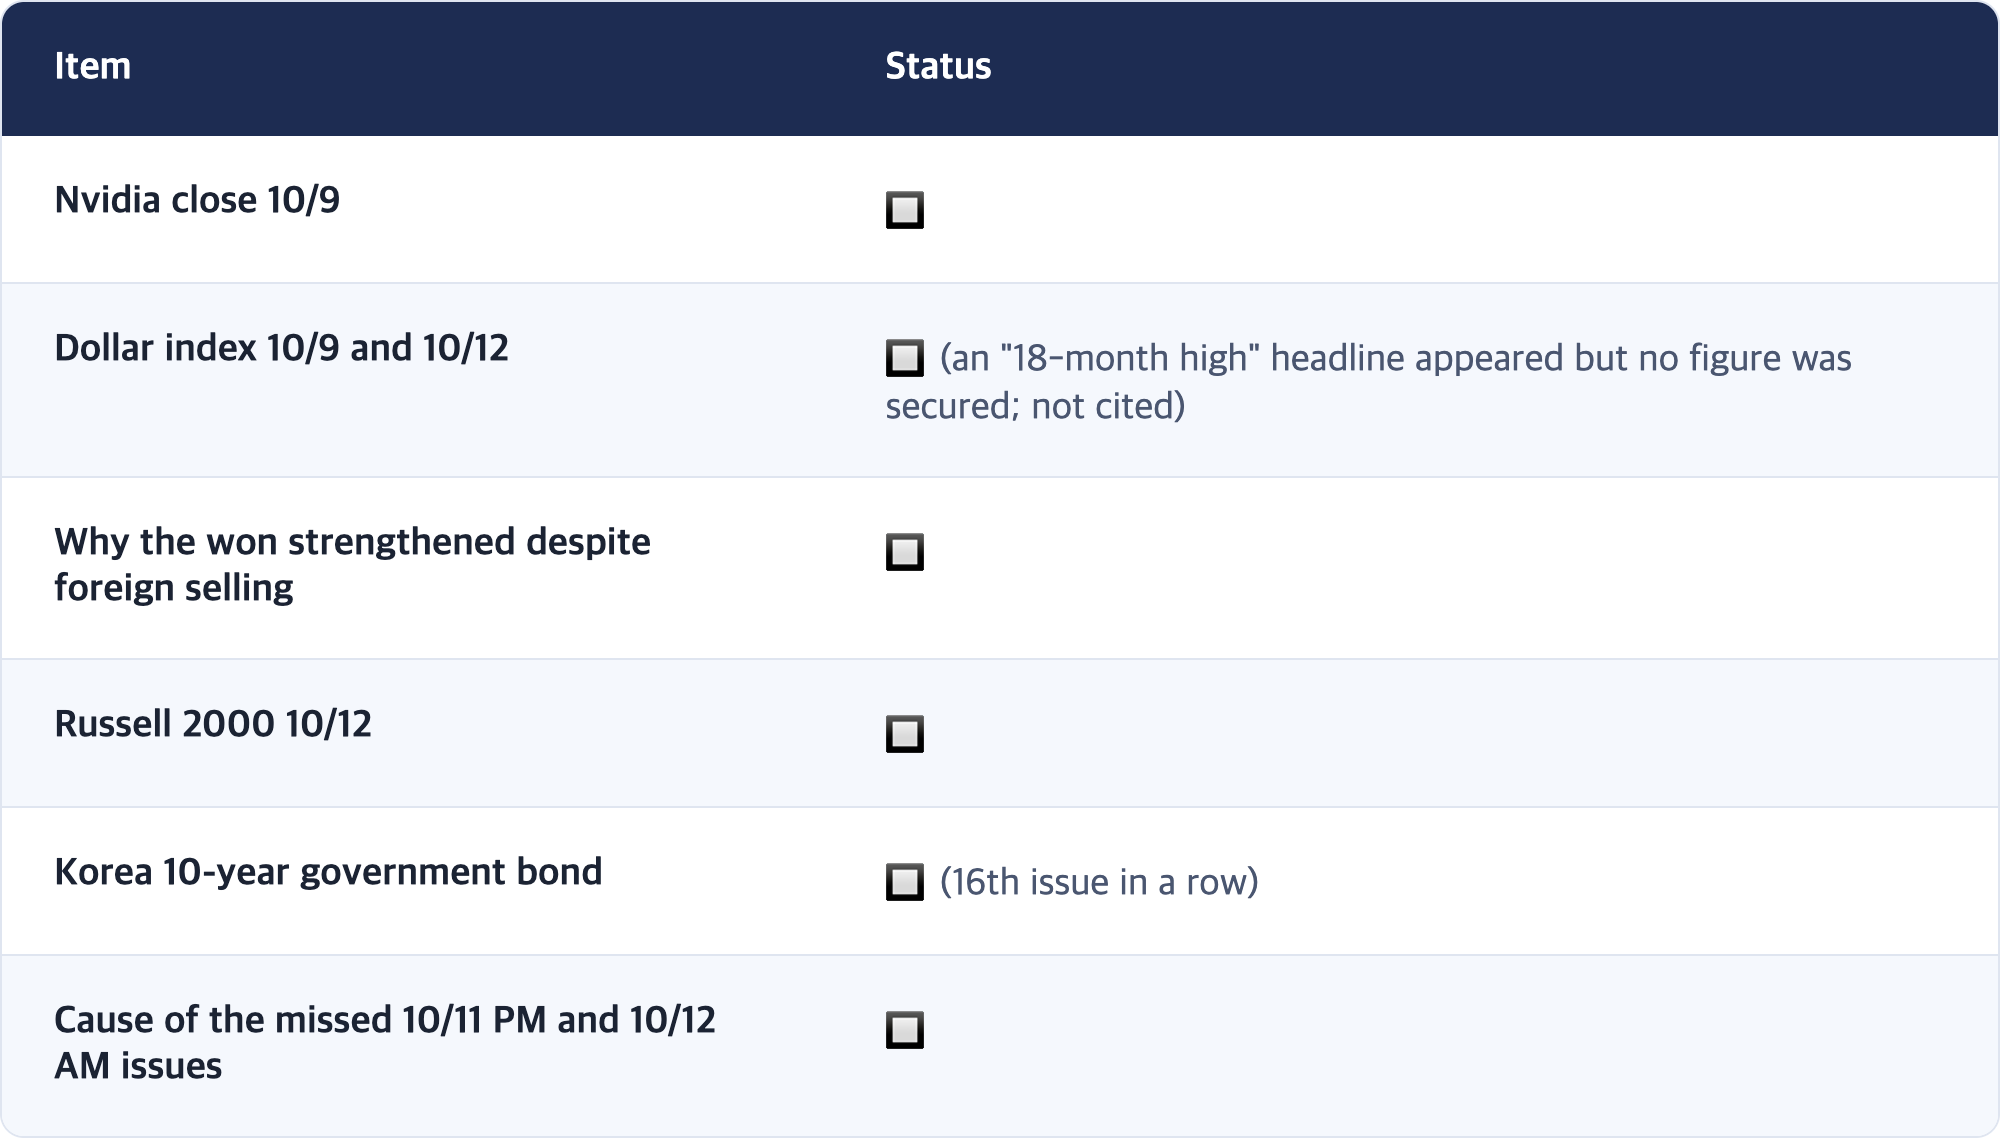
8. Event Calendar (KST)
Sources
- KOSPI plunges 3% on ₩2tn foreign selling, below 6,400 for first time in two months | Newspim
- KOSPI closes at 6,384.24, down 241.69 points | Asia Economy
- Wall Street mixed; Nasdaq −0.44% on chip weakness | Newspim
- NY close: mixed on oil surge and chip weakness | News1
- Micron falls 3.9% on Chinese memory catch-up | News1
- Oil at one-month high on Saudi attacks; SOX −2.7% on China worries | Seoul Economic Daily
- How major US stock indexes fared Friday 10/9/2026 | AP via La Nación
- How major US stock indexes fared Monday 10/12/2026 | AP via 10TV
- Market Review: October 12, 2026 | Investrade
- Brent tops $106 after deadly Saudi airport attack | CNBC
- China's CXMT to Launch 4F² Server DRAM This Year | BigGo Finance
- Why is Micron stock down? CXMT's 4F² DRAM breakthrough explained | Geo
- Oil prices on 10/9 | Energy News (Korea)
- Samsung Q3 preliminary operating profit ₩107tn | YTN
- Samsung posts ₩107tn, so why is the stock falling? | Financial News
- US September CPI expected +0.6% | TokenPost
- Week ahead: Q3 earnings season opens with big banks and September CPI | Global Economic
- Gold slips | eToday
- US October consumer sentiment at five-month low | SBS Biz
Market Analyst · We do not make buy or sell recommendations on individual stocks. This report provides macro context and interpretation.
📌 More market briefs
※ This post is market observation and organization intended to support your own judgment. It is not a recommendation to buy or sell any security. Figures are as of the time of writing and may differ between sources.
If this was useful, bookmark it or pass it along. It genuinely helps me write the next one.
I can survive. We can survive.