October 9, 2026 US Market Brief — Nasdaq and S&P 500 Before the Open
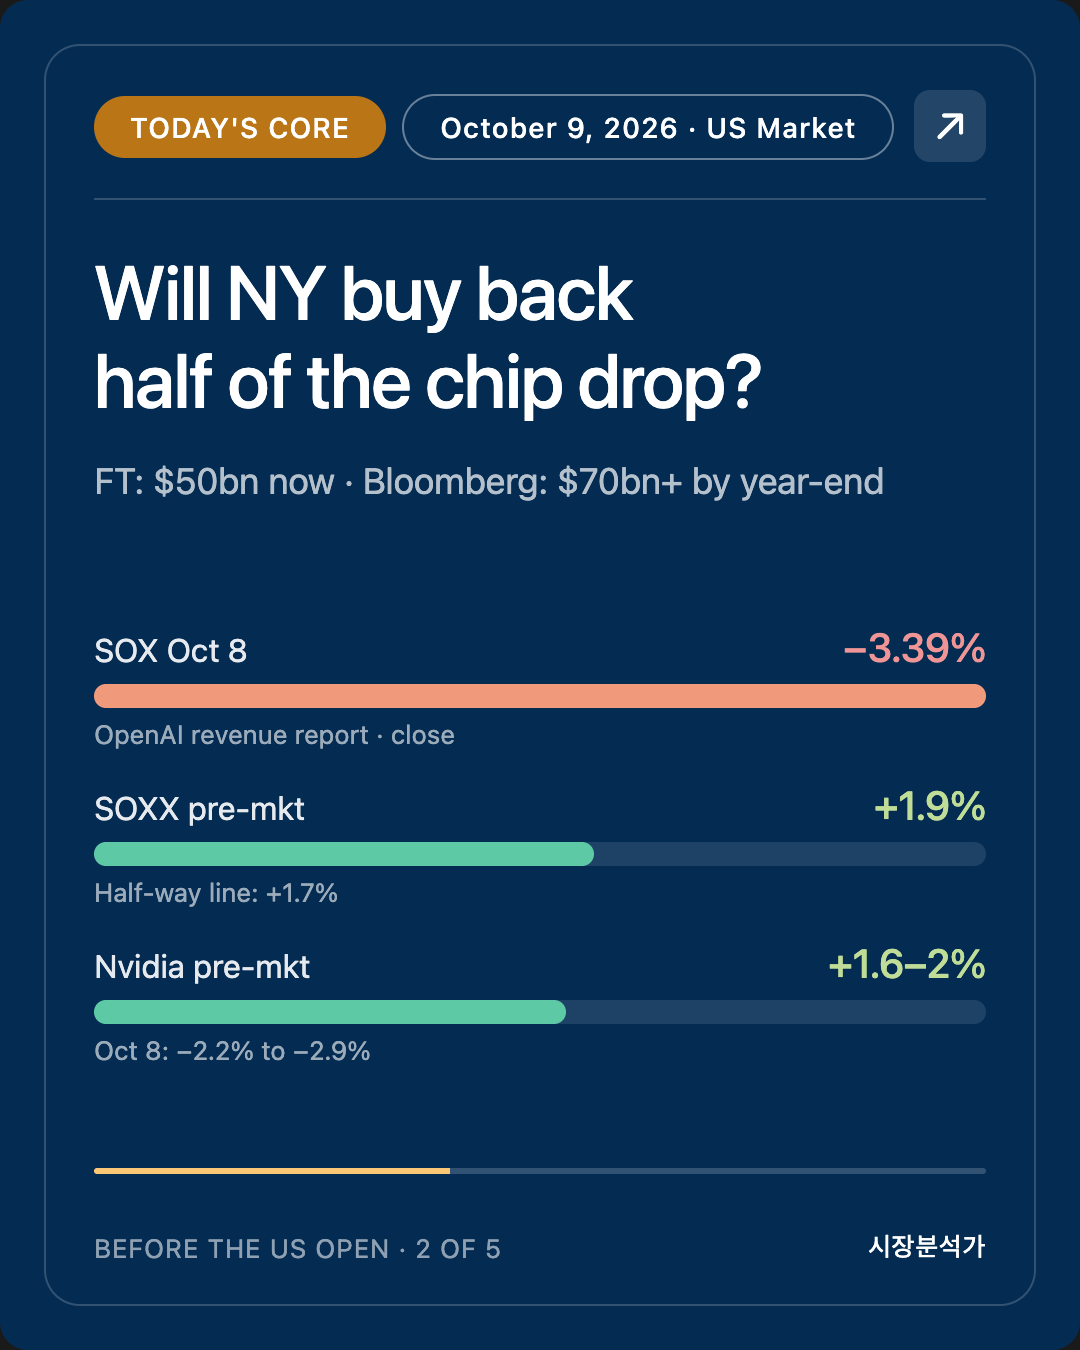
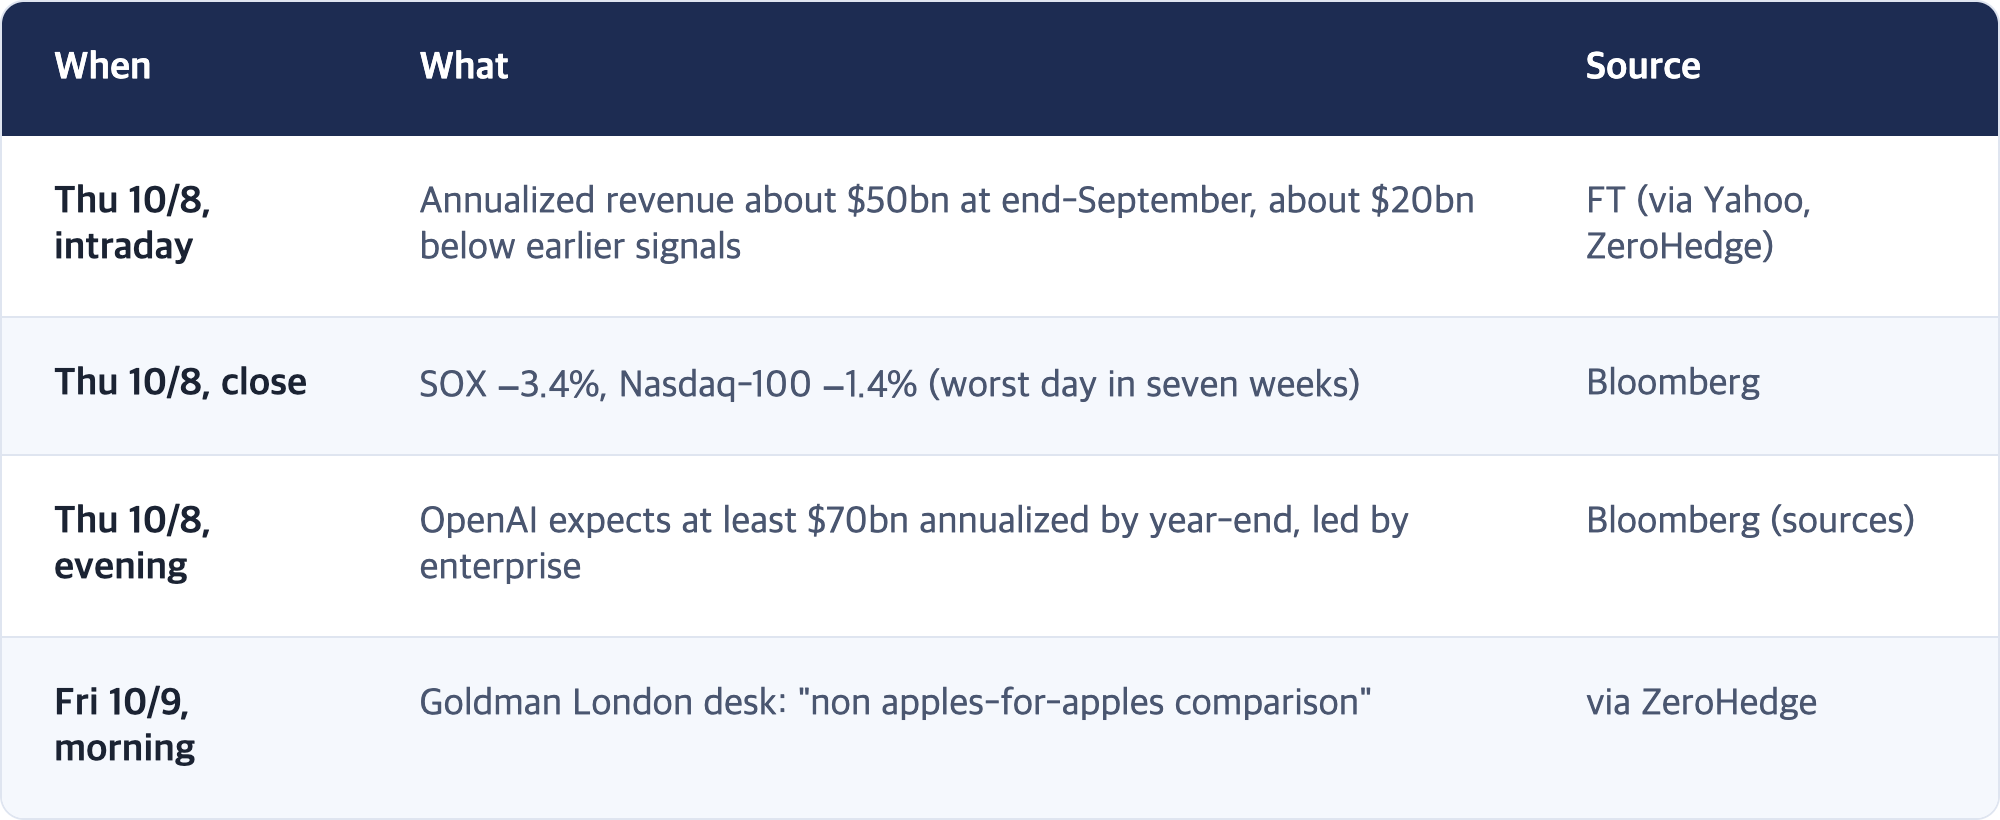
Yesterday's chip sell-off in New York came down to one number. The Financial Times reported that OpenAI's annualized revenue at the end of September was about $50 billion, roughly $20 billion below what the market had been working with, and the Philadelphia Semiconductor Index (SOX) fell 3.4%. Overnight, OpenAI pushed back: Bloomberg reported the company expects to reach at least $70 billion in annualized revenue by year-end, led by enterprise customers.
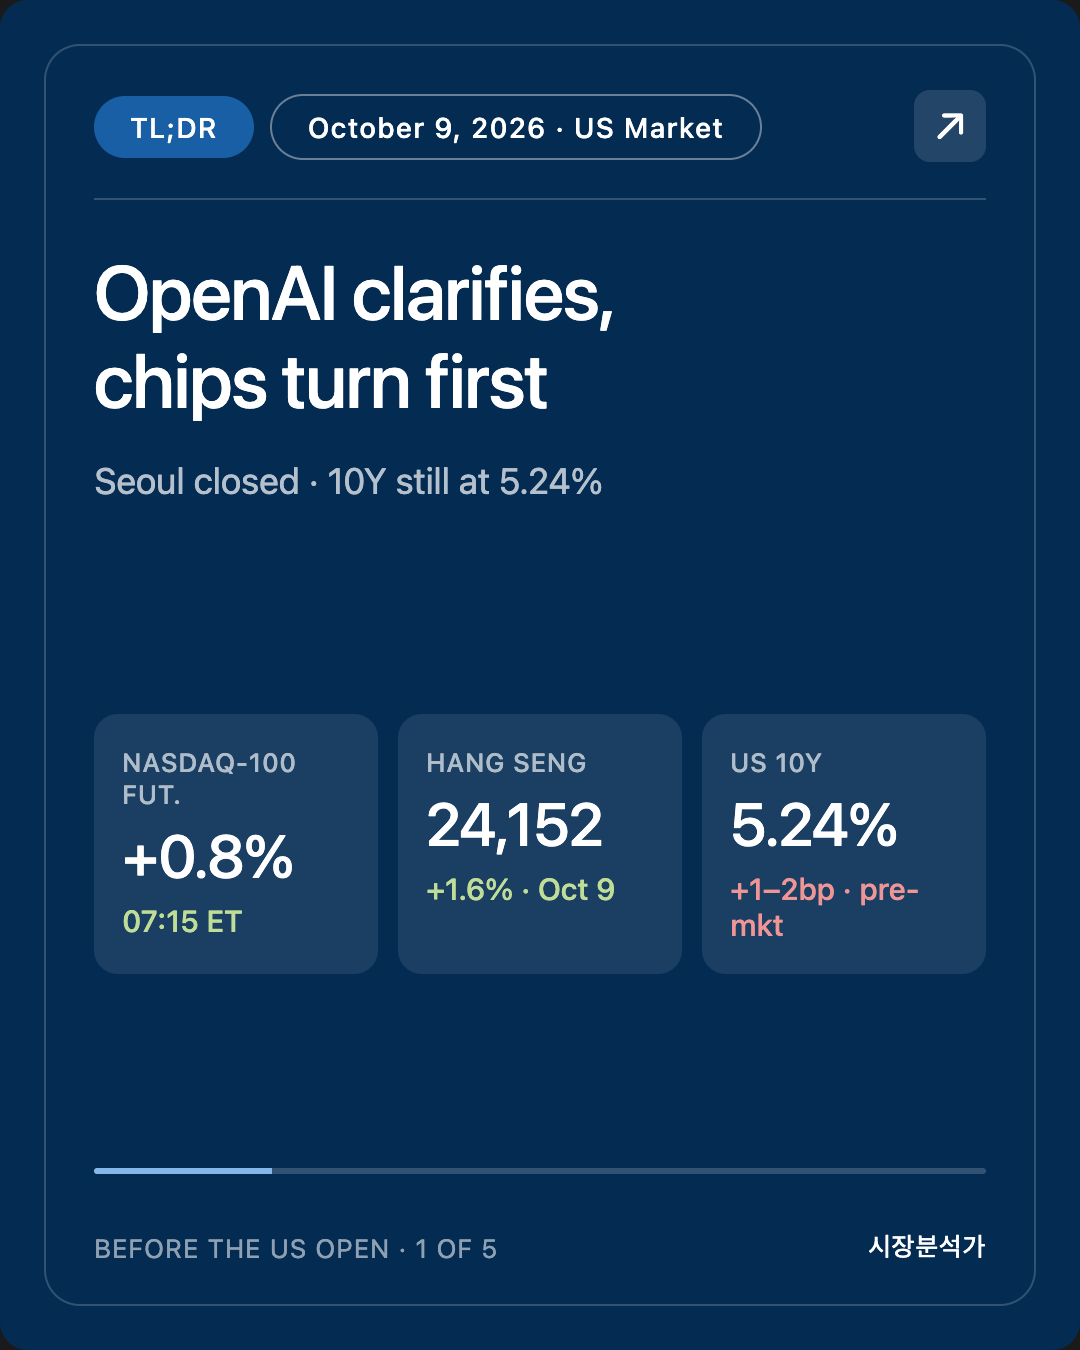
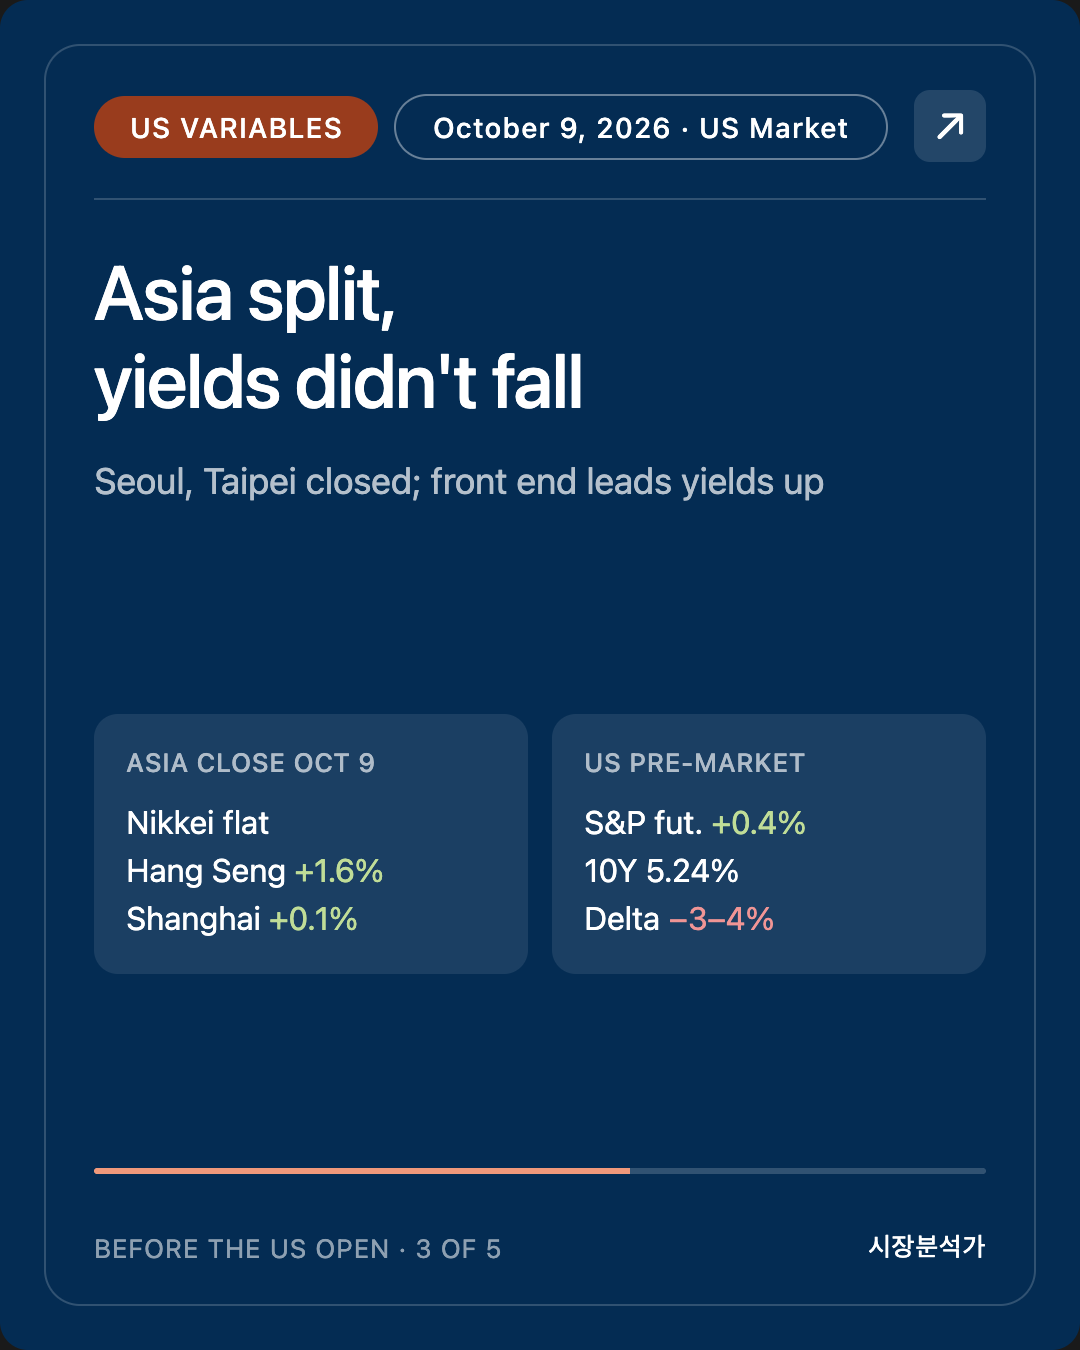
Chips turned first. As of 07:15 ET, Nasdaq-100 futures are +0.8%, S&P 500 futures +0.4% (7,850) and Dow futures +0.2%. The iShares semiconductor ETF (SOXX) is +1.9% pre-market and Nvidia +1.6–2%. Hong Kong's Hang Seng closed +1.6% at 24,152.44 and Europe's STOXX 600 is up about 1%.
Rates have not followed. The 10-year Treasury yield is 5.24–5.25% (+1–2bp), and the University of Michigan's one-year inflation expectation (forecast 4.8%) lands at 10:00 ET. Today's question for New York: does it buy back more than half of what it sold in chips yesterday?
This is Mr. Can. Here is the October 9, 2026 brief ahead of the US market open.
Written: 2026-10-09 05:50 PDT (Korea 10/9 21:50 KST)
Basis: Tokyo, Hong Kong and Shanghai closes on 10/9 + Europe intraday + US futures and pre-market (around 07:15 ET)
🟢 Scheduled 05:30 PDT, started 05:43 PDT. US figures are pre-market and futures, not closing prices.
🟡 Seoul is closed today for Hangul Day (the holiday celebrating the Korean alphabet), and Taiwan is closed too. Today's Asia wrap therefore leans on Tokyo, Hong Kong and Shanghai. Seoul reopens Monday, 10/12, the same day the US bond market is shut for Columbus Day.
⚡ TL;DR
- ★ OpenAI redrew the picture. FT: "about $50bn annualized at end-September." Bloomberg: "at least $70bn by year-end." A Goldman trading desk called the original comparison "not apples-for-apples" (as cited by ZeroHedge).
- ★ Chips are leading the rebound. SOXX +1.9%, Nvidia +1.6–2%, Nasdaq-100 futures +0.8% vs S&P +0.4% and Dow +0.2%. Apple is −2% and AT&T / T-Mobile are −6% to −8% on reports of SpaceX moving into mobile service.
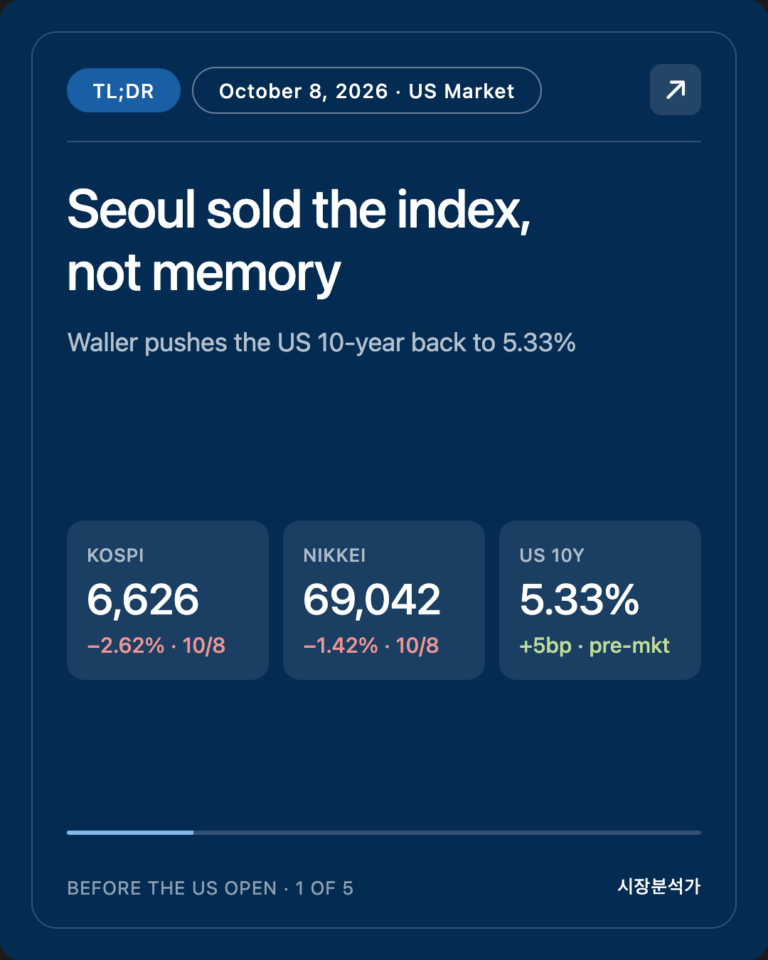
- Asia split. Hang Seng +1.6% (Hang Seng Tech +3.1%, Xiaomi about +10%); Nikkei 69,030.92, flat (SoftBank Group −4.3%); Shanghai +0.1%. Seoul and Taipei closed.
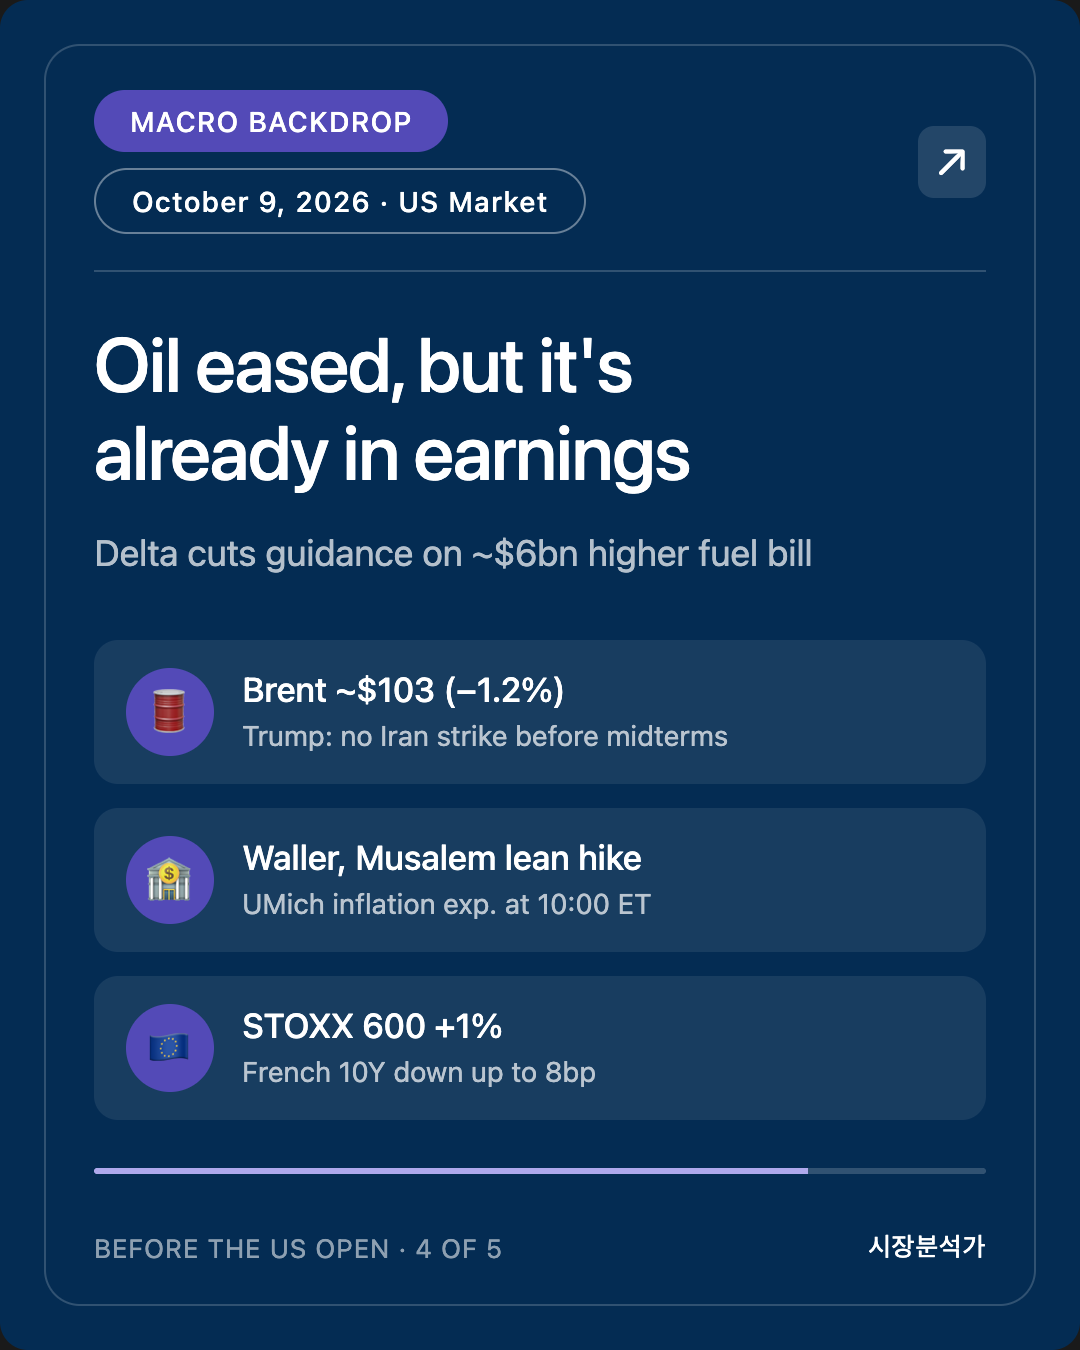
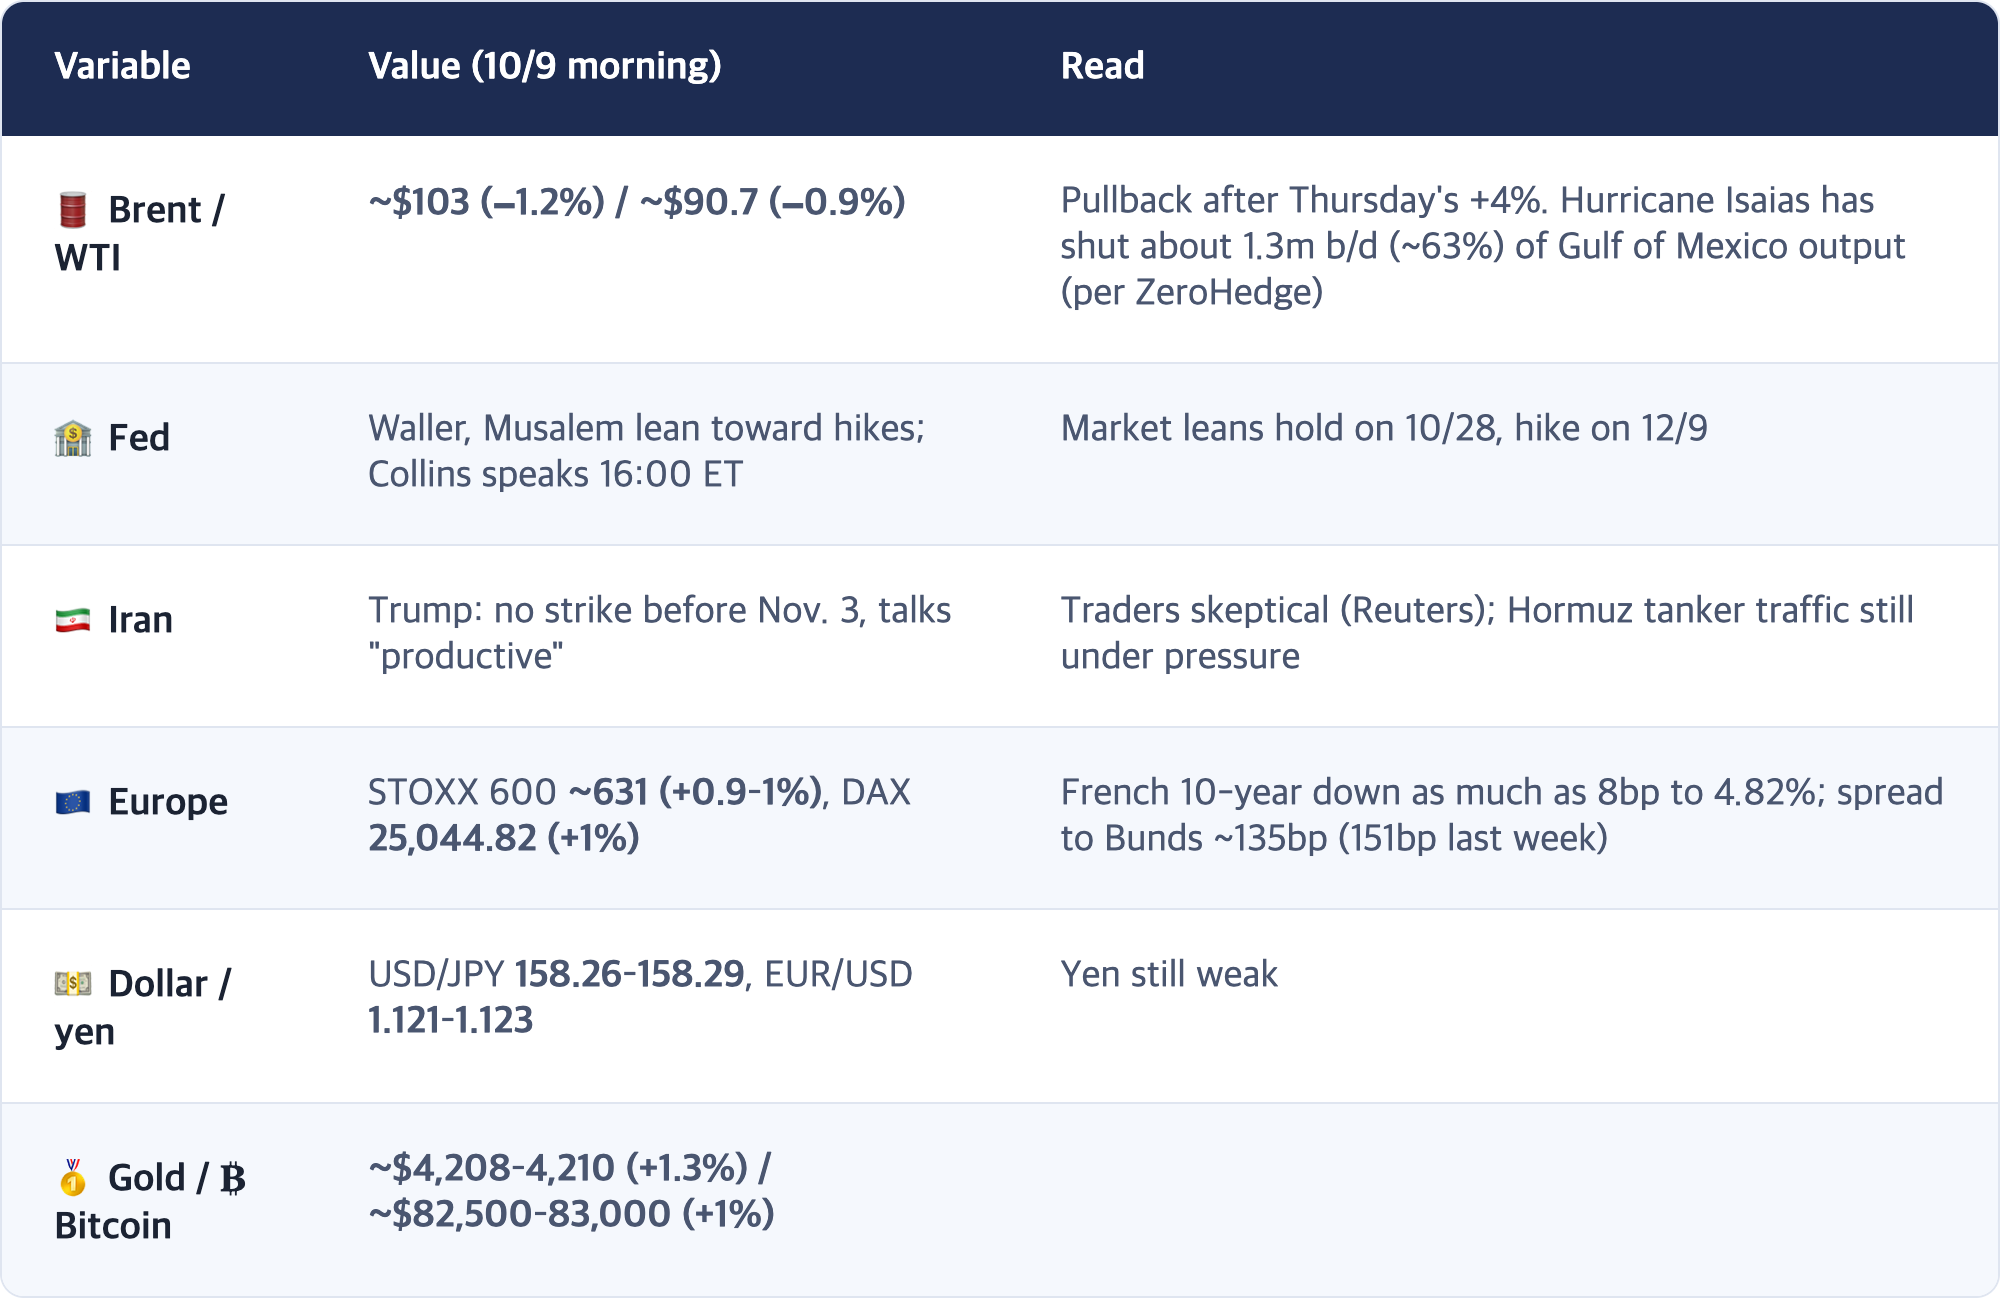
- Oil eased, Europe rallied. Brent about $103 (−1.2%), WTI about $90.7 (−0.9%) after President Trump said the US will not strike Iran before the Nov. 3 midterms and that talks are "productive." STOXX 600 +0.9–1%, DAX +1%, French 10-year yields down as much as 8bp.
- But yields are not falling. The 10-year is 5.24–5.25%. Delta Air Lines cut guidance, citing a fuel bill up about $6 billion for the year (shares −3% to −4% pre-market). Oil is now showing up in earnings, not just in inflation.
1. Checkpoint scorecard
The four set by the 10/8 PM brief (due by Seoul's close on 10/12)
The 10/8 PM checkpoints are scored at Monday's Korean close. Today we only take an interim read on the two tied to US Friday trading.
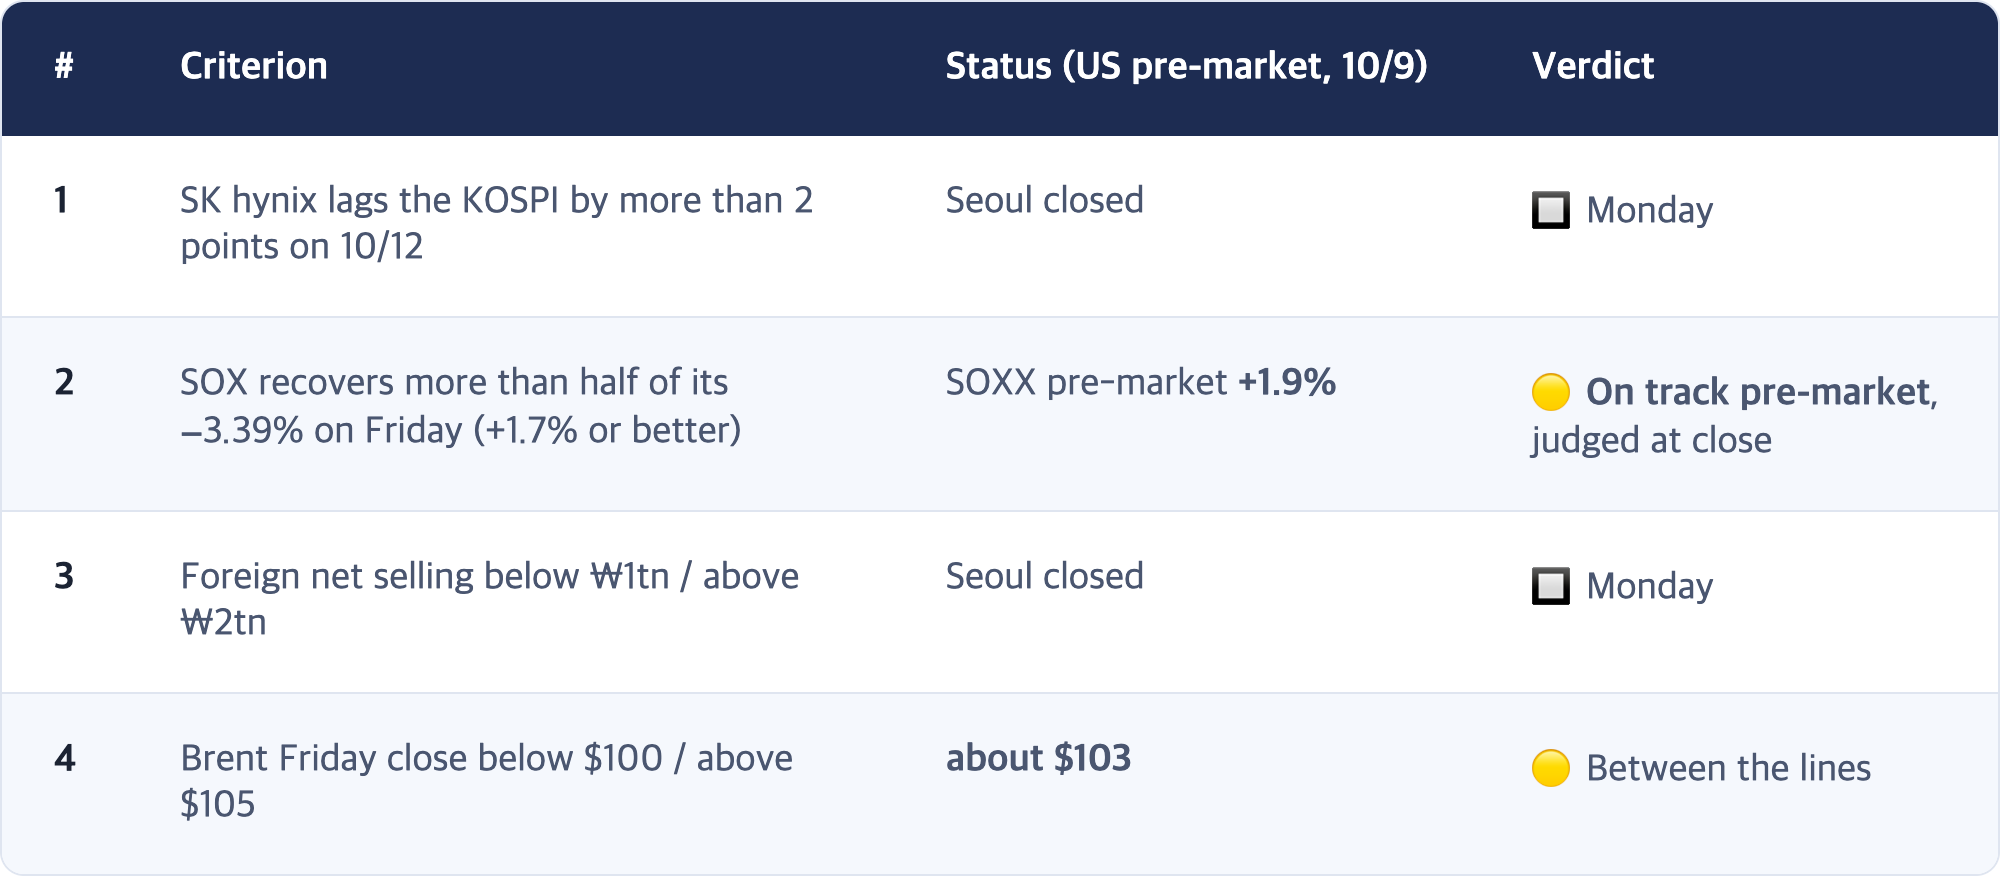
If item 2 holds to the close, Monday's Seoul test changes meaning: it becomes a question of whether Korea reacts on its own to news New York has already digested.
2. Today's core story: OpenAI's clarification turned chips first
[Fact] Two days of OpenAI revenue headlines
[Fact] US pre-market, 10/9 (around 07:15 ET)
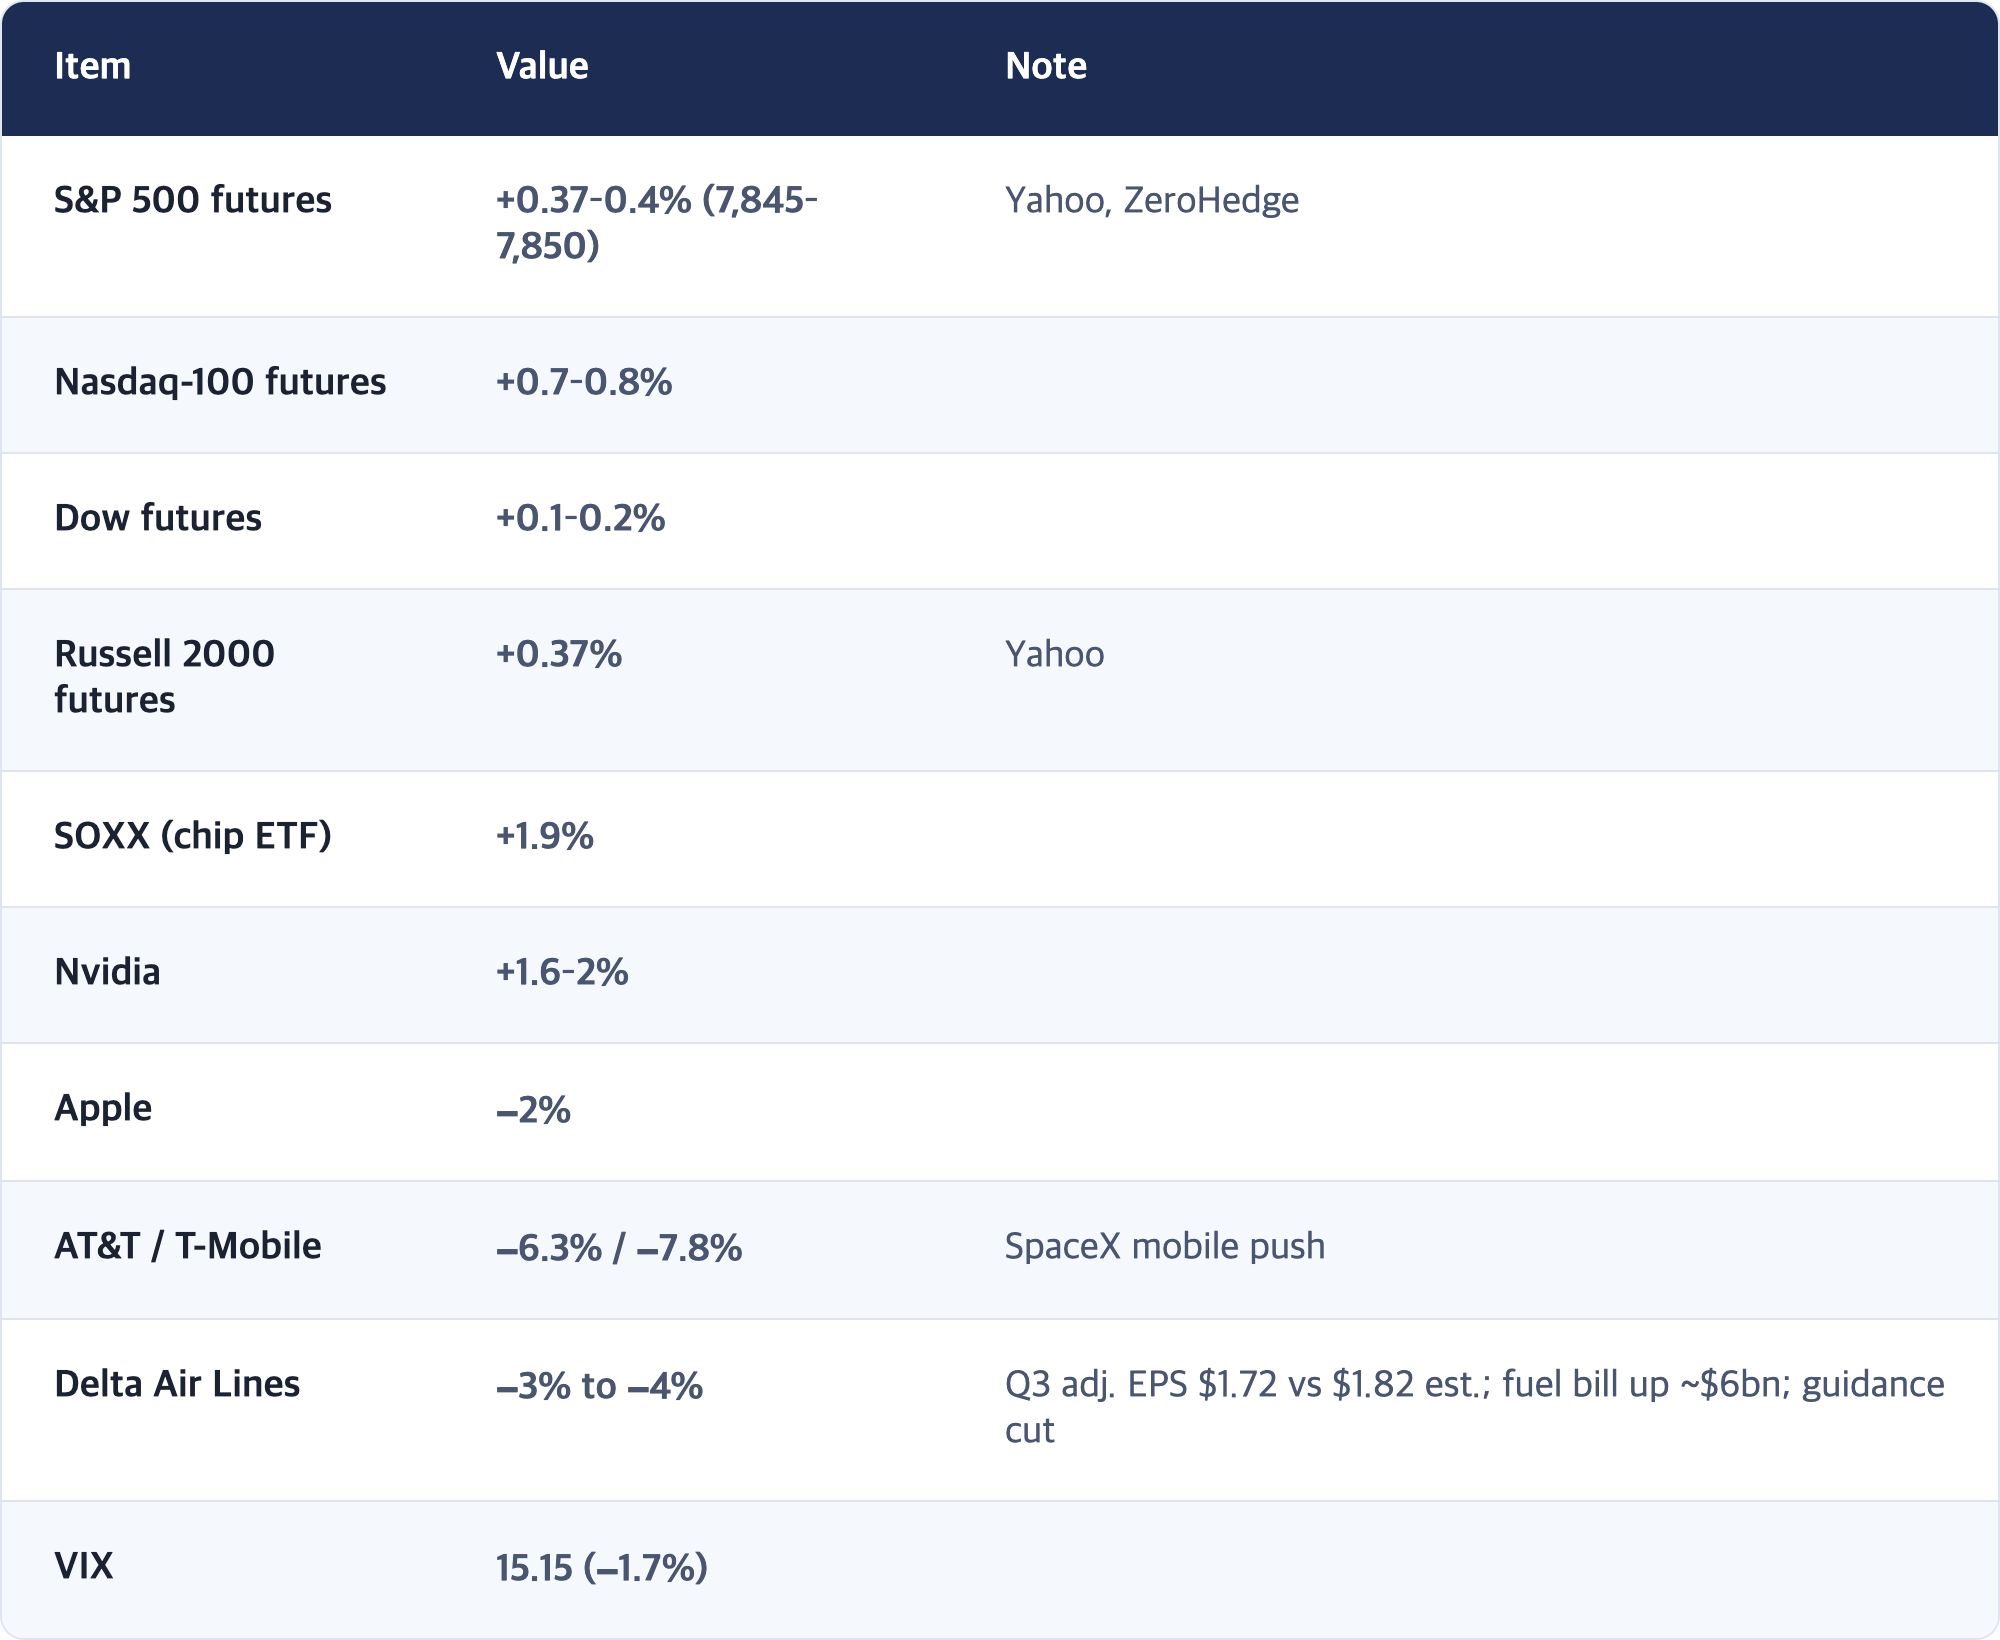
★ [Interpretation] The market reacted to how the number was counted
Annualized ("run-rate") revenue is a snapshot of current speed, and the snapshot changes a lot depending on what you count. Yesterday the market was surprised by a smaller snapshot; overnight OpenAI showed a different one for year-end.
One distinction matters. Today's clarification does not reverse yesterday's report. The ~$50bn end-September figure stands; $70bn is a forecast three months out. What the market is buying this morning is not new information but reassurance that the growth rate is intact. How much of the rebound survives the regular session is the first real evidence on whether Thursday was an overreaction to an accounting mismatch, or the start of a broader re-pricing of AI capital spending.
3. US variables: Asia split, and rates have not followed
[Fact] Asia closes, Friday 10/9
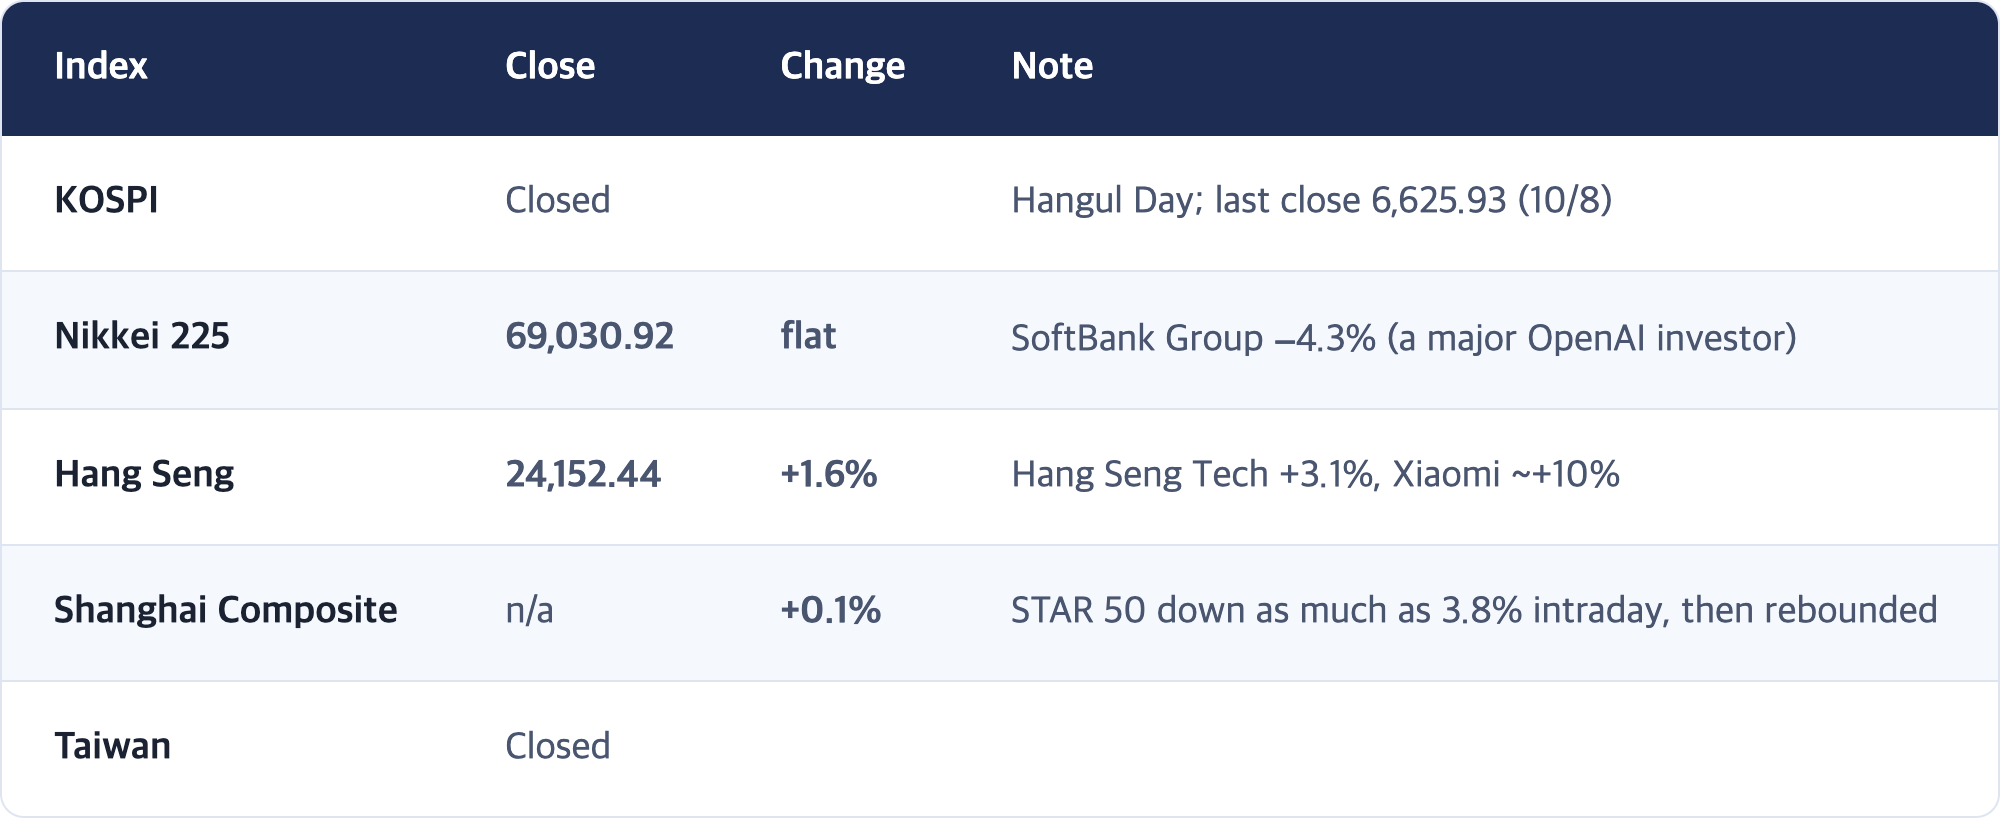
[Observation] Tokyo absorbed the OpenAI story through SoftBank; Hong Kong rallied on its own tech names. With Seoul and Taipei (the memory and foundry markets) both shut, today's Asian session is a weak answer to whether Thursday's chip sell-off spread to Asia. Seoul gives that answer on Monday.
[Fact] Rates, 10/9 pre-market
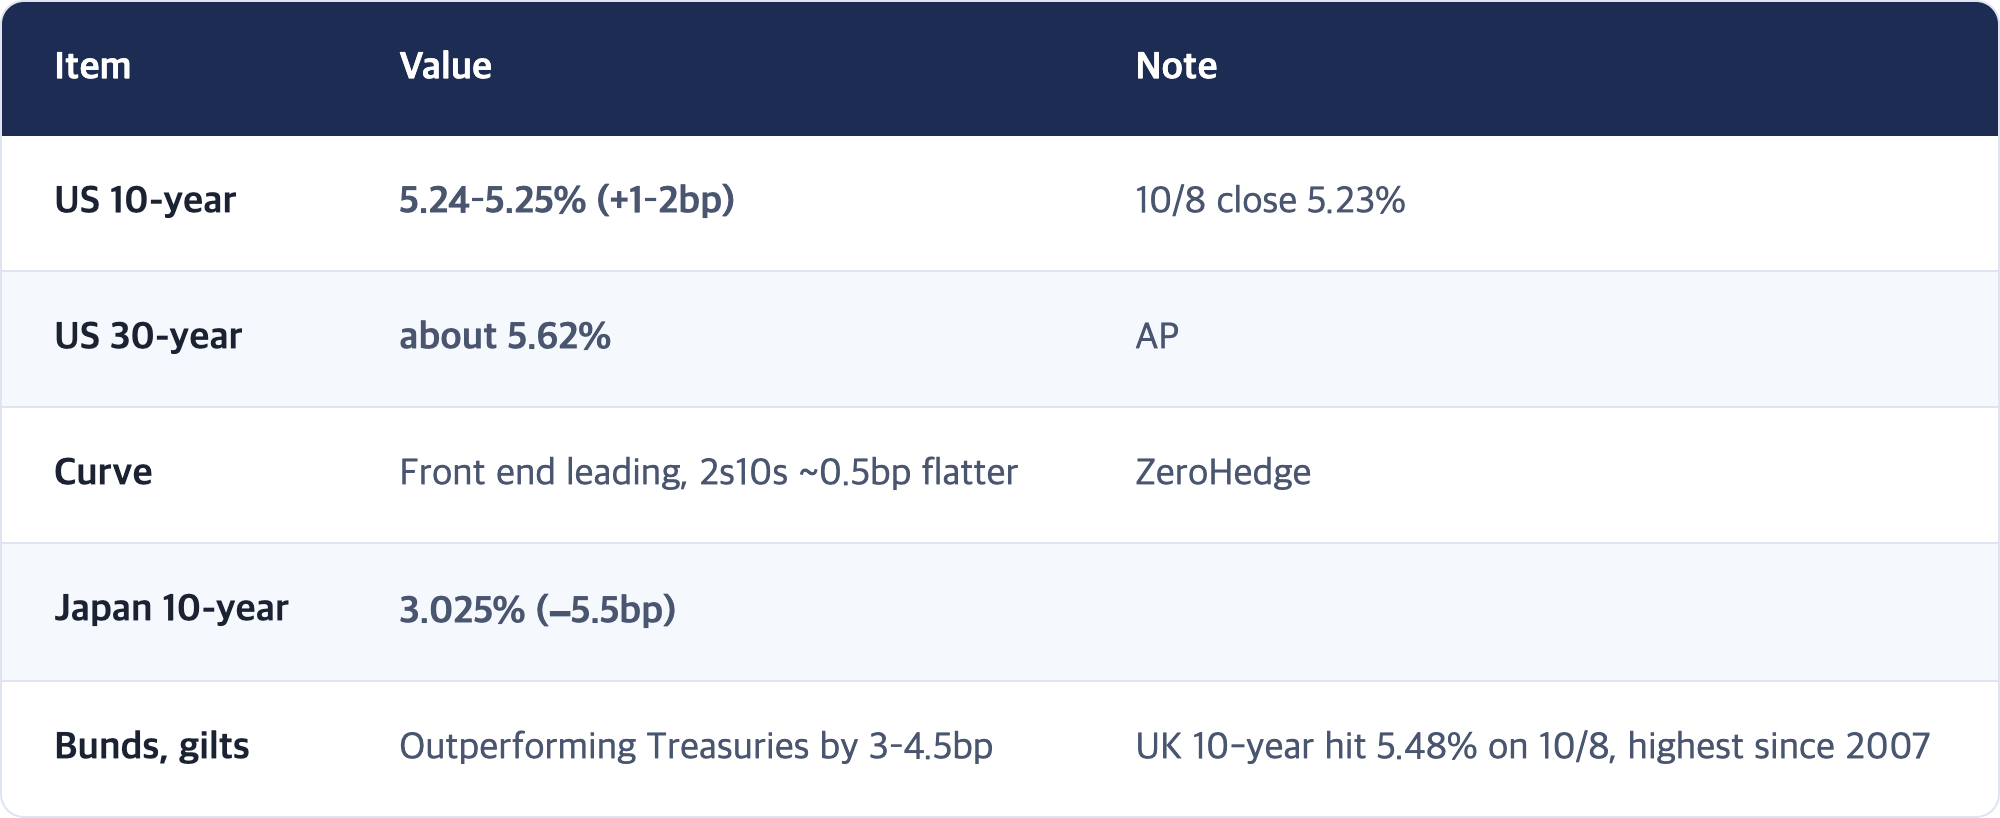
★ [Interpretation] Oil fell more than 1%, yet yields rose
The rise is led by short-dated Treasuries, which track Fed expectations most directly. Governor Waller ("additional hikes," not necessarily at consecutive meetings) and St. Louis Fed President Musalem (hikes over the next six to nine months) are still holding the front end up. That makes the 10:00 ET Michigan release matter: one-year inflation expectations are forecast at 4.8% (prior 4.6%). A hotter print could lift the front end again and take some steam out of the chip rebound.
4. Macro backdrop: oil came off, but it is already in earnings
★ [Interpretation] What Delta just showed
Until now, oil has mostly been a story of "prices → inflation → yields." Delta shows the other channel: a fuel bill up about $6 billion a year, and a guidance cut to match. Third-quarter earnings season opens Tuesday (10/13) with the big banks. With Brent above $100 for the better part of three months, oil is starting to reach stock prices through profits, not just through rates. A 1% daily dip does not close that channel.
5. Today's US session (Fri 10/9, PDT)
[Observation] Schedule (PDT)
- 05:30 Canada September jobs (prior −41,700; unemployment 6.4%)
- 06:30 US open
- 07:00 University of Michigan sentiment, October preliminary (est. 47.6–48 / prior 48.1); 1-year inflation expectations est. 4.8%, 5–10-year 3.5%
- 13:00 Boston Fed President Collins
- Mon 10/12: US bond market closed (Columbus Day), stocks open; Seoul reopens; Tokyo closed
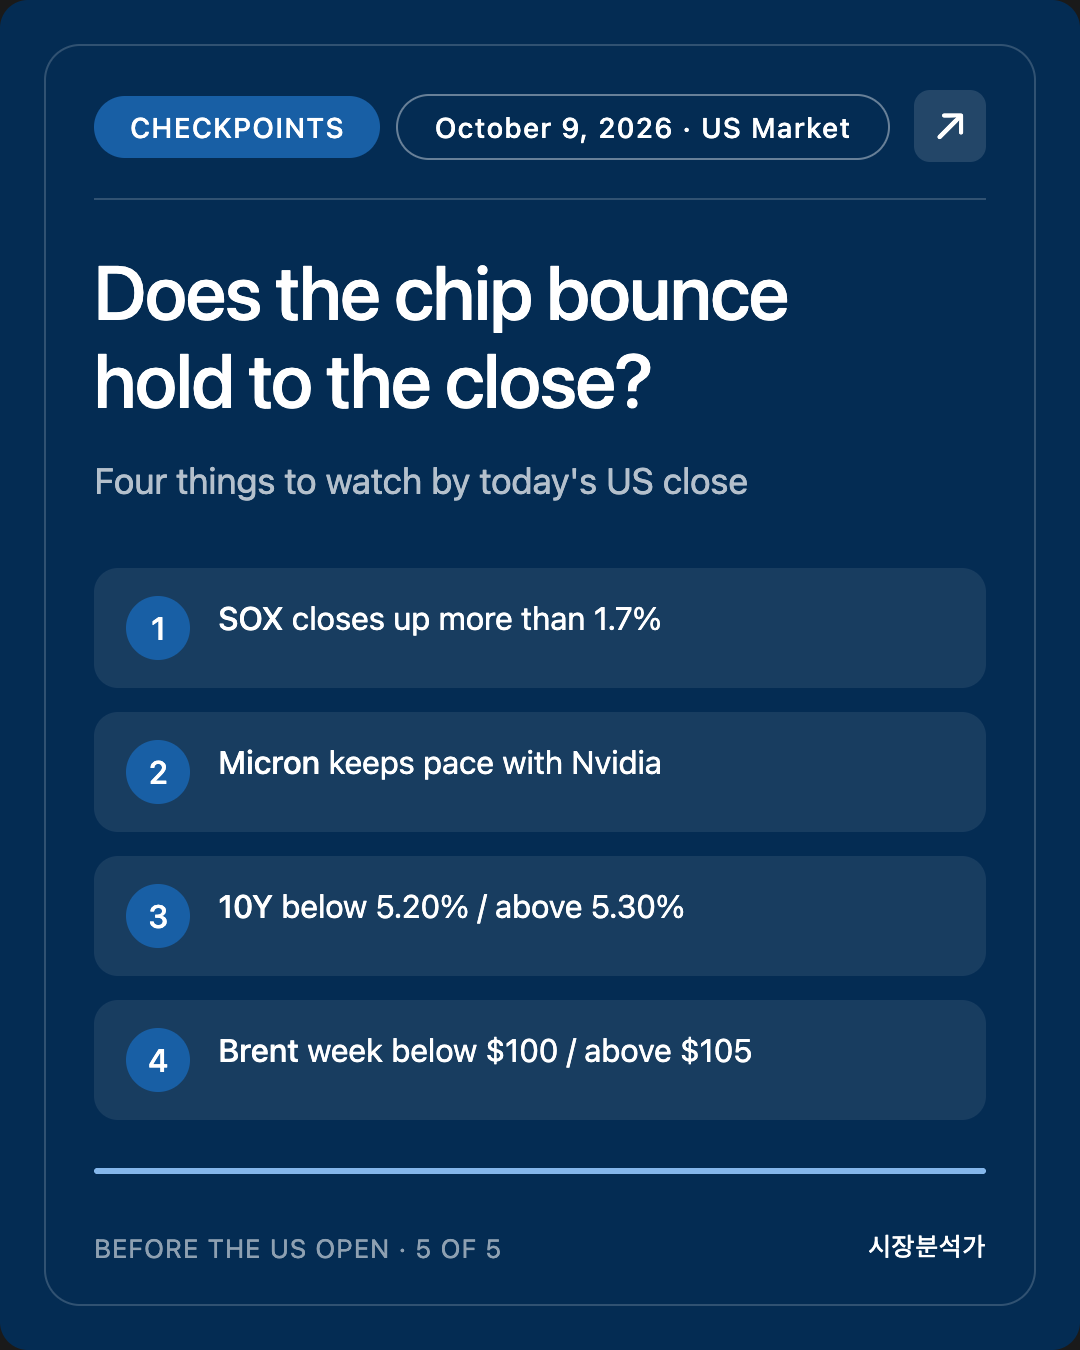
✅ Four checkpoints (by today's US close)
The axis: was Thursday's chip drop an overreaction to an accounting mismatch, or the start of re-pricing AI capex? There is also a third path we learned to watch for in September: chips rebound, but rates eat the rebound. Item 3 guards that path.
- Does the SOX close up more than 1.7% (half of Thursday's −3.39%)? Yes leans "overreaction"; a pre-market gain that fades intraday leans "re-pricing." (Most important)
- Does Micron keep pace with Nvidia? Micron fell 4.79% on Thursday, the most among the big chip names. If memory lags, Seoul carries more weight into Monday.
- 10-year close below 5.20% / above 5.30%. A Michigan one-year expectation above 4.8% points to the upper line.
- Brent weekly close below $100 / above $105. (Same lines as the 10/8 PM brief.)
[Interpretation] If item 1 is ✅ and the 10-year closes above 5.30%, that is the third path. Next week, Korean chips would then be under two hands at once, rates and AI demand, rather than one or the other.
6. Study note: why we treat pre-market numbers as an interim read only
Concept. Pre-market trading happens before the regular US session (09:30–16:00 ET). It is the same stocks, but with far fewer participants and a fraction of regular-session volume, so small orders can move prices a lot. Index futures trade almost around the clock and are deeper, but they are still not a substitute for the regular session.
Analogy. It is like ranking marathon runners by how they look while warming up. The runner who looks sharp often does lead, but the warm-up is not the finish line.
Real cases.
- 10/8 AM: we read Micron's pre-market weakness as a rates-and-Taiwan story. Most of its −4.79% close came from the OpenAI report that hit in the afternoon (corrected in the 10/8 PM brief).
- So today's SOXX +1.9% is marked 🟡 here; ✅ or ❌ waits for the close.
One line. Pre-market gives a hint about direction; the close gives the verdict. That is especially true on days with a scheduled release mid-morning, like today's Michigan data.
7. Corrections and open items
Corrections
- None. (No new errors found since the 10/8 PM brief.)
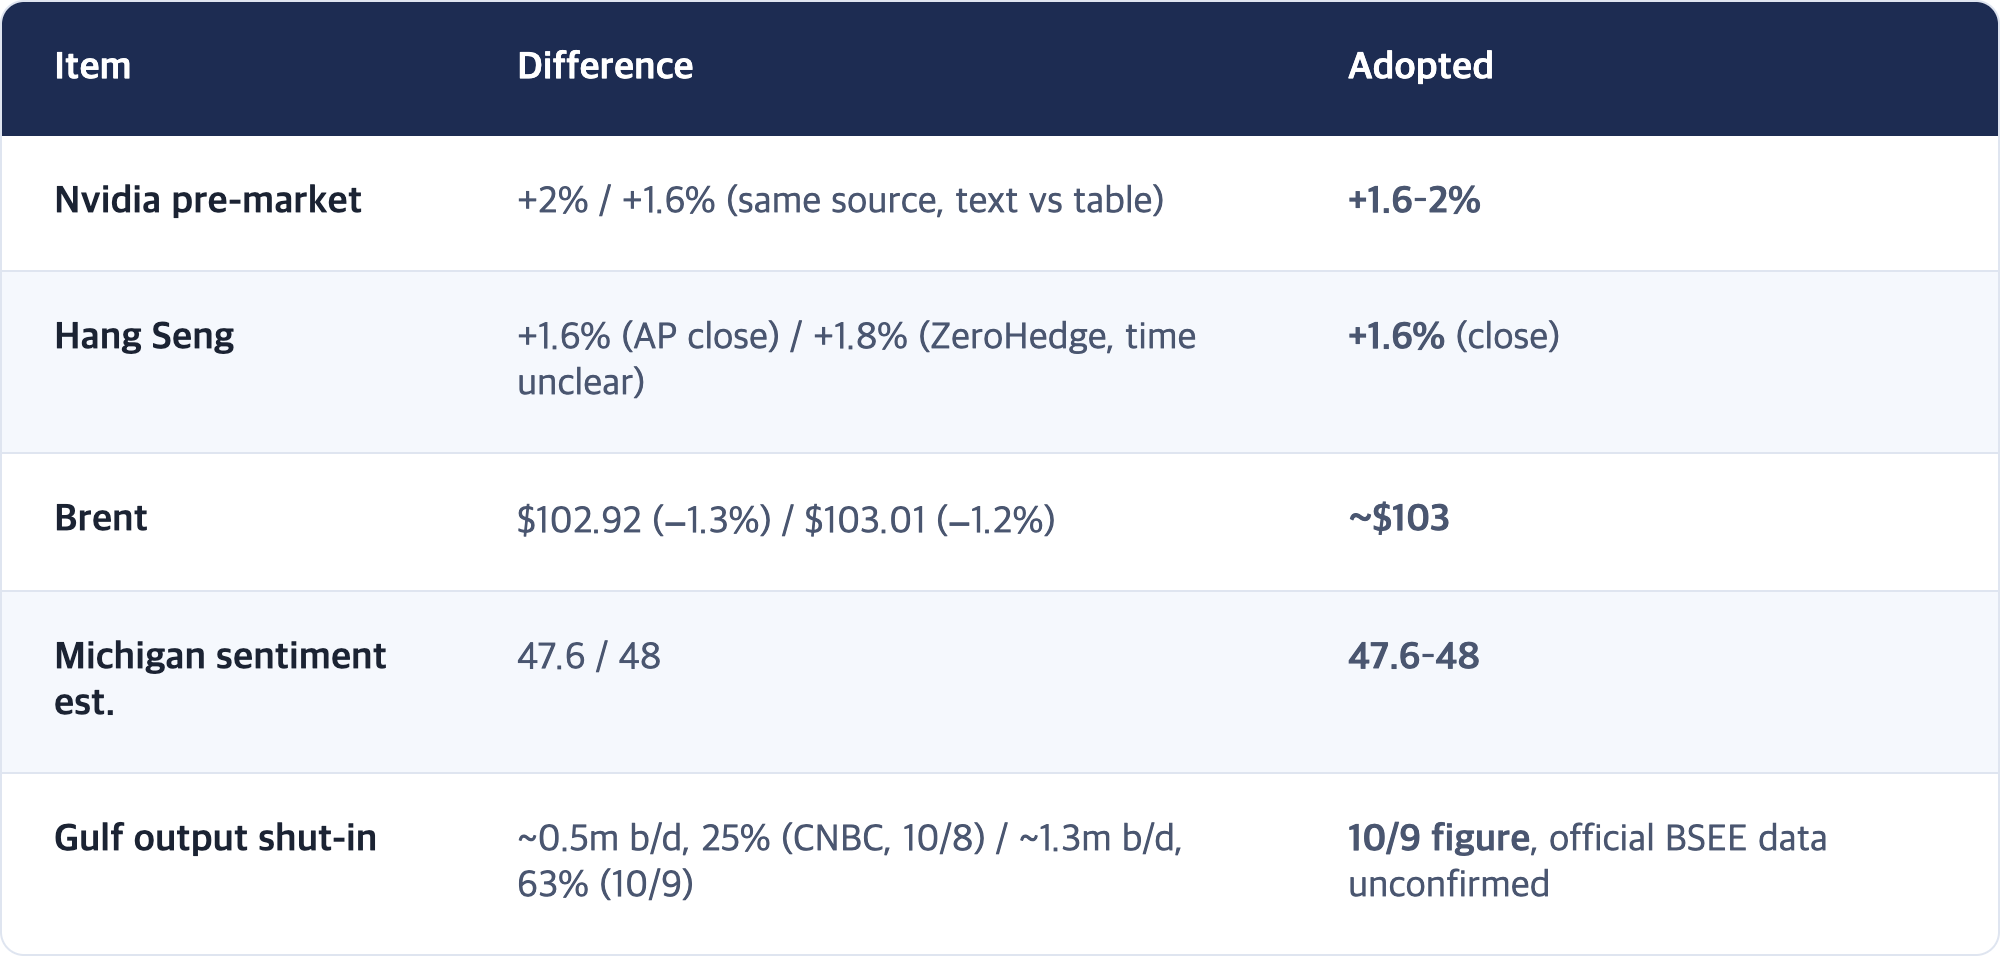
Source differences (adopted value in bold)
🔲 Unconfirmed
Shanghai Composite closing level · STOXX 600 / DAX closes · SOX index level (10/8) · Micron pre-market · US 2-year · single-source CME probabilities · USD/KRW during the Korean holiday · Korean 10-year government bond yield.
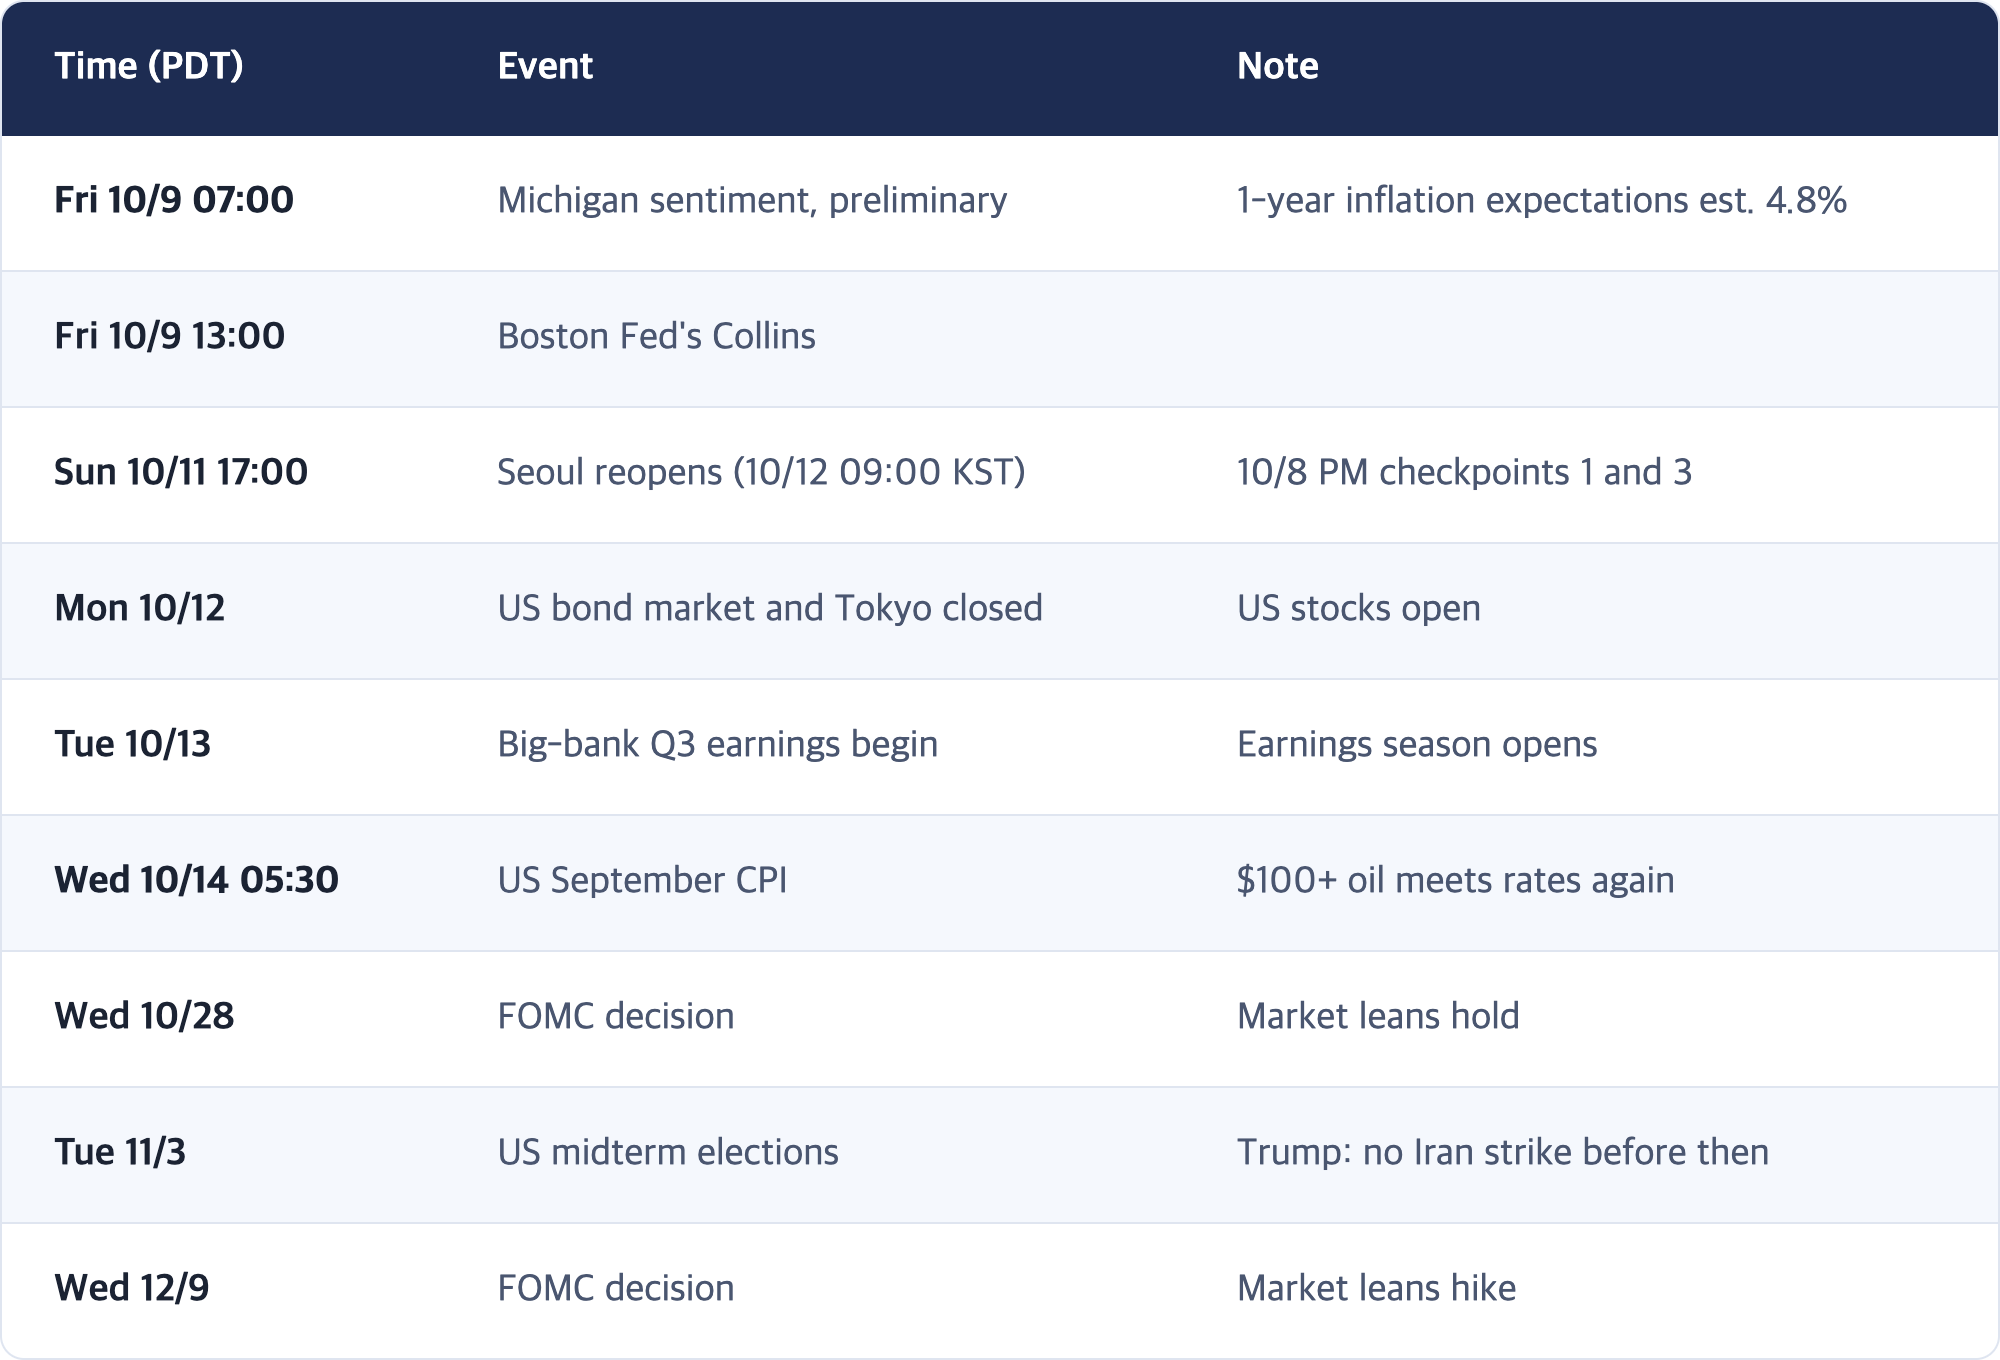
8. Event calendar (PDT)
Sources
- Stock market today: Dow, S&P 500, Nasdaq futures rise as oil prices fall, tech recovers | Yahoo Finance
- Futures Rise After OpenAI Damage Control Sparks Tech Rebound, Oil Slides | ZeroHedge
- World shares are mostly higher and crude prices fall after an unsettled day on Wall St | AP via KSAT
- Stock Market Today: Dow, S&P Live Updates for October 9 | Bloomberg
- European Shares Surge After Trump Comments On Iran Talks | finanzen.at
- Equities: AI concerns pressure stocks as futures rise | FXStreet (Deutsche Bank)
Market Analyst · This brief does not recommend buying or selling any individual security. It offers macro context and interpretation only.
📌 More market briefs
※ This post is market observation and organization intended to support your own judgment. It is not a recommendation to buy or sell any security. Figures are as of the time of writing and may differ between sources.
If this was useful, bookmark it or pass it along. It genuinely helps me write the next one.
I can survive. We can survive.