Oct 23, 2026 KOSPI Market Brief — What to Watch Before the Korean Open
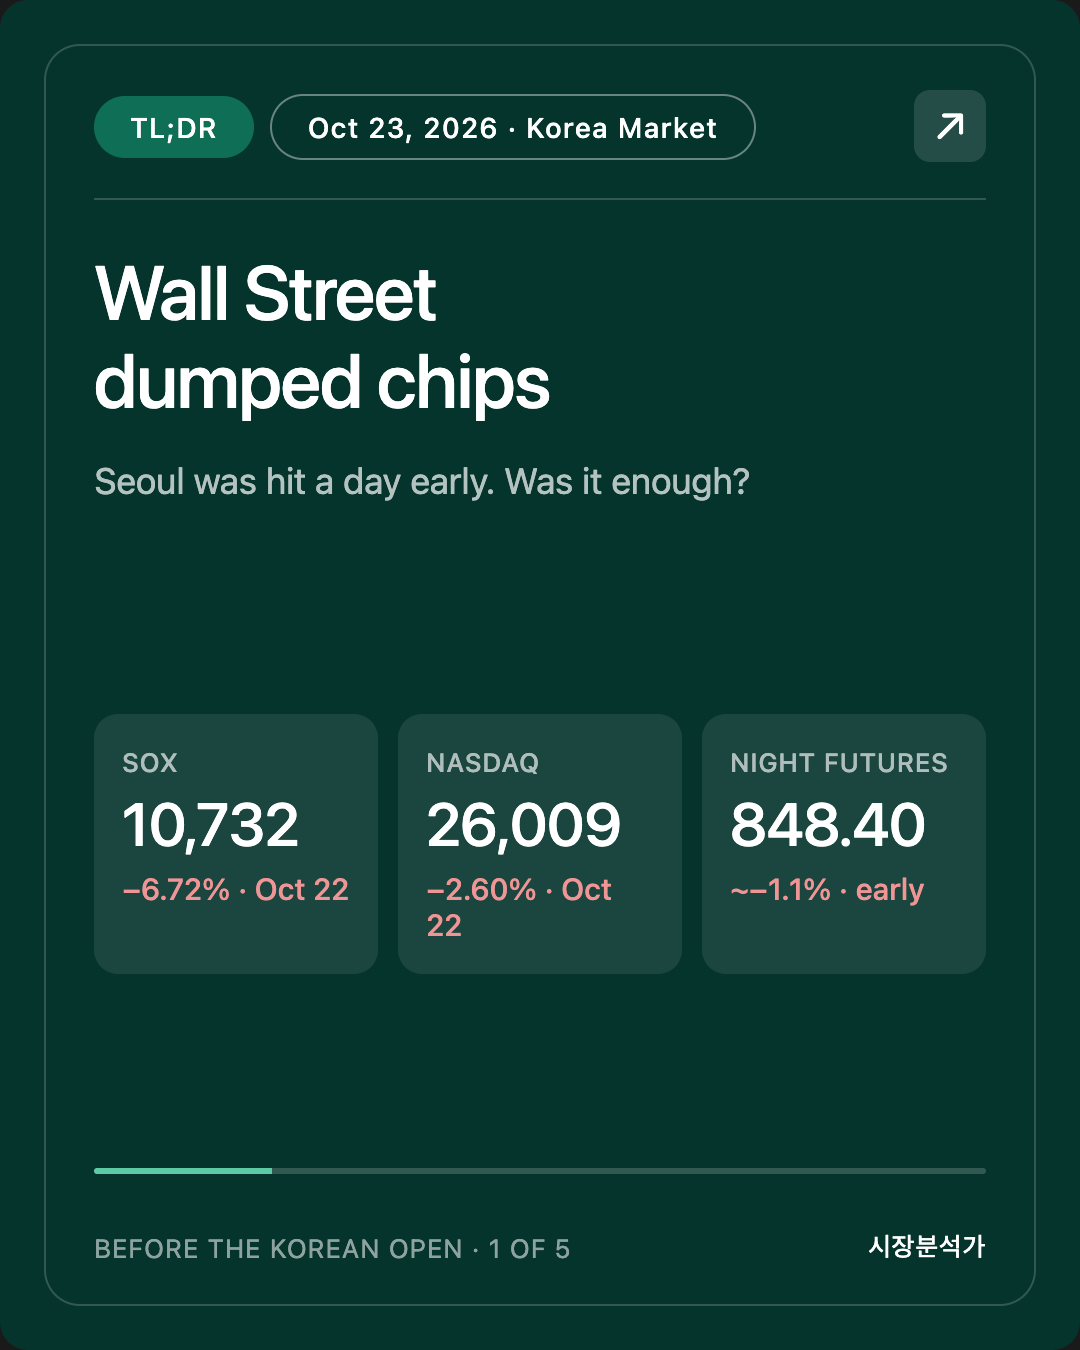
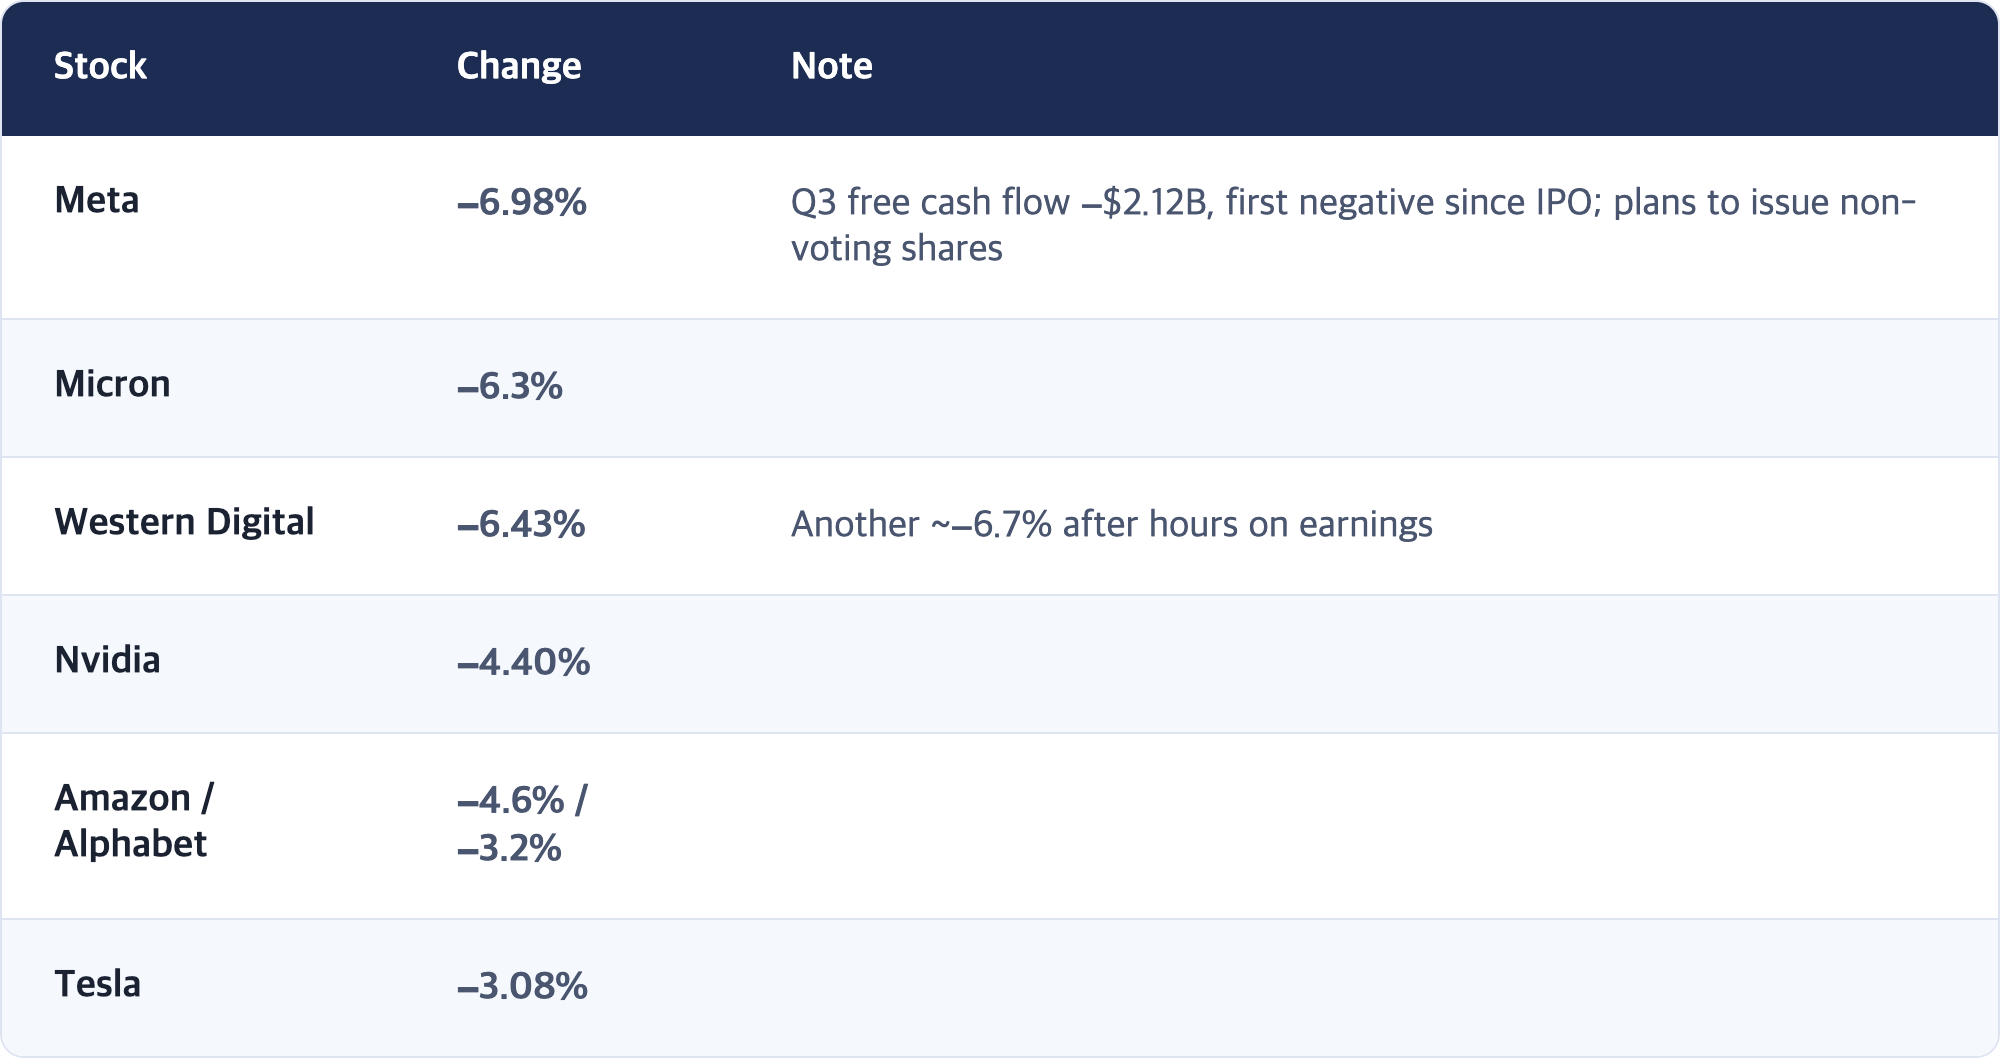
- ★ Wall Street dumped chips. SOX −6.72%, Micron −6.3%, Nvidia −4.40%, Western Digital −6.43%. Nasdaq −2.60% (worst since June), S&P 500 −1.21%.
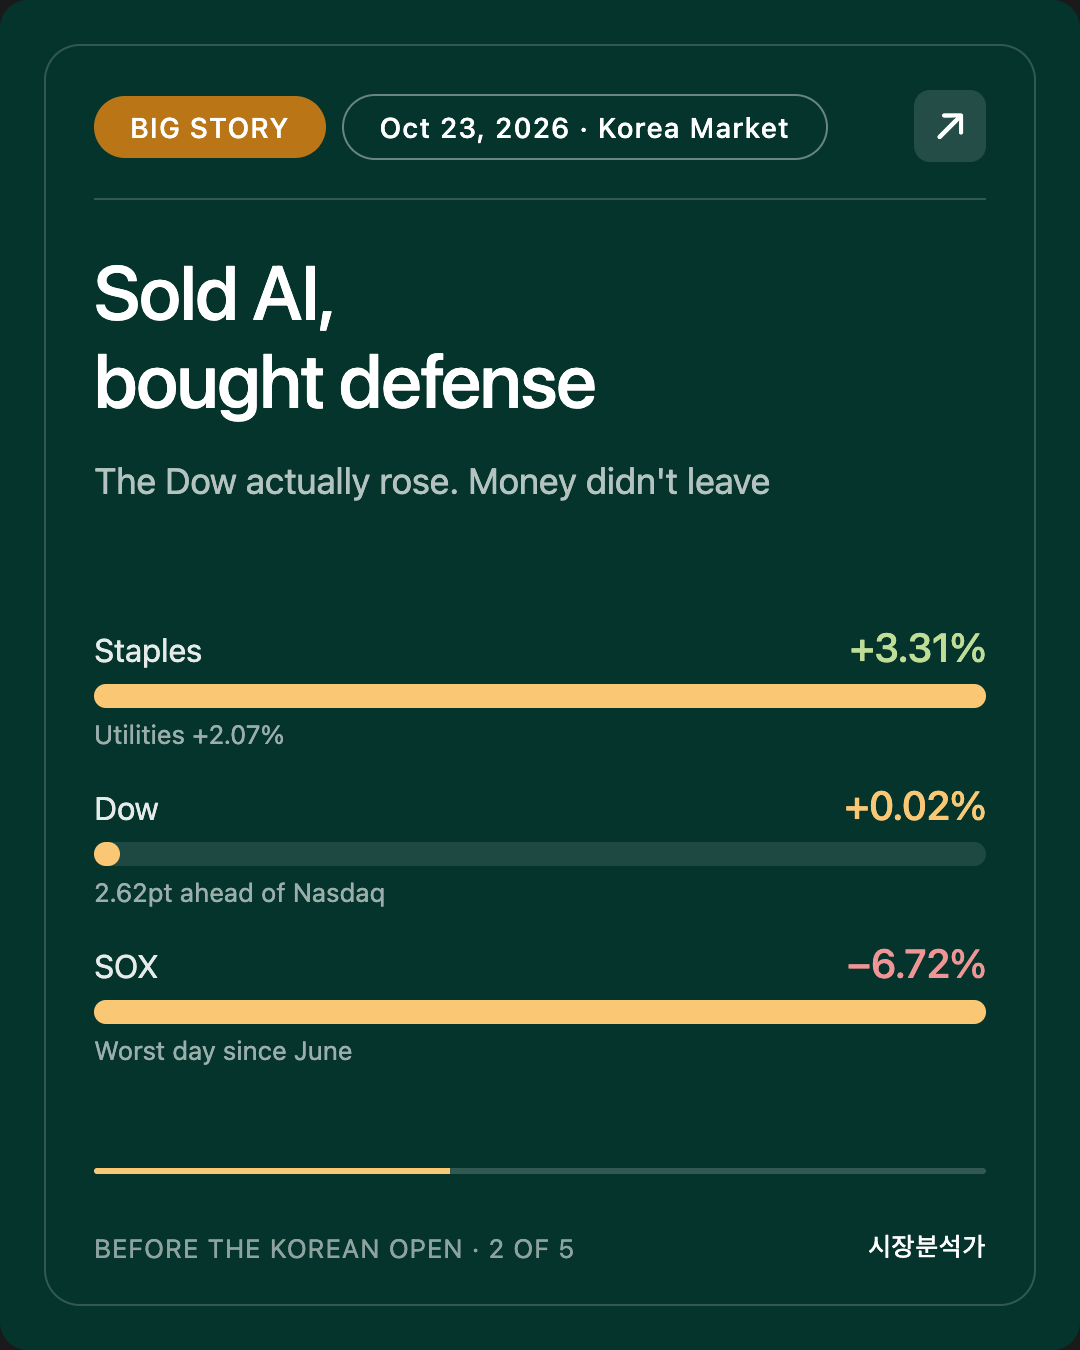
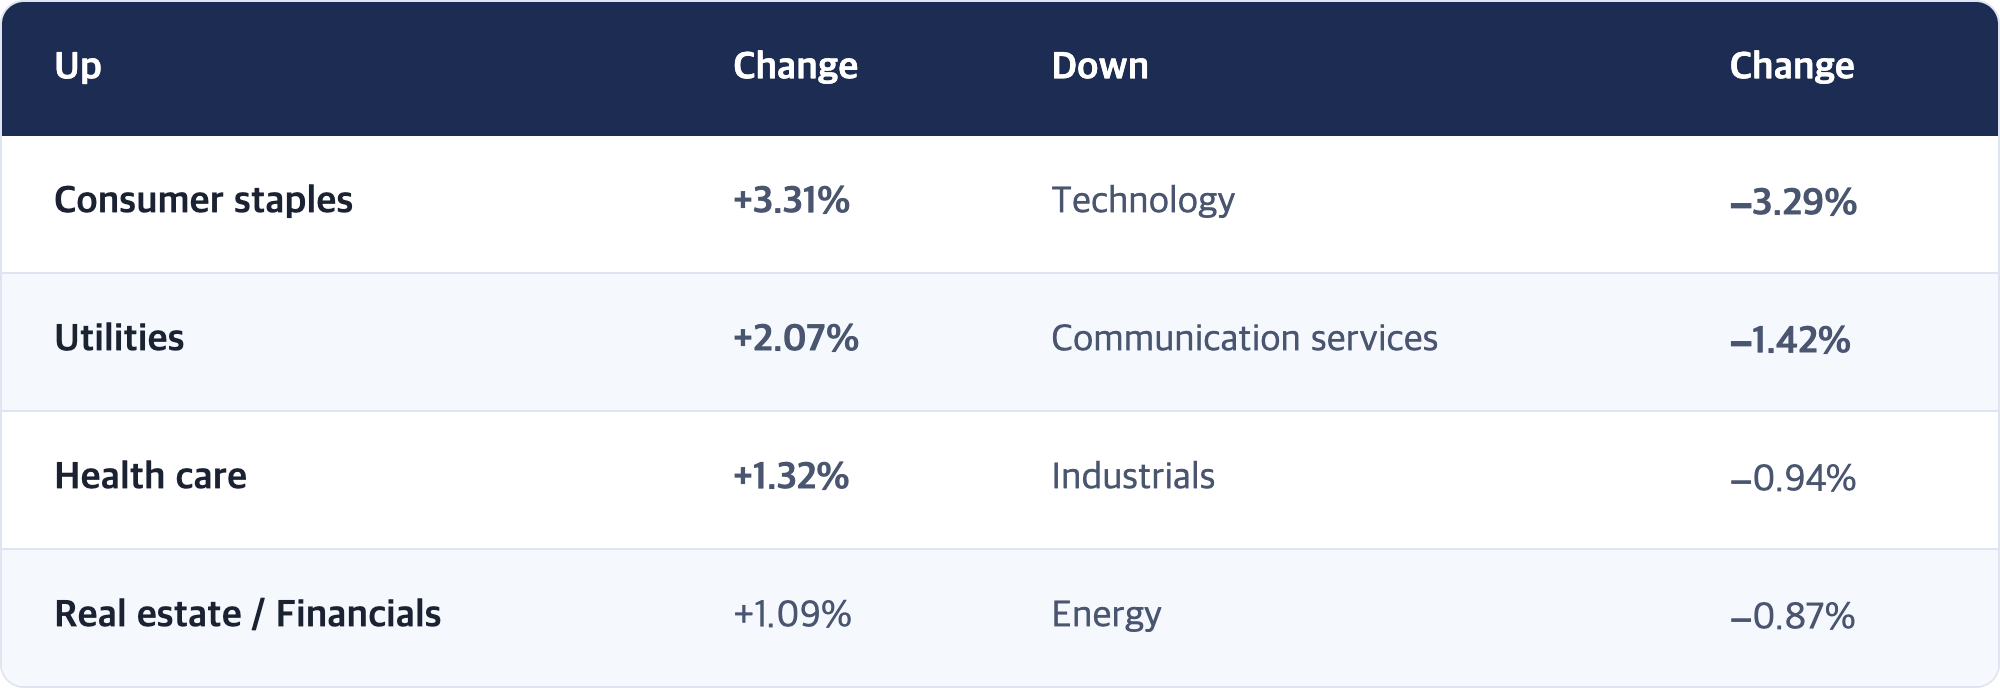
- ★ But the Dow closed higher (+0.02%). Staples +3.31%, utilities +2.07%, health care +1.32%; tech −3.29%. Money rotated out of AI rather than leaving the market.
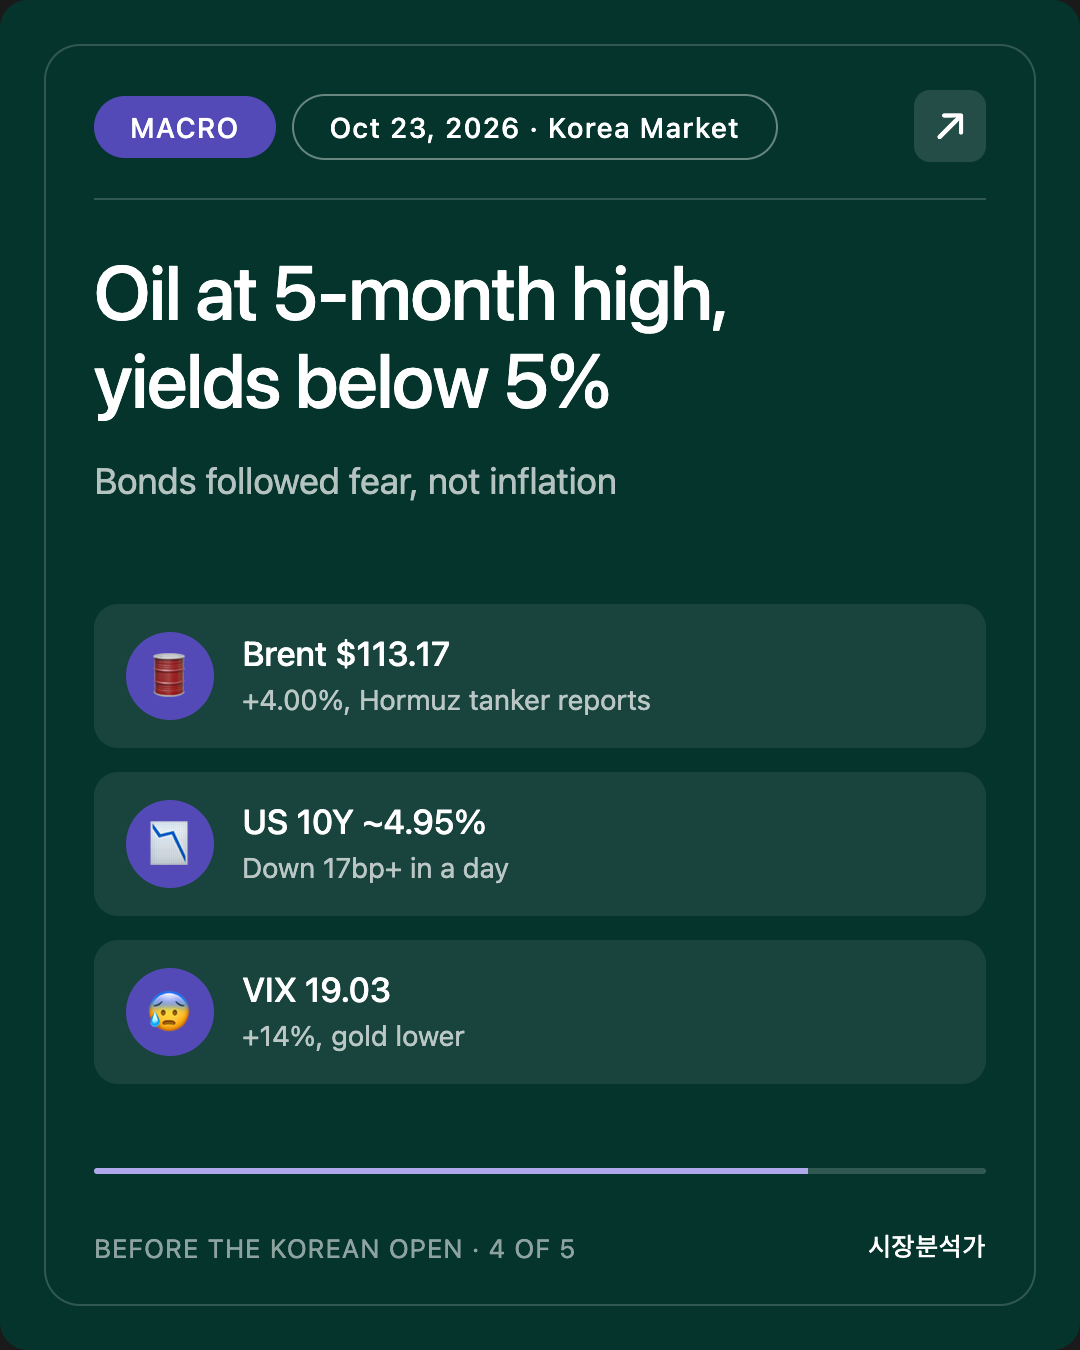
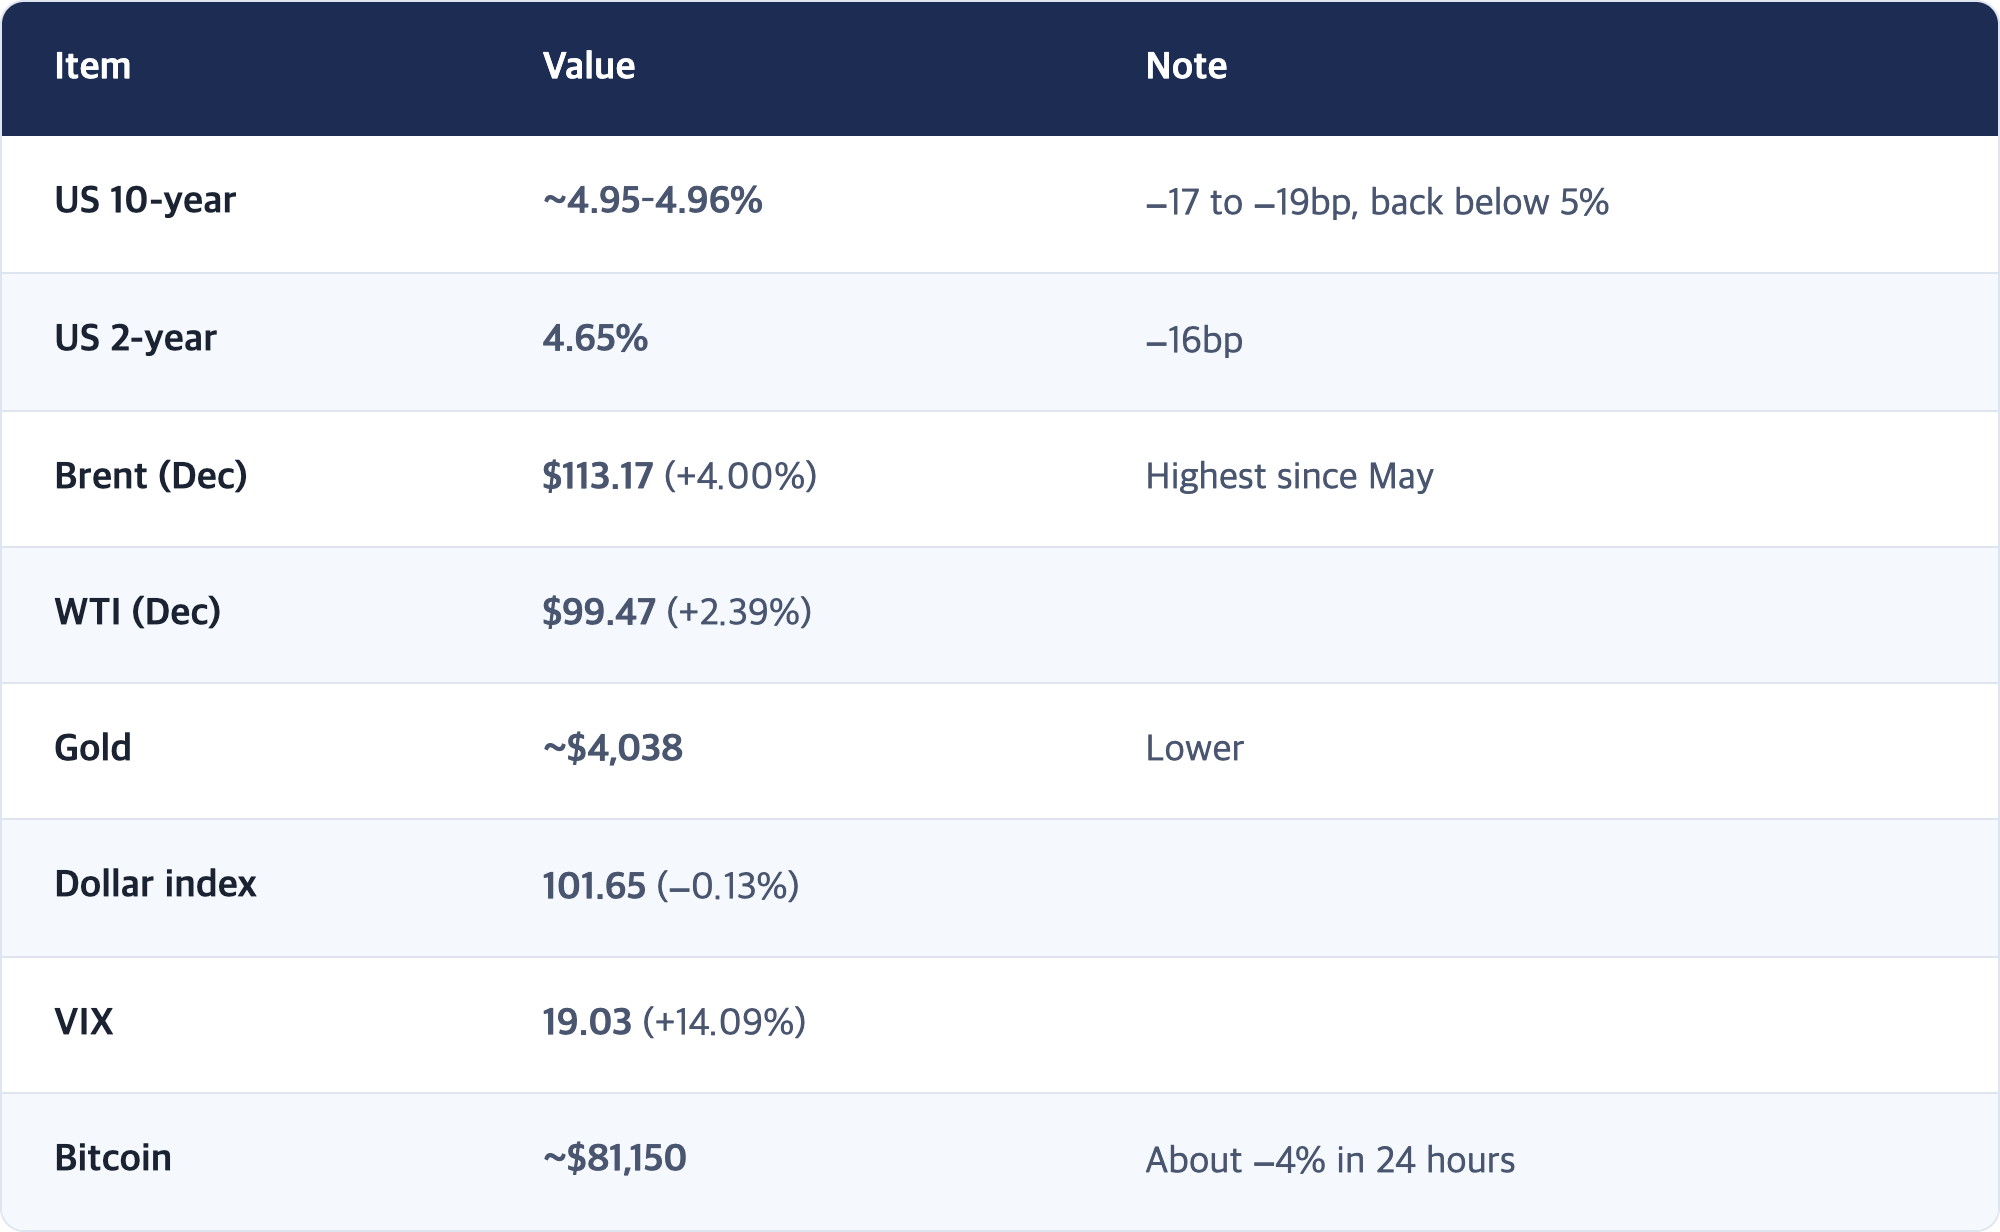
- ★ Oil hit a five-month high while yields fell hard. Brent $113.17 (+4.00%), US 10-year ~4.95–4.96% (−17 to −19bp), 2-year 4.65%. VIX 19.03 (+14%).
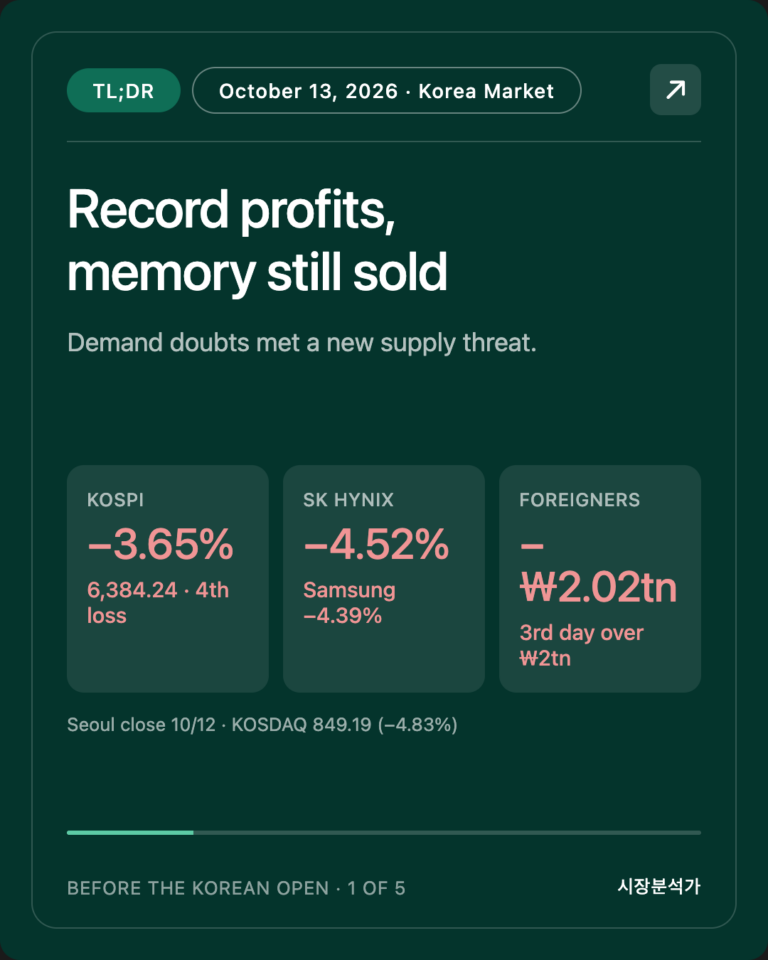
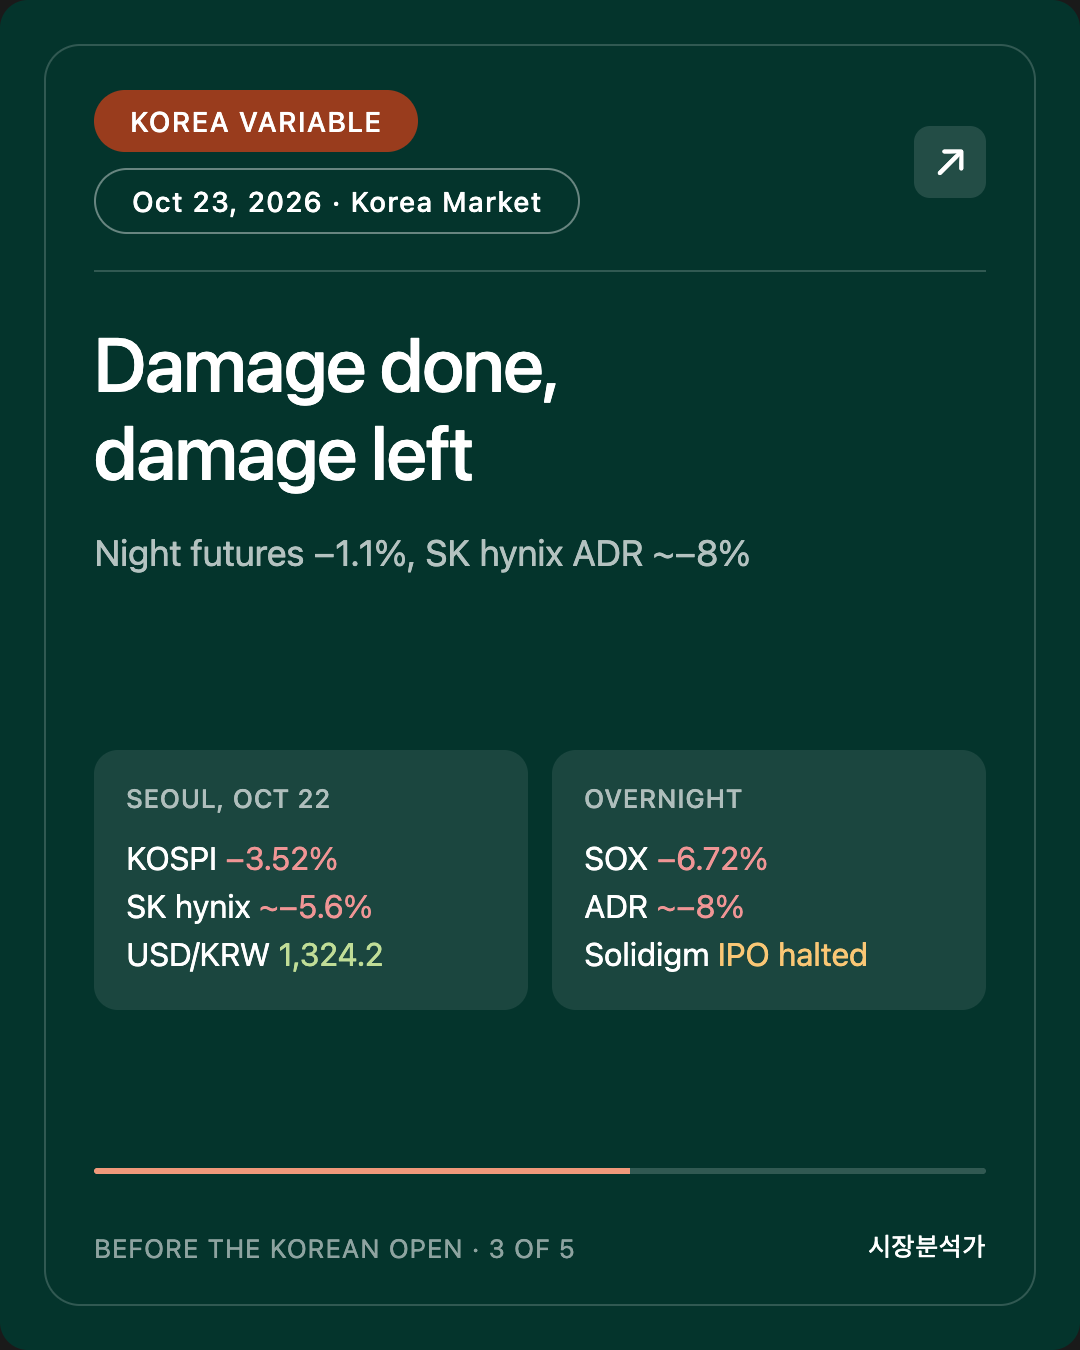
- Seoul flinched first. KOSPI closed Oct 22 at 5,533.77 (−3.52%). KOSPI 200 December night futures traded at 848.40 early, about −1.1% from the 858.02 cash close. SK hynix ADR about −8% (single source).
- Two Korea-specific items. SK hynix said it has halted IPO plans for its US subsidiary Solidigm. The won strengthened for a fifth straight day to 1,324.2 per dollar.
This is Mr. Can. Here is the Oct 23, 2026 brief ahead of the Korean market open.
Written: Oct 23, 2026 09:45 KST (Vancouver Oct 22, 17:45 PDT) · Work began 08:16 KST (16:16 PDT)
Basis: US close on Thu Oct 22 + after-hours earnings + KOSPI 200 night futures (early Oct 23) + Seoul close on Oct 22
🔴 Scheduled for 16:00 PDT; work started at 16:16 PDT and finished after the Korean open (09:00 KST). The body reflects pre-open information only.
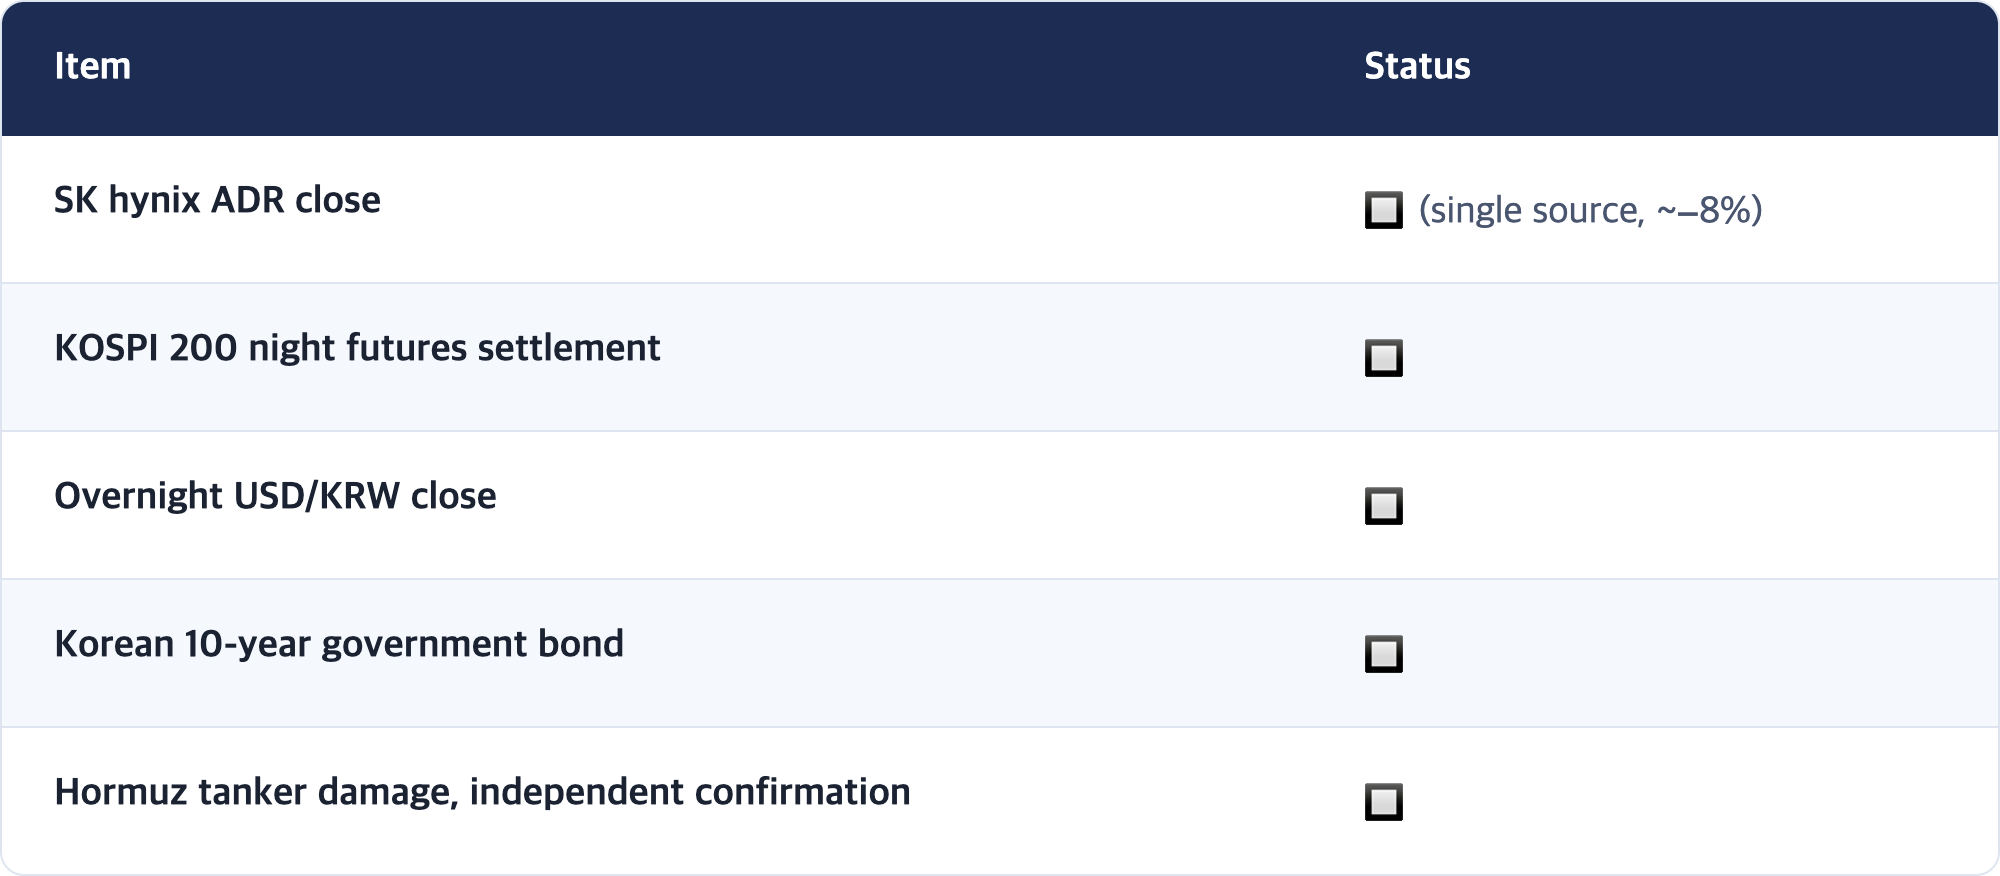
🟡 The SK hynix ADR move comes from a single source (about −8%), and the KOSPI 200 night futures figure is an early-morning snapshot, not a settlement. Korean 10-year government bond yields and the overnight USD/KRW close were not available.
SEO Intro
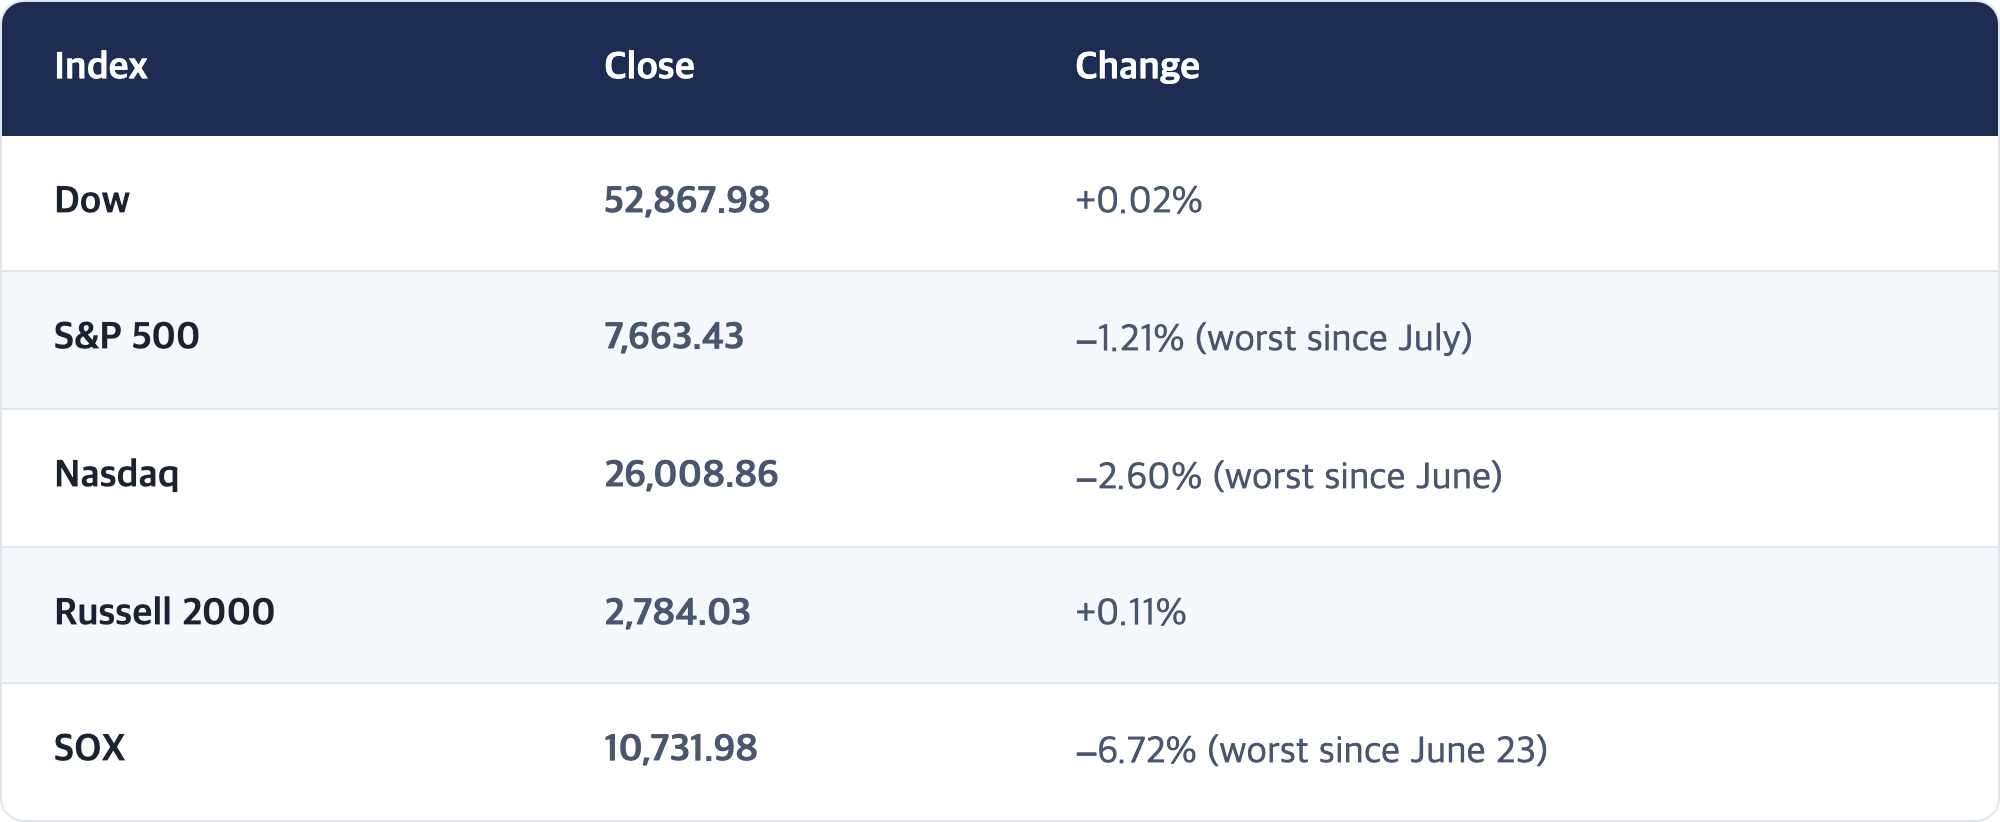
Wall Street dumped chip stocks on Thursday. The Philadelphia Semiconductor Index (SOX) fell 6.72% to 10,731.98, its worst day since June, and the Nasdaq dropped 2.60% to 26,008.86. Yet the Dow edged up 0.02% to 52,867.98, while consumer staples (+3.31%) and utilities (+2.07%) rallied. Investors weren't fleeing stocks. They were moving out of AI and into defense.
The trigger was Meta. Revenue beat, but third-quarter free cash flow turned negative (−$2.1 billion) for the first time since its IPO, and the stock fell 6.98%. Brent crude jumped 4.00% to $113.17, its highest since May, on reports of tankers hit in the Strait of Hormuz and Houthi attacks on Saudi Arabia. Even so, the US 10-year yield fell 17–19 basis points to roughly 4.95–4.96%. Fear beat inflation worries.
Seoul took its hit a day early: the KOSPI fell 3.52% on Wednesday. Today's question for Korea: how much of Wall Street's 6.7% chip rout did Seoul already price in? KOSPI 200 night futures were down only about 1.1% in early trading.
1. Scoring Yesterday's Checkpoints
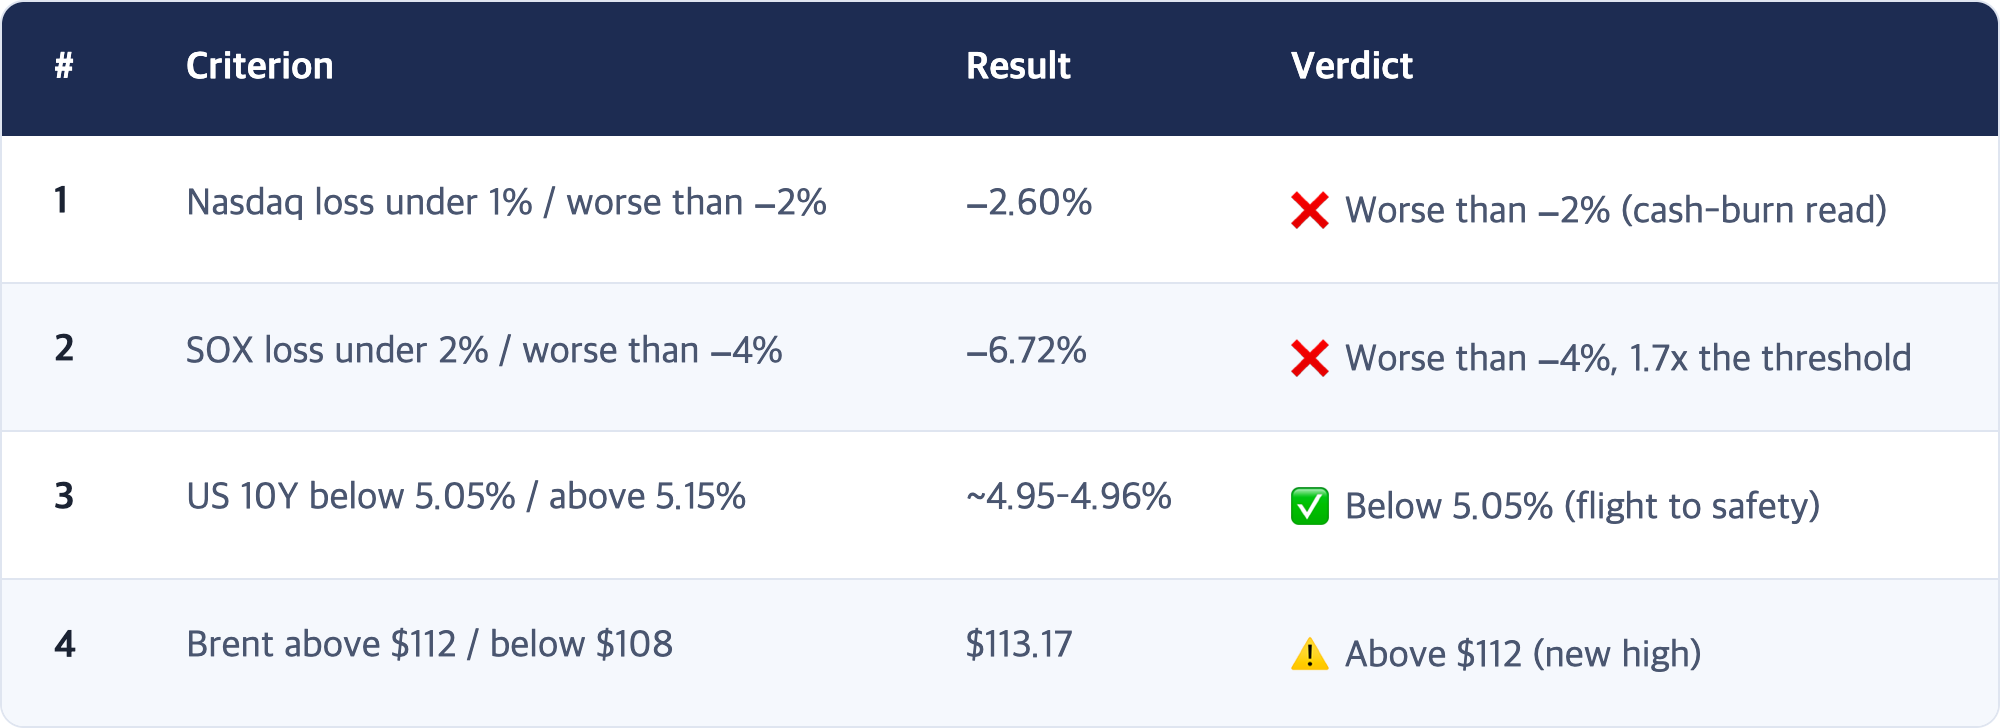
The four set in the Oct 22 AM brief (US close, Oct 22)
The frame was: does the market read Meta's spending as "growth" or as "cash burn"? A slot was left open for a third variable: new Iran headlines.
★ [Interpretation] Both scenarios arrived at once
The AM brief sketched two paths: a selloff with falling yields meant a flight from tech into bonds; Brent above $112 with rising yields meant oil taking control. The flight-to-safety path played out exactly, and oil also broke to a new high, but yields fell instead of following crude. The third variable did show up: Iranian state TV said seven tankers were damaged in the Strait of Hormuz, which President Trump dismissed as "fake hits." Bond traders treated it as a risk-off signal, not an inflation signal.
2. The Big Story: Wall Street Trimmed AI and Bought Defense
[Fact] US close, Thursday Oct 22
[Fact] Sectors (S&P 500)
[Fact] Notable stocks
★ [Interpretation] The third rotation this week, and the biggest
- Monday and Tuesday also saw investors sell AI and buy the Dow. Wednesday broke the pattern; Thursday brought it back much larger. The Dow beat the Nasdaq by 2.62 percentage points.
- This time the reason was clear. Meta showed the buyer's bank account: revenue grew 26%, but capital spending outran operating cash, and the company plans to issue new shares to help pay for it. The market asked how long AI's biggest customers can keep buying at this pace, and the sellers of chips and storage were hit hardest.
- Staples rallying more than 3% is unusual. Money moved to safety rather than out of stocks. AI doubt has not yet become recession fear.
3. Korea Watch: Seoul Was Hit First. How Much Is Left?
[Fact] Seoul close, Thursday Oct 22
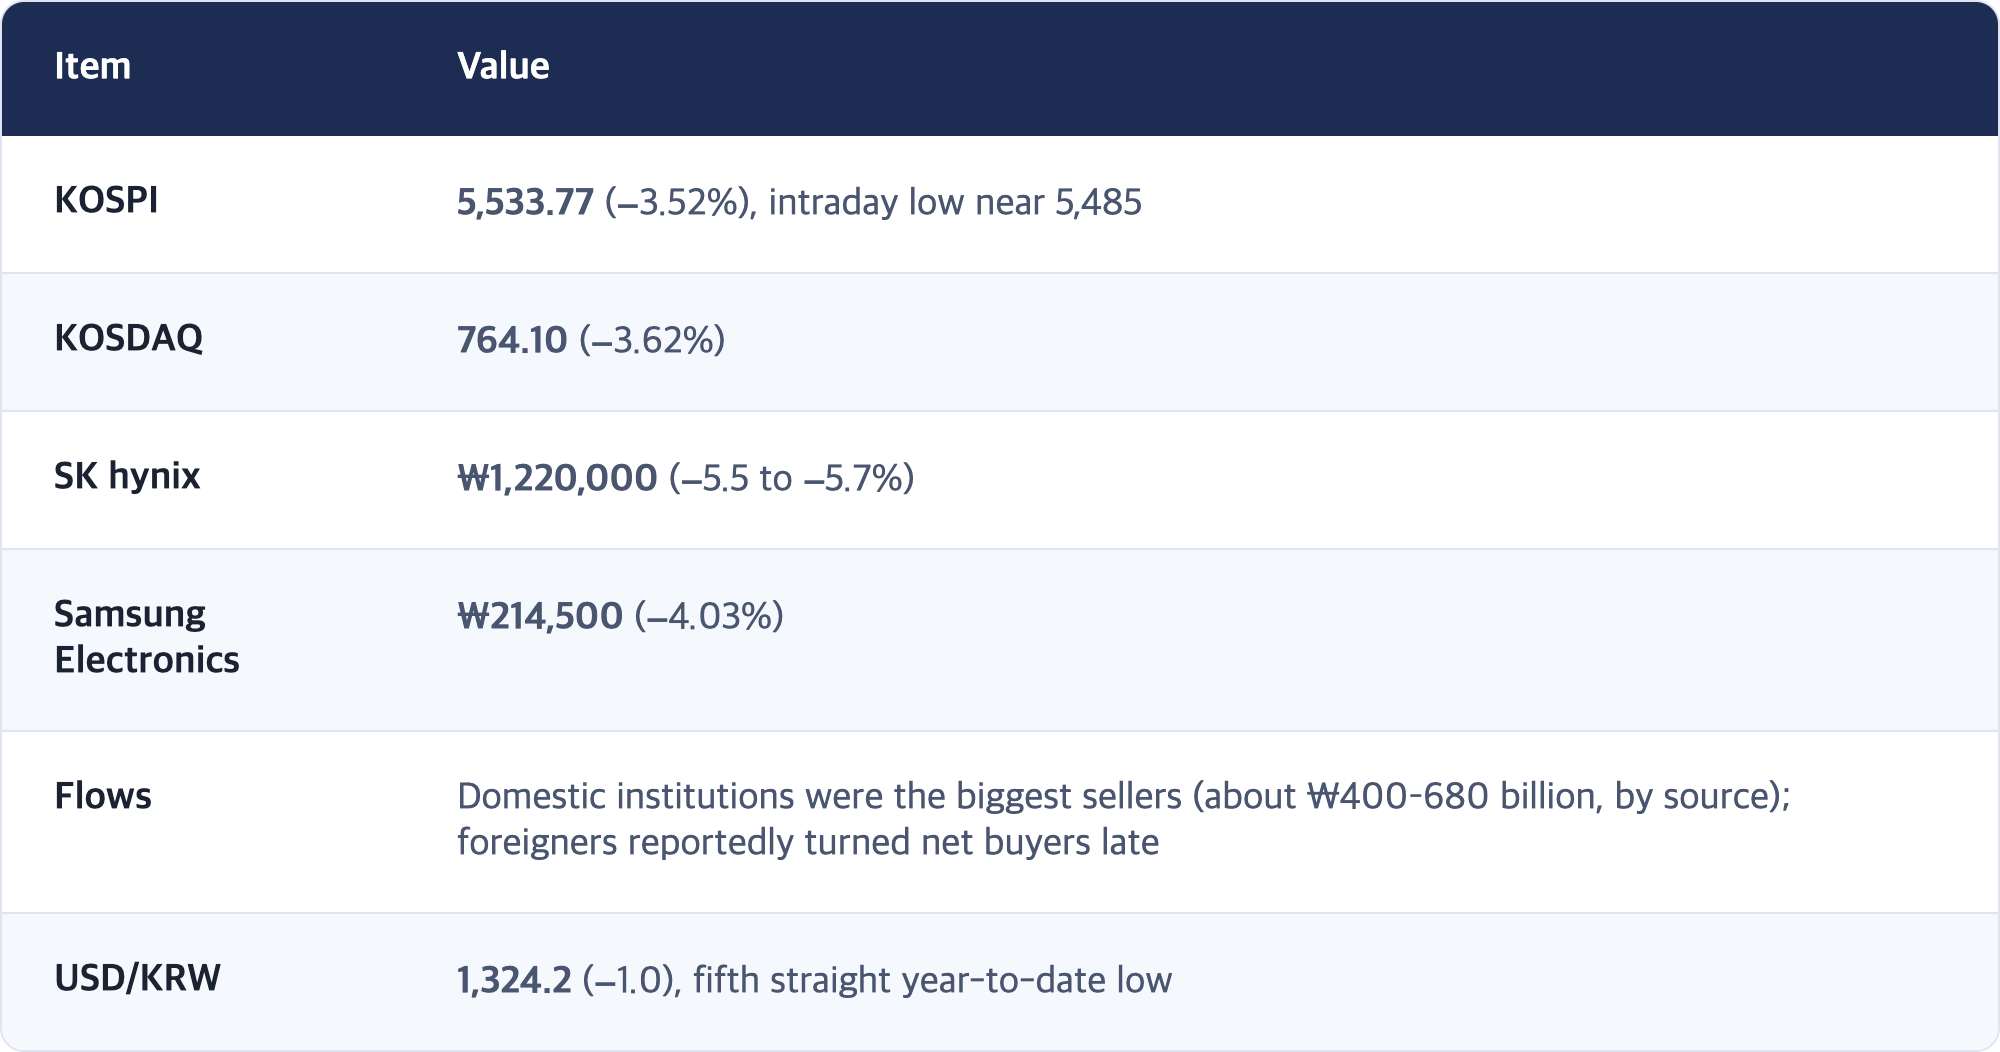
[Fact] Overnight Korea signals
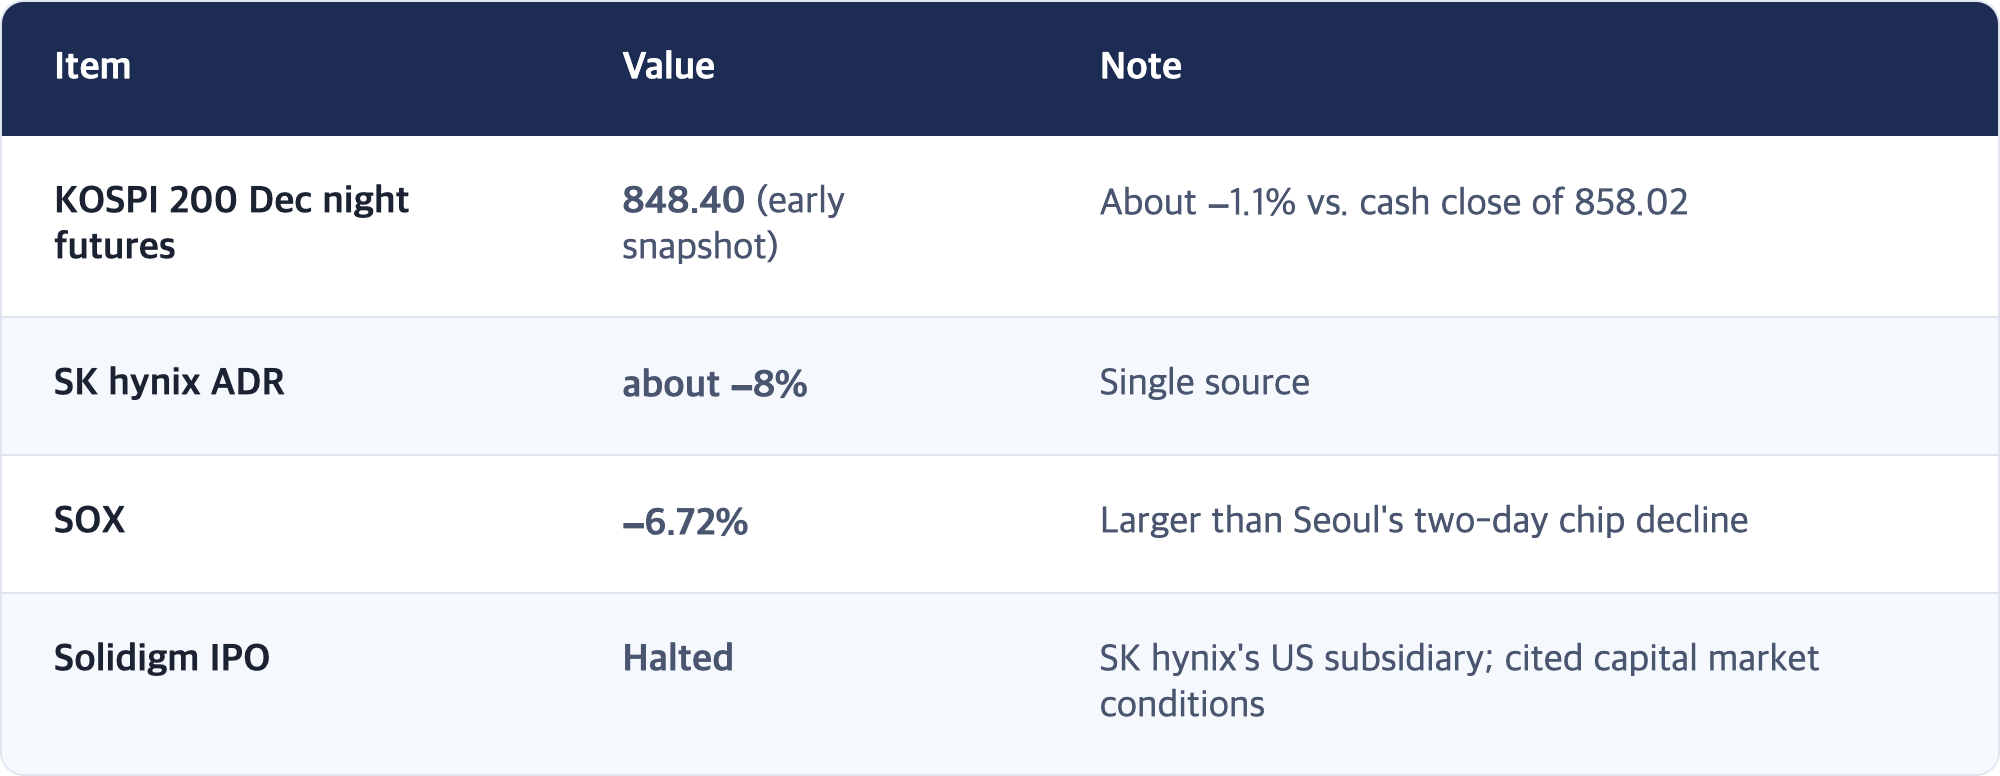
★ [Interpretation] Some of the damage is already done, some may remain
- A 1.1% dip in night futures is small next to a 6.7% SOX drop. The market thinks Seoul already absorbed much of the Meta news with Wednesday's 3.5% fall. Meta reported during Korea's early Wednesday morning; Seoul sold Thursday afternoon; New York sold Thursday night.
- But New York sold deeper. One day of SOX losses exceeds SK hynix's two-day drop, and the ADR fell about 8%. Large chipmakers may still have room to catch down.
- The Solidigm halt cuts both ways. It eases worries that a separate listing would dilute parent shareholders. But stopping because of "capital market conditions" is the Korean version of the same story: funding windows for AI are narrowing.
- The won stays strong. It firmed even as stocks fell 3.5%, helped by exporters selling dollars and the Bank of Korea's hawkish stance. If the won holds today, that supports the view that Wednesday's drop was domestic profit-taking more than foreign flight.
4. Macro Backdrop: Oil at a Five-Month High, Yields Sharply Lower
[Fact] Rates, FX, commodities (around the US close, Oct 22)
[Fact] What lifted oil
- Iranian state TV said seven tankers were damaged or set ablaze in the Strait of Hormuz; President Trump accused Iran of staging "fake hits" to raise prices. Not independently confirmed.
- Yemen's Houthis claimed attacks on Saudi targets including an Aramco facility; two people were reportedly killed at Dammam airport.
[Fact] US data
- Initial jobless claims fell to 194,000 (vs. 200,000 expected), a three-month low.
★ [Interpretation] Bonds followed fear, not inflation, for a second day
Oil rose 4% and jobless claims were strong, yet the 10-year fell more than 17bp. Bonds are being driven by where money leaving tech goes. For Korea, that's not all bad: a US 10-year below 5% gives emerging-market currencies and growth stocks room to breathe. The risk is the reverse: if Brent holds above $113 and the flight to safety fades, yields could start tracking oil higher again.
5. Today's Korean Session (Fri Oct 23): Checkpoints
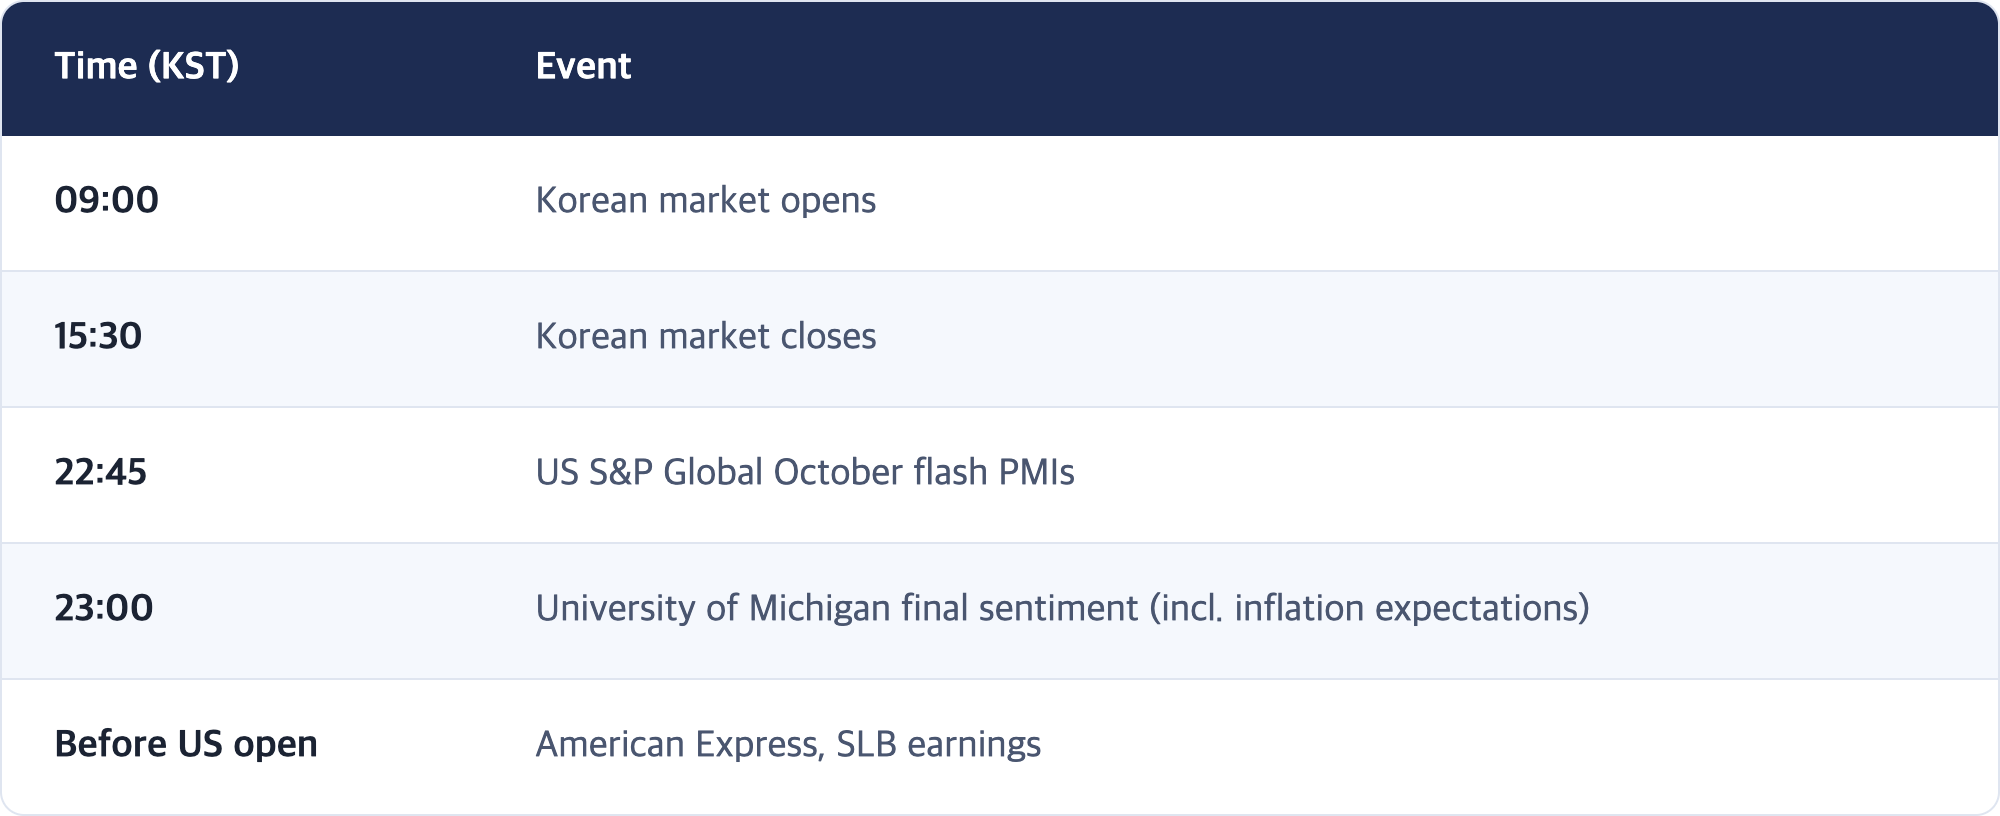
[Observation] Schedule (KST)
✅ Four checkpoints (by today's Korean close)
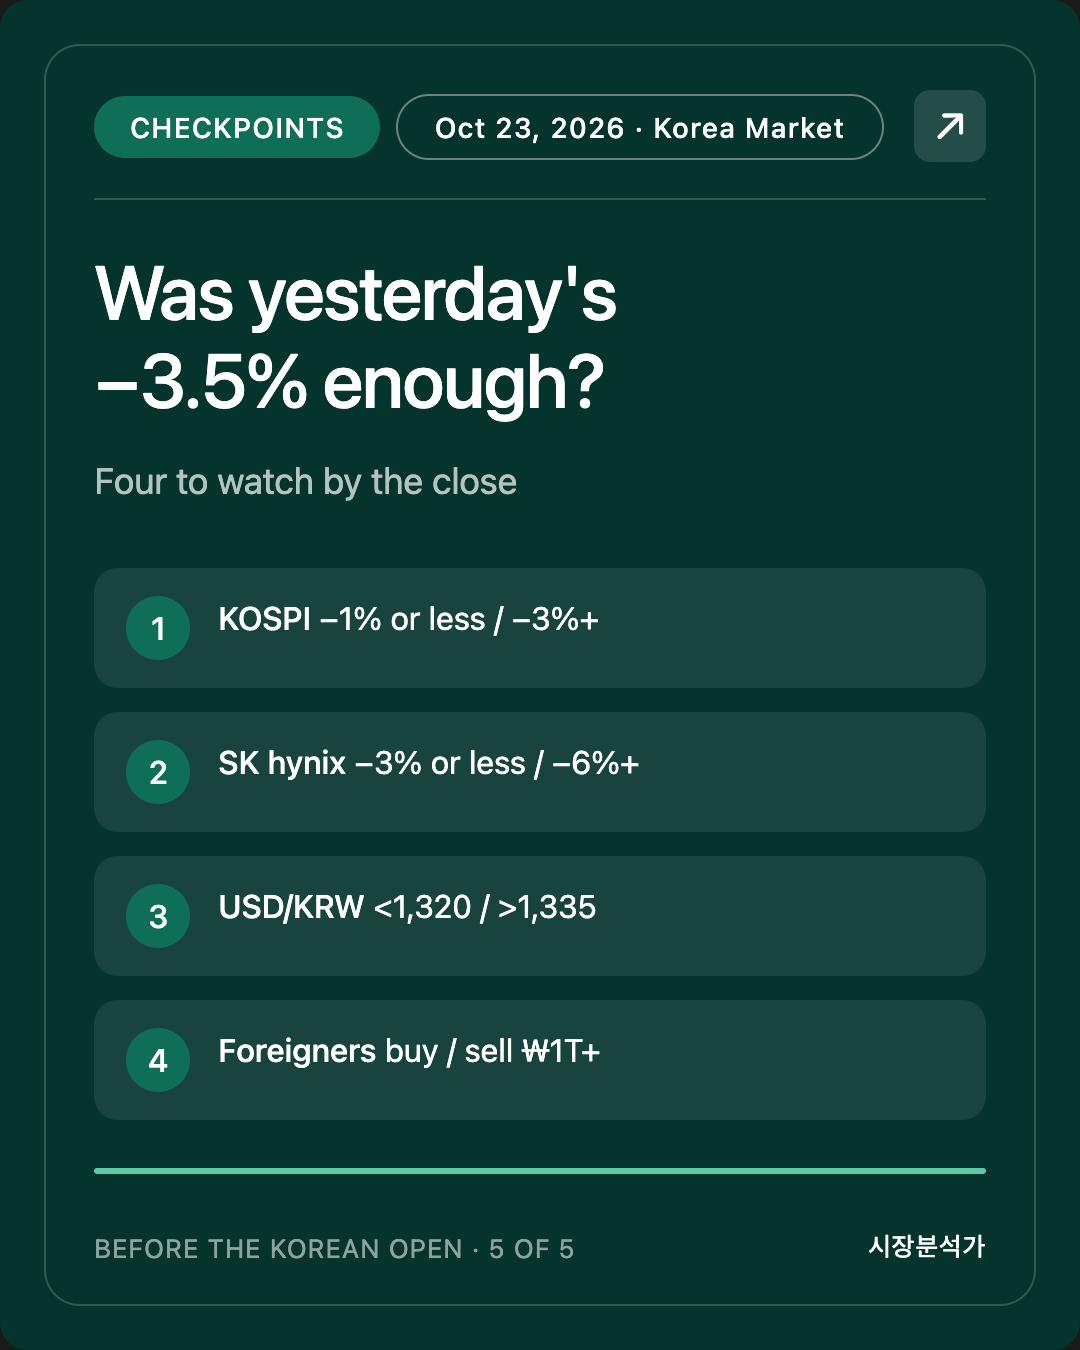
The frame: did Seoul's 3.5% drop already price in New York's 6.7% chip rout? The third-variable slot is left open for whether the Hormuz tanker reports hold up.
- KOSPI loss under 1% / worse than −3%. Near the −1.1% night futures means "priced in"; worse than −3% means much was left. (Most important)
- SK hynix loss under 3% / worse than −6%. How closely it tracks the ~8% ADR drop.
- USD/KRW below 1,320 / above 1,335. A sixth day of won strength, or a break on foreign outflows.
- Foreign investors net buyers / net sellers of more than ₩1 trillion on the KOSPI.
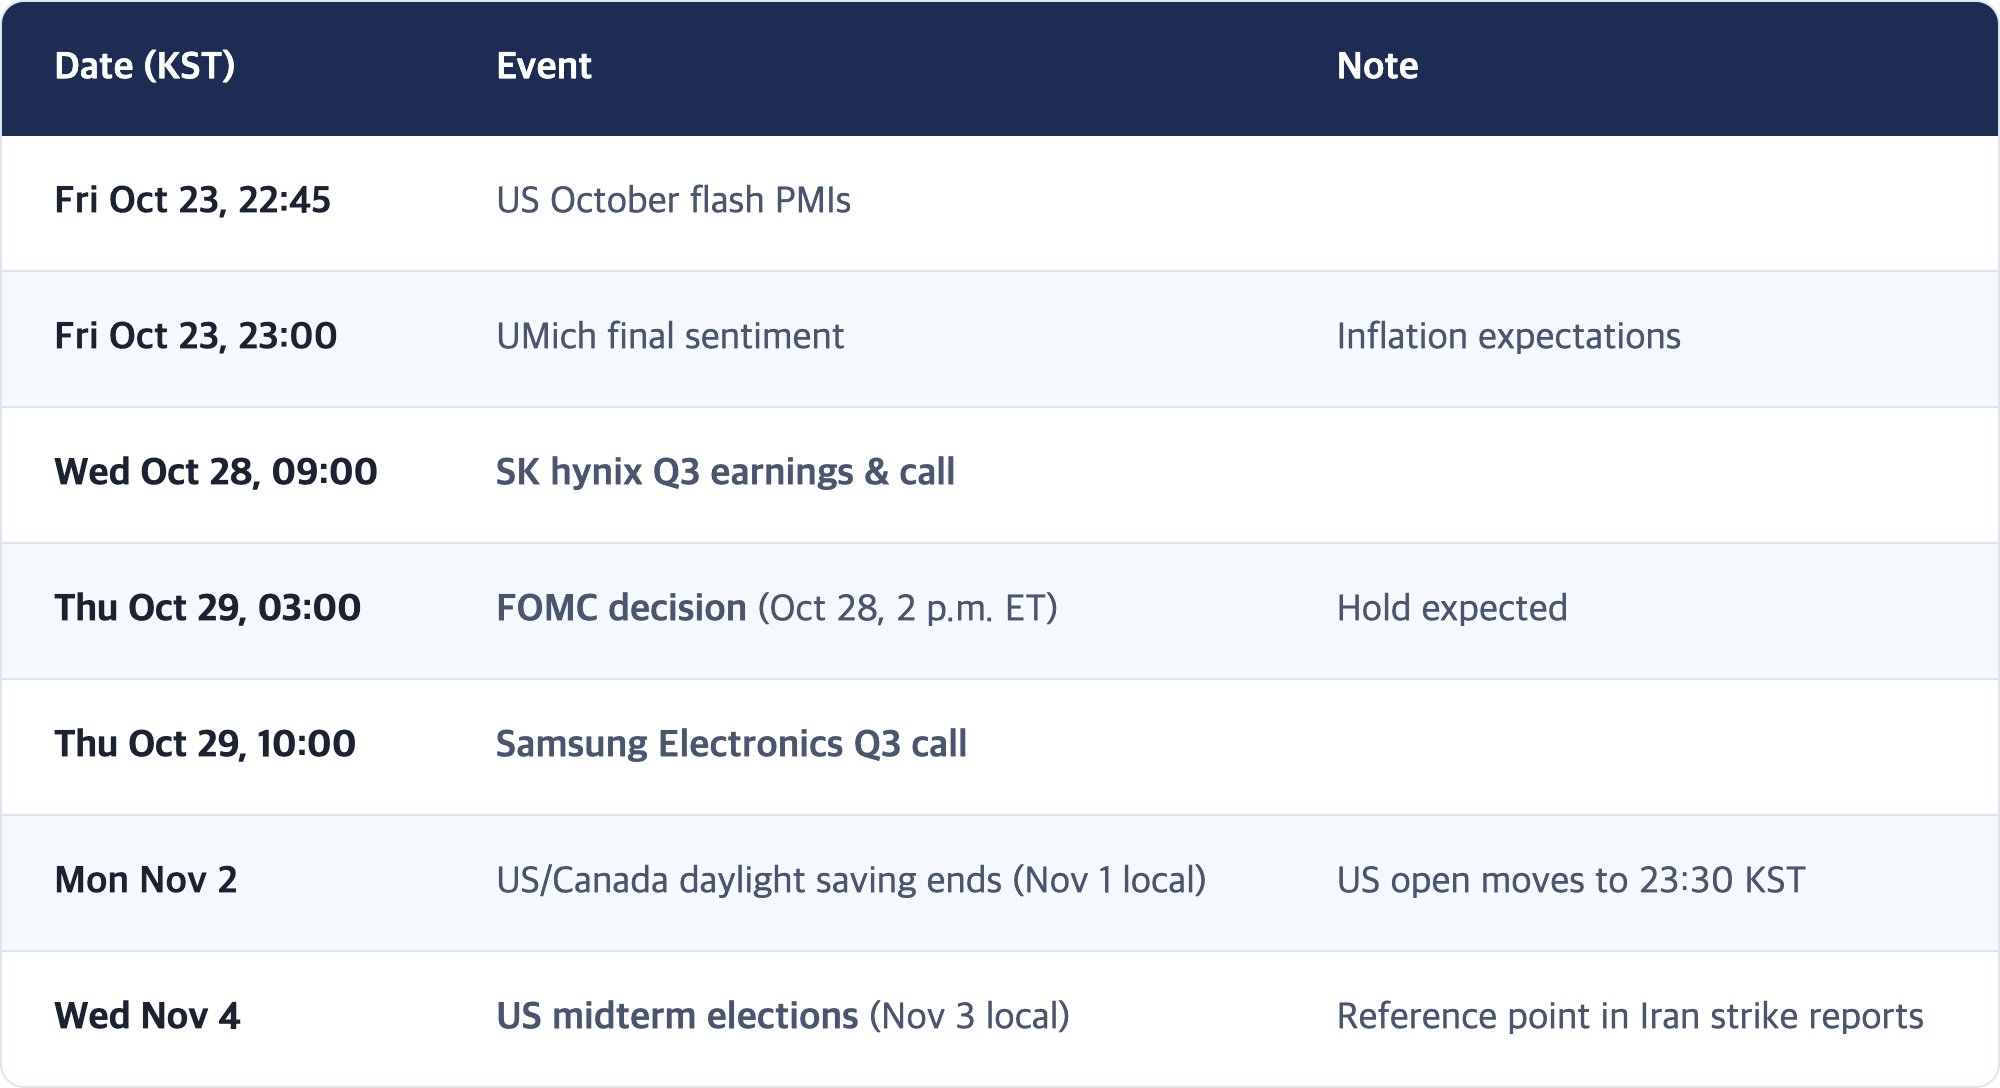
[Interpretation] If checkpoints 1 and 2 land on the mild side, Seoul's early flinch spared it today, and the focus shifts to SK hynix (Oct 28) and Samsung (Oct 29) earnings. If the KOSPI falls more than 3% and USD/KRW rises above 1,335, foreigners are leaving in earnest. Two straight days of 3%+ losses could force leveraged retail positions to unwind, which would make Monday even more important.
6. Study Note: "Priced In"
Concept
An event is priced in when markets have already moved to reflect it, before it happens or before another market reacts. When the news is confirmed, prices barely budge.
Analogy
If a rain forecast sends everyone to buy umbrellas today, the umbrella shop is quiet tomorrow even when it pours. Only a storm far worse than forecast brings the line back.
Today's example
Meta reported during Korea's early Wednesday morning. Seoul sold 3.5% on Thursday afternoon; New York sold chips 6.7% on Thursday night. Night futures falling only 1.1% suggest the market thinks Seoul already bought its umbrella. But if New York's storm was heavier than forecast (the SOX drop exceeded Seoul's two-day chip decline), the line could form again today.
Why it matters
Headlines read "US chips crash → Korea crashes." But markets react in the order information arrives, not in calendar order. Knowing which market digested the news first explains why the same story hits on different days at different sizes.
One-liner
The market that reacts first reacts less later, unless the news turns out bigger than expected.
7. Corrections & Open Items
Corrections
- None.
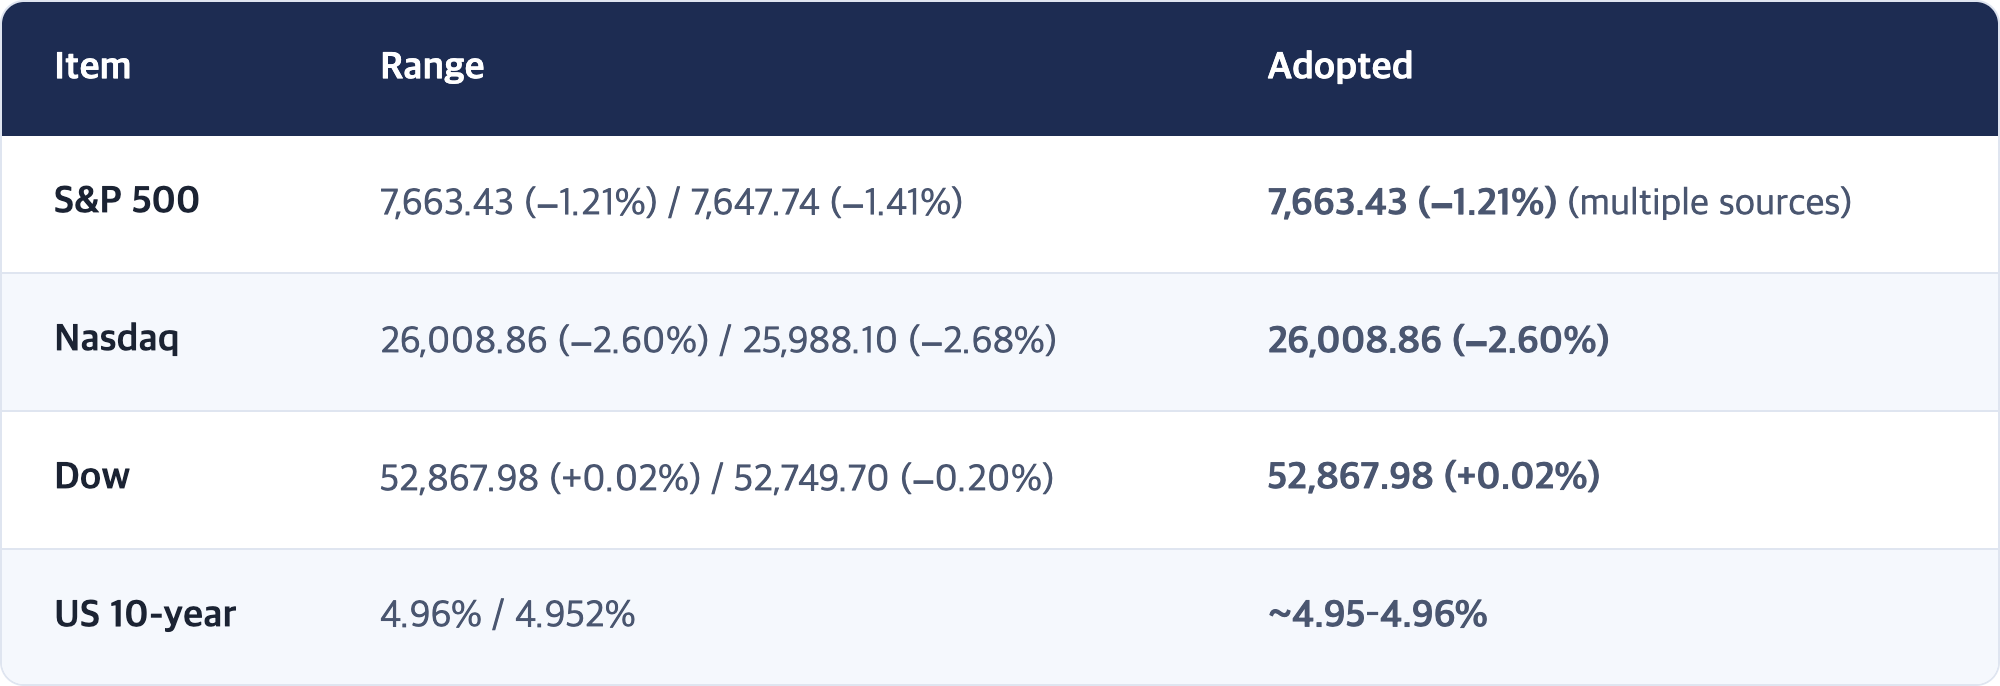
Source discrepancies
🔲 Unconfirmed
8. Event Calendar (KST)
Sources
- Closing Look — Thursday, October 22, 2026 | CappNotes
- Stock market today: S&P 500, Nasdaq tank as tech stocks sink amid AI trade worries | Yahoo Finance
- Wall Street Sinks as Nasdaq Falls Over 2% on AI Cost Worries | GV Wire
- Nasdaq Tumbles 2% as Meta and Tesla Fall and Oil Prices Surge | GuruFocus
- AI investment worries hit tech stocks; Nasdaq −2.6% | Ajunews (Korean)
- SK hynix halts Solidigm IPO; chip rebound in focus | Top Star News (Korean)
- KOSPI 200 night futures down over 1% | Stockplus (Korean)
- USD/KRW at 1,324.2, fifth straight yearly low | Money Today (Korean)
Market Analyst · This brief does not recommend buying or selling individual stocks. It provides macro context and interpretation.
📌 More market briefs
※ This post is market observation and organization intended to support your own judgment. It is not a recommendation to buy or sell any security. Figures are as of the time of writing and may differ between sources.
If this was useful, bookmark it or pass it along. It genuinely helps me write the next one.
I can survive. We can survive.