September 21, 2026 US Market Brief — Nasdaq and S&P 500 Before the Open
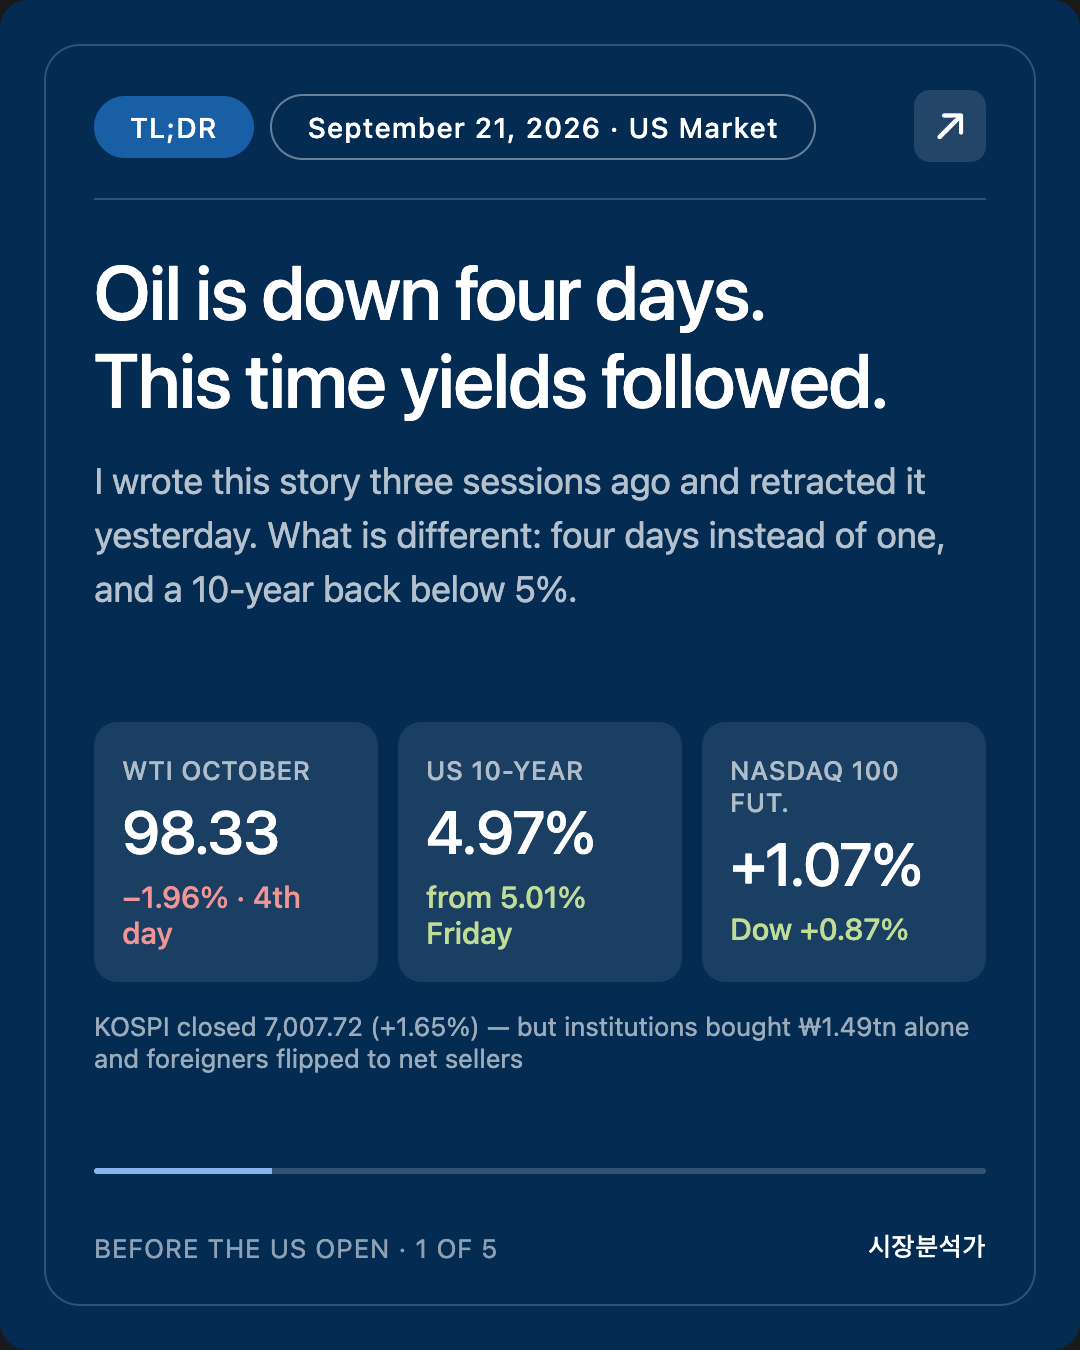
- Oil has fallen for four straight sessions. WTI October $98.33 (−1.96%), Brent November $102.09 (−1.71%). Europe's STOXX 600 is +0.8% with tech up about 2%.
- ★ What is different from three sessions ago: the bond market came along. The US 10-year sits near 4.97%, below Friday's 5.01% close. Gold is −0.73%, and European energy is the only sector lower (−0.3%) in a rising market. That is what an oil-to-inflation-expectations-to-yields transmission actually looks like.
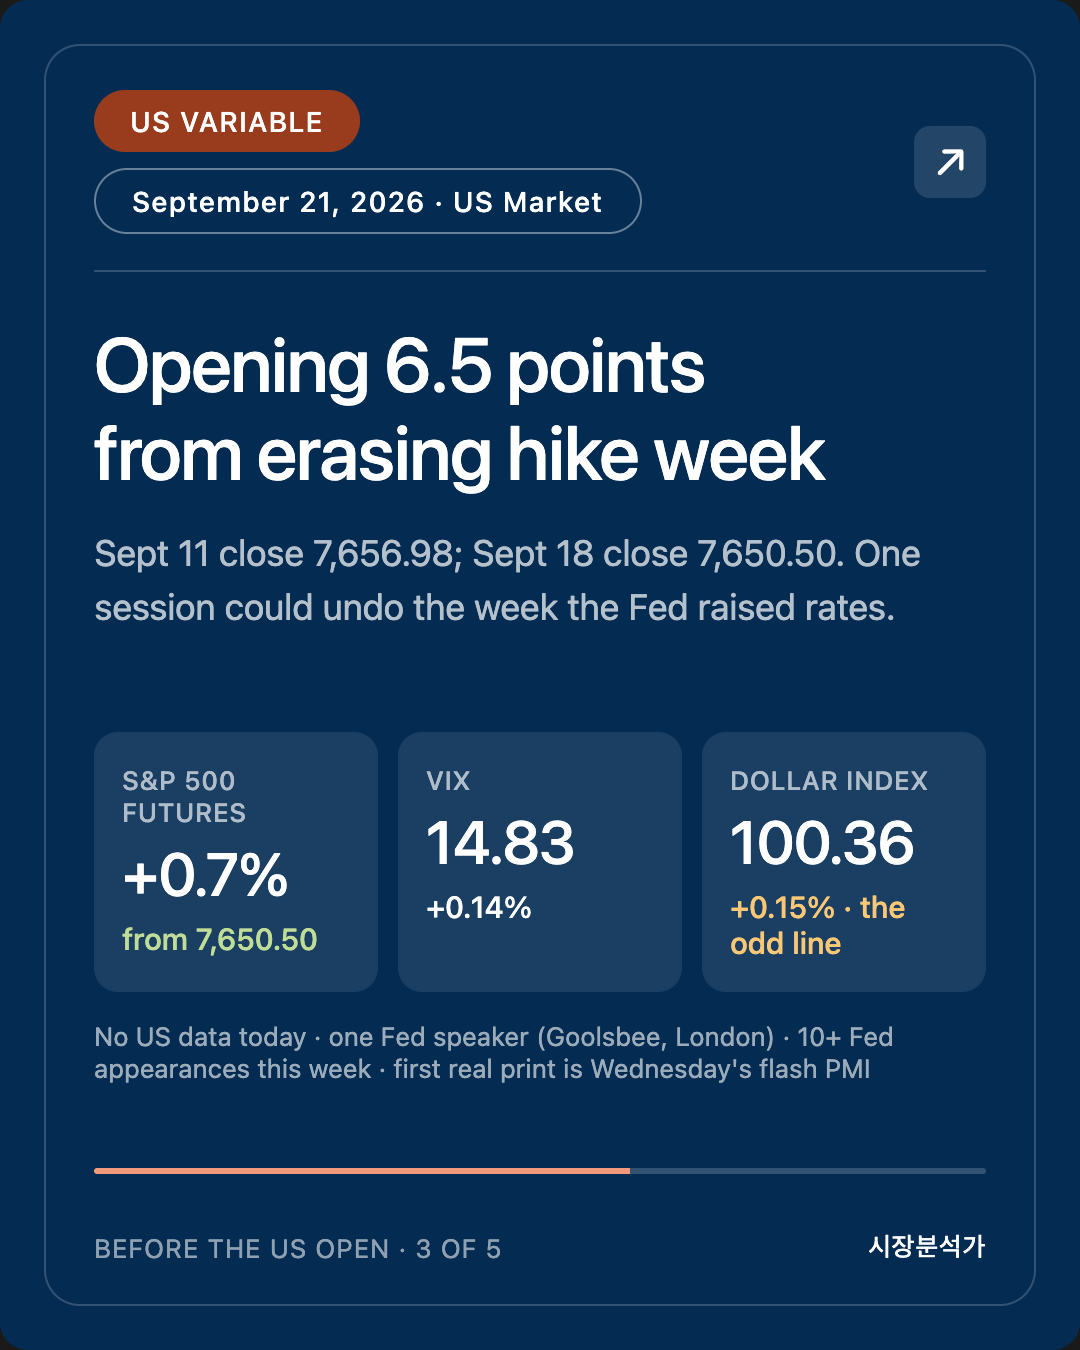
- US pre-market is led by tech. Nasdaq 100 futures +1.07%, Dow +0.87%, S&P 500 +0.7%, Russell 2000 +0.76%. VIX 14.83. Bitcoin is up about 6.1% near $85,400.
- KOSPI closed at 7,007.72 (+1.65%), but the internals are thin. Institutions bought a net ₩1.49tn on their own; foreigners flipped to net sellers into the close; 552 stocks fell against 310 that rose. 🔴 Samsung Electronics gained 4.98% while SK Hynix managed 0.59% — the gap widened over the day.
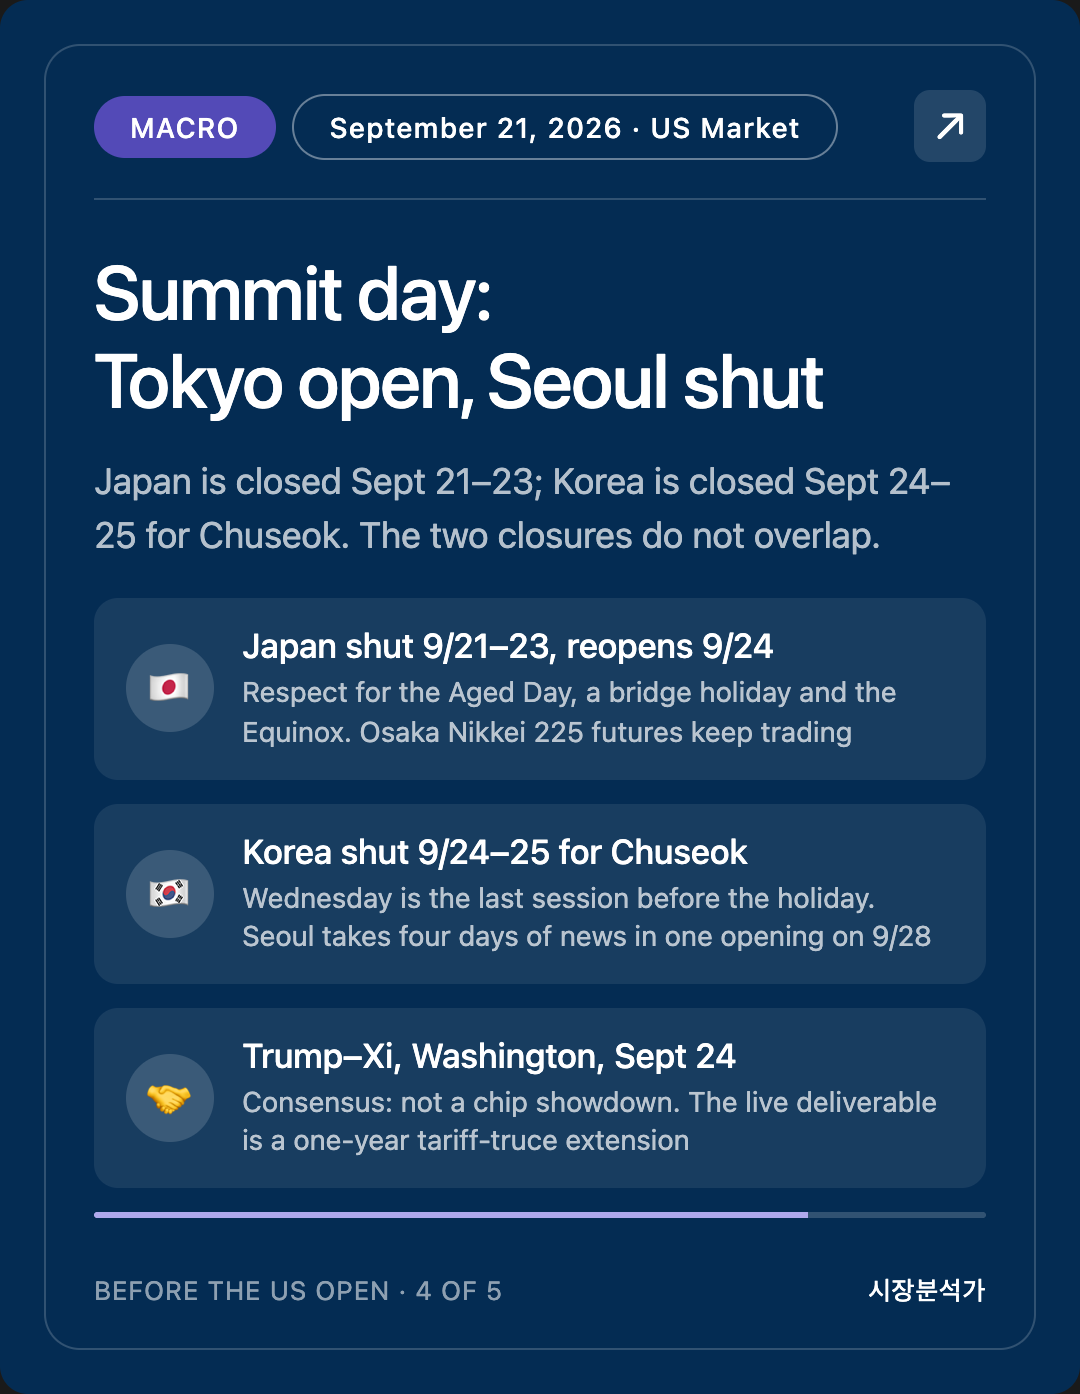
- ★ Half of Asia is shut this week, and the two closures do not overlap. Japan is closed Sept 21–23; Korea is closed Sept 24–25 for Chuseok. On the day Trump and Xi meet in Washington (Thursday), Tokyo is open and Seoul is not.
This is Mr. Can. Here is the September 21, 2026 brief ahead of the US market open.
Written: 2026-09-21 05:50 PDT (Korea: Mon 9/21 21:50 KST)
Basis: Asian closes for 9/21 + European morning + US pre-market, before the open
🟢 This edition is on time. Scheduled 05:30 PDT, written 05:50 PDT, forty minutes before the US open. Every US figure below is a pre-market quote, not an intraday one. The run of late and missed editions since 9/16 ends here.
SEO Intro
On Friday the Fed had just raised rates and the Dow had its worst week since March. This morning, US equity futures are green, gold is down, and the ten-year Treasury yield has slipped back below 5%.
The reason being cited is oil. Crude has now fallen four sessions in a row. Messages are passing between Washington and Tehran, and reports say more barrels are leaving the Gulf than the market expected — even after Houthi missiles and drones hit Saudi Arabia over the weekend.
I want to be careful here, because I have told this story once already and had to take it back.
Three sessions ago I wrote that oil had smothered the Fed's message. Yesterday I retracted it: measured over the full week, oil had gone up, not down, and I had been quoting the wrong futures contract. There was no blanket to speak of.
The same story is back this morning. So today's brief asks a narrower question: what is different this time, and what single number would tell me I am wrong again?
Meanwhile in Seoul, the KOSPI closed back above 7,000 — but only one kind of buyer showed up.
1. Scoring Yesterday's Four Checkpoints
Yesterday's brief asked whether Monday morning's rally in Seoul reflected the record export data or was just pre-holiday position squaring. Korea has now closed, so all four are scorable.
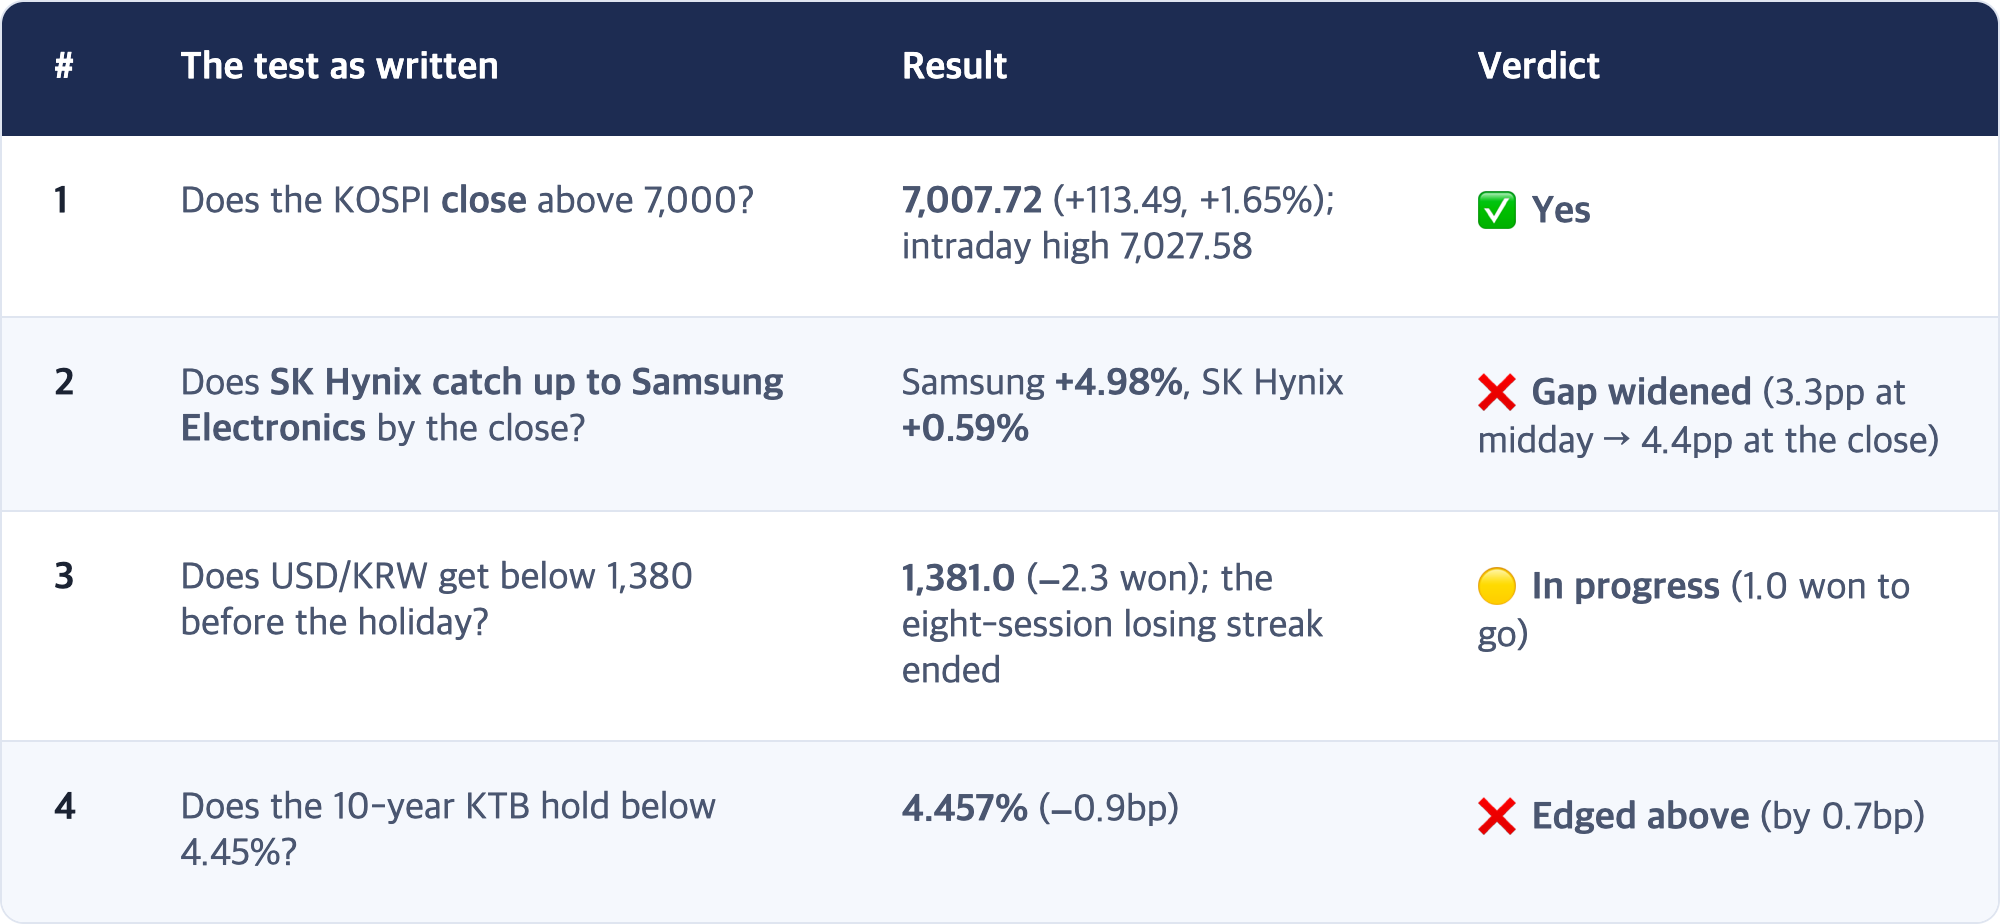
[Interpretation] Passing #1 means less once you read #2 beside it
Taken separately that is one win, two losses and one open. Read together, the win gets thinner.
The reason I wrote #2 yesterday was this: if the export release had lifted the whole semiconductor complex, the two big memory names should have moved together. If they kept splitting, the move was about individual flows, not the data.
They split — and split wider. And 552 stocks fell against 310 that rose. The index cleared 7,000 while two-thirds of the market went down.
[Interpretation] The KOSPI did not recover 7,000; Samsung Electronics recovered it. Had I written yesterday's checkpoint as a single index level, I would be reading today wrongly right now. Asking about prices and flows is what saved it.
(Context for readers outside Korea: Samsung Electronics and SK Hynix are the two dominant memory-chip makers, together a very large share of the KOSPI. Semiconductors were 47.8% of Korea's exports in the first twenty days of September.)
2. Today's Core Question: Oil Is Down Four Days. What Is Different?
[Fact] Oil and everything standing next to it
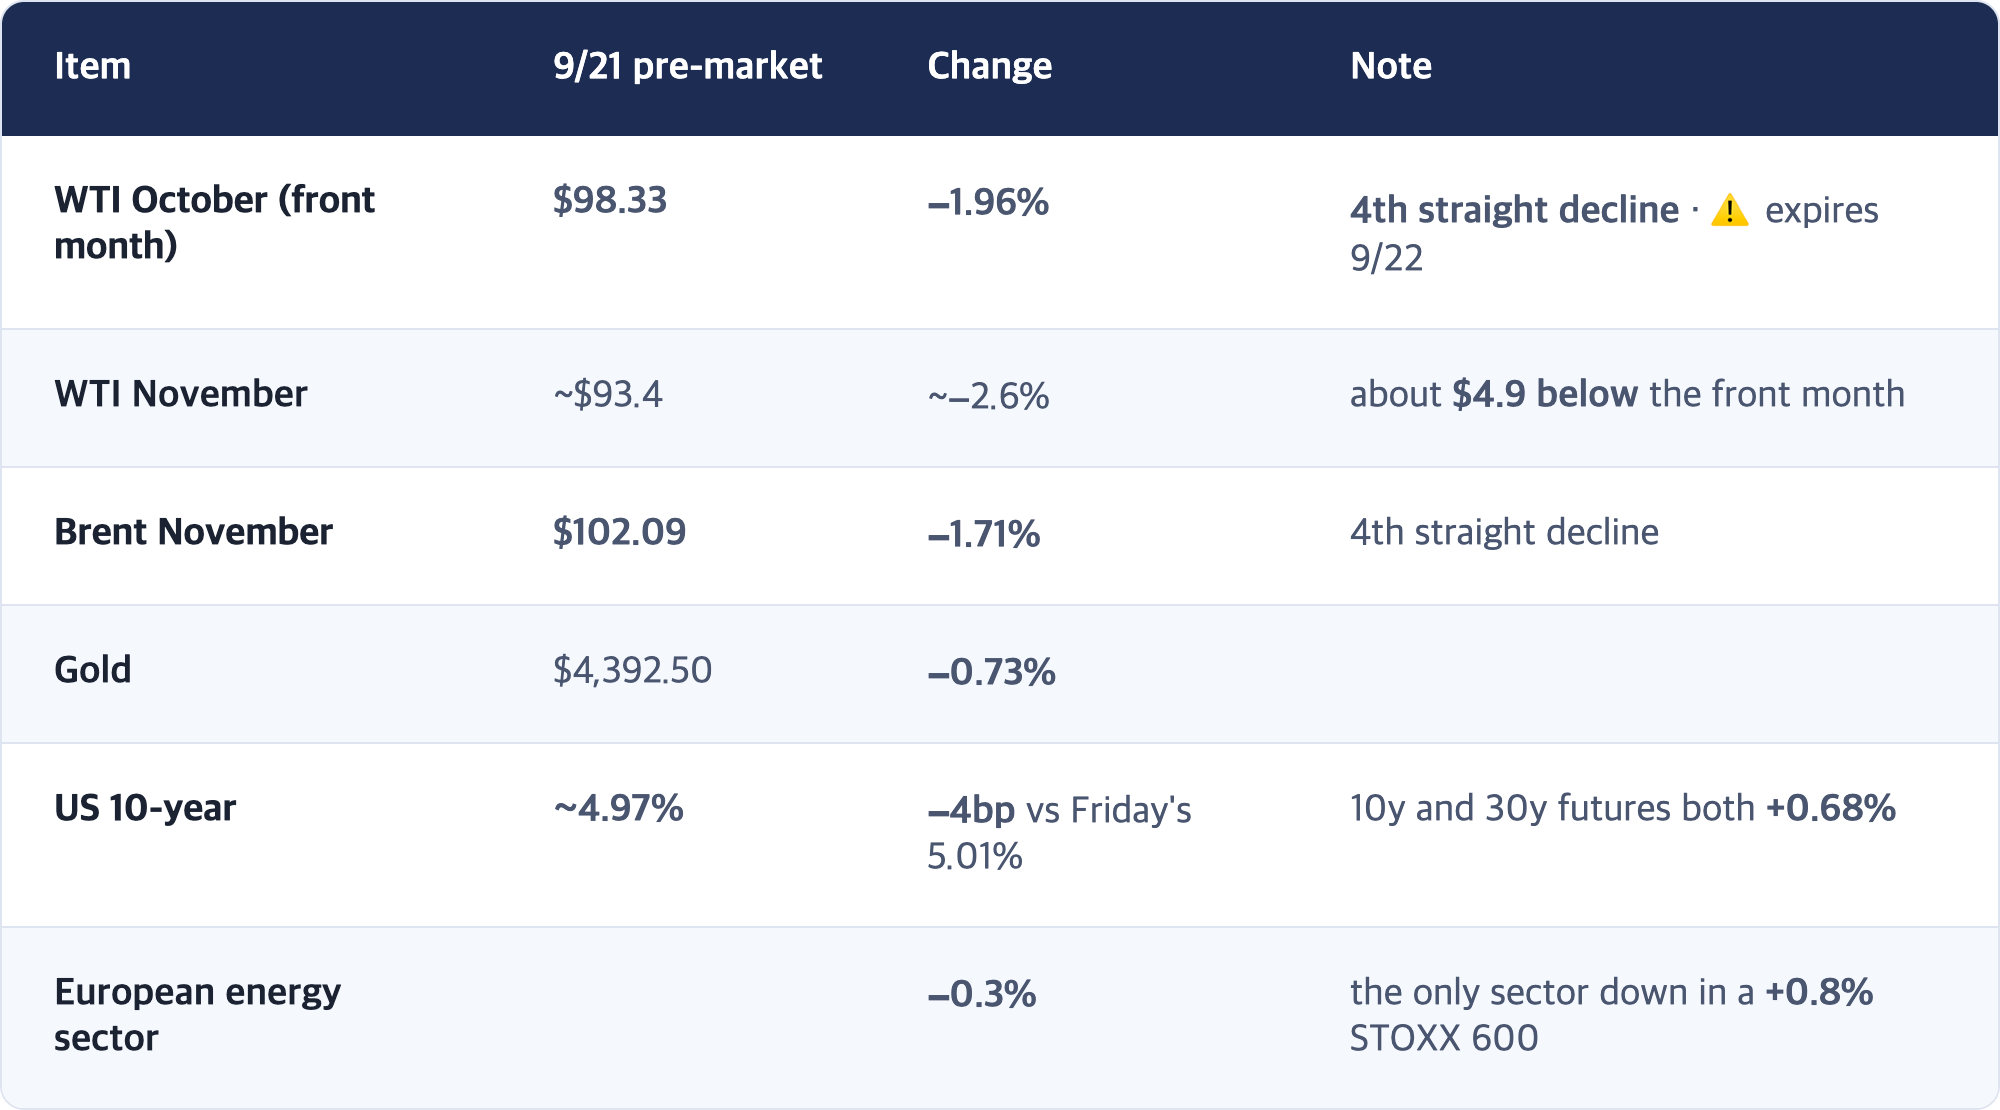
Two reasons are being reported: messages are being exchanged between the US and Iran, and more crude is leaving the Gulf than expected. Both outweighed the weekend's Houthi missile and drone attacks on Saudi Arabia.
🔴 [Interpretation] I published this story three sessions ago and retracted it yesterday
Worth restating plainly:
- Sept 18 brief: "The Fed said one more, and oil smothered that message for two days."
- Sept 20 brief: retracted — over the full week oil had risen (WTI +1%, gasoline +6%), and I had quoted the November contract while the market quoted October. There was no blanket.
The same story returned this morning. To avoid making the same error twice, the honest move is to count what actually changed.
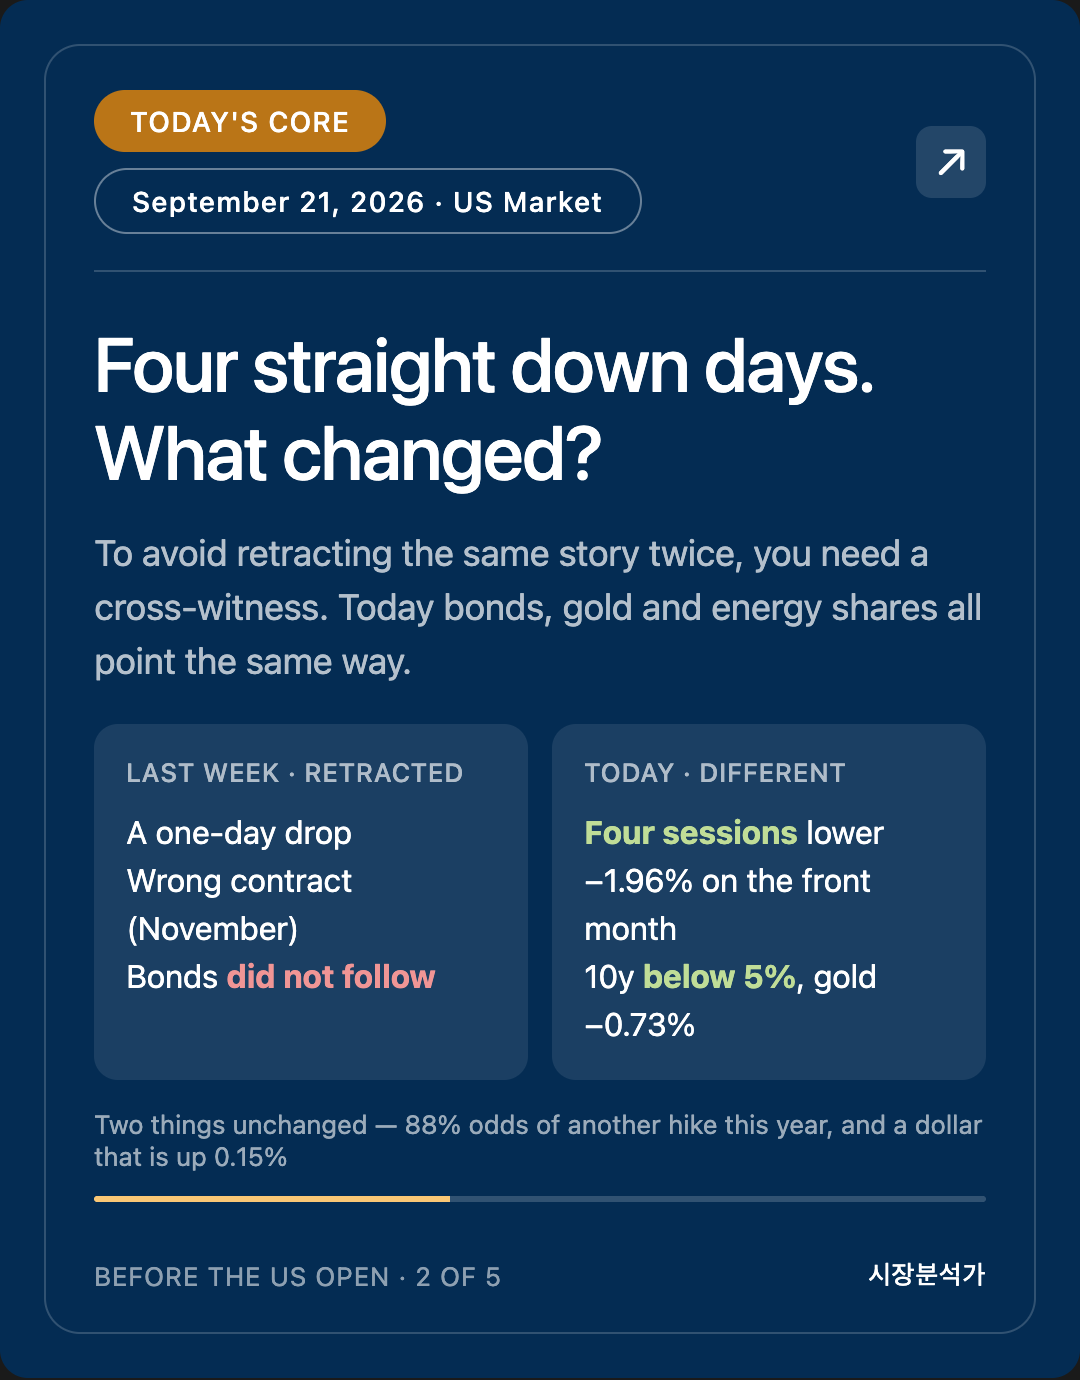
[Interpretation] Three things changed. Two did not.
Changed
- Four sessions, not one. The Sept 18 brief leaned on a single day. This is a four-session run in which the weekly and daily directions agree.
- It is down on the front month. My earlier mistake was reading a deferred contract. Today the October contract itself is −1.96%. Change the contract month and the conclusion survives.
- ★ The bond market came along. This is the part that matters. The 10-year has gone 5.01% → ~4.97%, 10y and 30y futures are both +0.68%, and gold is −0.73%. That is the oil-to-breakevens-to-yields chain actually firing. Last week that link was missing.
Unchanged
- The Fed has not turned. CME futures put the odds of at least one more hike this year near 88%. October odds stood at 59.7% as of Sept 20. Cheaper oil does not relieve that until those numbers move.
- The dollar is firmer, not softer. DXY 100.35–100.37 (+0.15%), above its 20-day EMA at 99.63. A dollar rallying alongside risk appetite does not fit cleanly. Some of today's bid may be coming not from oil but from Thursday's summit.
✅ [Interpretation] So here is tonight's single test
Does the US 10-year close below 5.00%?
- If it does — the oil move genuinely passed through to inflation expectations and yields, and calling oil the driver is fair.
- If it closes back above 5% — today's equity gain came from summit positioning and tech flows, not from crude. In that case the oil story is a one-day story again.
3. The US Variable: Before the Open (9/21 ET)
[Fact] Pre-market
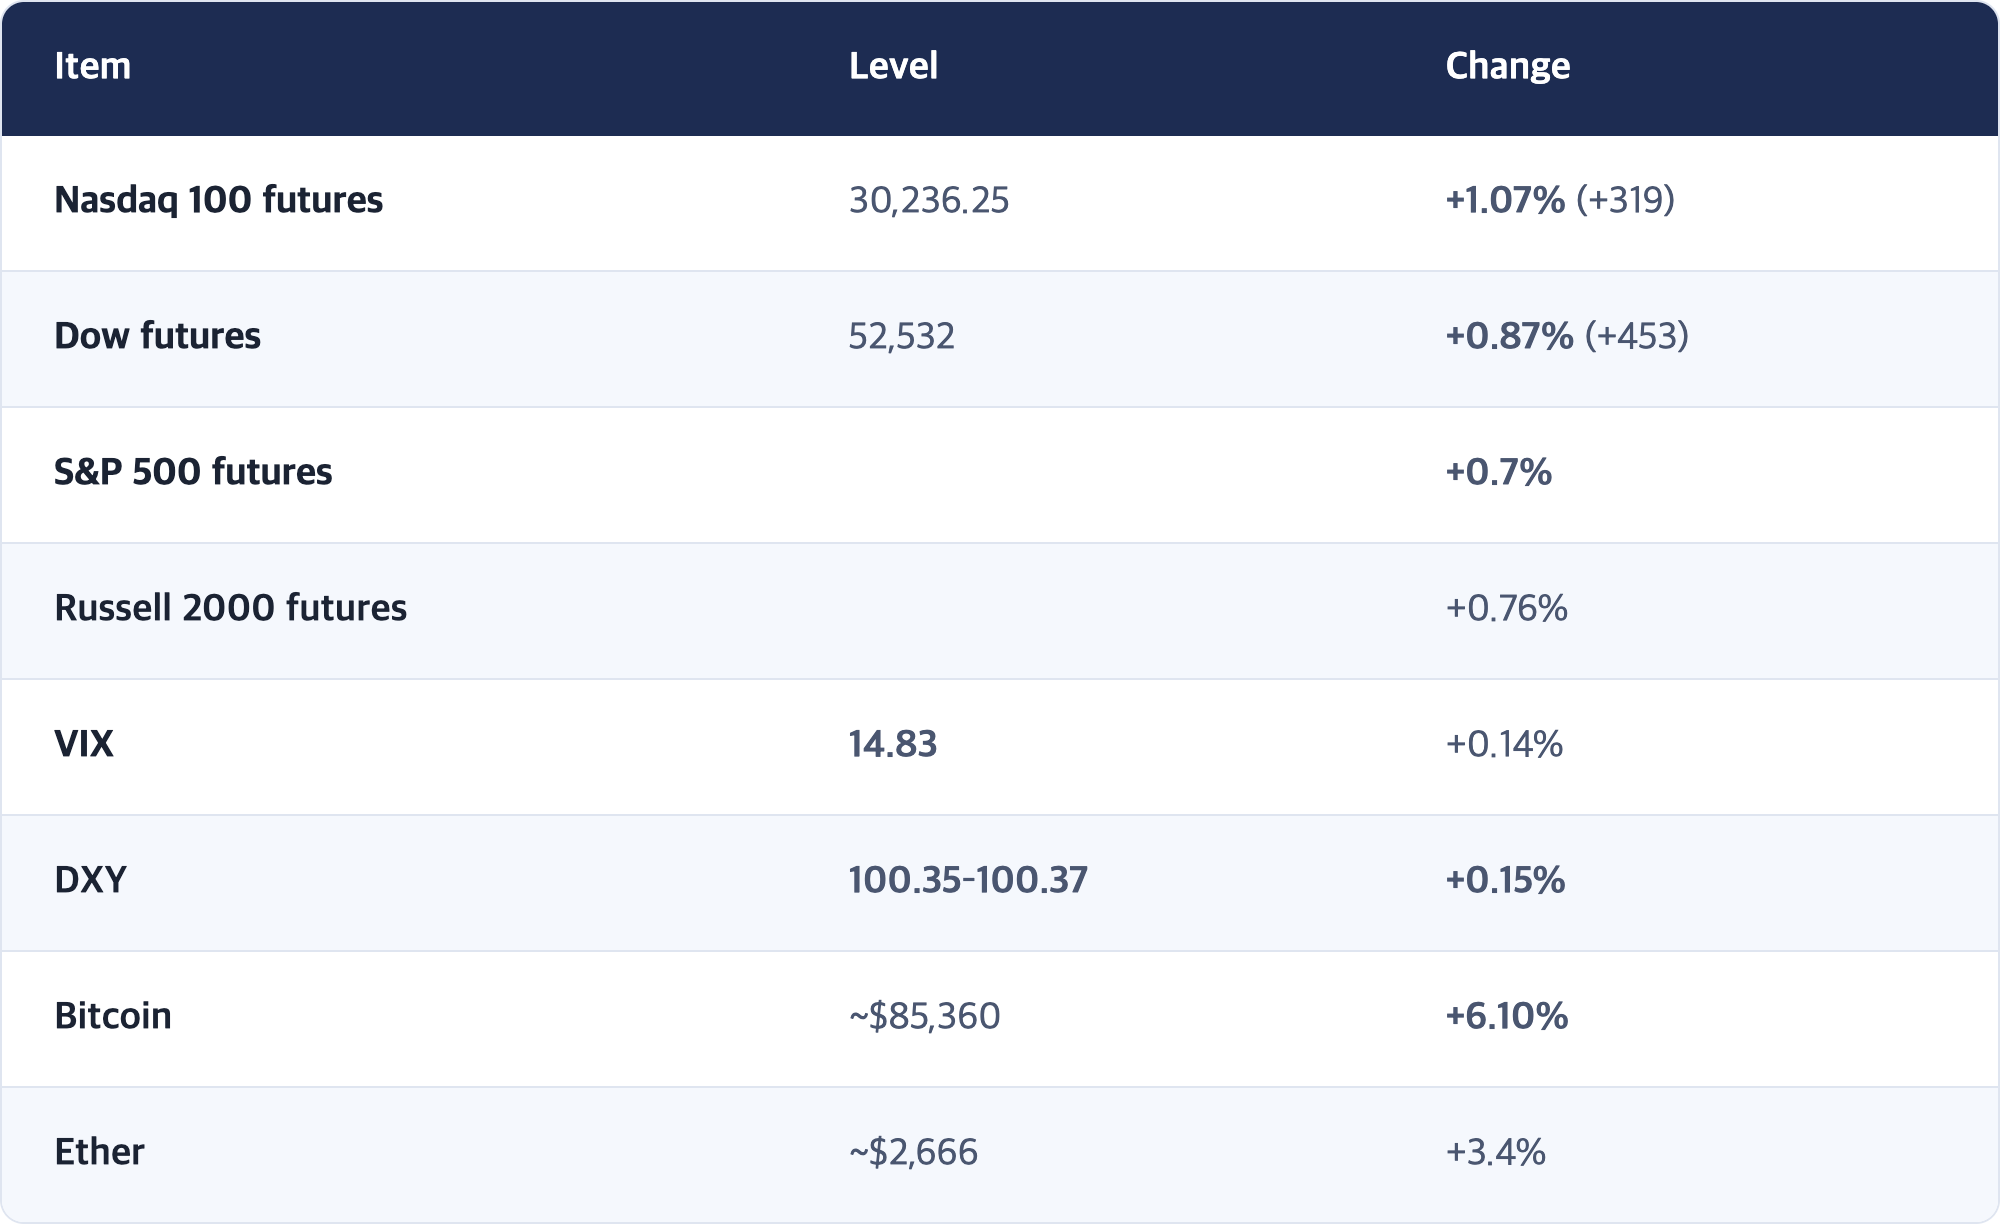
Friday's closes for reference: Dow 51,682.64 · S&P 500 7,650.50 · Nasdaq 26,522.55 · SOX 11,921.69.
[Observation] The S&P 500 is 6.5 points from erasing hike week
The Sept 11 close was 7,656.98. The Sept 18 close was 7,650.50. The gap is 6.48 points. If futures hold +0.7% into the bell, the index clears that line at the open.
[Interpretation] Last week was the week the Fed raised rates, and the Dow had its worst week since March. Erasing that in the first session of the following week would say the market is pricing this hike as already-known news rather than the start of a tightening cycle. But it only counts on a closing basis — Seoul has now failed three intraday breakouts in three weeks.
[Fact] The Fed and this week's calendar
- Today (9/21): Chicago Fed President Austan Goolsbee speaks at an OMFIF event in London. No US data.
- More than ten Fed appearances are scheduled this week. Light on data, heavy on talk.
- Wed 9/23: S&P Global flash PMIs for the US, Europe and Japan — the only large data point of the week.
- Thu 9/24: jobless claims · new home sales · Trump–Xi summit · Swiss National Bank decision
- Fri 9/25: durable goods orders · final University of Michigan sentiment (following August's drop to 47.8)
- Wed 9/30: 🔴 Micron earnings and the August PCE report land on the same day — AI capex and inflation checked in one session.
- Oct 28: FOMC
[Interpretation] In a week without data, markets move on words and events. Ten Fed speakers and Thursday's summit will fill that space. Treat today's and tomorrow's direction as noise rather than trend. The first real number arrives Wednesday.
4. Macro Backdrop: Asia's Close and This Week's Calendar
[Fact] Korea, 9/21 close (KST)
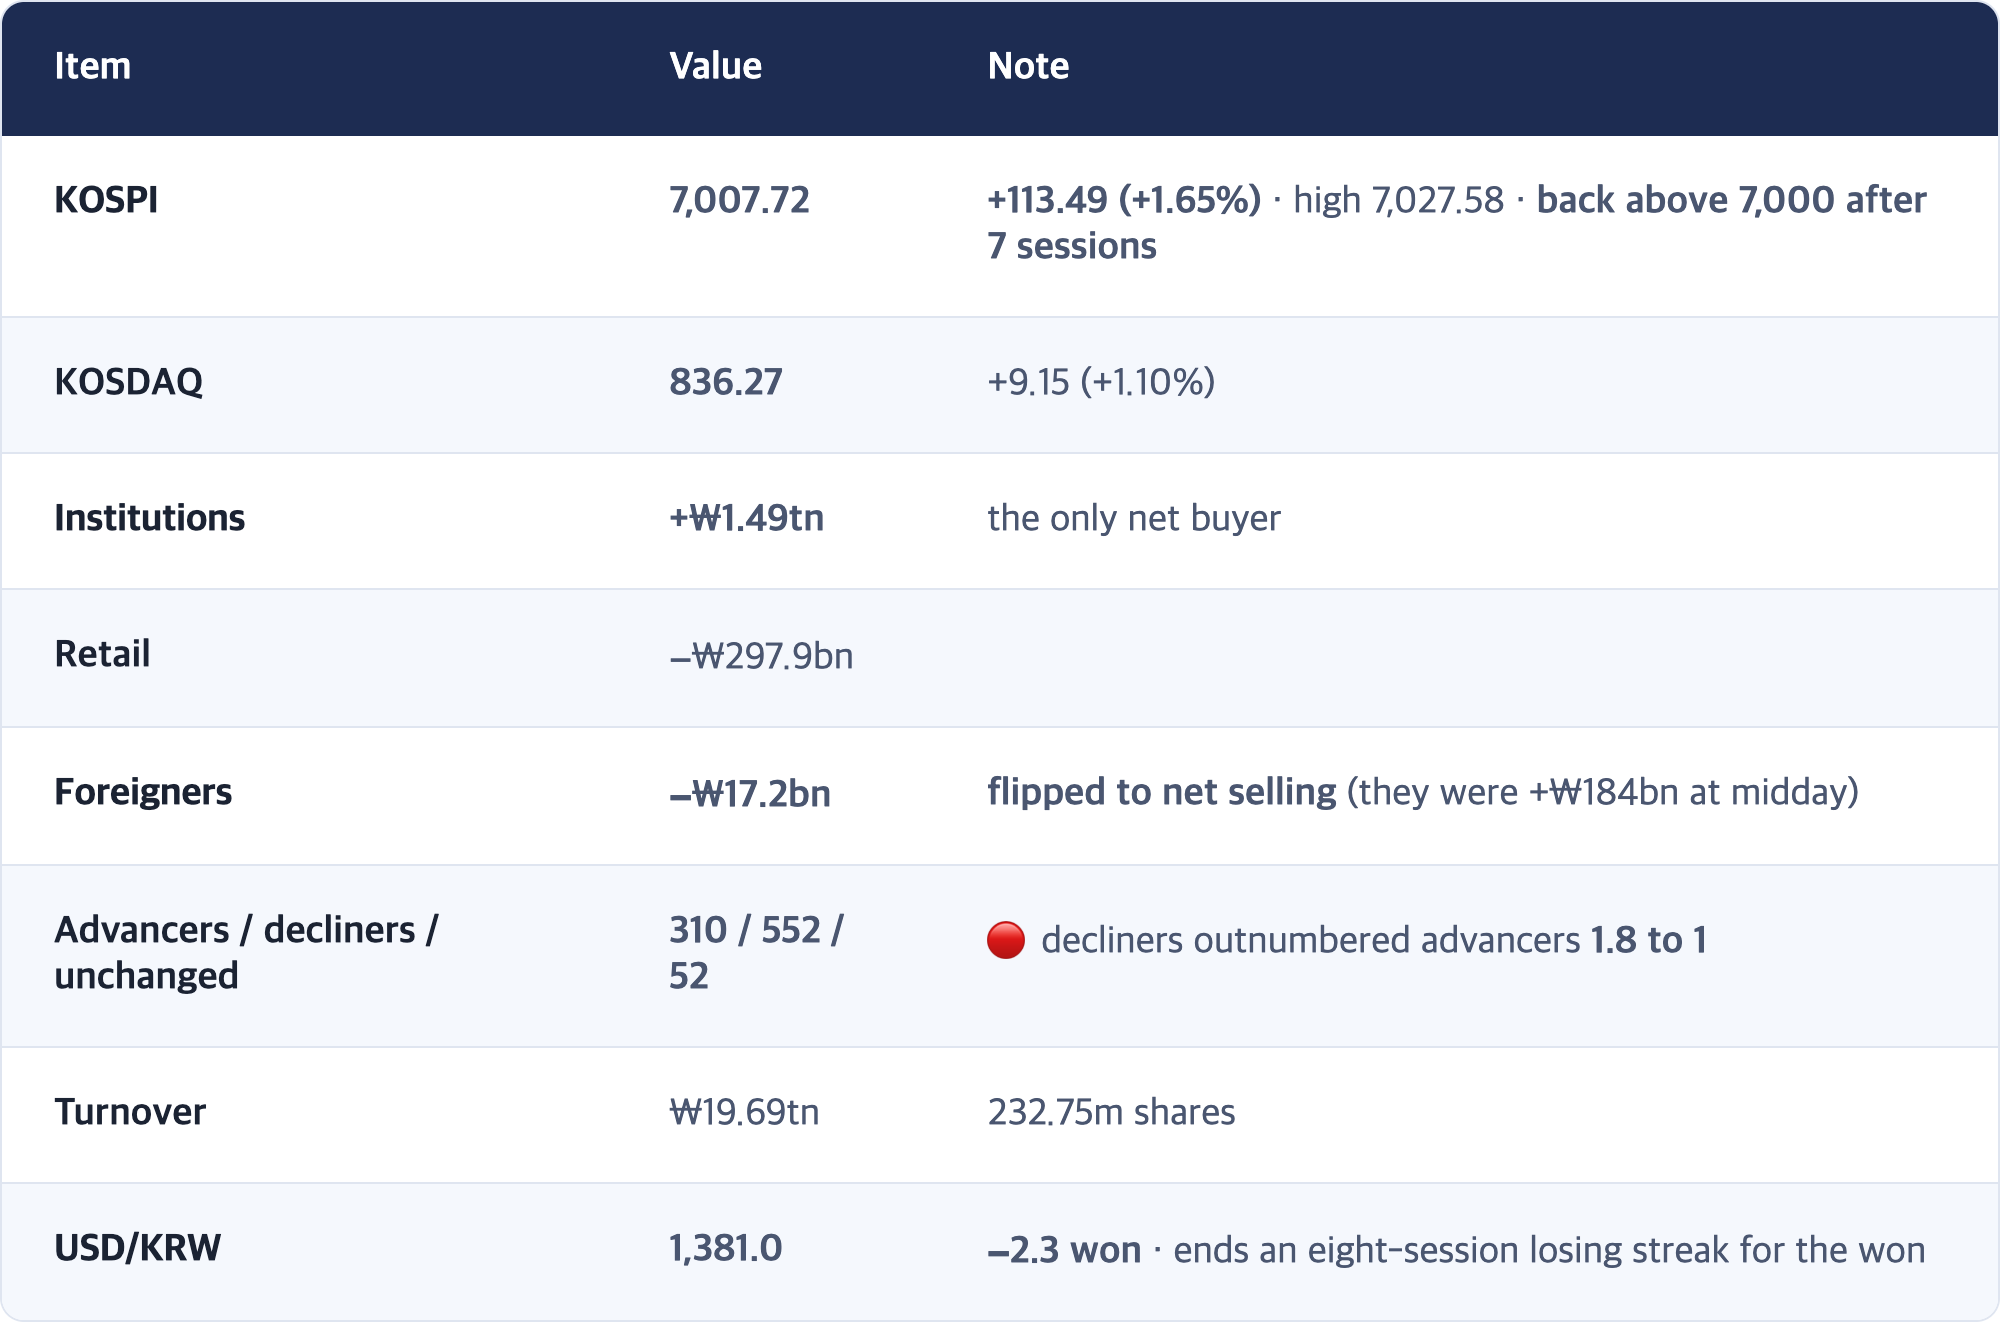
Movers — Samsung Electronics ₩274,000 (+4.98%) · Samsung Electronics pref. ₩208,000 (+6.07%) · SK Hynix ₩1,868,000 (+0.59%) · LG Energy Solution ₩352,000 (−3.30%) · Hyundai Motor ₩359,000 (−1.64%)
Korea Treasury Bonds (9/21) — 2y 4.013% (+3.3bp) · 3y 4.056% (+2.1bp) · 5y 4.275% (+5.0bp) · 10y 4.457% (−0.9bp) · 30y 4.597%
[Interpretation] The Korean curve flattened today: the front end rose while the 10-year fell. Yesterday I argued that US rate pressure had stopped reaching Korean bonds and was being absorbed entirely by the currency. Today the currency gave back 2.3 won — the first day in eight that the won moved the other way.
[Fact] Asia and Europe
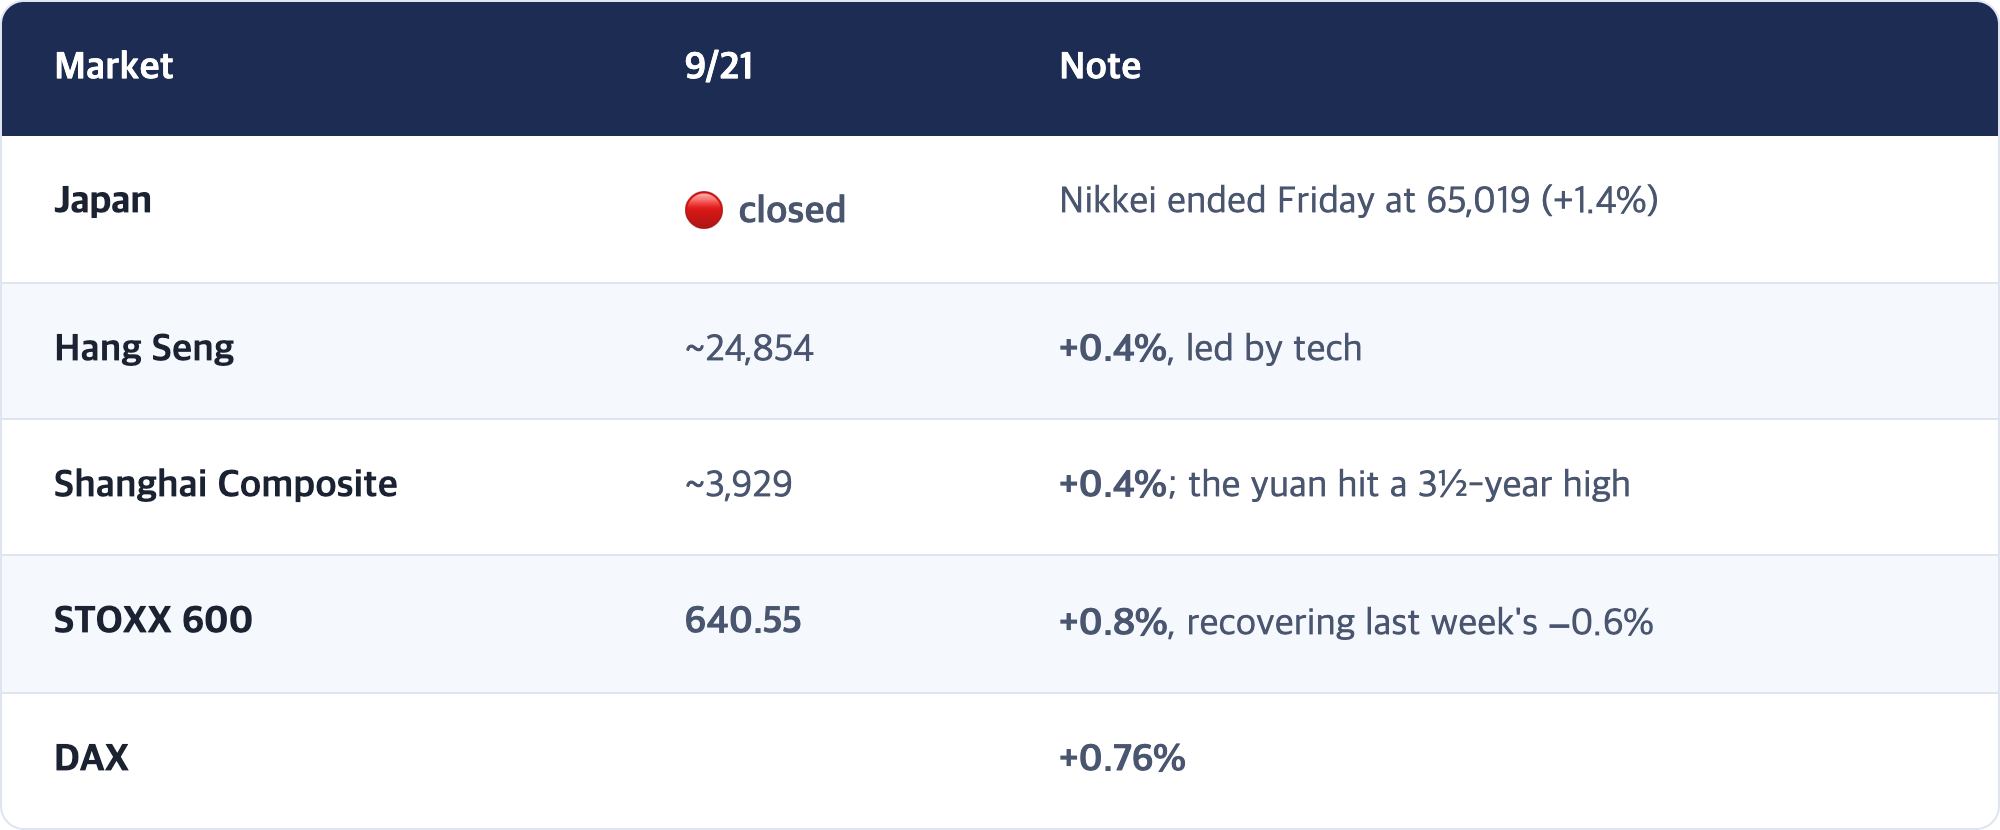
By sector in Europe: tech +2%, banks +1.6%, energy −0.3%. Chip-equipment names Soitec and Aixtron led. Markets also digested German state elections in the northeast, where the far-right AfD came first — with little visible market reaction.
🔴 [Fact] This week's Asian holiday map
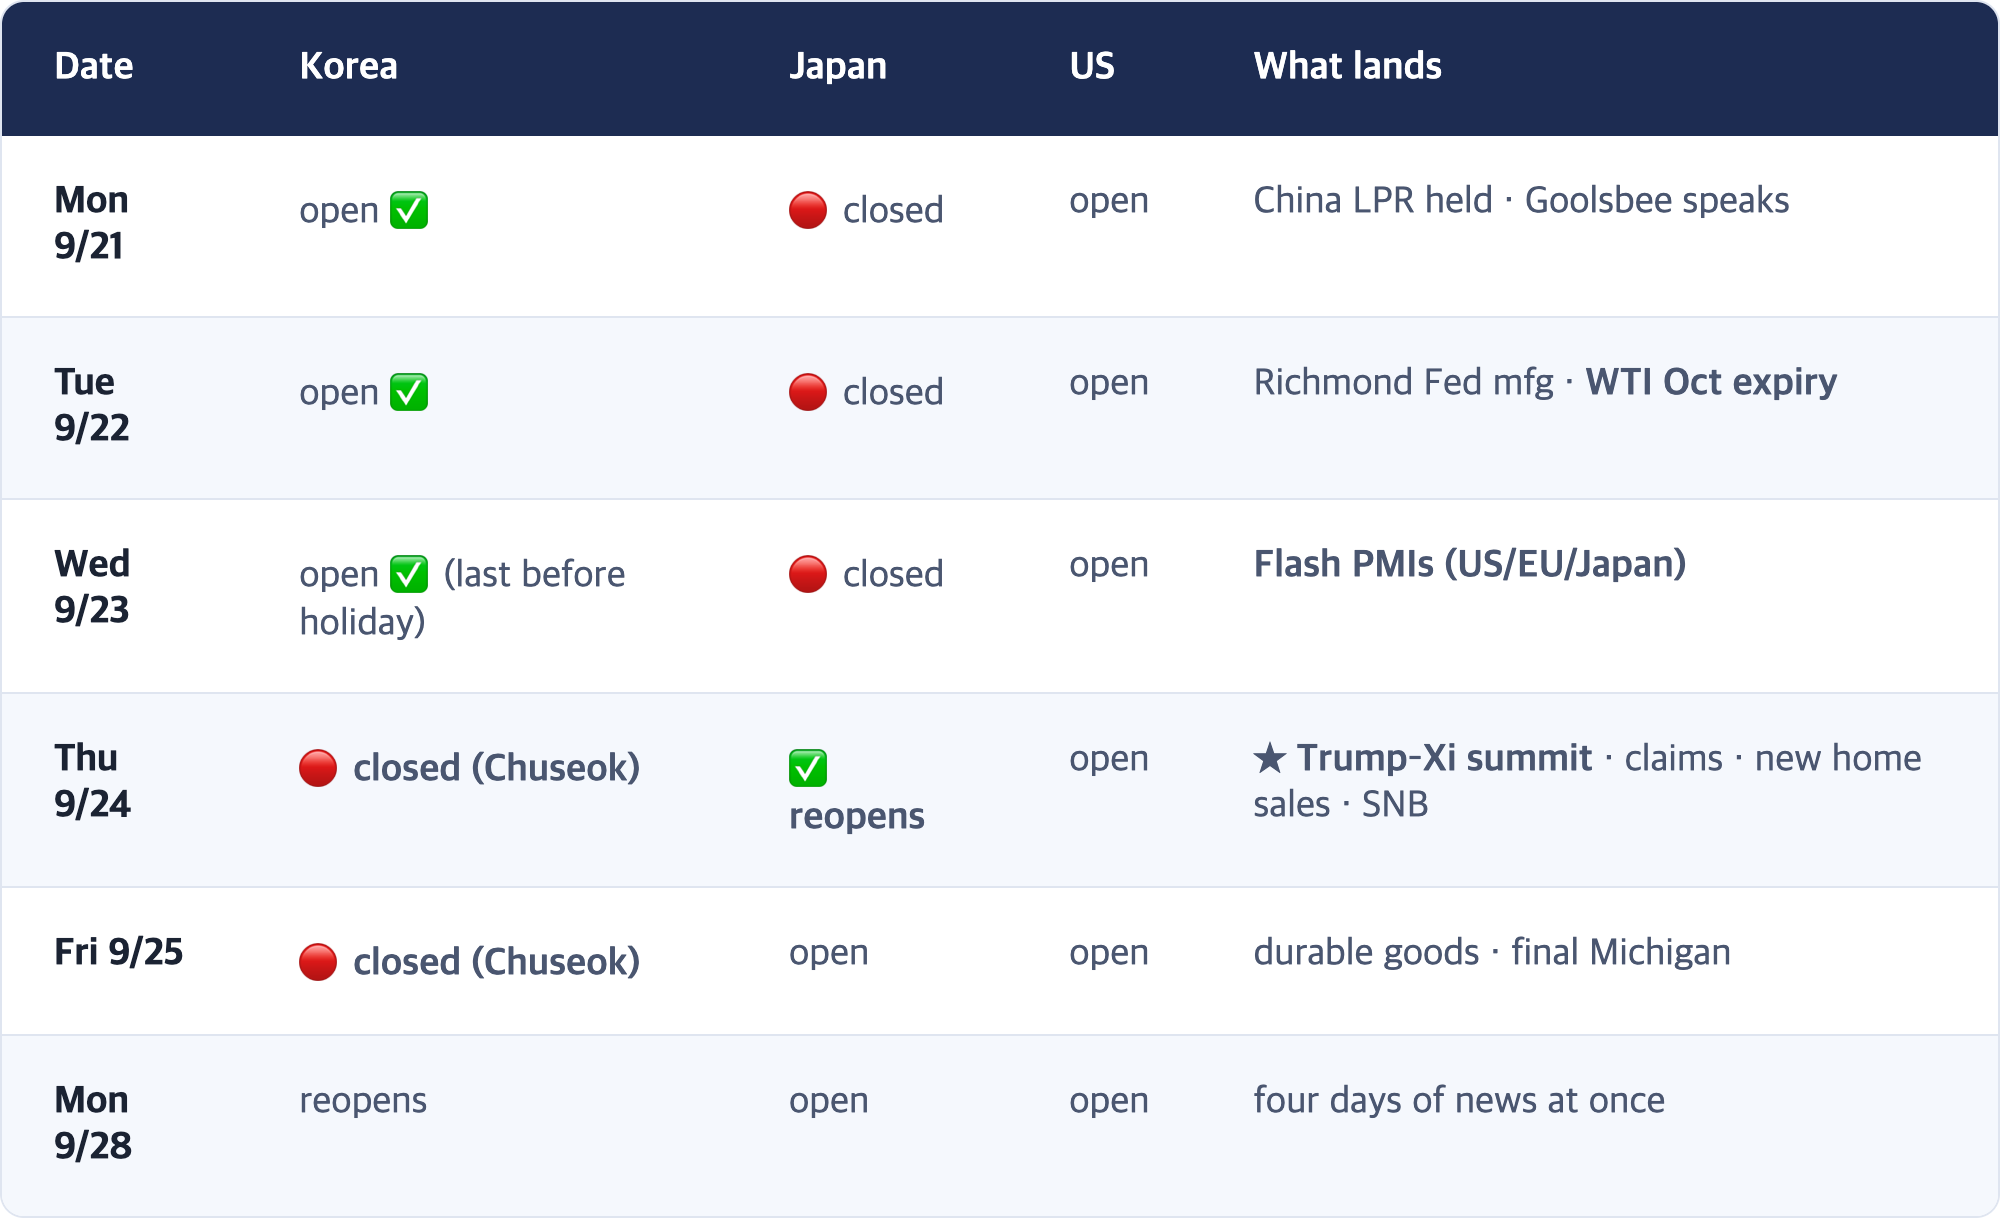
Japan closes for Respect for the Aged Day (9/21), a bridge holiday (9/22) and the Autumnal Equinox (9/23). Osaka Exchange derivatives, including Nikkei 225 futures, keep trading through the closure — cash equities do not.
(Chuseok is the Korean harvest festival, the country's largest holiday. Markets shut Thursday and Friday and reopen Monday.)
🔴 [Interpretation] Tokyo is open for the summit. Seoul is not.
Yesterday I called Thursday's meeting a semiconductor showdown. Having read the expert previews, that was too strong, and I am correcting it.
[Fact] The current consensus reads roughly as follows.
- The most likely deliverable is a one-year extension of last October's Busan trade truce. The 90-day tariff truce is close to expiring.
- Meaningful US concessions on advanced semiconductor export controls are considered unlikely. AI chips and chipmaking equipment are still treated as strategic, and were left out of the AI safety-notification mechanism now under discussion.
- The live agenda is tariffs, rare earths and critical minerals, Taiwan arms sales, and AI cooperation.
- Treasury Secretary Scott Bessent has proposed a new US–China AI dialogue framed around national security.
[Interpretation] Semiconductors are on the agenda but will not be settled there. For Korea, the outcome that actually matters on Thursday is whether the tariff truce is extended — which touches autos, steel and batteries before it touches chips.
And one structural point remains. That day, Tokyo ends a three-day closure and opens; Seoul is shut for Chuseok.
[Interpretation] So for two sessions, Tokyo is the only place in Asia where semiconductor risk gets priced. Seoul takes four days of news in a single opening on Sept 28, by which point Tokyo will likely have set a direction. I do not know which direction. I only claim that Seoul's Sept 28 gap is more likely than usual to follow Tokyo's lead.
5. Previewing the US Session (9/21 ET)
[Observation] The shape of the open
- Risk appetite is broad. Tech futures lead the Dow (+1.07% vs +0.87%), small caps are up with them (+0.76%), and Bitcoin is +6.1%. Risk assets are rising together.
- Gold and oil are down. Safe-haven demand and inflation hedges falling at the same time is consistent with one less notch of inflation worry.
- But the dollar is up. DXY +0.15%. That single line does not fit the picture above.
[Interpretation] What to be careful about today
There is no US data today, and only one Fed speaker, in London. On thin-catalyst days, large moves are usually flows and positioning rather than fundamentals.
Bitcoin's weekend jump was reported alongside a short squeeze and an SEC move on tokenized stocks. Tech strength on a day like this can be a retracement and short-covering rather than a new view. Do not read the size of today's rally as the signal — use the four tests below to read its character instead.
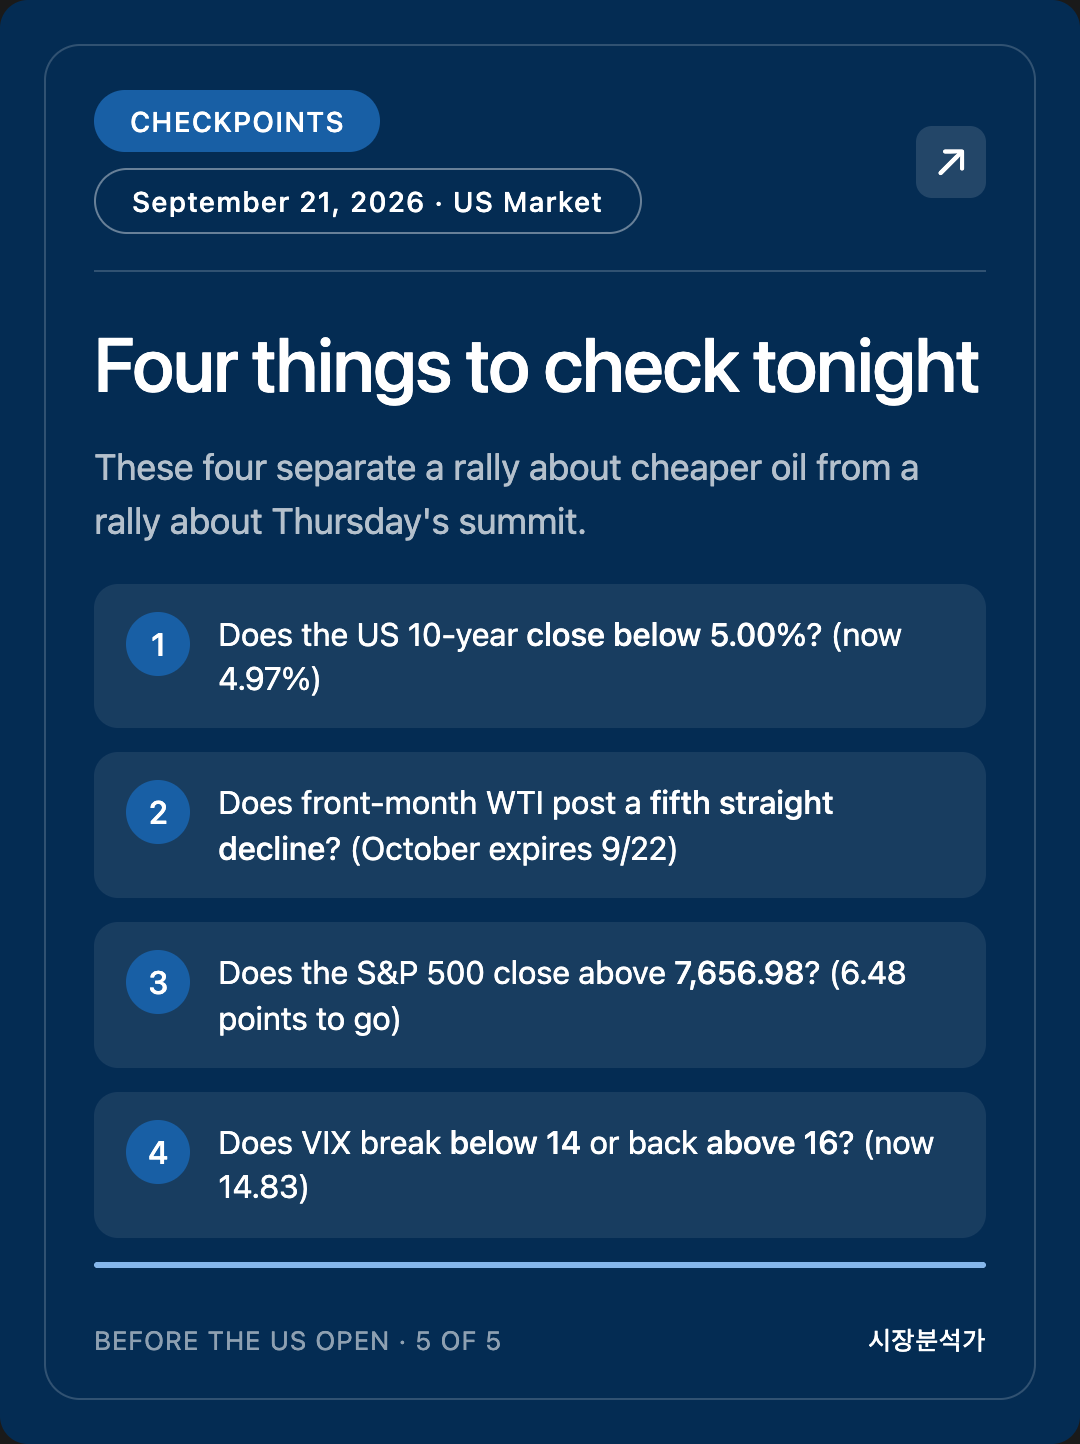
✅ Four Checkpoints (open through today's close)
These four separate "today is about cheaper oil" from "today is about Thursday's summit."
- Does the US 10-year close below 5.00%? Pre-market ~4.97% against Friday's 5.01%. Below means the oil-to-yields channel is working; back above 5% means equities rose on summit hopes, not crude.
- Does front-month WTI post a fifth straight decline? It needs to settle below $98.33 on the October contract. ⚠️ October expires tomorrow (9/22), so outlets will start quoting November (~$93.4). A number that suddenly drops five dollars is a contract change, not a crash. See the study note below.
- Does the S&P 500 close above 7,656.98 (the Sept 11 close)? It needs 6.48 points from Friday's 7,650.50. Clearing it erases the entire hike-week loss in one session.
- Does VIX break below 14, or back above 16? It sits at 14.83. Lower says the market treats Thursday as a catalyst; higher says it has started pricing it as event risk.
6. Study Note: Why One Day's Oil Price Is Reported as $93, $98 and $102
A follow-up to yesterday's correction — because the same confusion is happening again today, in real time.
The concept
Crude is priced in futures, not spot. Futures are split by when the barrels are delivered: October, November and December contracts all trade at once, at different prices.
What the press simply calls the oil price is the front month — the contract closest to expiry.
But the front month expires and rolls to the next one. That is the rollover. During those few days, some outlets are still quoting October while others have already moved to November. That is why one day produces two or three different oil prices.
Today is exactly one of those days
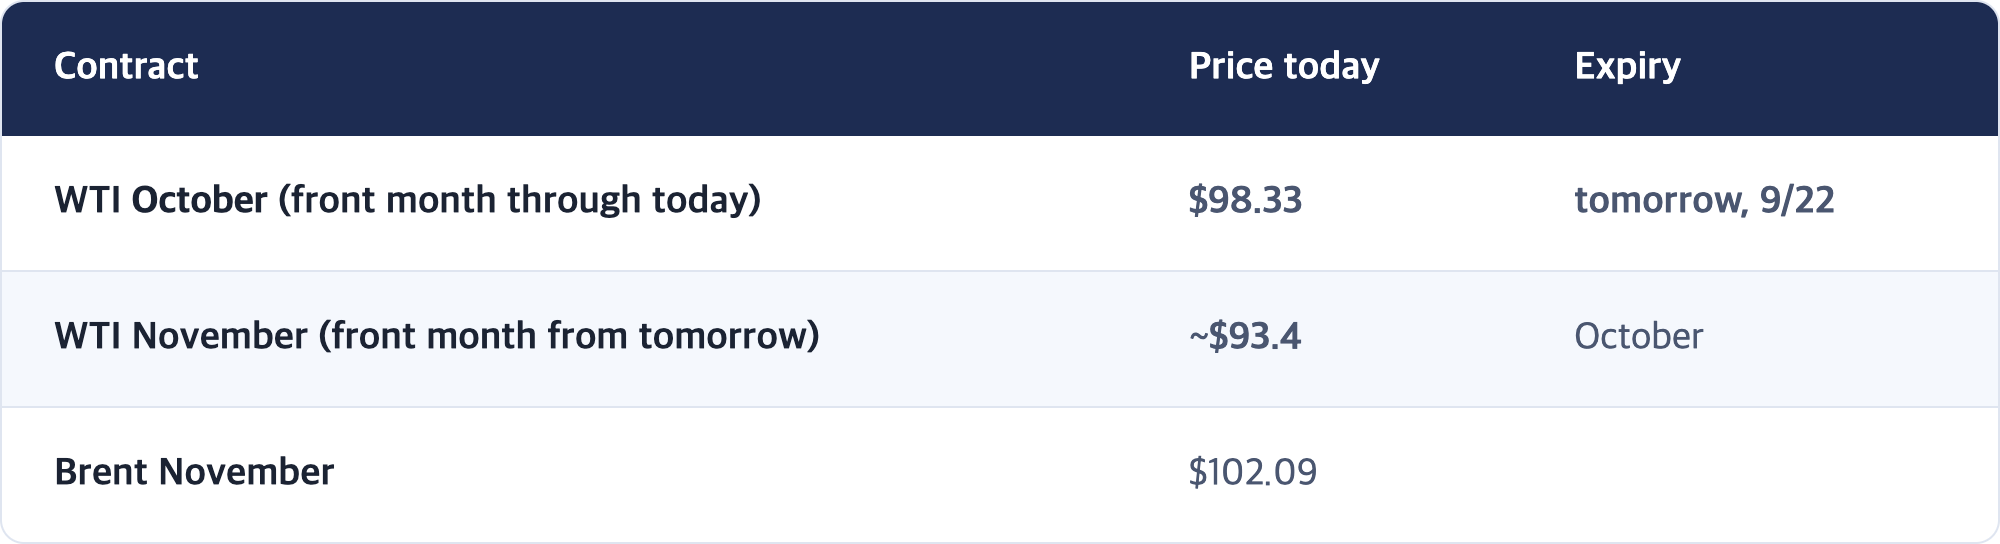
Reported as $98 today and $93 tomorrow, it looks like a 5% collapse. The market may have done nothing at all — the quoted seat simply changed.
The analogy
Think of wholesale produce. This month's cabbage and next month's cabbage carry different prices. If the paper printed this month's number yesterday and next month's today, it would look like the price crashed, when all that changed was which column was printed.
One step further: backwardation
Right now WTI's near contract ($98.33) is more expensive than the further one (~$93.4). That shape is called backwardation.
- Backwardation — nearer is dearer → a signal that barrels are scarce right now
- Contango — further is dearer → plenty now, worry later
The spread is about $4.9, and it has held through four straight days of falling prices. [Interpretation] The level is falling while the near-term tightness has not cleared. That is why I read today's decline as expected supply relief rather than delivered supply relief.
The worked example — where I got it wrong
In the Sept 18 brief I wrote WTI at $95–97, reading the November contract at $95.72. The actual front-month settlement that day was $100.30. A $4.58 gap decided whether oil had fallen or risen, and the weekly narrative built on top of it had to be retracted a day later.
One line
Always read oil together with its contract month. Compare like with like — front month against front month. In an expiry week, a jump in the number may be a change of seat rather than a change of price.
7. Corrections and Open Items
🔴 Two corrections
- Calling Thursday's summit a semiconductor showdown, as yesterday's brief did, was too strong. Export controls are on the agenda, but meaningful US concessions are considered unlikely, and the most probable deliverable is a one-year extension of the Busan trade truce. → For Korea, the thing to watch shifts from chips to the tariff truce.
- Yesterday's brief put the WTI contract-month spread at "more than $2." As of Sept 18 it was $4.58 (October 100.30 vs November 95.72). The direction was right; the size was understated by half.
A difference of basis, not an error
- Yesterday's brief said the KOSPI regained 7,000 after eight sessions; today's closing reports say seven. The first counts from the intraday high, the second from the close. → This brief uses the closing basis: seven sessions.
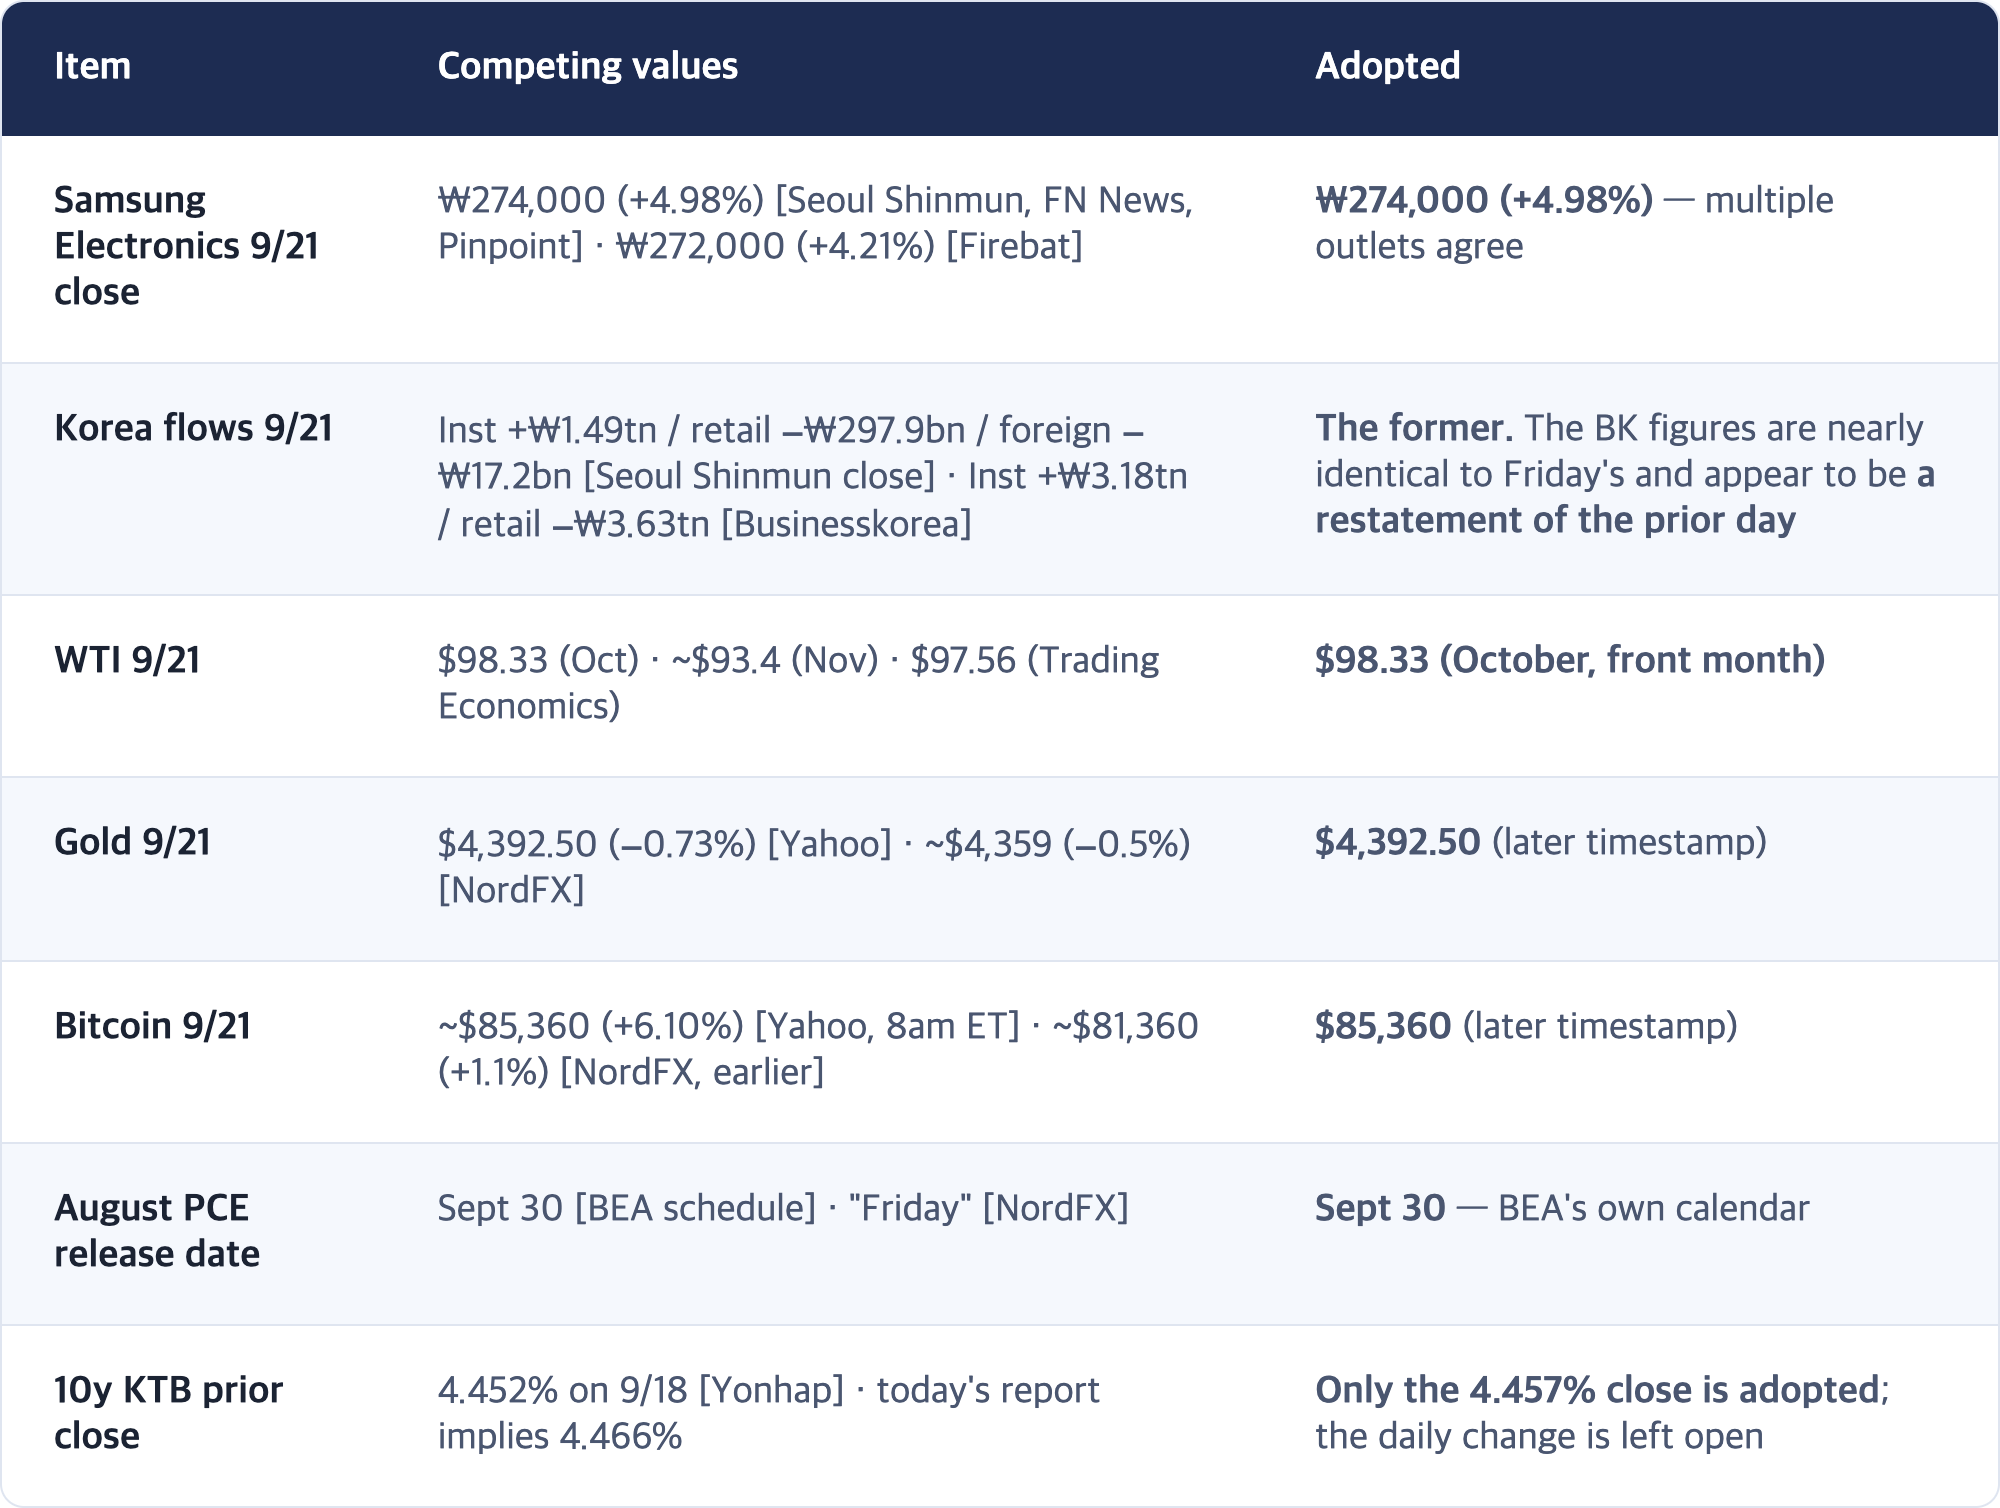
Source discrepancies (value adopted stated)
Open items
- SOX pre-market for 9/21 — only inferable indirectly from European chip-equipment strength (+2%)
- USD/KRW overnight NDF quotes
- Korean foreign futures flows for 9/21 — cash flipped to net selling; futures unconfirmed
- US 2-year yield for 9/21 — only the 10-year is confirmed, so no 2s10s spread
- October FOMC odds updated for 9/21 — 59.7% as of 9/20 remains the latest; today's figure is 88% for at least one hike this year, a different measure
Operations log
- 🟢 Published on schedule. Cron 05:30 PDT, written 05:50 PDT, forty minutes before the open. This ends the run of late and skipped editions that started on 9/16.
Sources
- KOSPI closes at 7,007.72, back above 7,000 after seven sessions (Seoul Shinmun)
- KOSPI closes up 113.49 points at 7,007.72 (Asiae)
- Chip strength pushes KOSPI past 7,000; Samsung Electronics +4.98% (FN News)
- KOSPI 7,007.72 close: Samsung and SK Hynix both higher (Slist)
- KOSPI reclaims 7,000 — September 21, 2026 closing review (Firebat)
- USD/KRW ends 2.3 won lower at 1,381.0 (Money Today)
- FX rates for September 21: USD/KRW 1,381.00 (SNM News)
- Korean Treasury yields mixed; 3-year closes at 4.056% (Betanews)
- Stock market today: Dow, S&P 500, Nasdaq futures rise as oil falls, anticipation builds for Trump-Xi summit (Yahoo Finance)
- Europe's STOXX 600 gains as tech rallies, oil retreat eases nerves (Reuters / Investing.com)
- Market Pulse – September 21, 2026 | Fed, Oil, Asia, Gold (NordFX)
- US Dollar Index: Trades firmly near 100.35 ahead of Fed speeches (FXStreet)
- Oil prices, US-Iran, Saudi Arabia (CNBC)
- Crude Oil Price Chart and Historical Data (Trading Economics)
- Weekly Economic Calendar: September 21-25, 2026 (Letters to a Young Investor)
- Newsquawk Economic Calendar — 21st-25th September 2026
- Personal Consumption Expenditures Price Index — release schedule (BEA)
- Japanese Stock Market to Close for Three Days from September 21 to 23 (GuruFocus)
- Japan Stock Market Closed for Three Days: What Traders Need to Know (EBC Financial Group)
- Expectations for the Trump-Xi September Meeting (Brownstein)
- Will the Trump-Xi summit make limited progress on AI? (PIIE)
- What to expect from the Trump-Xi summit in Washington (World Economic Forum)
- Xi Arrives in Washington for Trump Summit as Tariff Truce Clock Runs Down (Eastern Herald)
- Bitcoin Price Recovery Surges Past $81,000 on Strong Market Signals (Cryptonomist)
This brief interprets market flows and macro variables. It is not a buy or sell recommendation on any individual security.
📌 More market briefs
※ This post is market observation and organization intended to support your own judgment. It is not a recommendation to buy or sell any security. Figures are as of the time of writing and may differ between sources.
If this was useful, bookmark it or pass it along. It genuinely helps me write the next one.
I can survive. We can survive.