Oct 20, 2026 US Market Brief — Nasdaq and S&P 500 Before the Open
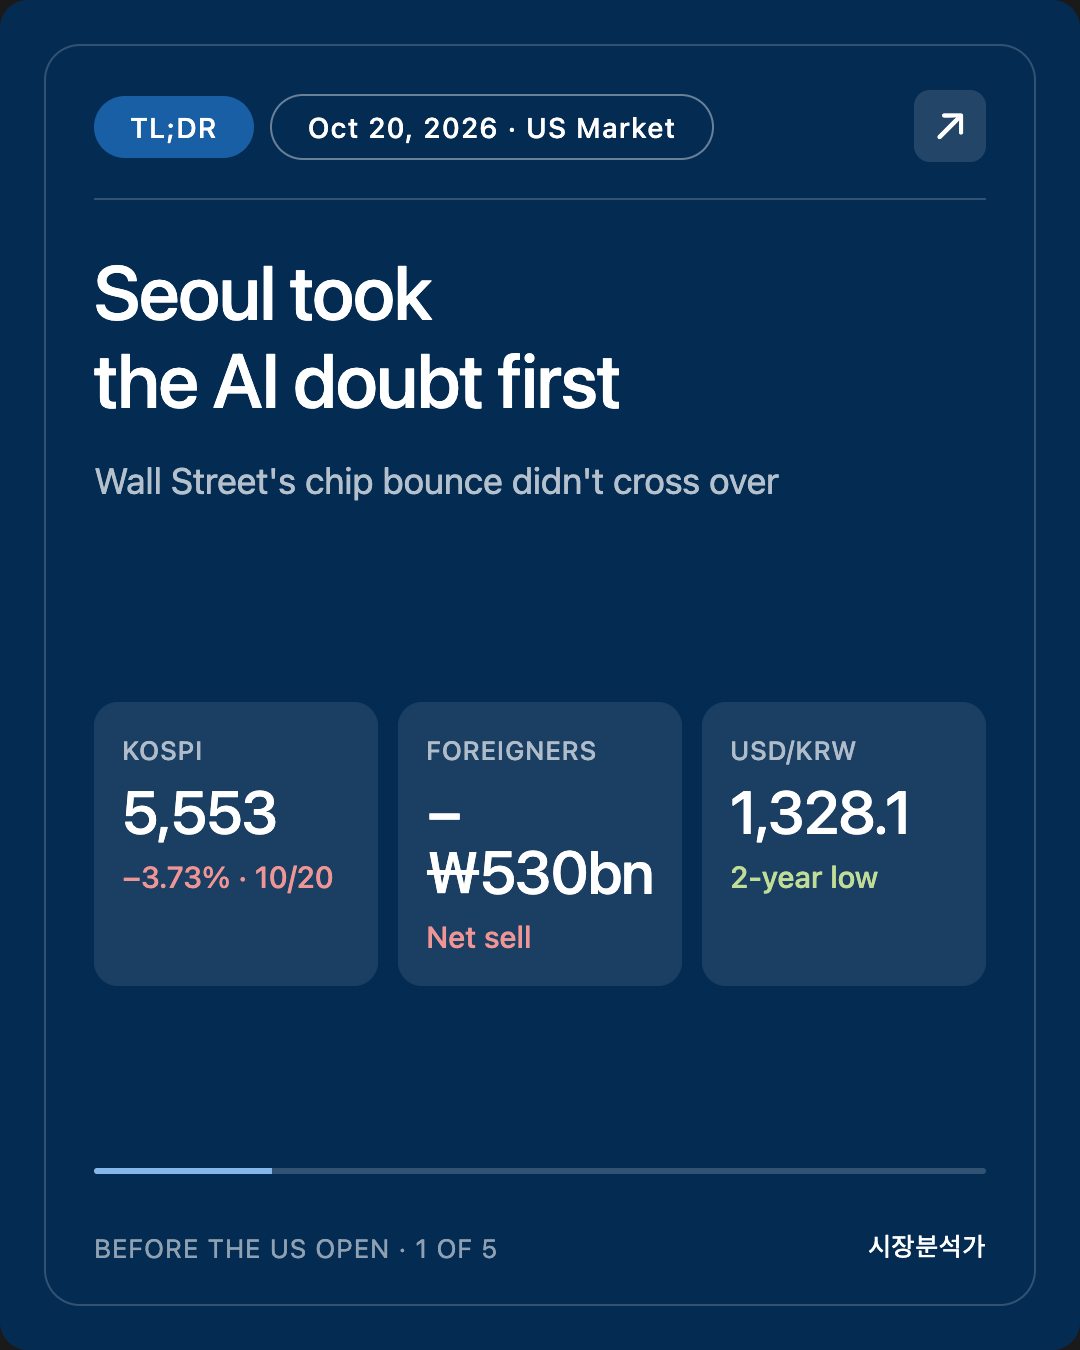
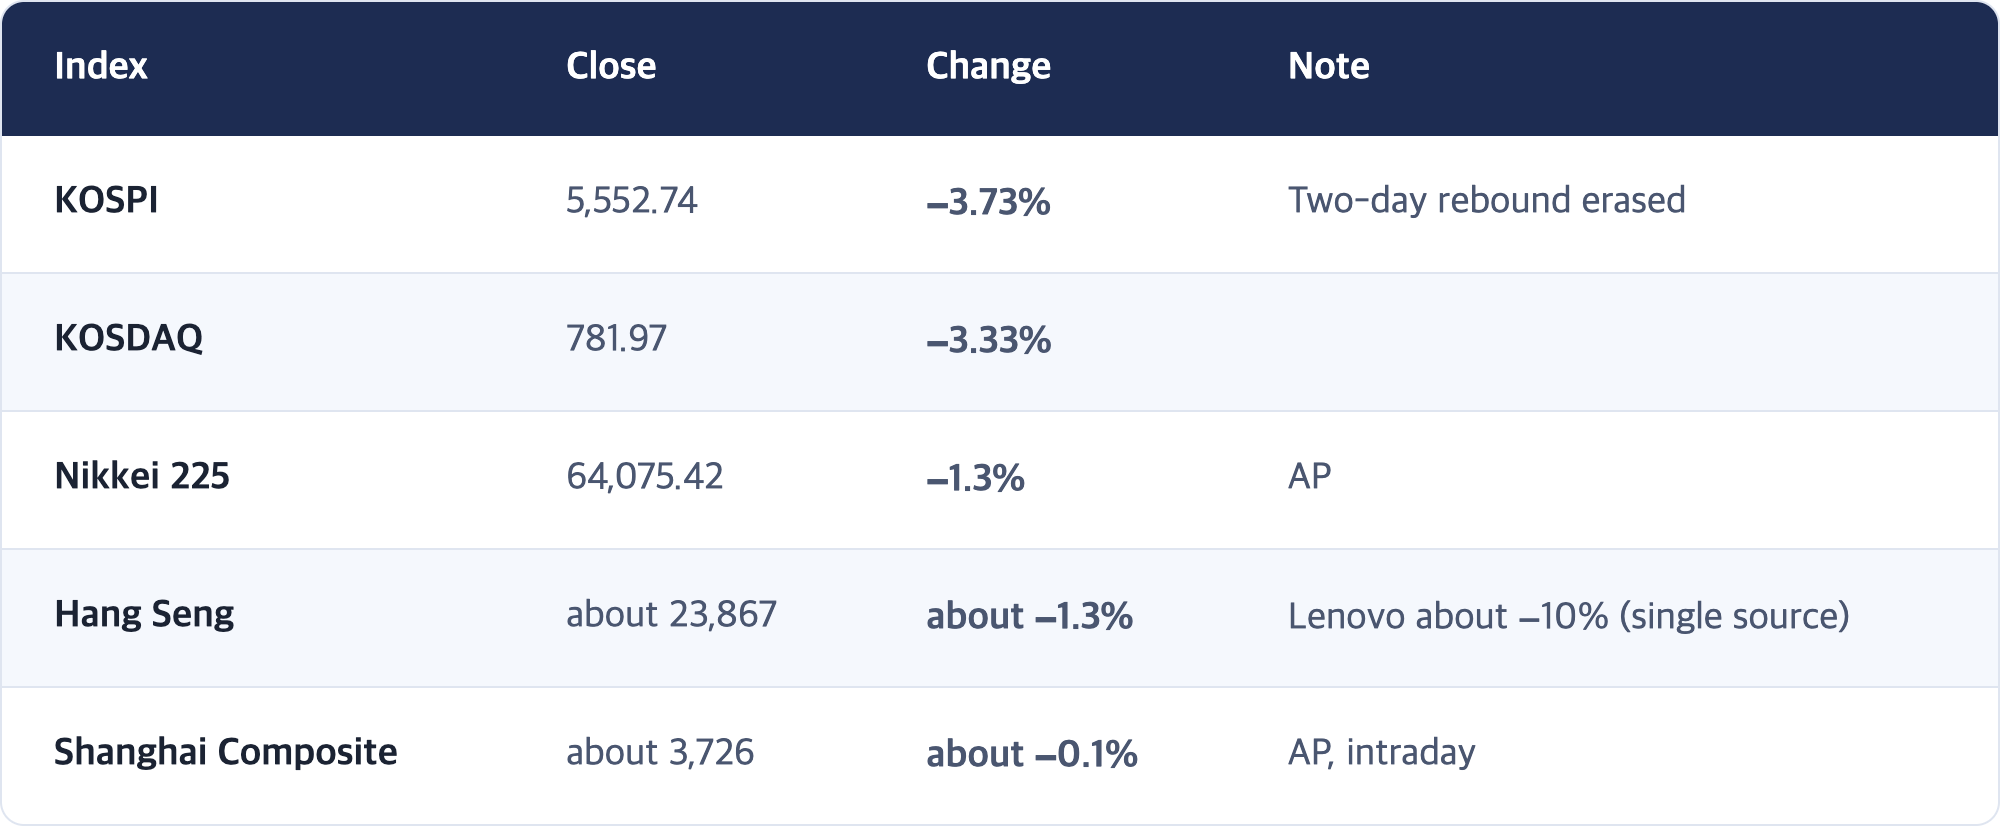
- ★ Seoul took the AI doubt first. KOSPI 5,552.74 (−3.73%), KOSDAQ 781.97 (−3.33%). Foreigners −₩530–538bn, institutions about −₩1tn, retail +₩898bn. SK Hynix −4.23% (−7.36% intraday), Samsung Electronics −2.98%.
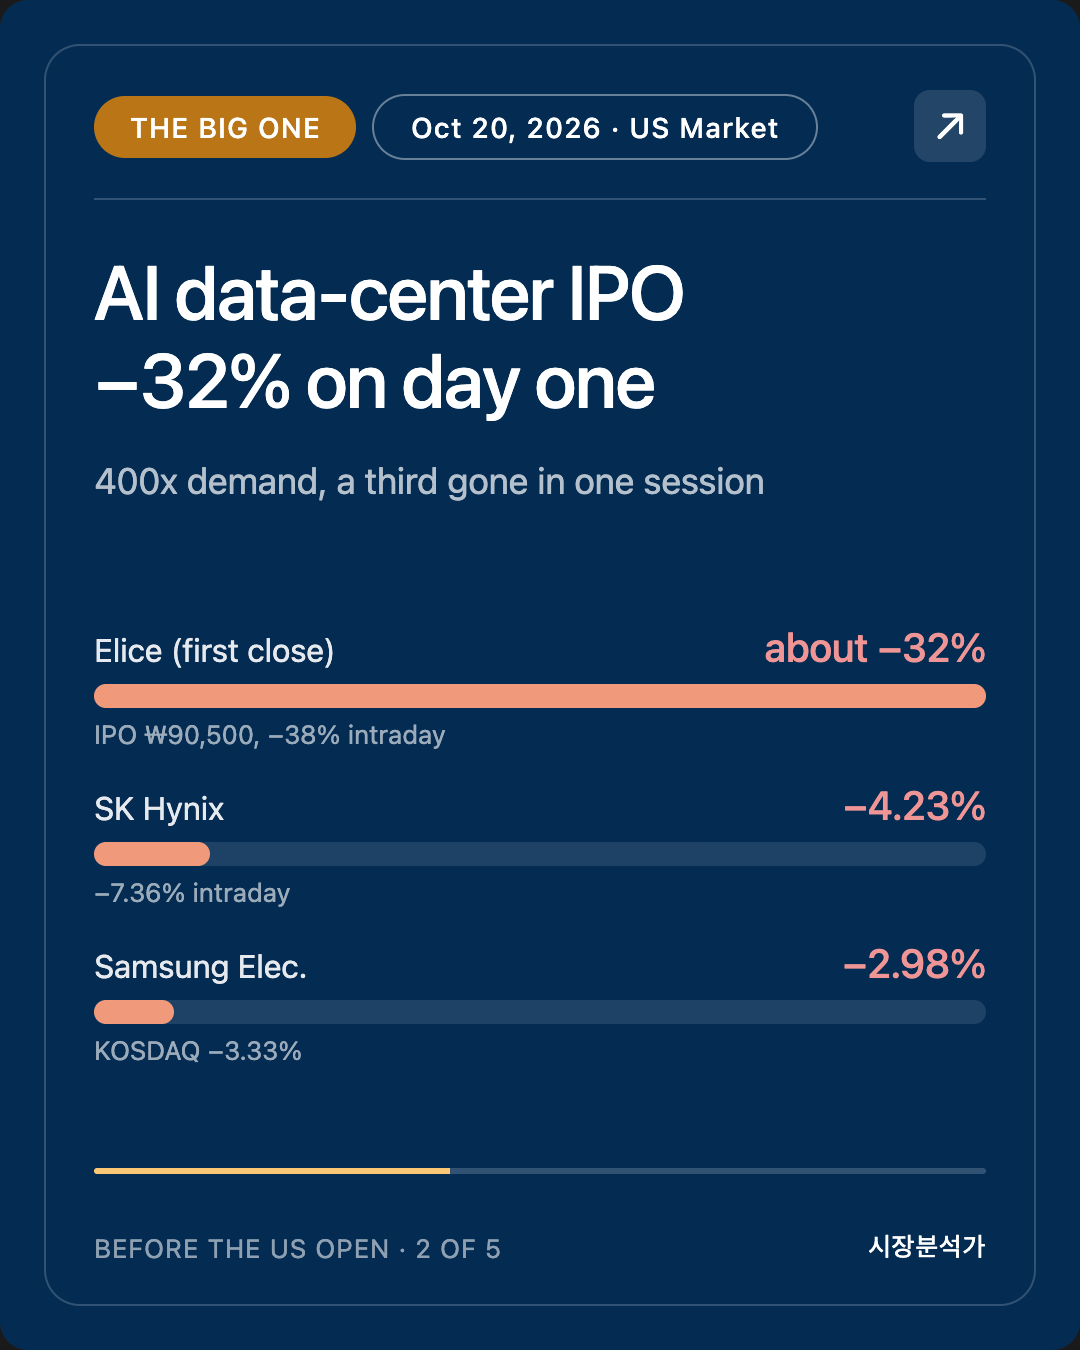
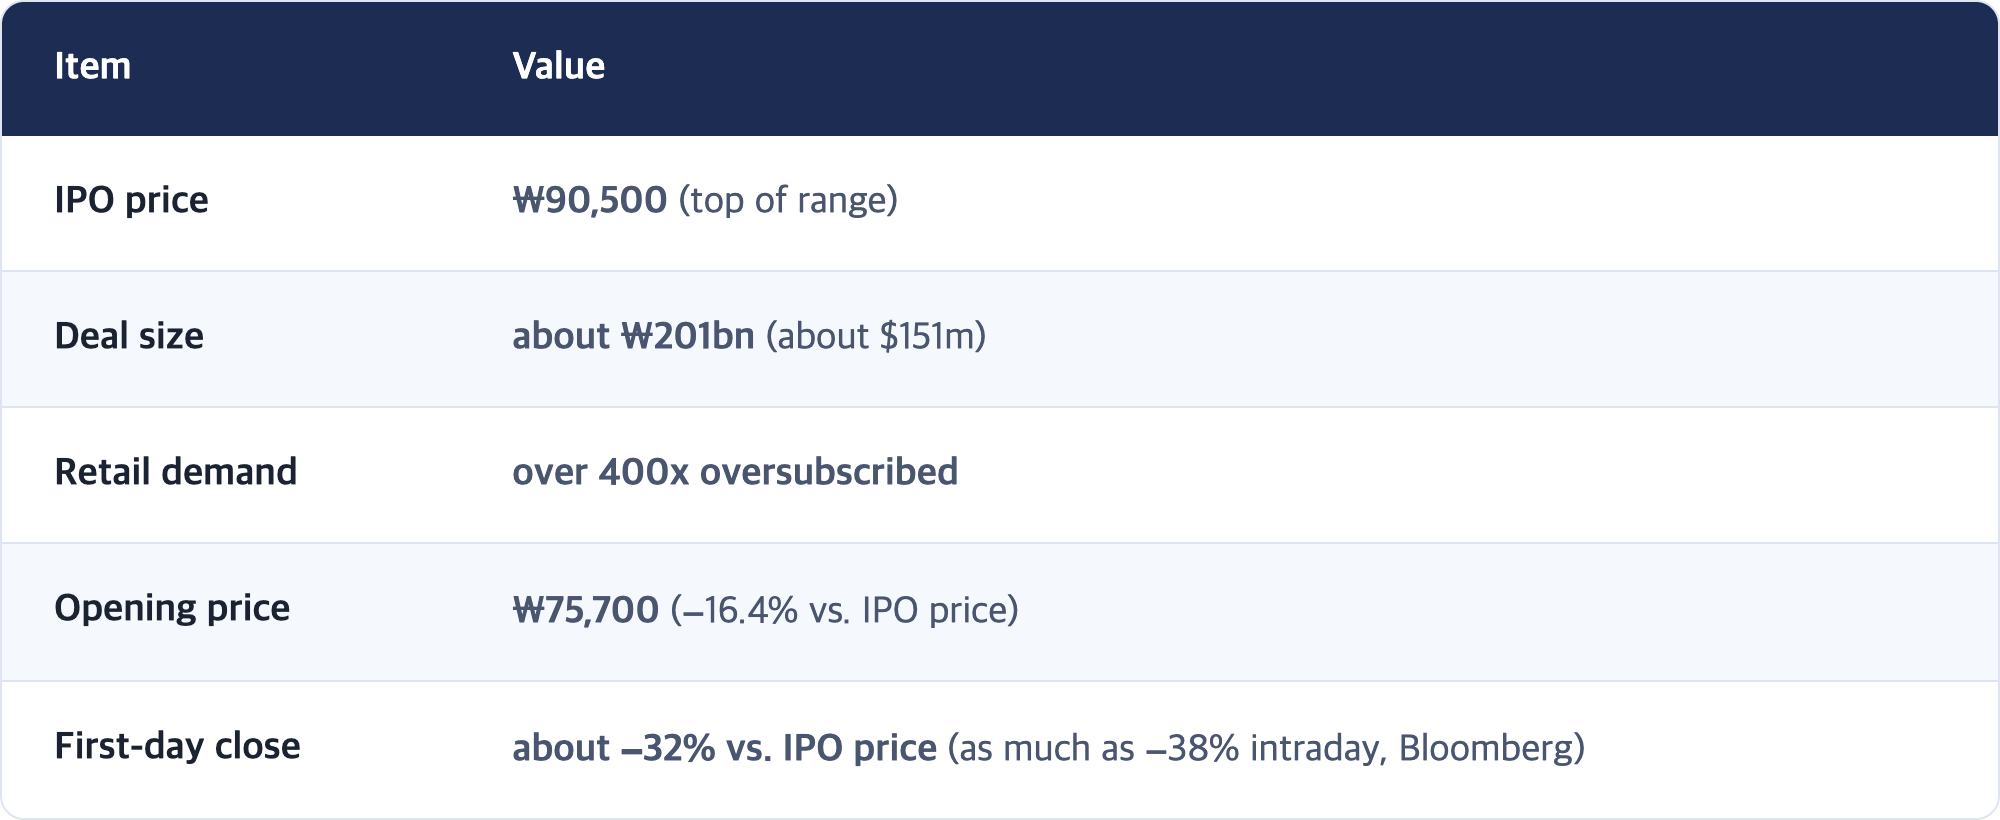
- ★ Elice's debut: about −32%. Priced at ₩90,500 (top of range), raising about ₩201bn ($151m). An AI data-center flop landed on the same day as renewed CoreWeave debt worries.
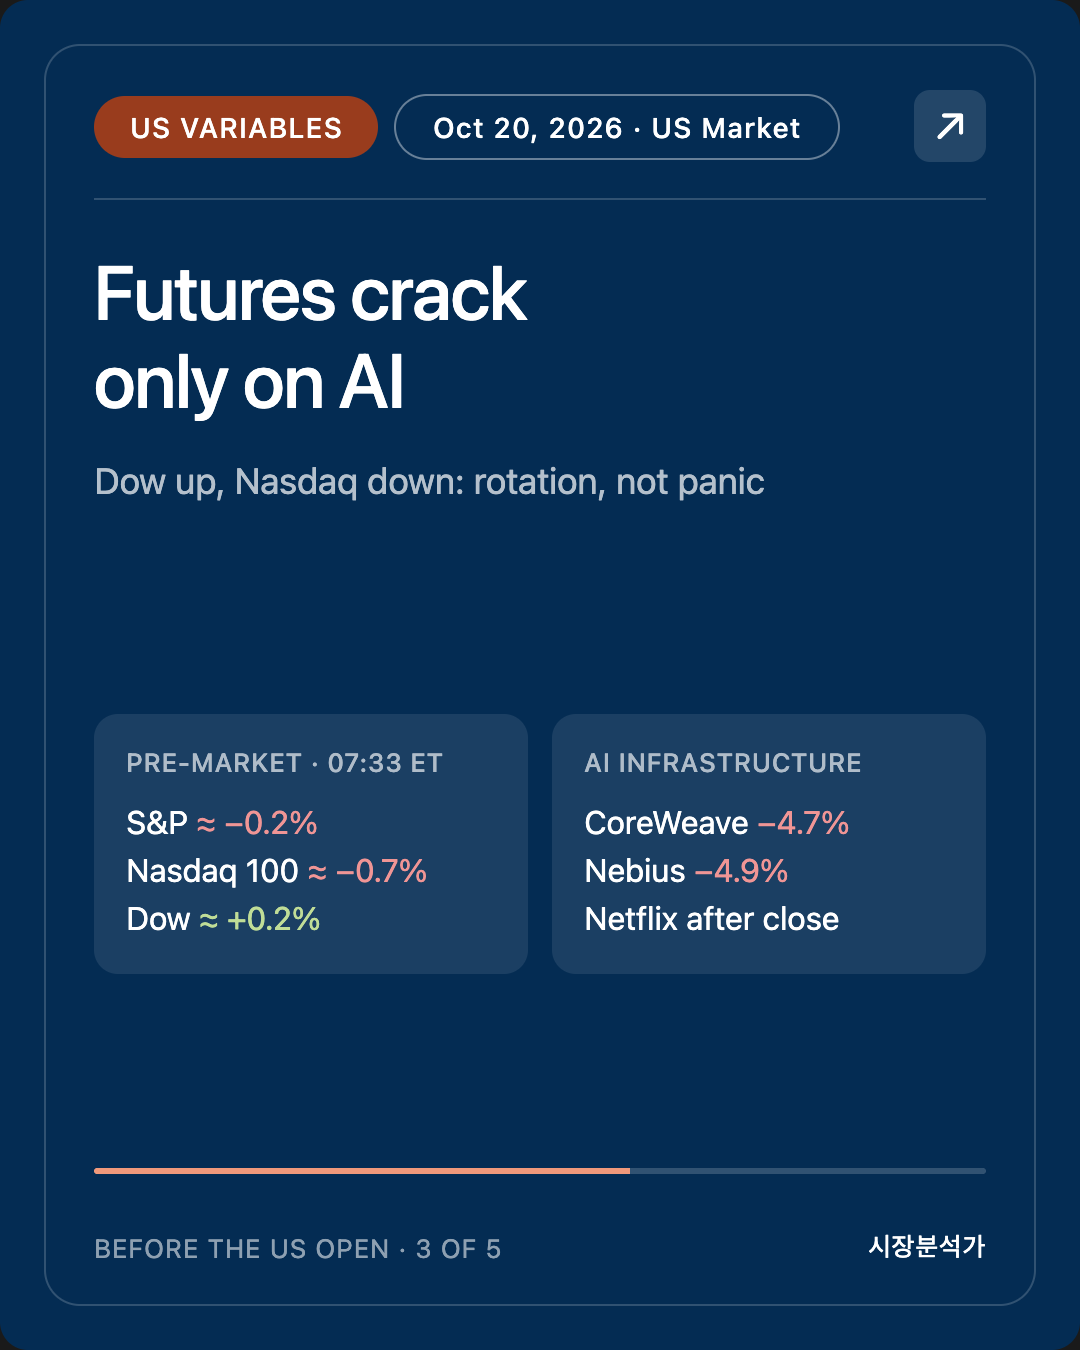
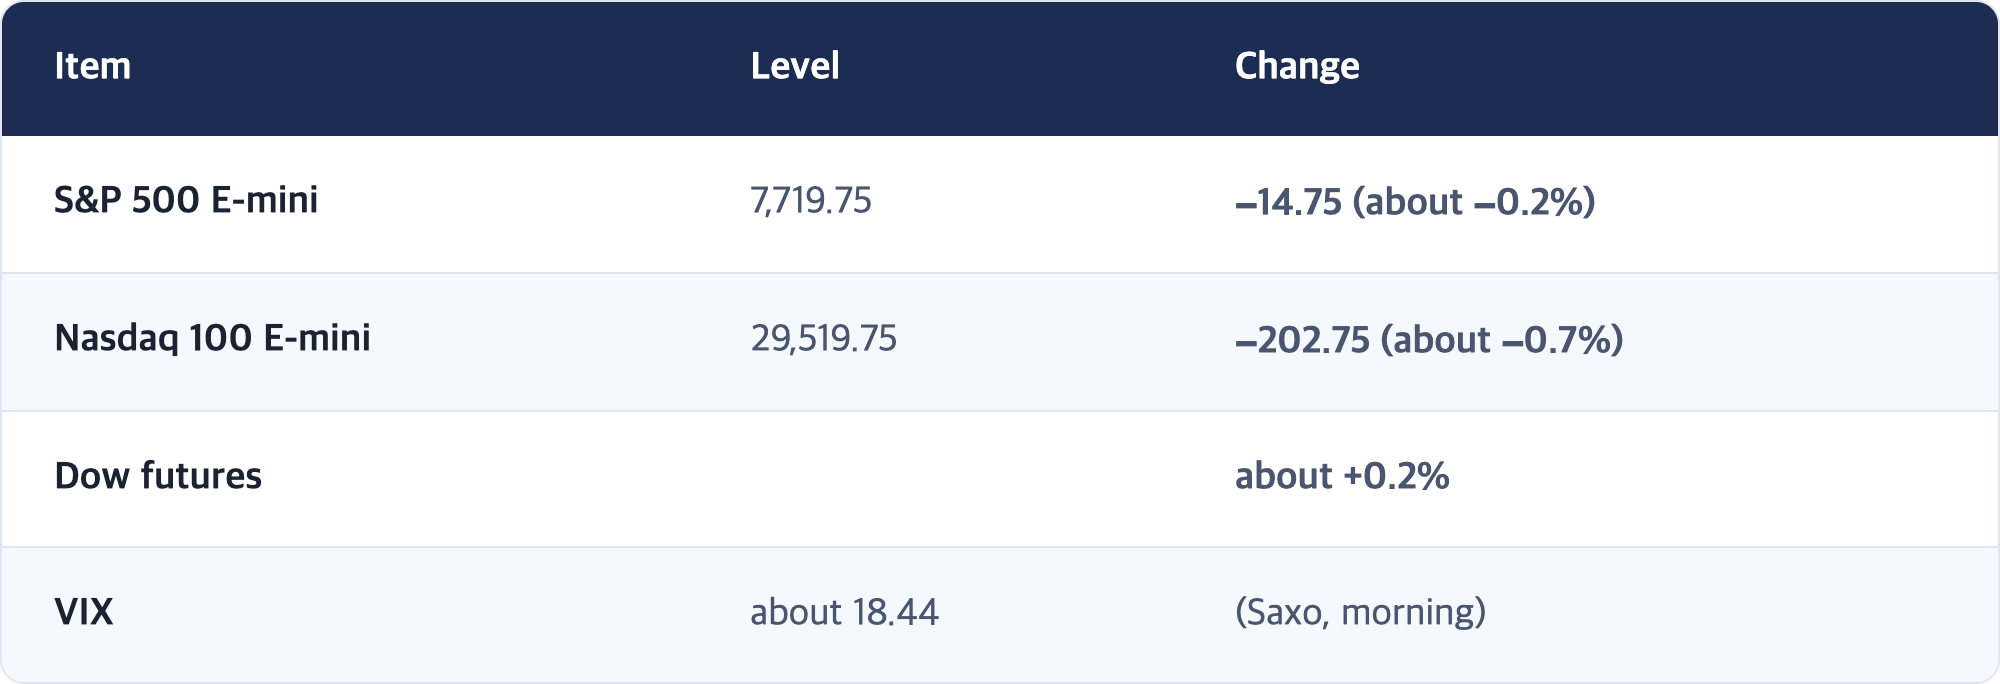
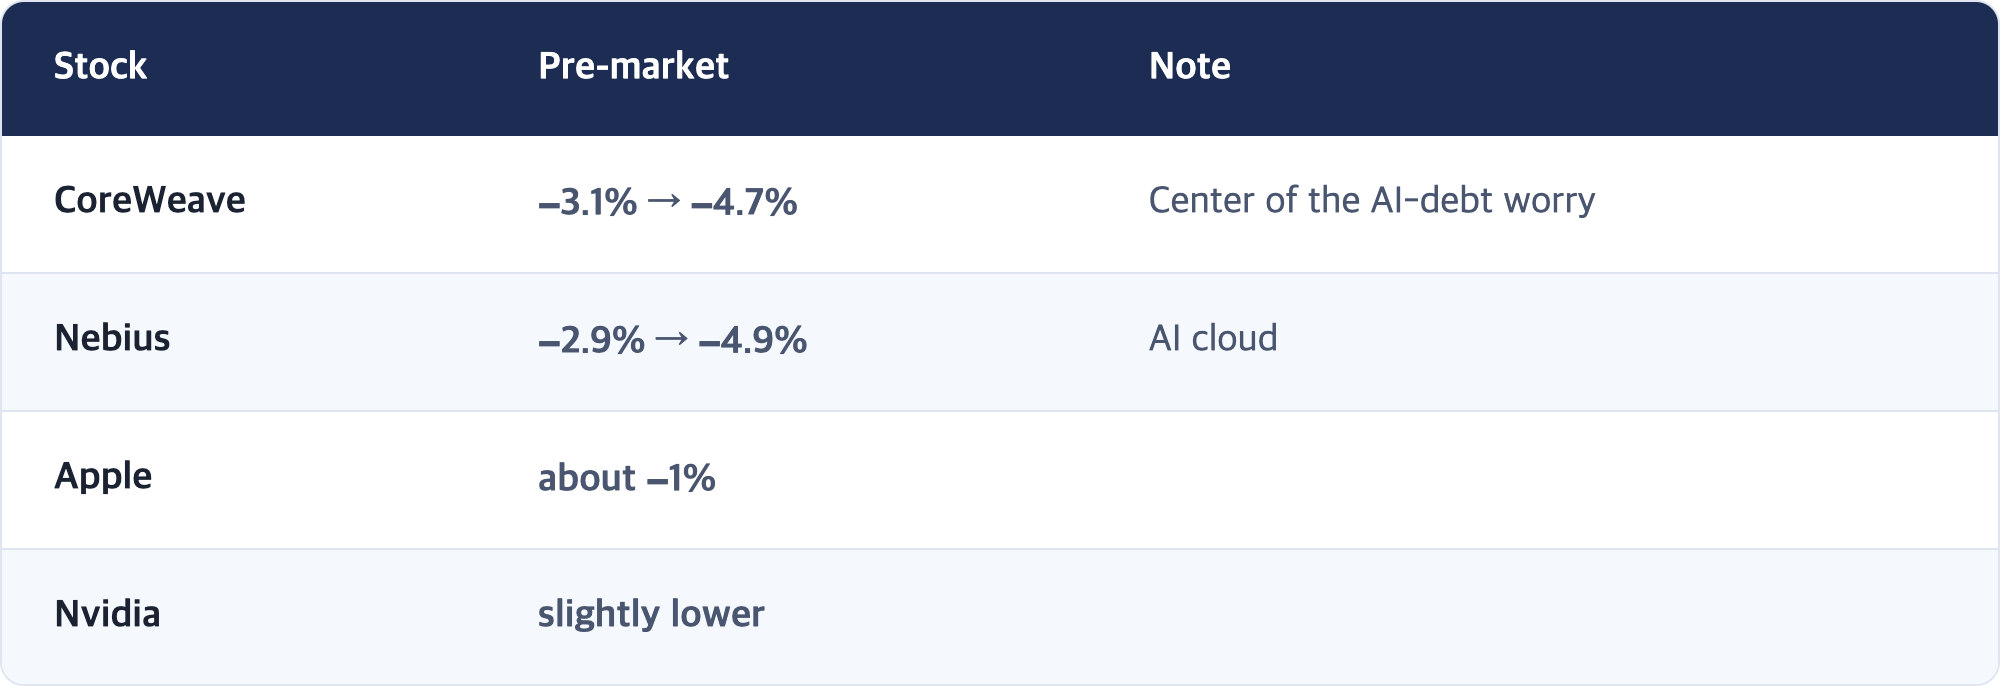
- ★ US futures are cracking only on the AI side. Nasdaq 100 futures about −0.7%, S&P 500 futures about −0.2%, Dow futures about +0.2% (07:33 ET). CoreWeave −4.7%, Nebius −4.9% pre-market.
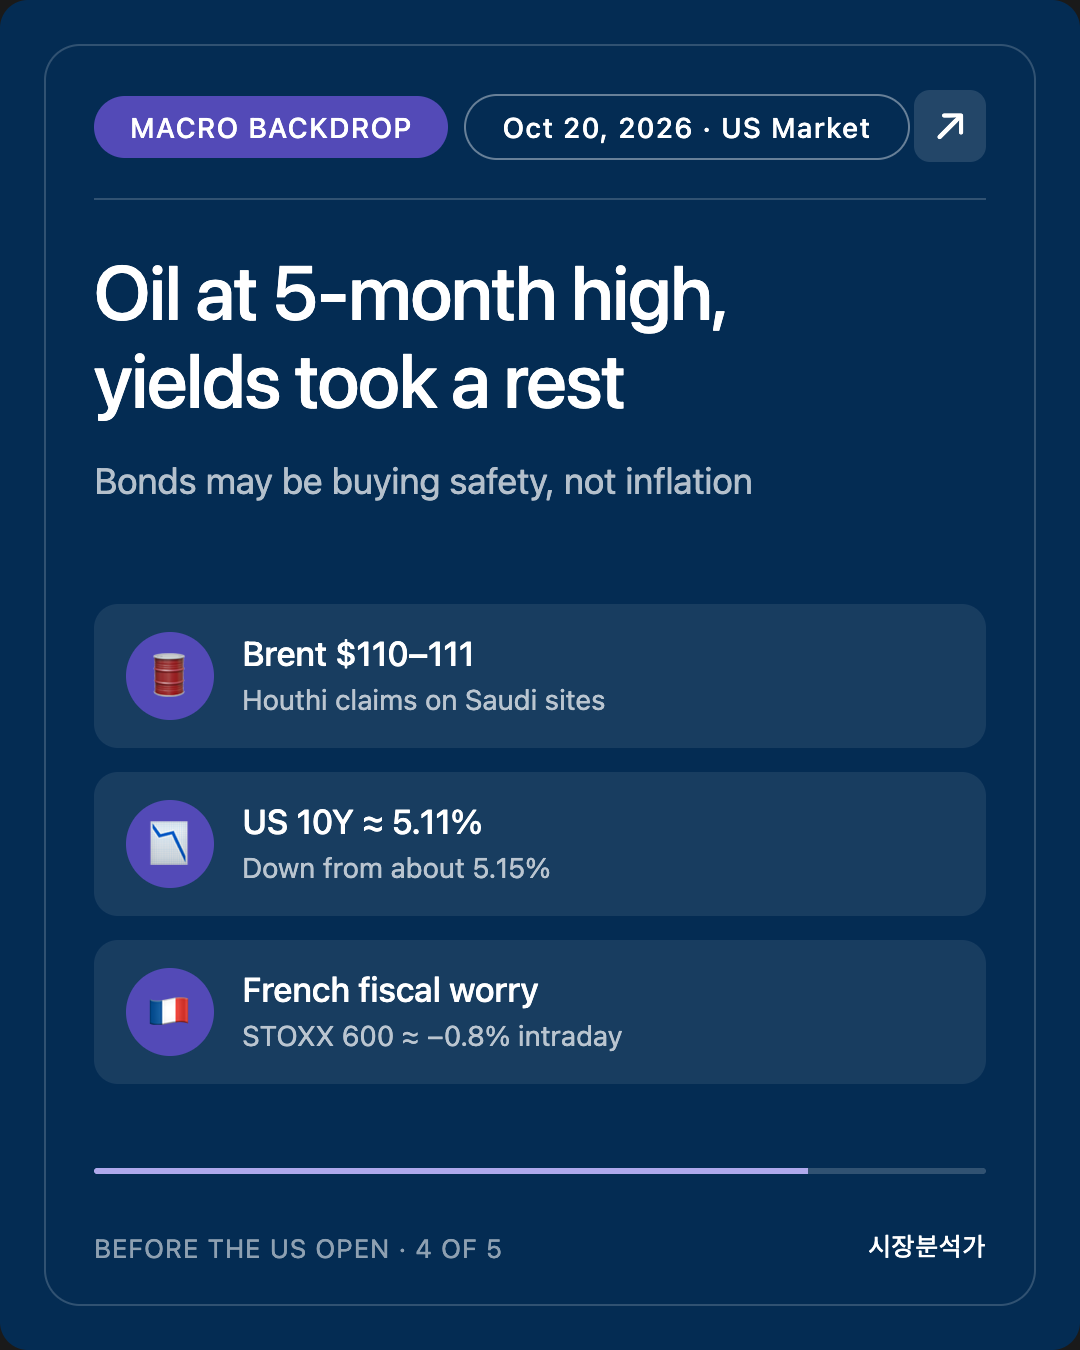
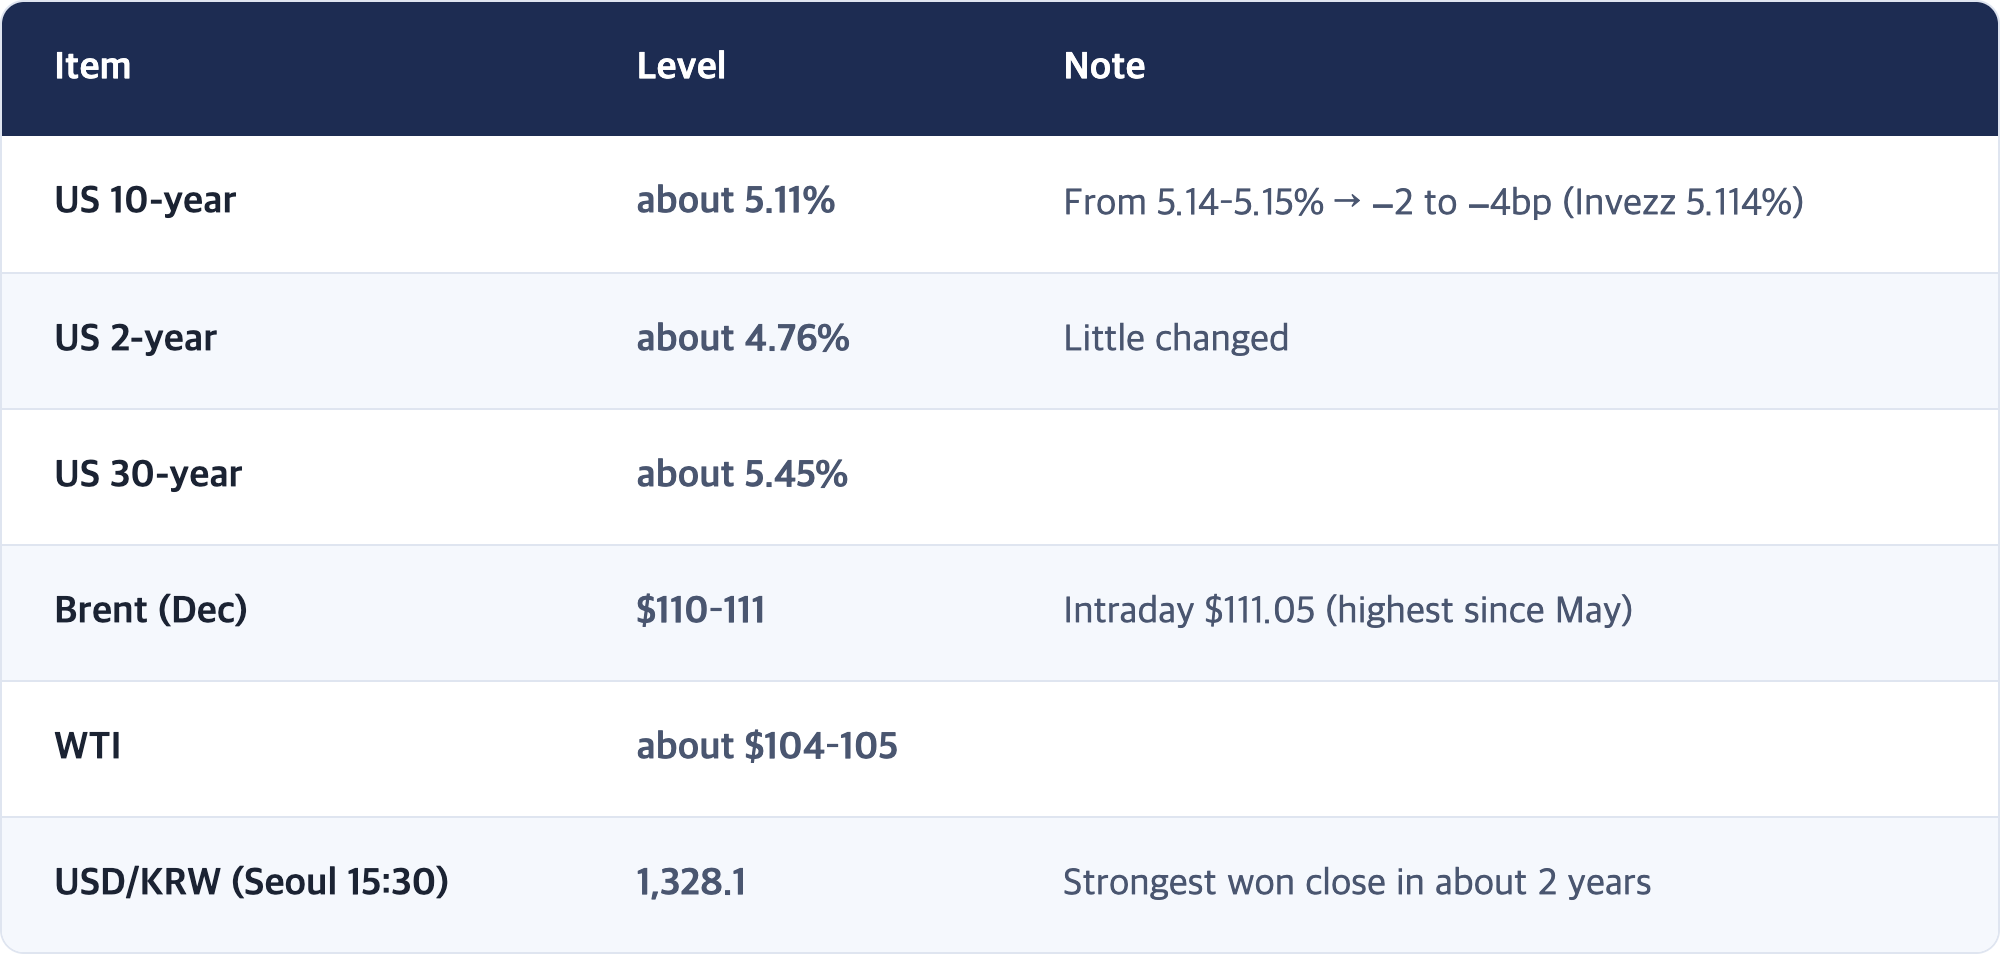
- Oil is at a five-month high. Brent $110–111 (intraday $111.05, highest since May), on Houthi claims of strikes on Saudi sites (unconfirmed by Riyadh) and reported ship attacks in the Gulf. The US 10-year actually eased to about 5.11%.
- The won moved against stocks. USD/KRW 1,328.1 (a fresh year low for a third straight session). Europe fell for a second day on French unrest and fiscal worries (STOXX 600 about −0.8% intraday).
This is Mr. Can. Here is the Oct 20, 2026 brief ahead of the US market open.
Written: 2026-10-20 05:50 PDT (Seoul 10/20 21:50 KST) · work started 05:43 PDT
Basis: Seoul, Tokyo, Hong Kong and Shanghai closes on 10/20 + Europe intraday + US pre-market (around 07:33 ET) + overnight Treasuries
🟢 Scheduled for 05:30 PDT, started 05:43 PDT. Written before the US open (06:30 PDT).
🟢 No missed editions. The previous one was the 10/19 PM brief (Korea 10/20 preview).
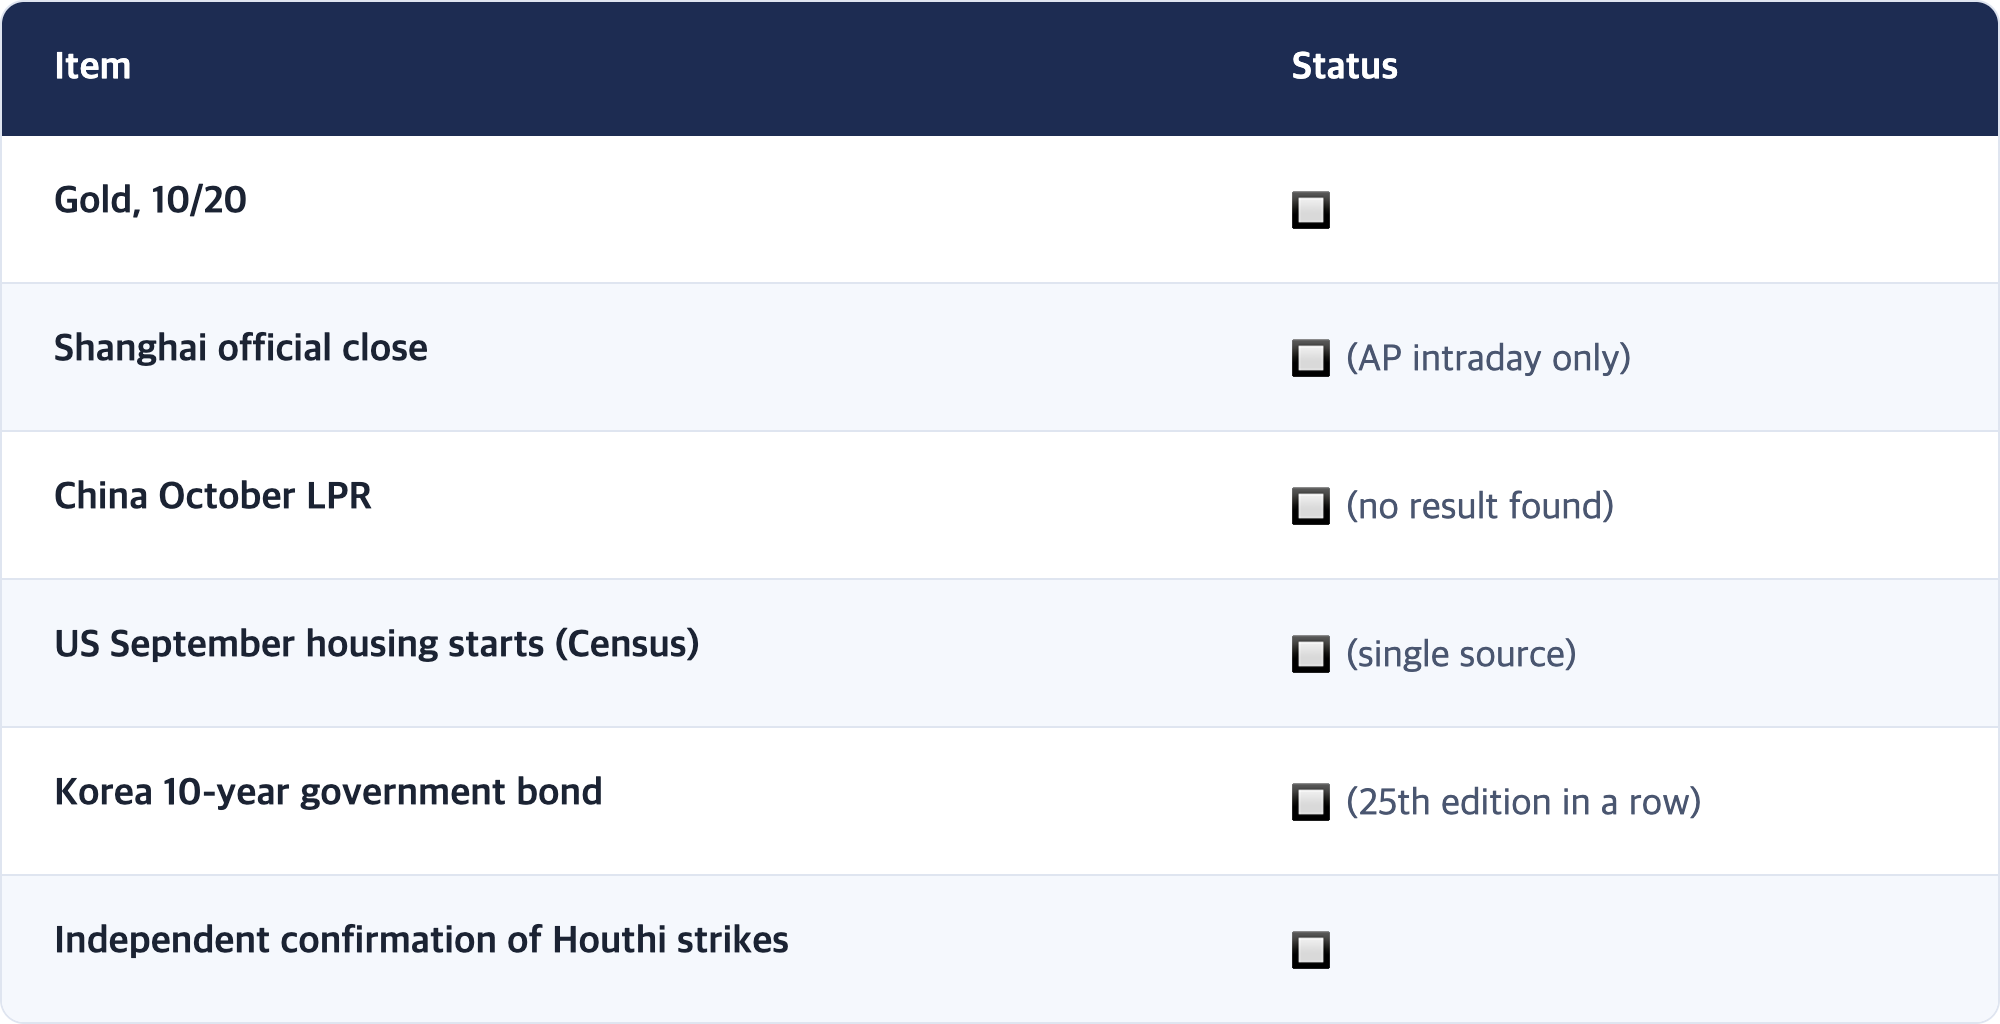
🟡 Gold, official Shanghai and Hang Seng closes, and Korea's 10-year government bond yield were not available (see section 7).
SEO Intro
Seoul did not take Monday's Wall Street chip rebound. Korea's KOSPI closed −3.73% at 5,552.74, giving back two days of gains in one session, and briefly fell below 5,500 (low 5,493.24). Foreign investors sold a net ₩530–538 billion (about $400 million) and institutions about ₩1 trillion. SK Hynix fell 4.23% and Samsung Electronics 2.98%.
On the same day, Elice, a Korean AI data-center company, debuted on the KOSDAQ and closed roughly 32% below its IPO price, the worst first day for a sizable Korean IPO on Bloomberg's records. Retail demand had been more than 400 times oversubscribed. The market read it as a blunt question: does financing AI infrastructure actually pay?
Yet the won got stronger, not weaker, closing at 1,328.1 per dollar, its strongest close in about two years. US futures are split: Nasdaq 100 futures about −0.7%, Dow futures +0.2%, with CoreWeave and Nebius down 4–5% pre-market. Today's question for Wall Street: was Monday's chip bounce a one-day event, or did Seoul simply flinch first?
1. Checkpoint Scorecard
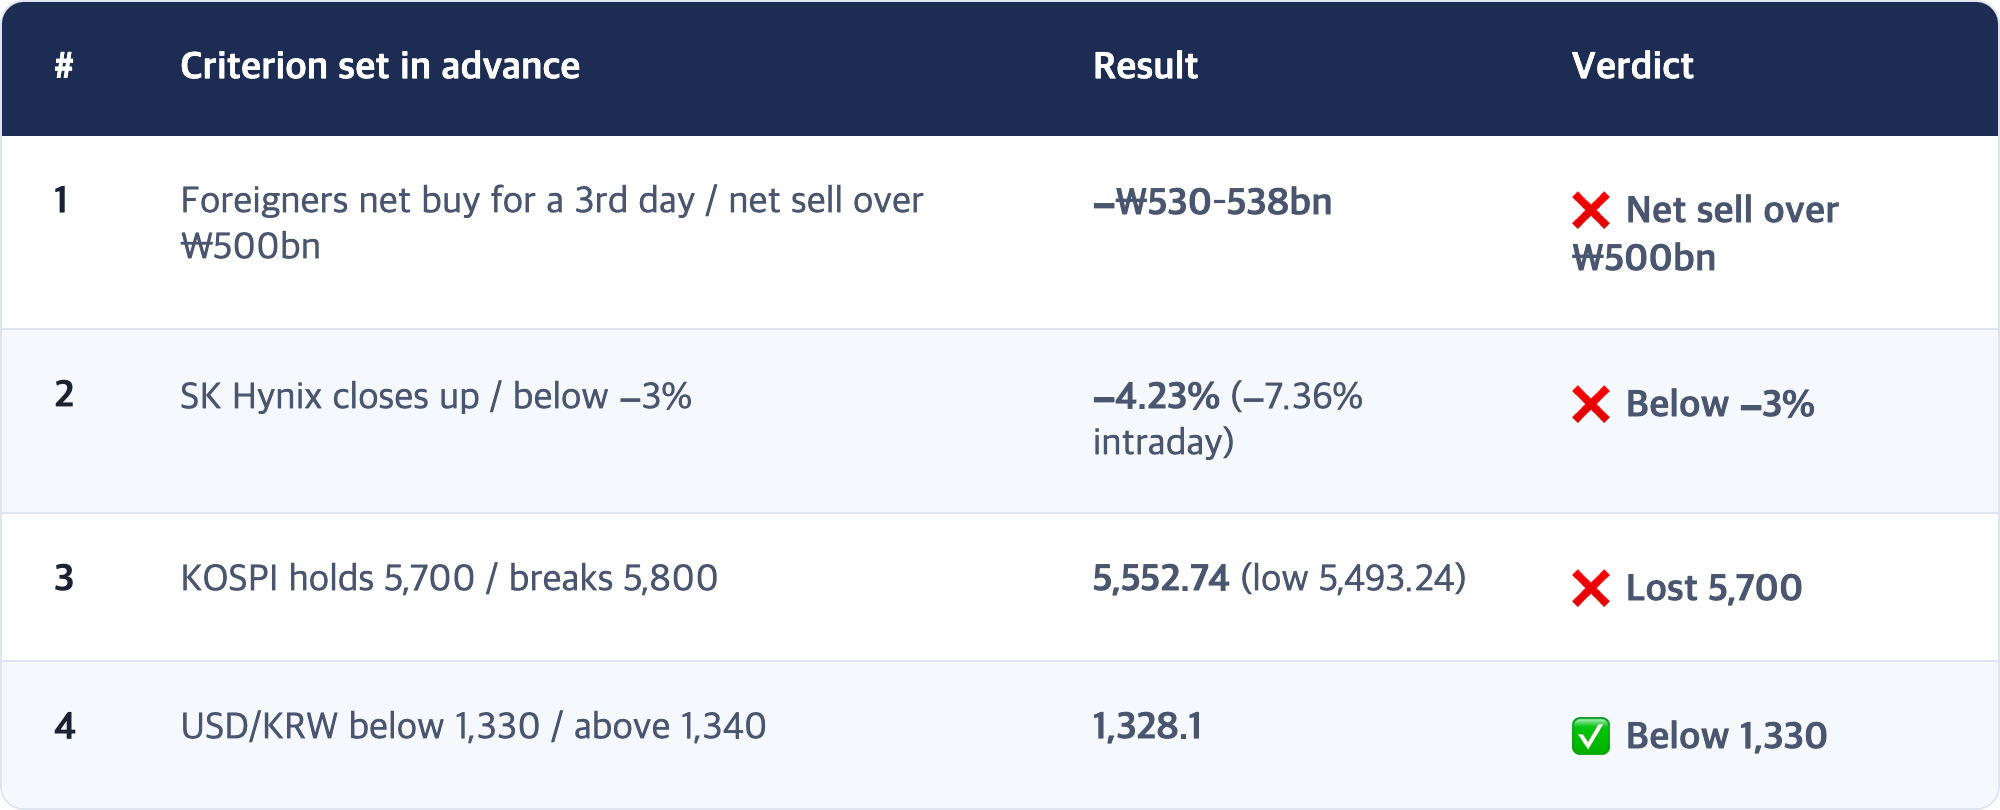
The four from the 10/19 PM brief (Korea close, 10/20)
The axis was "does Wall Street's chip rebound cross over to Seoul's chipmakers, or does Seoul keep moving only outside chips?" The third-variable slot was left for the US 10-year yield.
★ [Interpretation] The third variable was not rates
The 10/19 PM brief said that if foreigners sold more than ₩500bn, Monday's buying was probably a one-off, and to check whether the 10-year was above 5.15%. Checkpoints 1–3 all came in on the bad side. But the 10-year slipped overnight to about 5.11%. Rates did not push Seoul down.
[Observation] Checkpoint 4 is the odd one. Foreigners sold over ₩500bn, and the won still strengthened. If foreigners were pulling money out of Korea, the won would normally weaken. A stronger won suggests this was not "selling Korea" but "selling AI and chips inside Korea" (interpretation).
[Interpretation] A rule we wrote on 9/28 held again: build the axis on two options (rates vs. flows) and a third variable walks in (doubt about AI returns, crystallised by the Elice debut). The verdict (bad) was right; the explanation (rates) was wrong.
2. The Big Picture: Seoul Took the AI Doubt First
[Fact] Asia closes, Tue 10/20
[Fact] Elice's first day (KOSDAQ)
★ [Interpretation] Seoul is the market most sensitive to "who is paying for AI?"
Monday's US chip bounce was mostly a rebound from oversold levels (10/19 PM), and CoreWeave still closed lower that day. On Tuesday Seoul took the side of that unresolved worry. Korean press pointed to CoreWeave's credit risk feeding into possible capex cuts by Big Tech, plus Chinese memory makers catching up.
[Observation] Elice is the symbol. Retail investors piled in at over 400 times the allotment, and a third of the value vanished on day one. The institutions that set the price and the people trading on the first day had very different views. One fund manager called AI-infrastructure sentiment "disconnected from fundamentals," while another analyst said Elice's finances look nothing like CoreWeave's. Both can be true.
[Interpretation] So Seoul's −3.73% reads better as "AI funding → chips" than "rates → chips." The same channel showed up on 10/16, when the KOSPI triggered a circuit breaker.
3. US Variables: Futures Are Cracking Only in AI Infrastructure
[Fact] US pre-market (CNBC, 07:33 ET)
[Fact] Pre-market movers (varies by timestamp)
[Fact] US September housing starts (08:30 ET, single source)
- Starts 1.221 million (consensus about 1.305 million), permits 1.400 million (consensus about 1.385 million).
- 🟡 Seen in one outlet only. Not used for any verdict until checked against the Census release.
★ [Interpretation] Dow up, Nasdaq down is rotation, not panic
S&P 500 futures are only about −0.2%, while the Nasdaq 100 is −0.7% and the Dow +0.2%. Money is not leaving the market; it is moving from AI to everything else. An ActivTrades analyst called it "a dip inside a selective market."
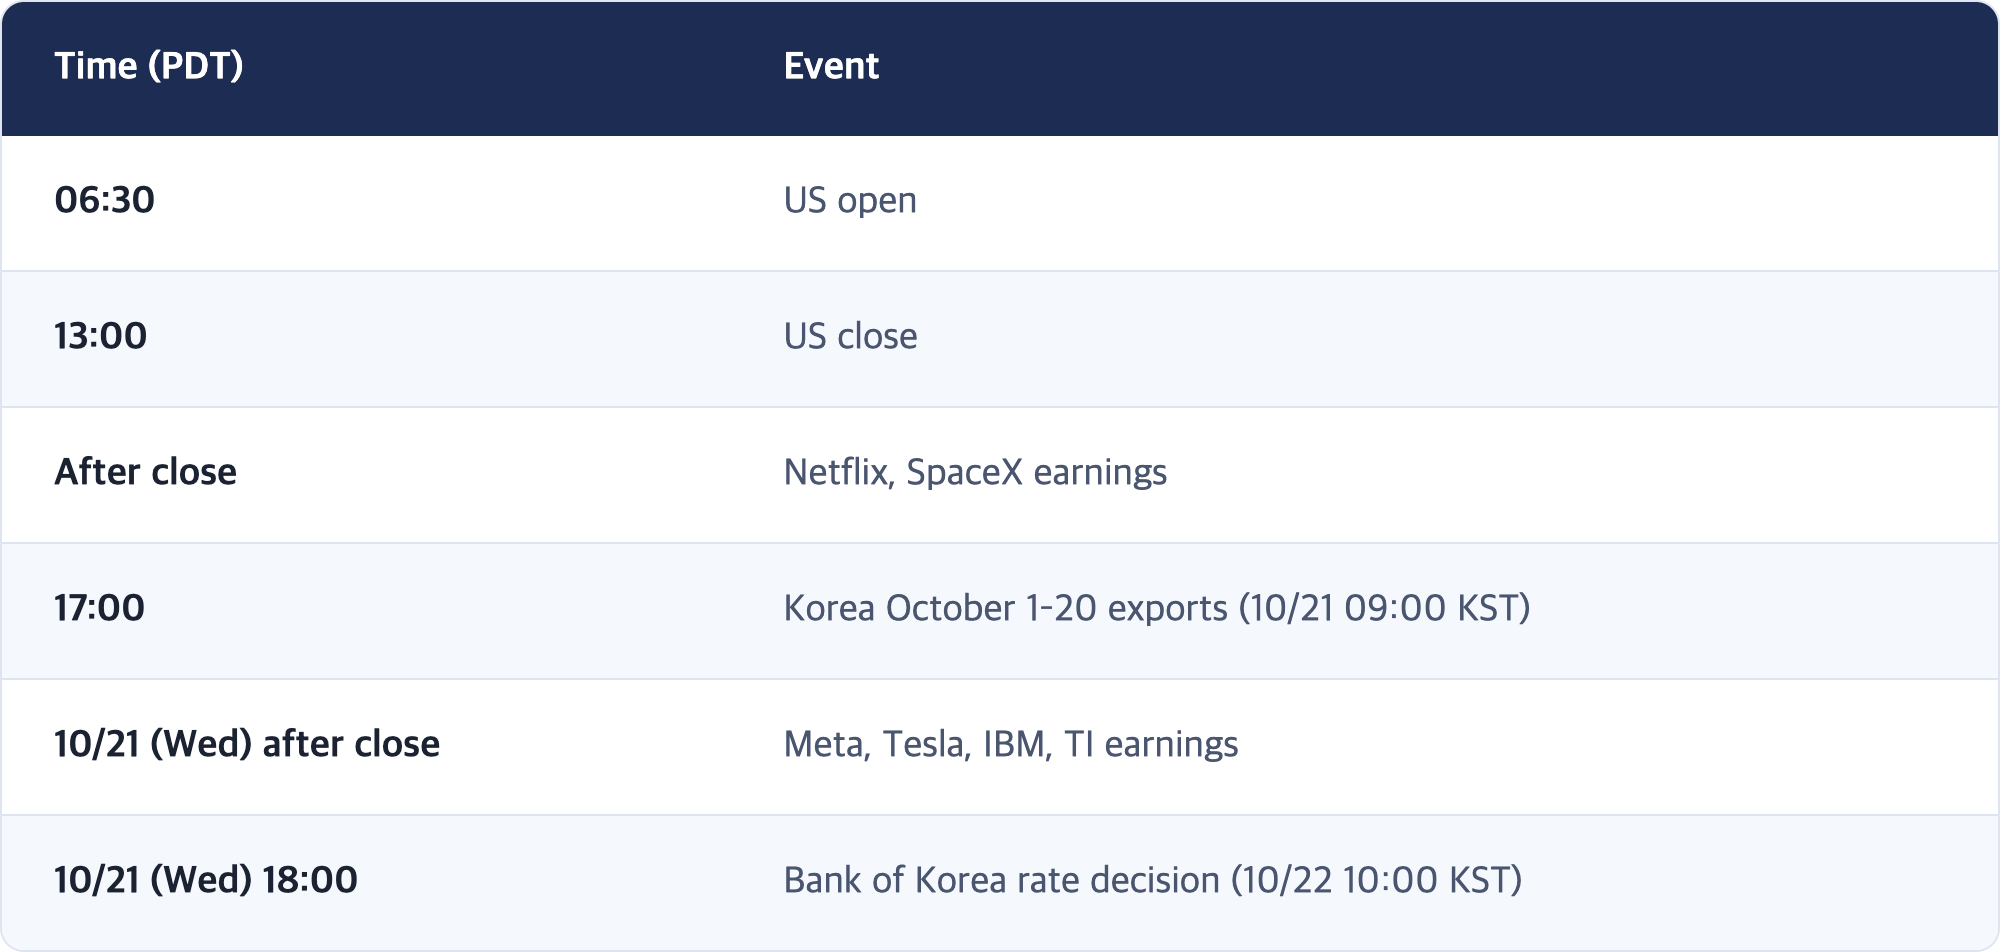
[Observation] Netflix and SpaceX report after today's close, then Meta and Tesla on Wednesday. Meta is where AI capex guidance lands. Whether Seoul was right to price in "Big Tech may cut spending" gets its first hard number Wednesday evening with Meta.
4. Macro Backdrop: Oil at a Five-Month High, Rates Resting, Europe Watching France
[Fact] Rates, FX and commodities (morning of 10/20)
[Fact] What lifted oil
- Houthi claims of strikes on Saudi sites: energy and airport facilities. Saudi authorities have not confirmed.
- Reported ship attacks in the Gulf: Kpler counts at least 18 vessels allegedly attacked over two weeks.
- Iran's exports at zero: reported under the renewed US naval blockade (Saxo).
- ING said the risk premium could fade if flows continue, but "no signs of this yet."
[Fact] Europe
- STOXX 600 intraday about 634.68 (−0.76%), DAX intraday about −0.4%. The DAX closed Monday at 25,319.77 (−1.18%).
- Protests in France and Italy revived worries about government finances and borrowing costs; French government bonds sold off hard.
★ [Interpretation] Oil up, yields down: bonds may be buying safety, not pricing inflation
Usually higher oil means inflation worries and higher yields. Today Brent is at a five-month high and the 10-year edged lower. Several notes said Treasuries were bought as a safe haven while stocks wobbled. It is the same shape as a pattern we flagged on 10/17: "when inflation looks worse and yields fall anyway, bonds are buying fear, not inflation" (interpretation).
[Observation] The Fed is in its blackout period and the 10/28 FOMC is expected to hold. US data are light this week. Oil and AI earnings, not rates, are the two forces likely to move Wall Street this week.
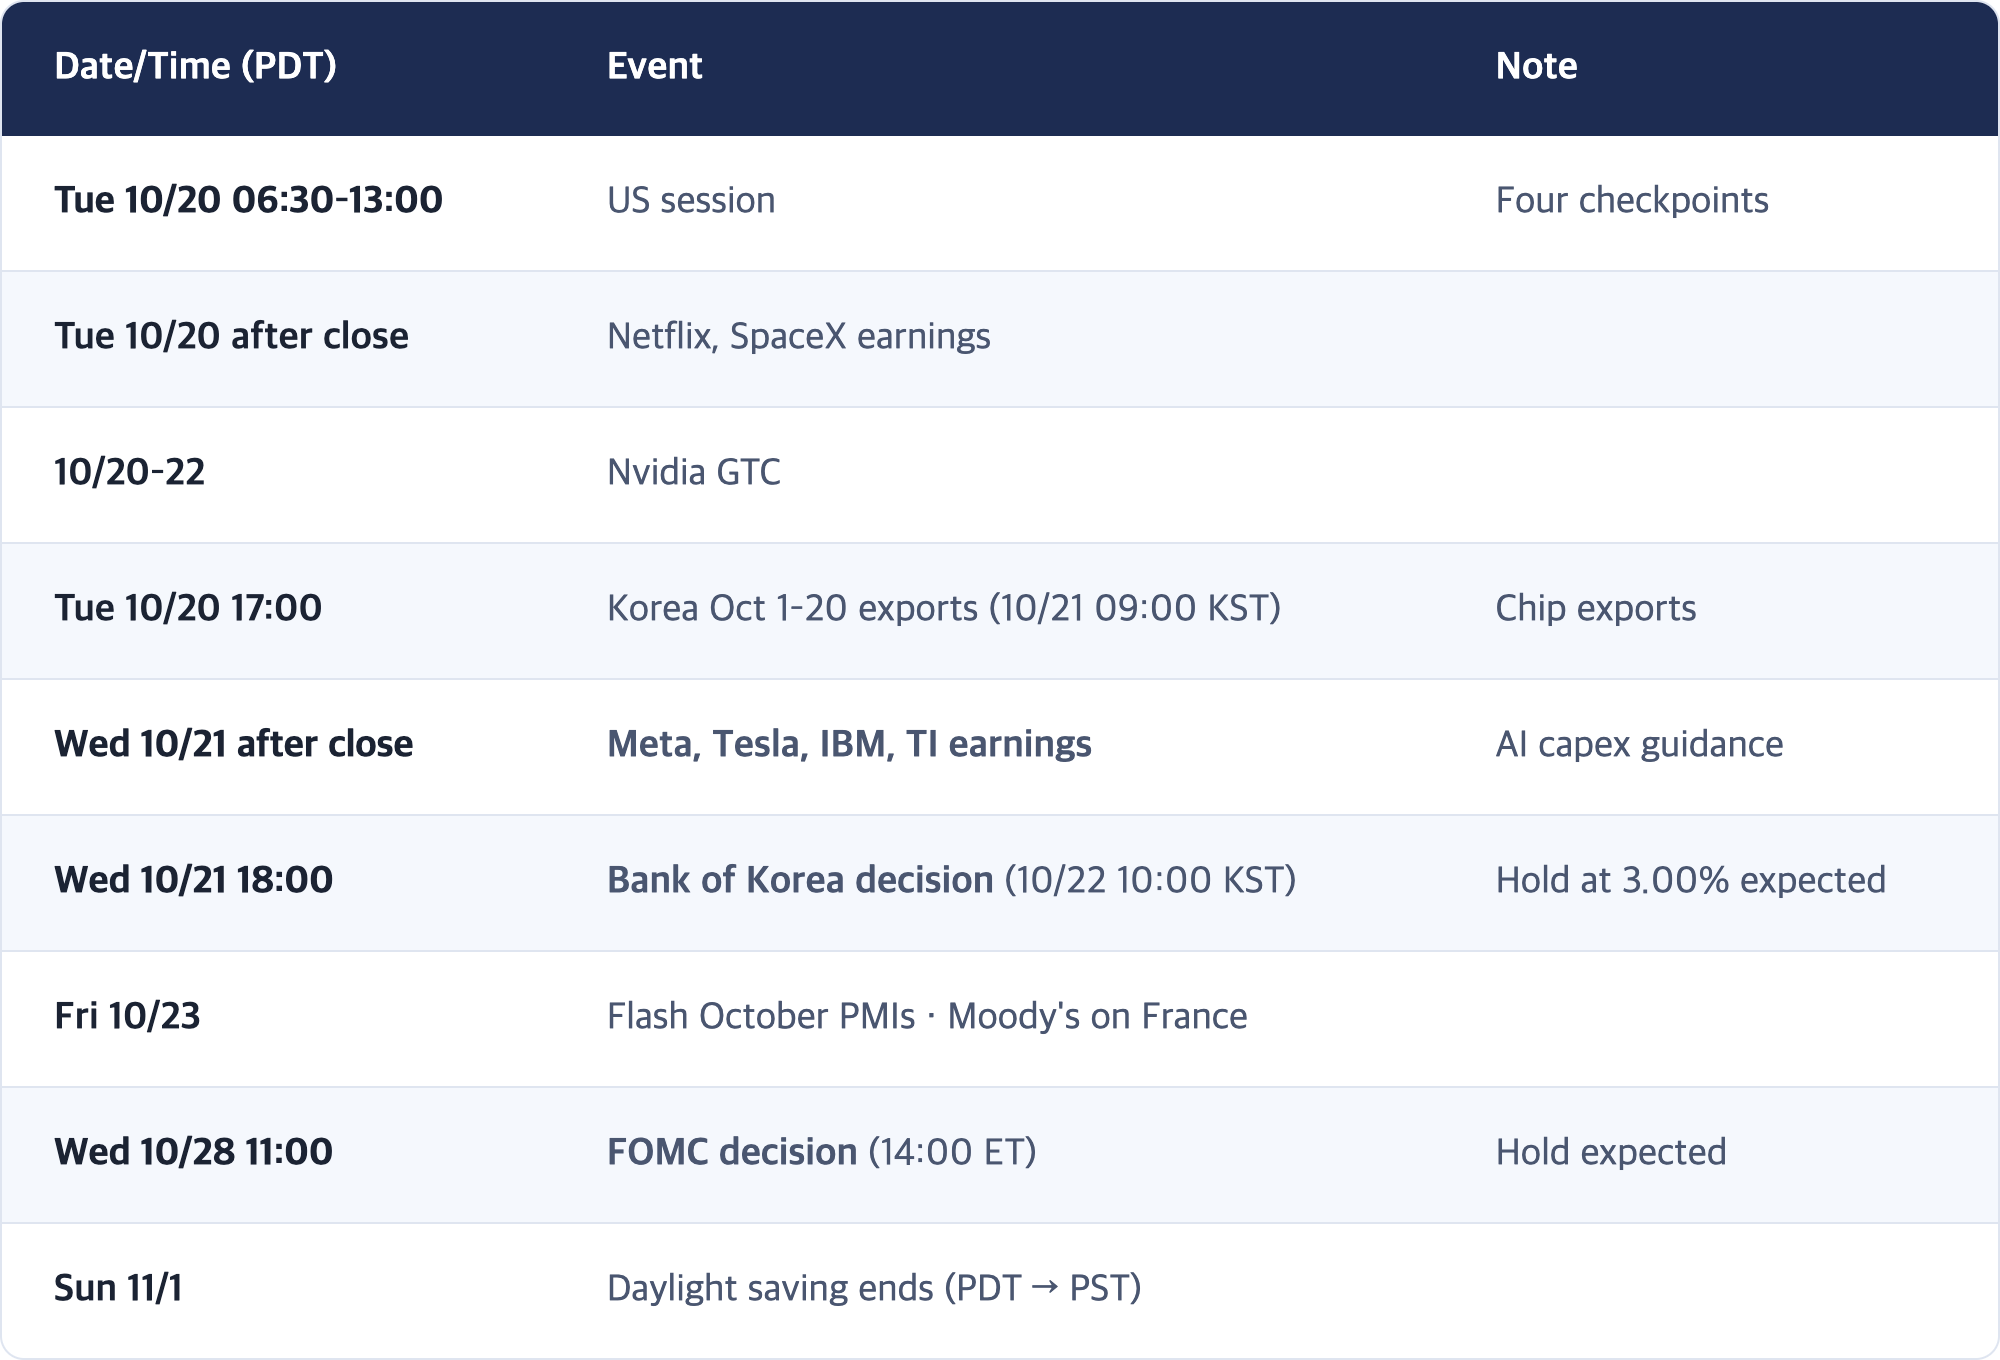
5. Today (Tue 10/20) in US Markets: Checkpoints
[Observation] Remaining schedule (PDT)
✅ Four checkpoints (by today's US close)
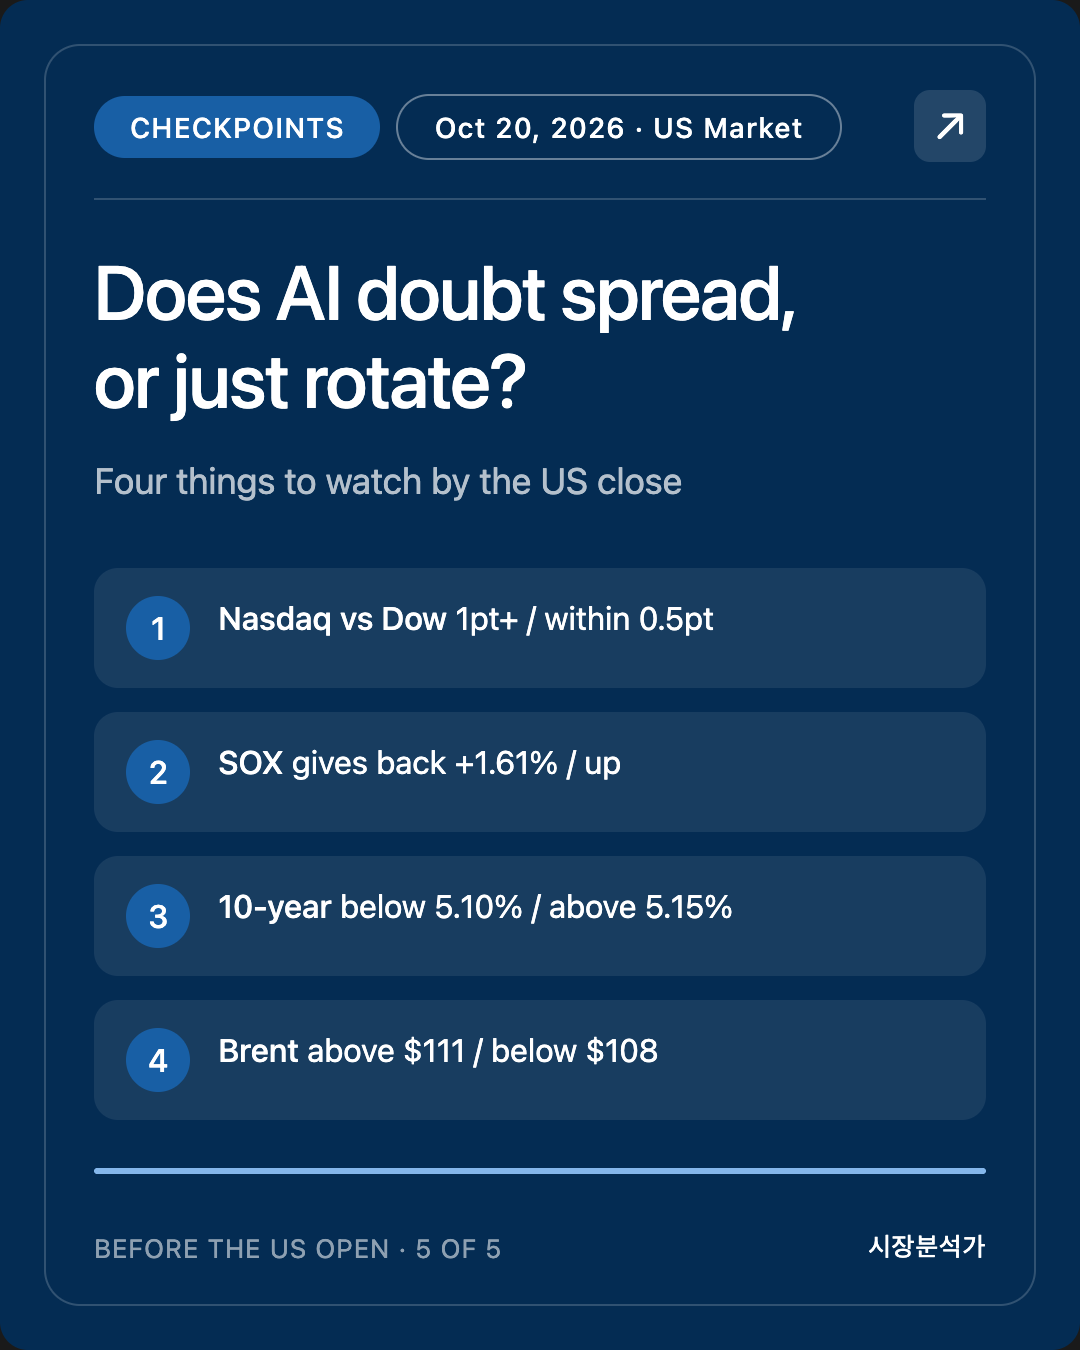
The axis: "does Seoul's 'who funds AI?' doubt spread to Wall Street, or does New York just rotate out of chips?" The third-variable slot goes to oil.
- Nasdaq vs. Dow gap: 1 point or more / within 0.5 point. A gap over 1 point means the rotation out of AI is real.
- SOX gives back all of Monday's +1.61% / closes higher. Giving it all back makes Monday a one-day bounce.
- US 10-year closes below 5.10% / above 5.15%. Falling yields with rising oil is the "bonds buying fear" shape.
- Brent (Dec) above $111 / below $108. Does it break the five-month high?
[Interpretation] A 1-point-plus gap and a full SOX giveback would mean Seoul's drop was simply an early signal. A gap within 0.5 point and SOX higher would mean Seoul overreacted, leaving room for a bounce there tomorrow. Brent above $111 with the 10-year above 5.15% would reopen the "oil → rates" channel for the first time this week.
6. Study Note: Why One IPO Flop Can Be a Market-Wide Signal
Concept
An IPO price is set before listing, through institutional book-building. The first-day market price is set by the people who actually start trading. A large gap between the two means the expectations right before listing and the reality on listing day are far apart.
Analogy
Imagine a gadget with 400 people lined up to pre-order, which then sells 30% below sticker on the resale market on launch day. The product did not get worse overnight. What spread that morning was the question, "Is this really worth that much?"
Today's case
Elice priced at the top of its range with retail demand over 400 times. It still closed about 32% lower. The same week, other AI-infrastructure listings stalled abroad (Firmus Grid withdrew its IPO; Nscale met resistance to its target valuation). This looks less like one bad IPO and more like the price the market puts on the whole AI-infrastructure category wobbling.
Why it matters
The IPO market is the door through which new money first enters a sector. When that door narrows, it affects listed peers (CoreWeave, Nebius): both their share prices and what it costs them to borrow.
One line
A first-day IPO plunge can signal that the value placed on an entire sector is shifting.
7. Corrections and Open Items
Corrections
- None.
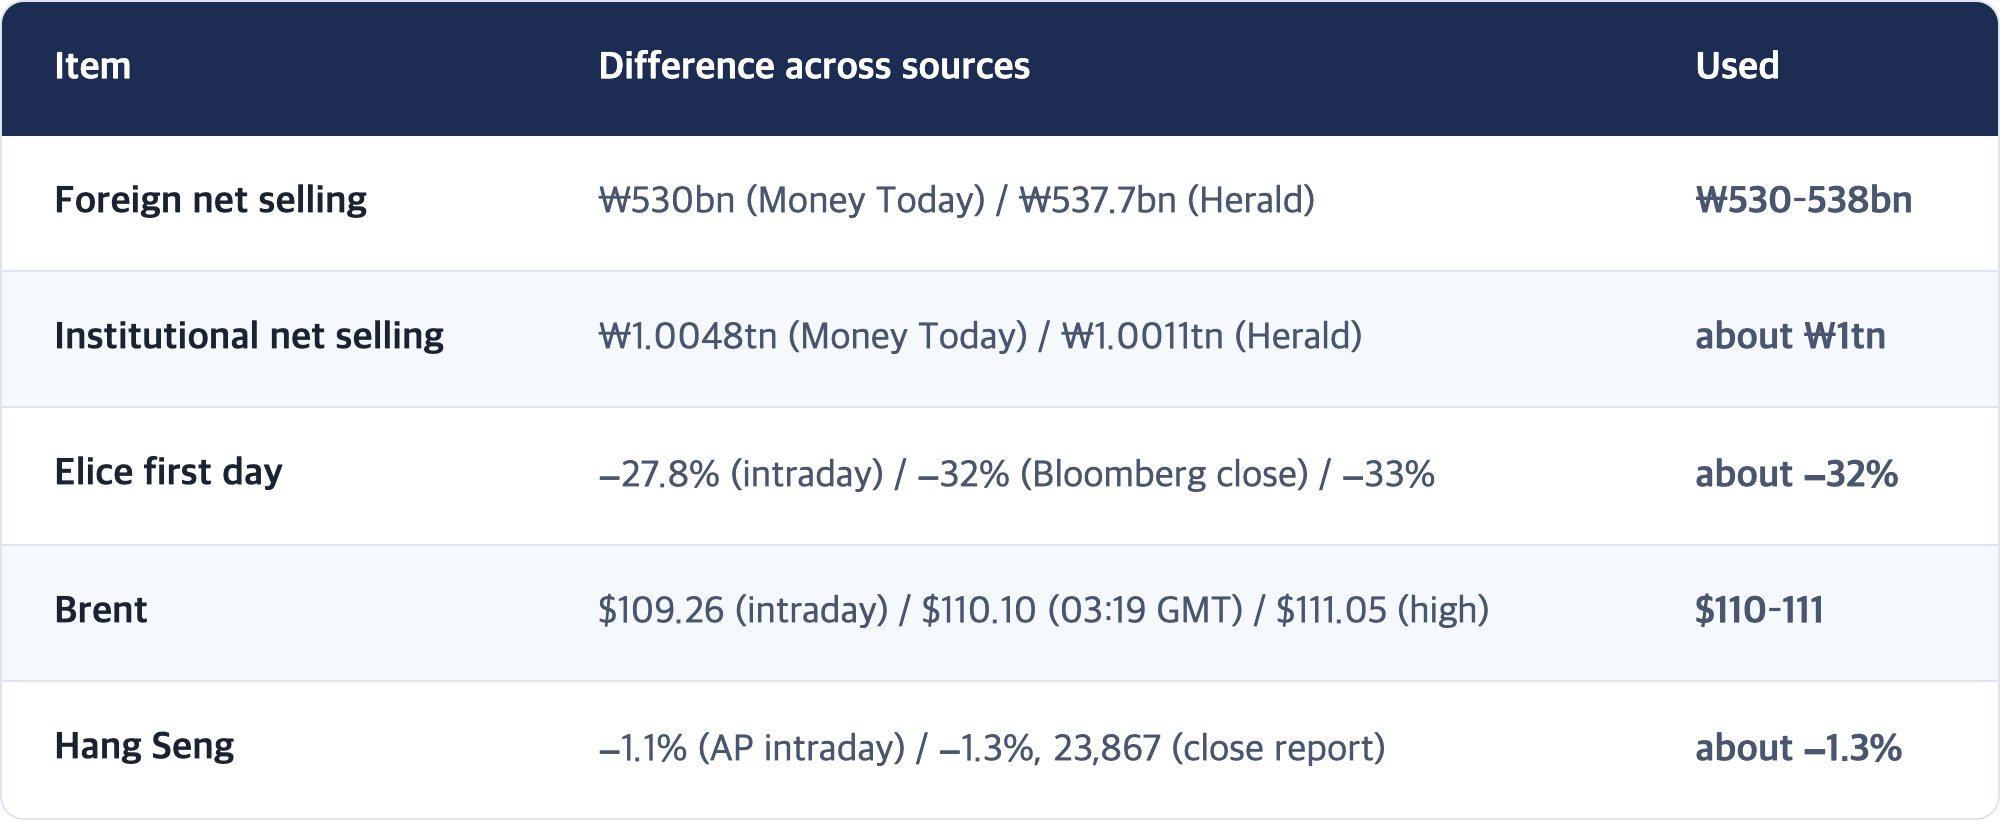
Source differences (value used in the body)
🔲 Unconfirmed
8. Event Calendar (PDT)
Sources
- KOSPI falls 3.73% to 5,552.74 on foreign and institutional selling | Money Today
- KOSPI gives back rebound, closes near 5,550 | Herald Business
- Market close: KOSPI drops 3.7% | Businesskorea
- Samsung −2.98%, SK Hynix −4.23% at close | Segye Ilbo
- Won closes at 1,328.1, year's strongest | Seoul Economic Daily
- Data-Center Firm Elice Plunges 32% in Debut After Korea IPO | Bloomberg via Yahoo
- South Korean AI data centre firm Elice shares tumble in IPO debut | Reuters via TradingView
- Asian shares mostly decline after AI stocks lead a rebound on Wall Street | AP via Click2Houston
- Hang Seng closes down 319 points as Lenovo plunges | BigGo Finance
- Premarket Stock Trading Data | CNBC
- Nasdaq futures dip as oil prices climb, earnings loom | Reuters via TradingView
- Why Are Nasdaq Futures Falling Premarket? | Stocktwits
- Market Quick Take – Korea slides as Brent holds near 110 | Saxo
- Brent hits five-month high as attacks on ships, Saudi sites fuel supply worries | The Globe and Mail
- Brent Crude Reaches Five-Month High of $111.05 | ADVFN
- US Treasury yields ease | Invezz
- European stocks extend slide as French unrest triggers de-risking | Investing.com
- US September housing starts 1.221M vs 1.305M | investingLive
Market Analyst · No individual buy or sell recommendations. This brief offers macro context and interpretation only.
📌 More market briefs
※ This post is market observation and organization intended to support your own judgment. It is not a recommendation to buy or sell any security. Figures are as of the time of writing and may differ between sources.
If this was useful, bookmark it or pass it along. It genuinely helps me write the next one.
I can survive. We can survive.