October 21, 2026 US Market Brief — Nasdaq and S&P 500 Before the Open
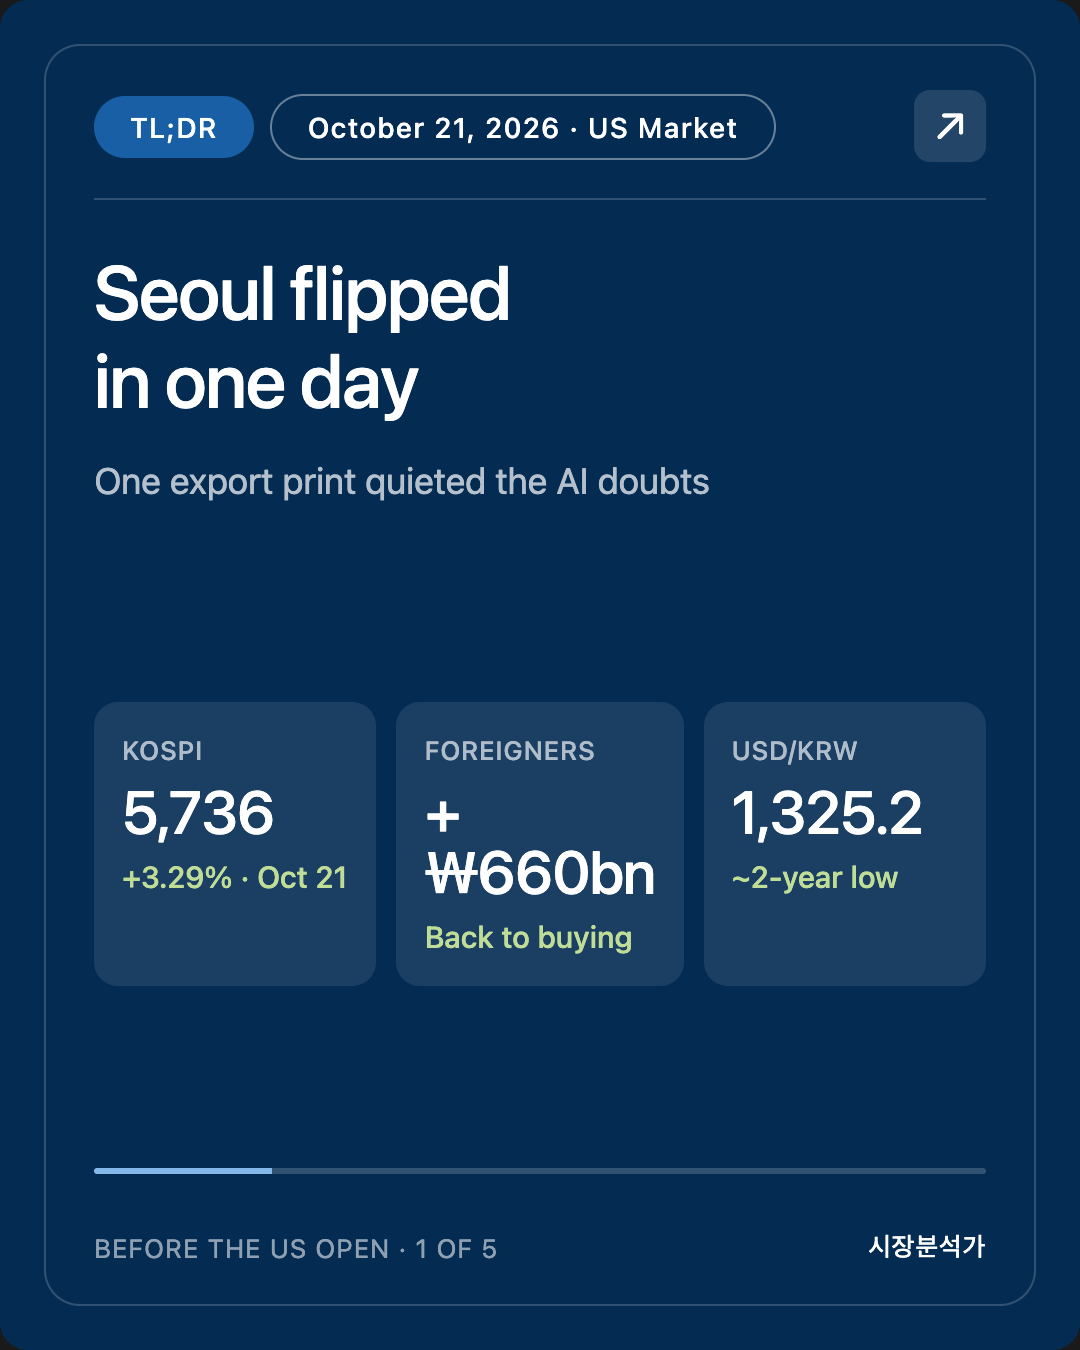
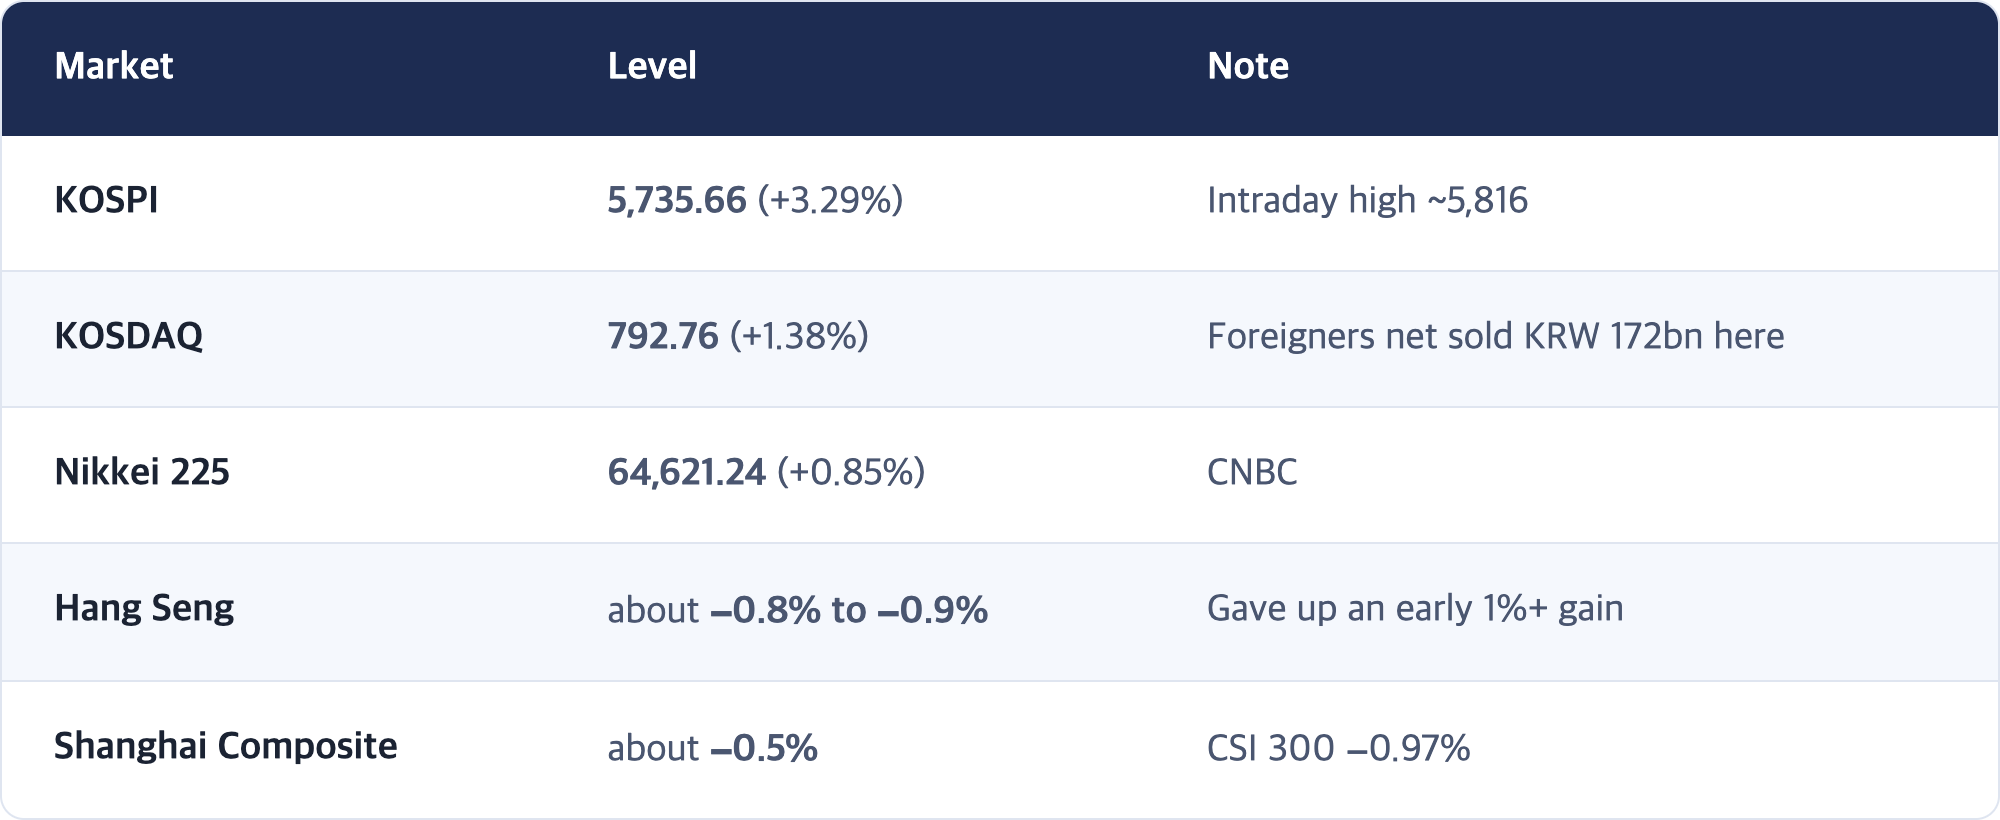
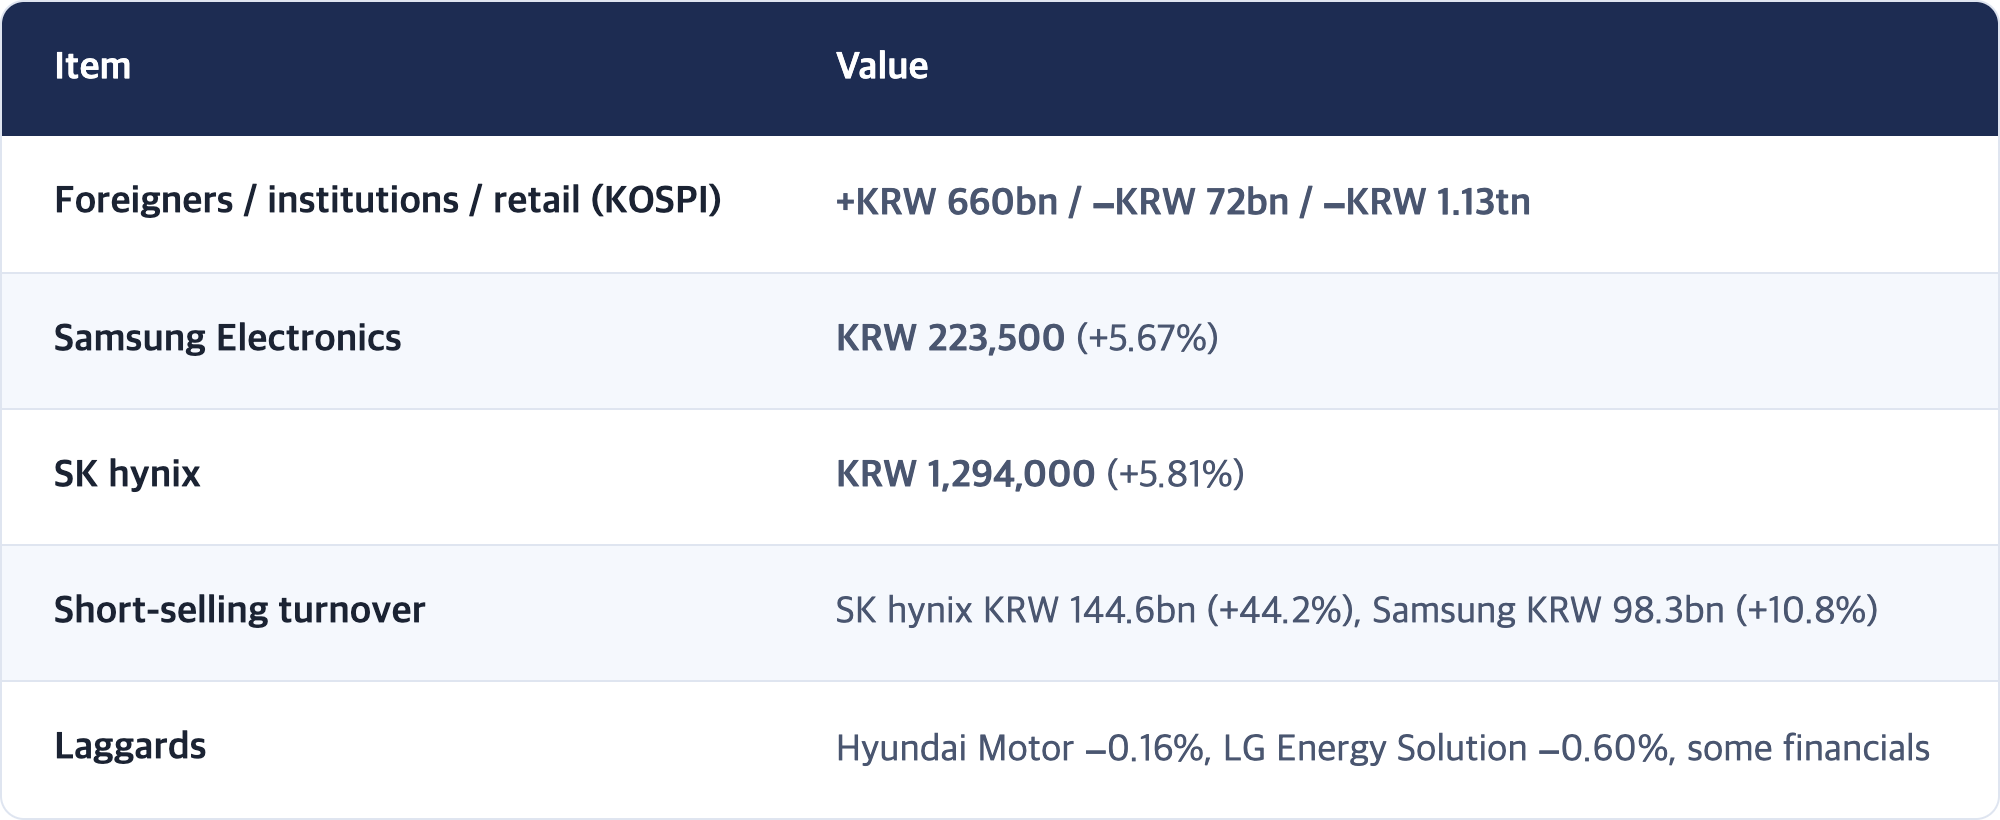
- ★ Seoul reversed in one day. KOSPI 5,735.66 (+3.29%), KOSDAQ 792.76 (+1.38%). Foreigners net bought about KRW 660 billion, mostly Samsung (KRW 472bn) and SK hynix (KRW 200bn). The won strengthened to 1,325.2 per dollar, its strongest close in about two years.
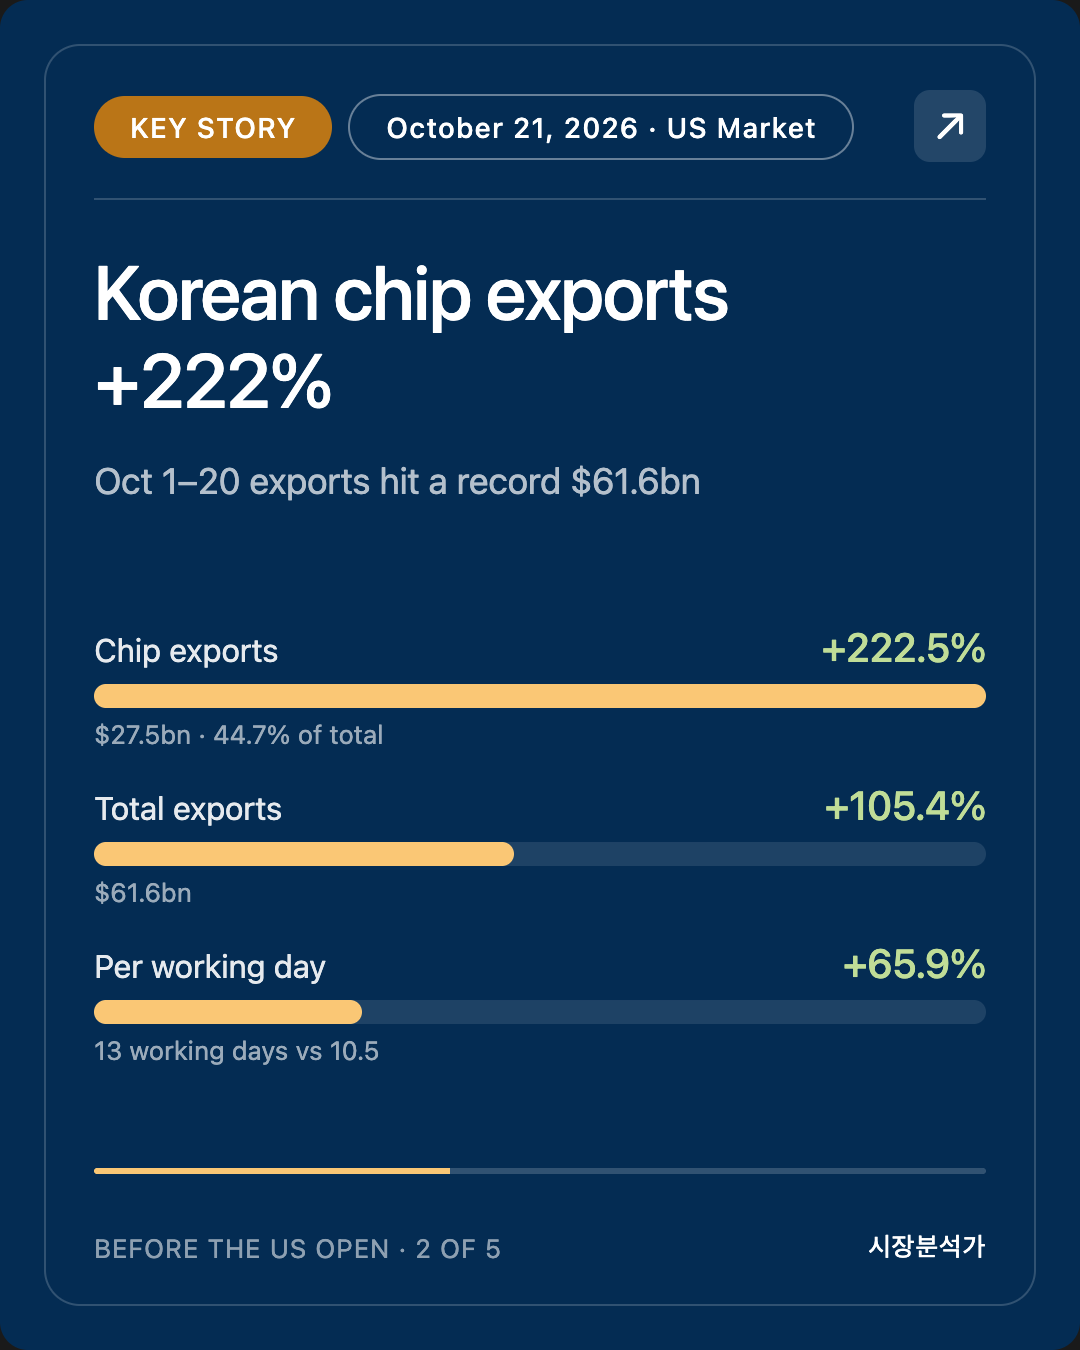
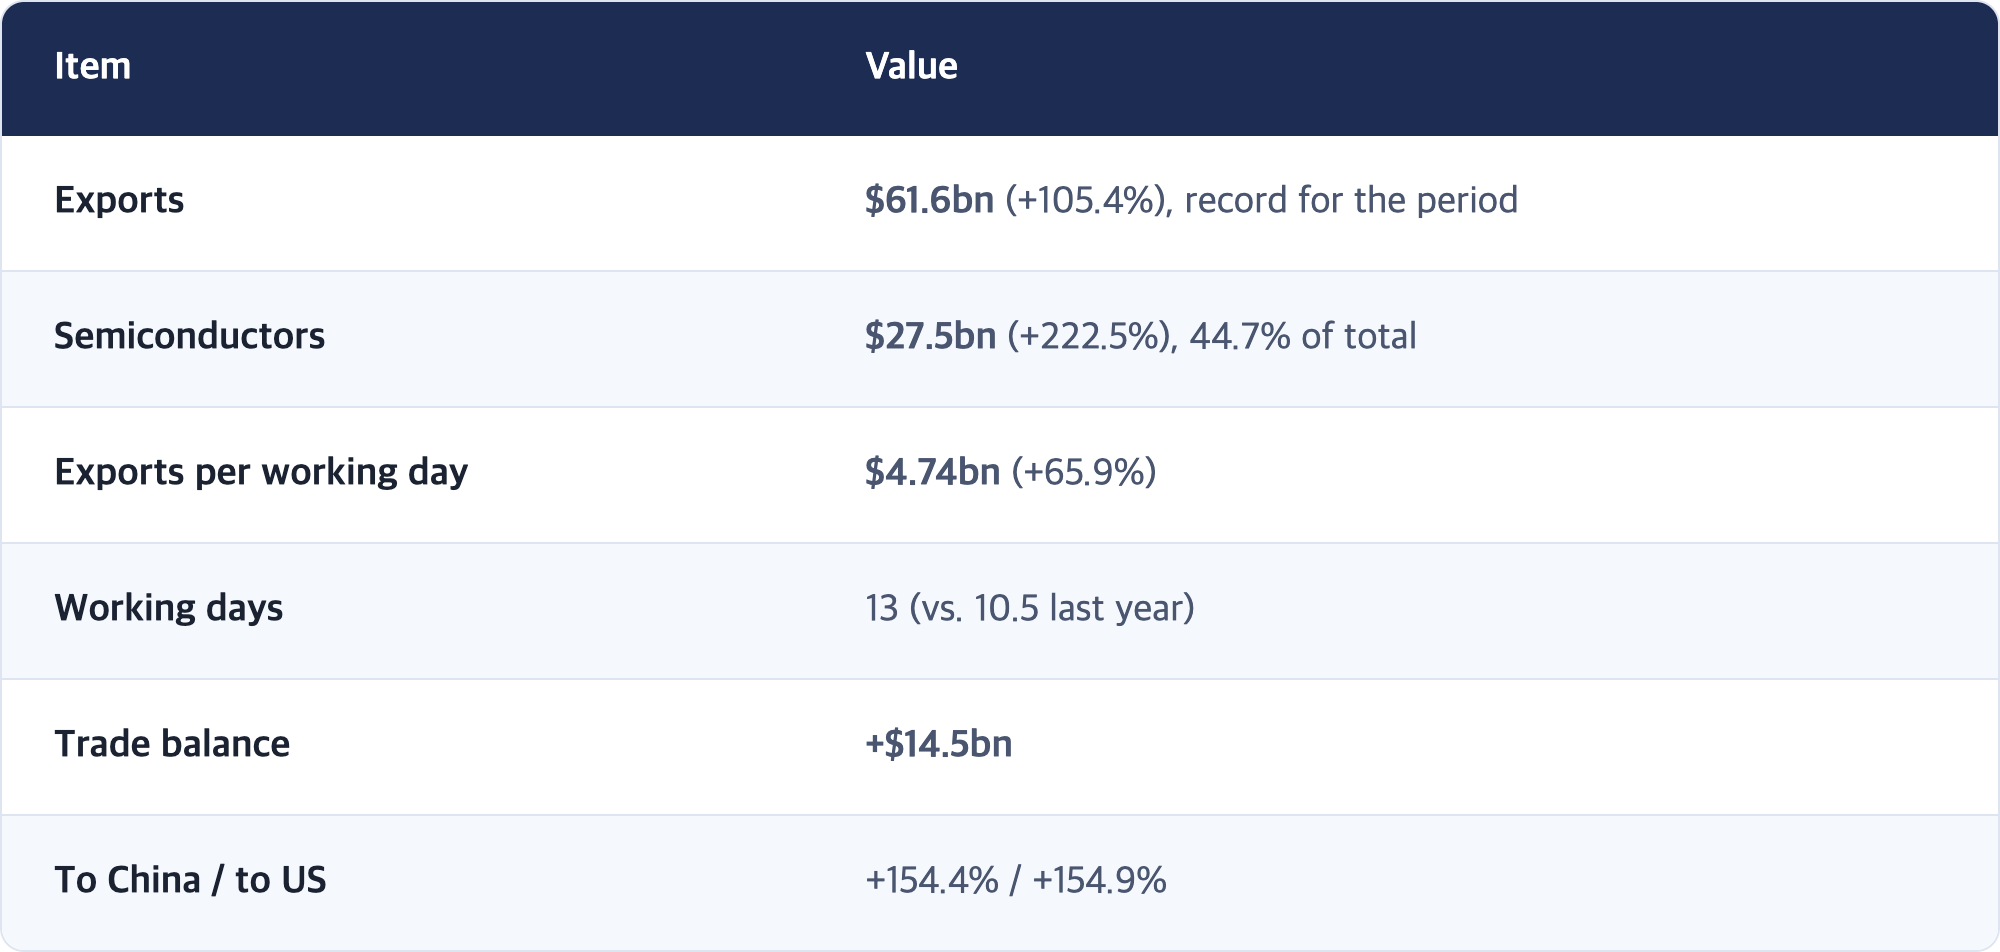
- ★ The catalyst was exports. Oct 1–20 exports $61.6bn (+105.4%), chips $27.5bn (+222.5%), chips now 44.7% of all exports. There were 2.5 more working days than last year, but even per working day exports rose 65.9%.
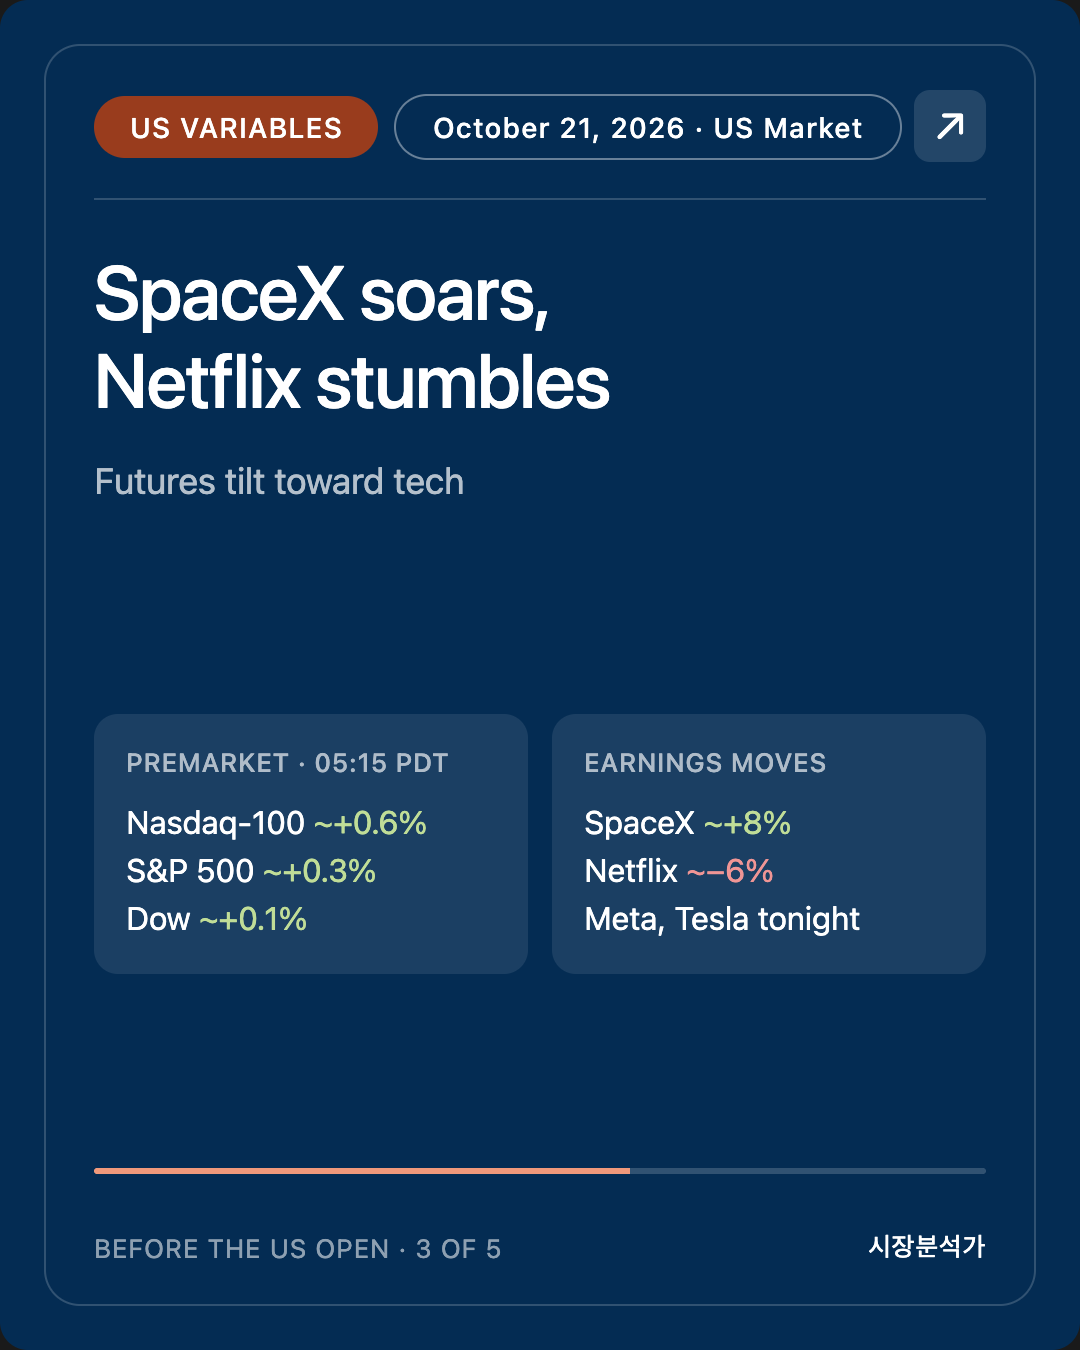
- ★ US futures favor tech. Nasdaq-100 futures about +0.5–0.7%, S&P 500 futures about +0.2–0.3%, Dow futures flat to +0.3%. SpaceX reported Q3 revenue of $14.6bn (single source; consensus about $12.9bn), with its AI segment larger than Starlink and rockets combined.
- Netflix went the other way. Q3 profit beat, but it cut its Q4 revenue outlook plus ad-revenue and free-cash-flow guidance. Shares are about −6% premarket.
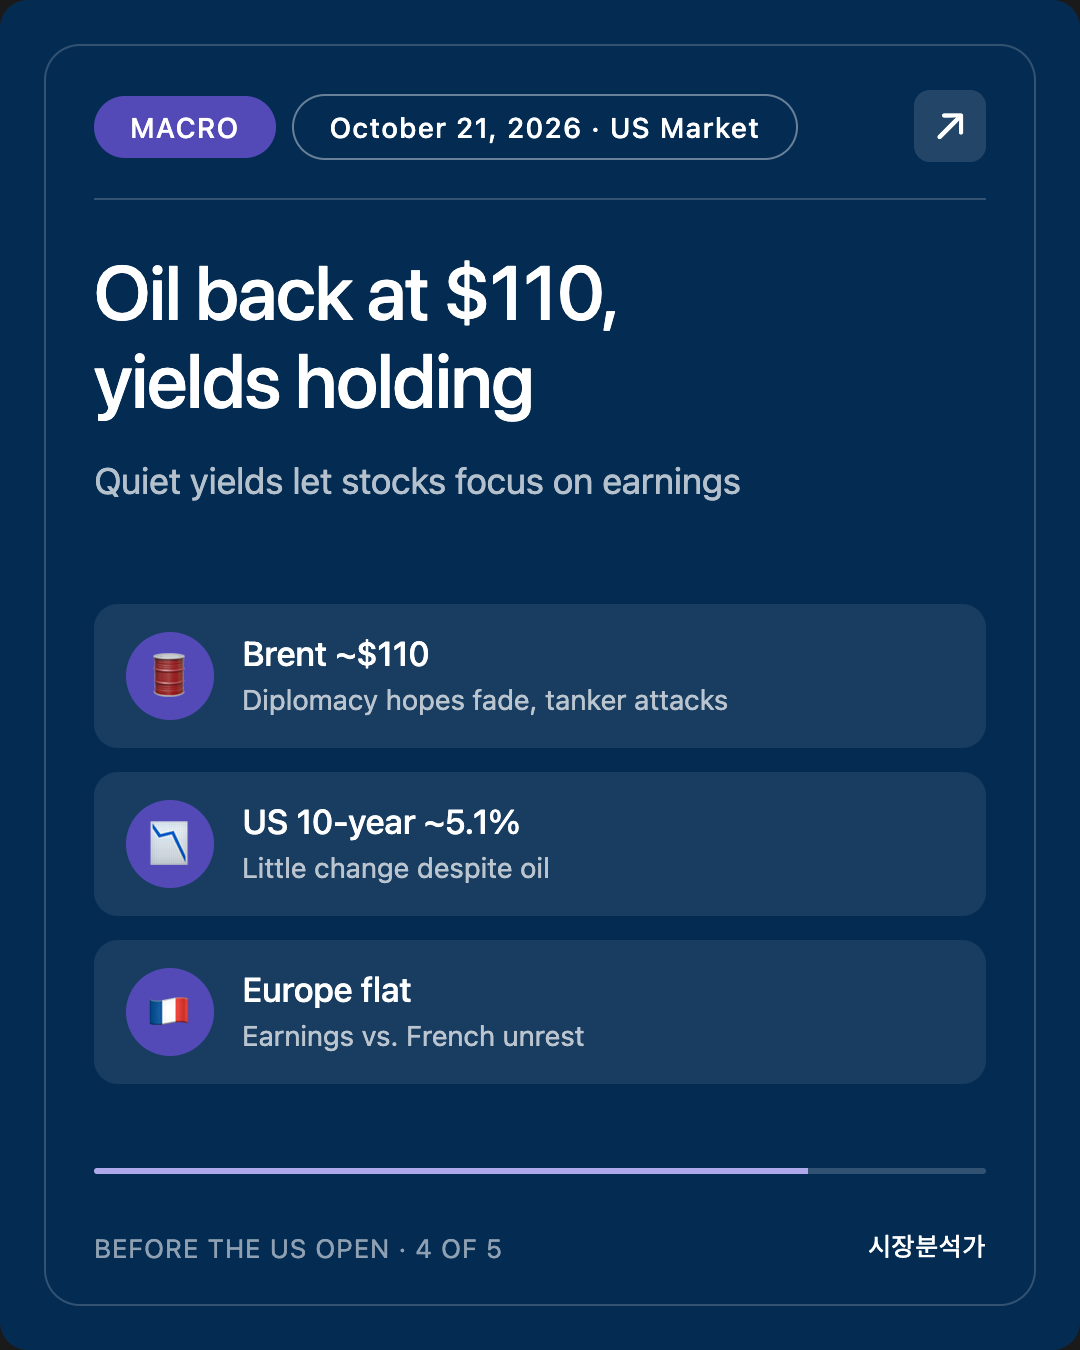
- Oil is back at $110; yields are quiet. Brent about $110 (+1.2–1.5%), US 10-year about 5.09–5.12%, VIX 17.2, gold about $4,146. After the close: Meta, Tesla, IBM, Texas Instruments. Tonight (Pacific time): Bank of Korea rate decision.
This is Mr. Can. Here is the October 21, 2026 brief ahead of the US market open.
Written: 2026-10-21 05:55 PDT (Korea 10/21 21:55 KST) · Work started 05:43 PDT
Based on: Korea, Japan, Hong Kong and China closes on 10/21 + Europe intraday 10/21 + US premarket (around 05:15 PDT) + overnight Treasuries + after-hours earnings on 10/20 (SpaceX, Netflix)
🟢 Scheduled 05:30 PDT, started 05:43 PDT. Written before the US open (06:30 PDT).
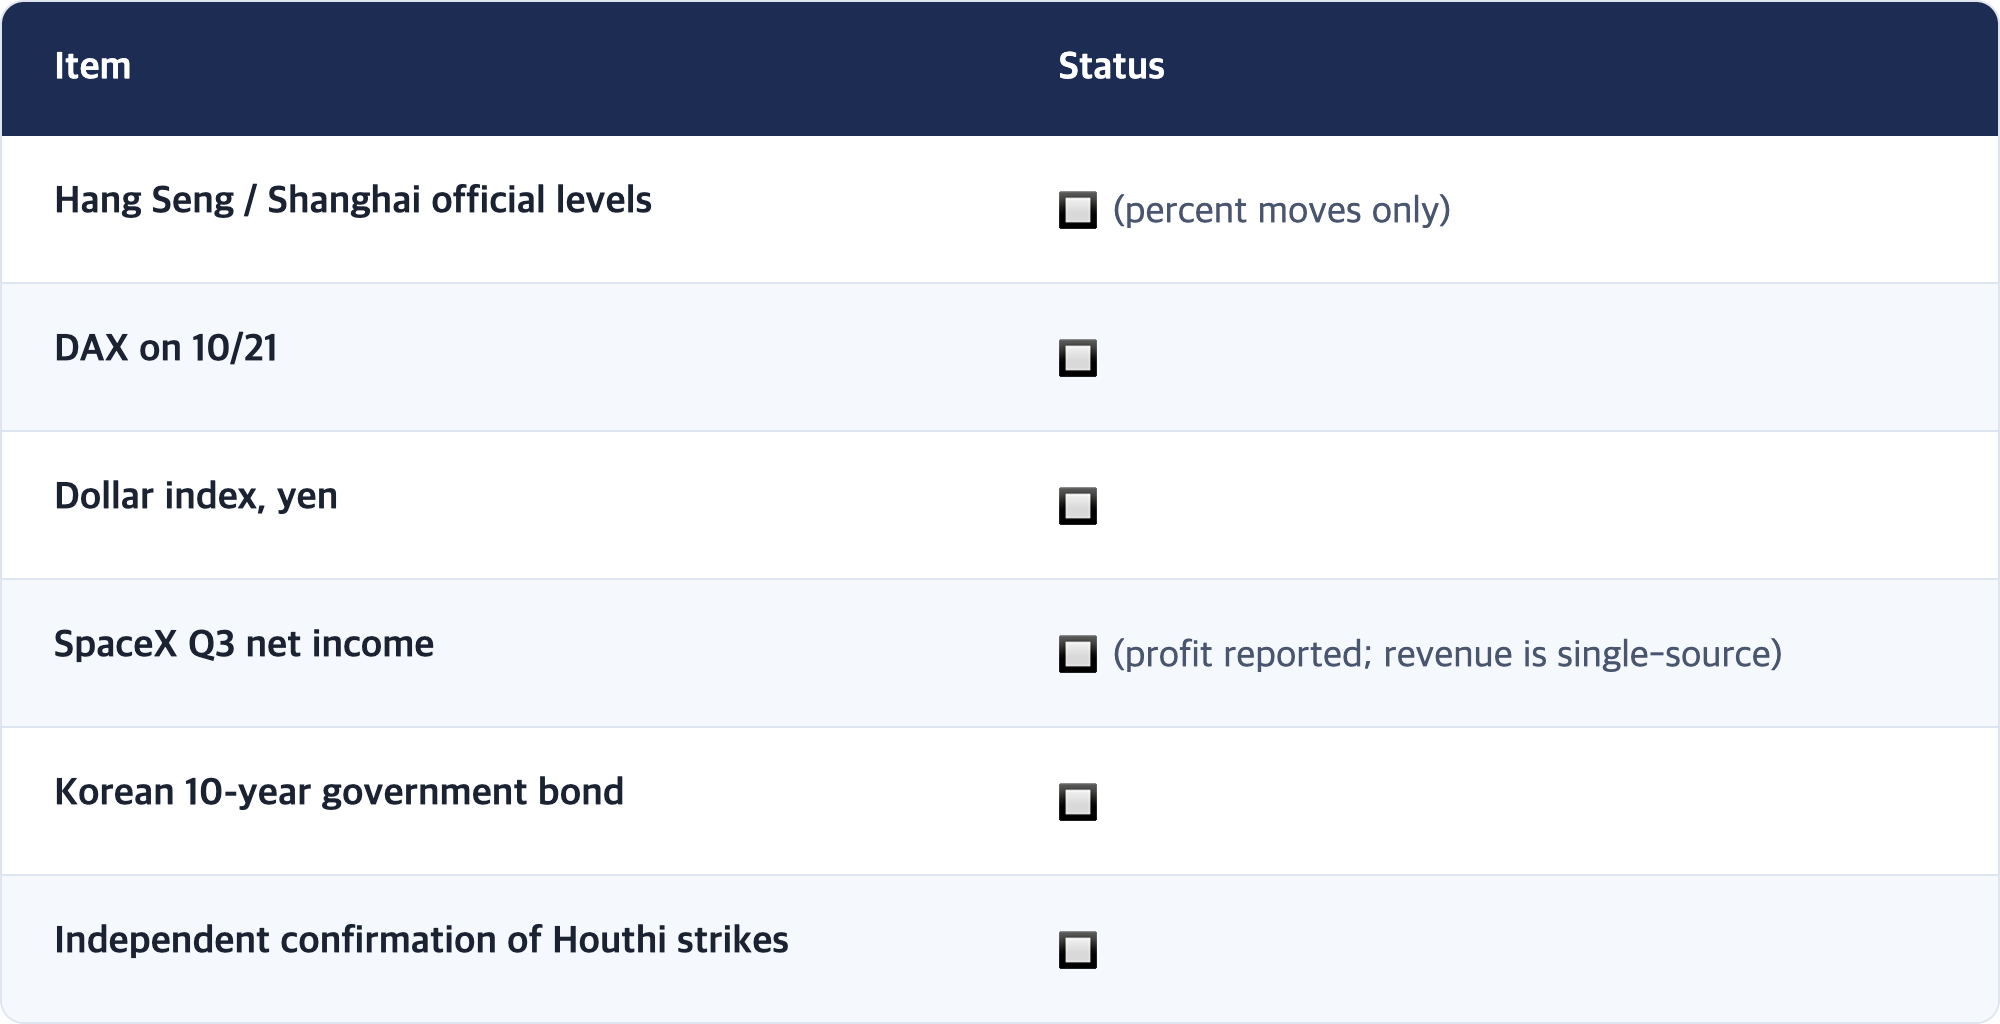
🟡 Official Shanghai/Hang Seng index levels, DAX, the dollar index, yen and Korean government bond yields were not secured (see section 7).
SEO Intro
Seoul flipped in a single day. After a 3.73% drop on Tuesday, Korea's KOSPI closed Wednesday at 5,735.66 (+3.29%), back above 5,700. Foreign investors bought roughly KRW 660 billion (about $500 million) of Korean stocks, and the two memory giants, Samsung Electronics (+5.67%) and SK hynix (+5.81%), led the way.
The trigger was a data release. Korea's customs agency reported exports for October 1–20 at $61.6 billion (+105.4%), a record for the period, with semiconductors at $27.5 billion (+222.5%). Tuesday's selloff was driven by doubt over who is really paying for the AI build-out. Wednesday's export print answered: the orders are real.
US futures are leaning the same way this morning. SpaceX beat expectations and is up roughly 7–9% premarket, and Nasdaq-100 futures are up about 0.5–0.7%. Netflix is the exception, down about 6% on weaker guidance. Meta and Tesla report after the close. The question for today's US session: does Wall Street's chip sector pick up Seoul's rebound, or wait for Meta's numbers?
1. Scorecard
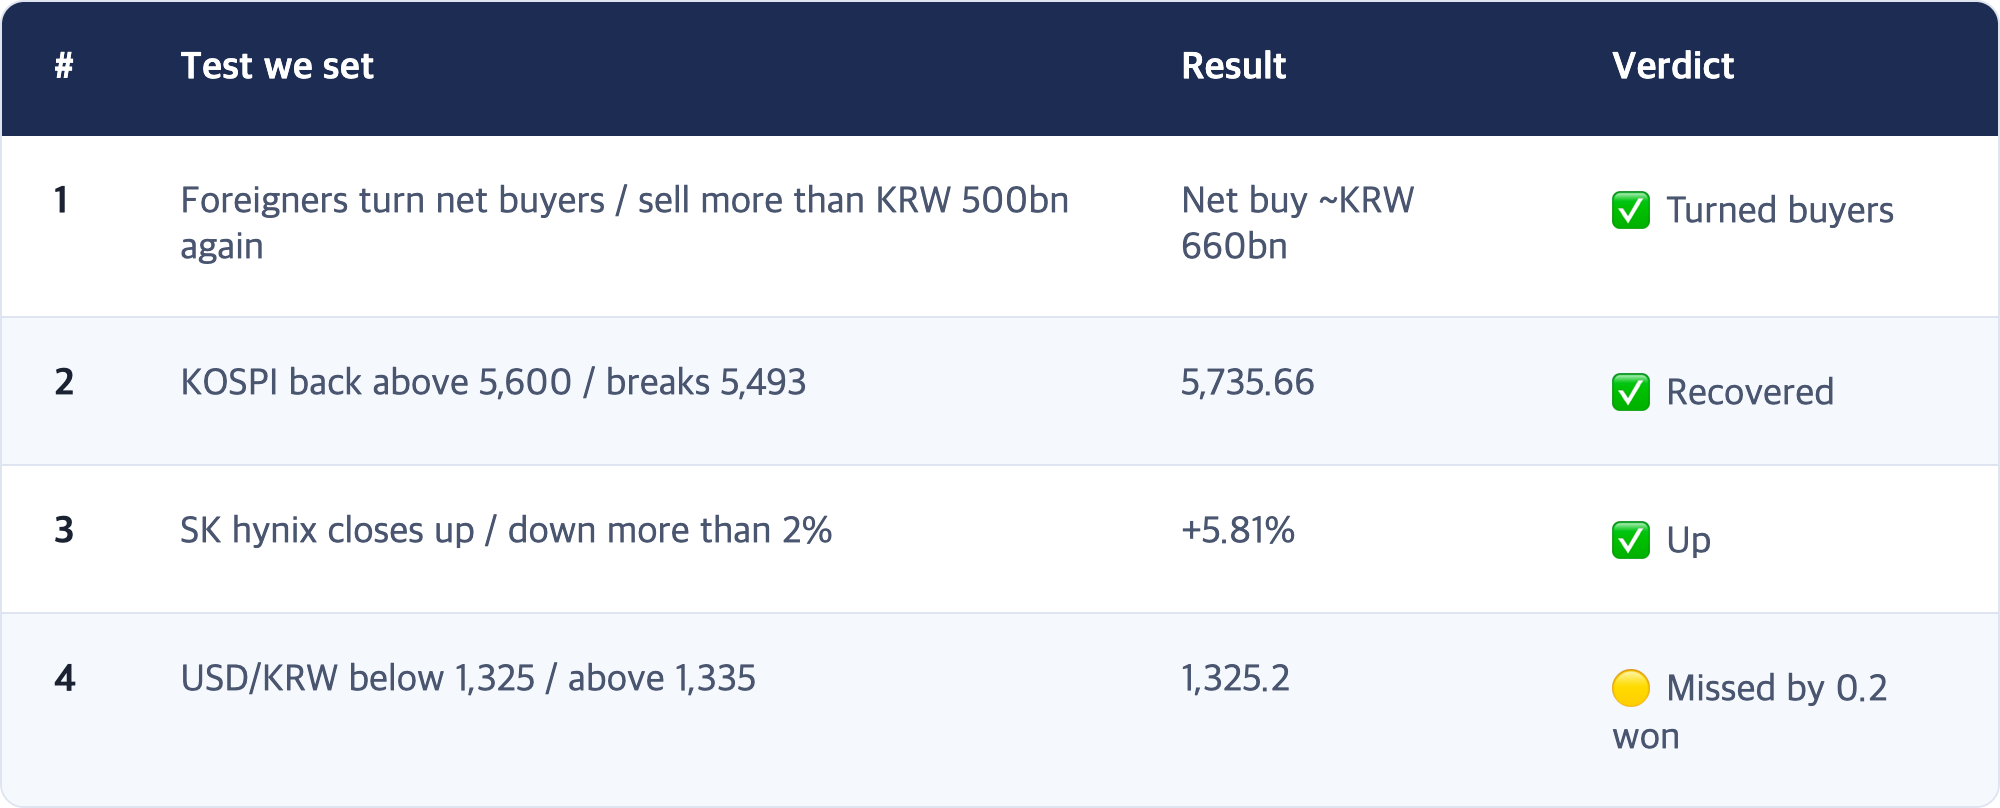
The four checkpoints from the 10/20 PM report (Korea close, 10/21)
The question was whether Seoul would hold by rotating out of chips, or fall for a second day across the board. The third variable was the 9:00 KST export release.
★ [Interpretation] The third variable settled it
We wrote that a foreign buying turn plus a move back above 5,600 would mean Tuesday's −3.73% was Seoul panicking a day early. That is what happened. But the money did not rotate out of chips, as our framing assumed. It came straight back into them. One export number was enough to quiet the doubt about chips themselves.
[Observation] The won moved with stocks again. Foreigners bought, and the currency strengthened.
2. Today's Key Story: An export print quieted the AI doubts
[Fact] Asia close, Wednesday 10/21
[Fact] Korea flows and leaders
[Fact] Korea exports, October 1–20 (preliminary)
★ [Interpretation] The doubt was "does AI pay?" The answer was an order book
- Tuesday's selloff was about a question, not a price. A sharp first-day drop in an AI data-center IPO and a governance dispute around SK hynix's US subsidiary fed one doubt: who is actually funding all this capacity?
- Wednesday's rebound was about a number. Chip exports up 222% mean the orders are arriving. Adjusting for working days still leaves exports up 66%.
- But short sellers grew too. SK hynix short-selling turnover rose 44%. Buyers and doubters both got bigger on the same day, so one rally does not end the debate.
[Observation] Asia split along chip lines: Seoul and Tokyo rose; Hong Kong and Shanghai fell. This looks like a semiconductor rally more than a broad risk-on day.
3. US Variables: SpaceX soars, Netflix stumbles
[Fact] US premarket (around 05:15 PDT; timing varies by source)
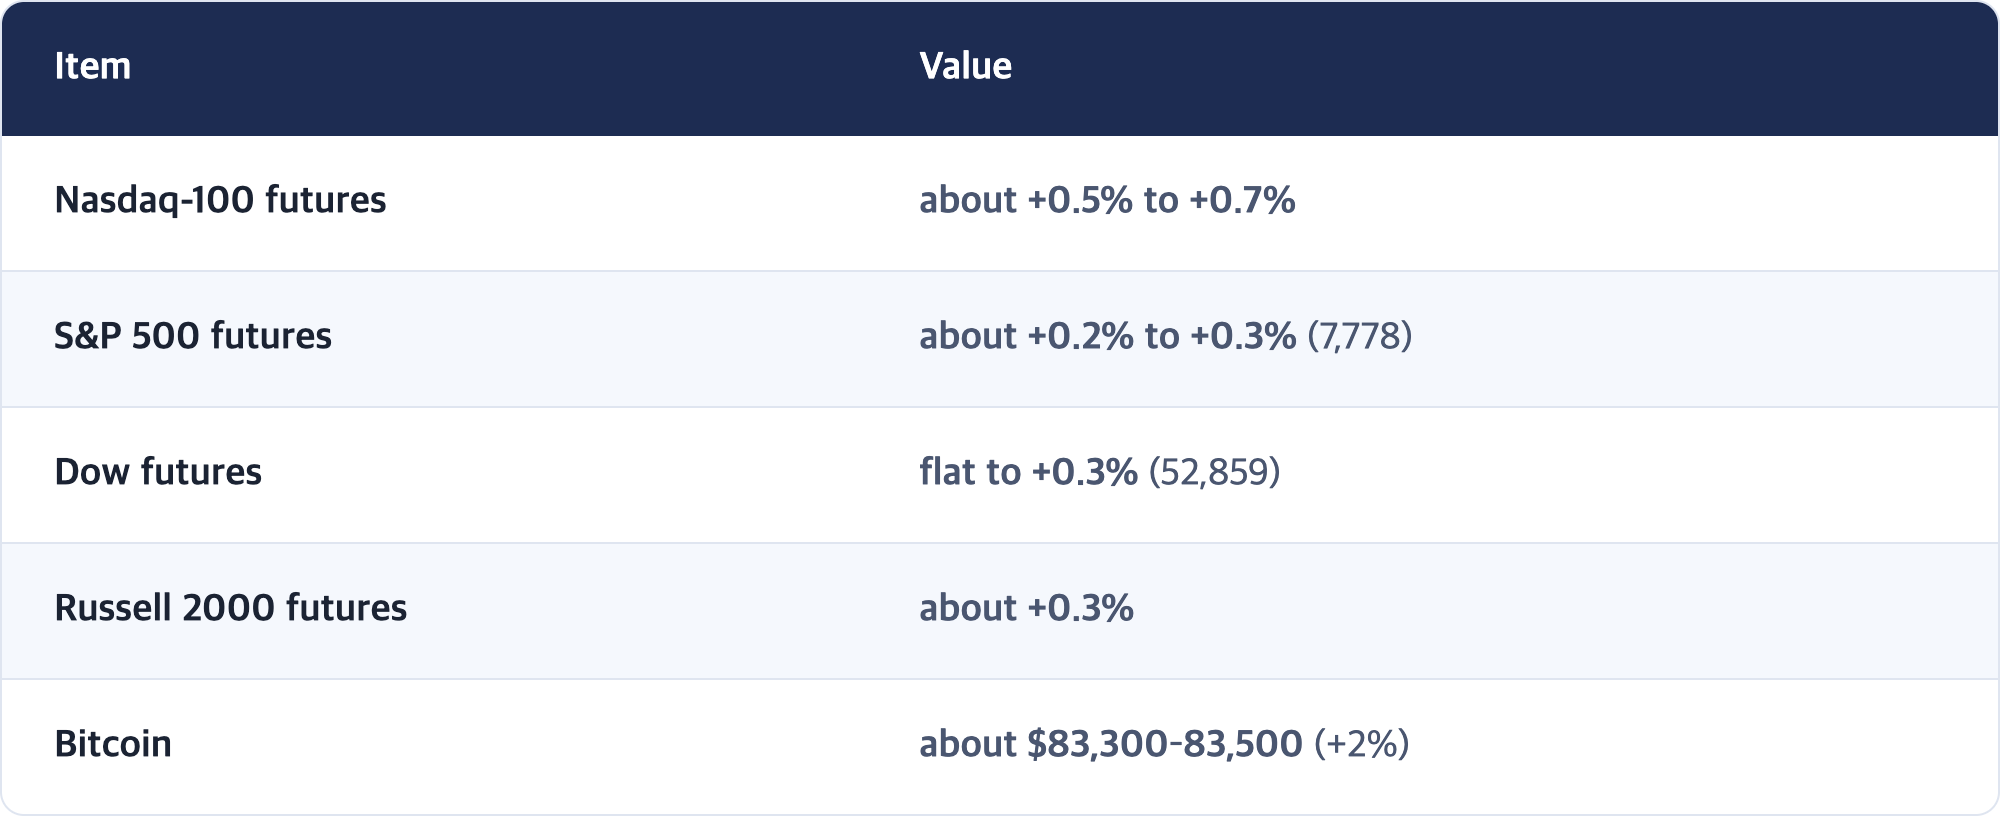
[Fact] After-hours and premarket movers
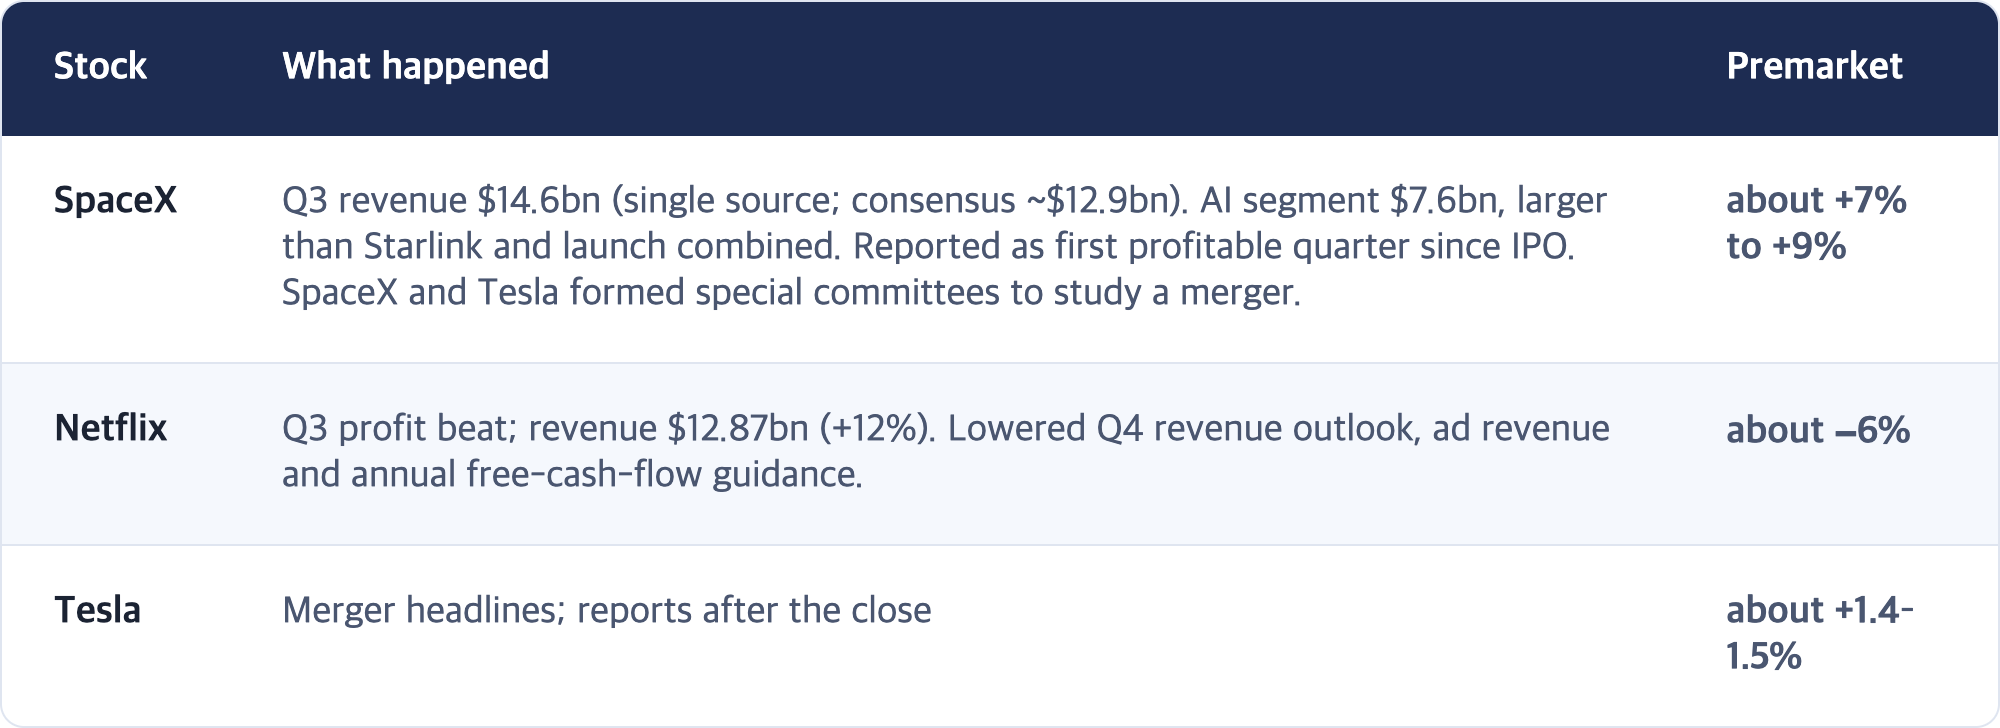
★ [Interpretation] Wall Street is picking up Seoul's number
- For two days New York didn't sell AI, it rotated sideways. The SOX rose 1.61% Monday and slipped about 0.29% Tuesday while the Dow gained 1%. Seoul, meanwhile, swung −3.73% then +3.29%.
- Two pieces of evidence tilt futures toward tech today: Korea's chip exports and SpaceX's AI revenue. Both say AI is producing real sales.
- Netflix's drop is not an AI story. It is about ads and cash flow. Read it alongside Meta's ad numbers tonight as a signal on consumer and advertising demand.
4. Macro Backdrop: Oil is back at $110, yields are holding
[Fact] Rates and commodities (Wednesday morning)
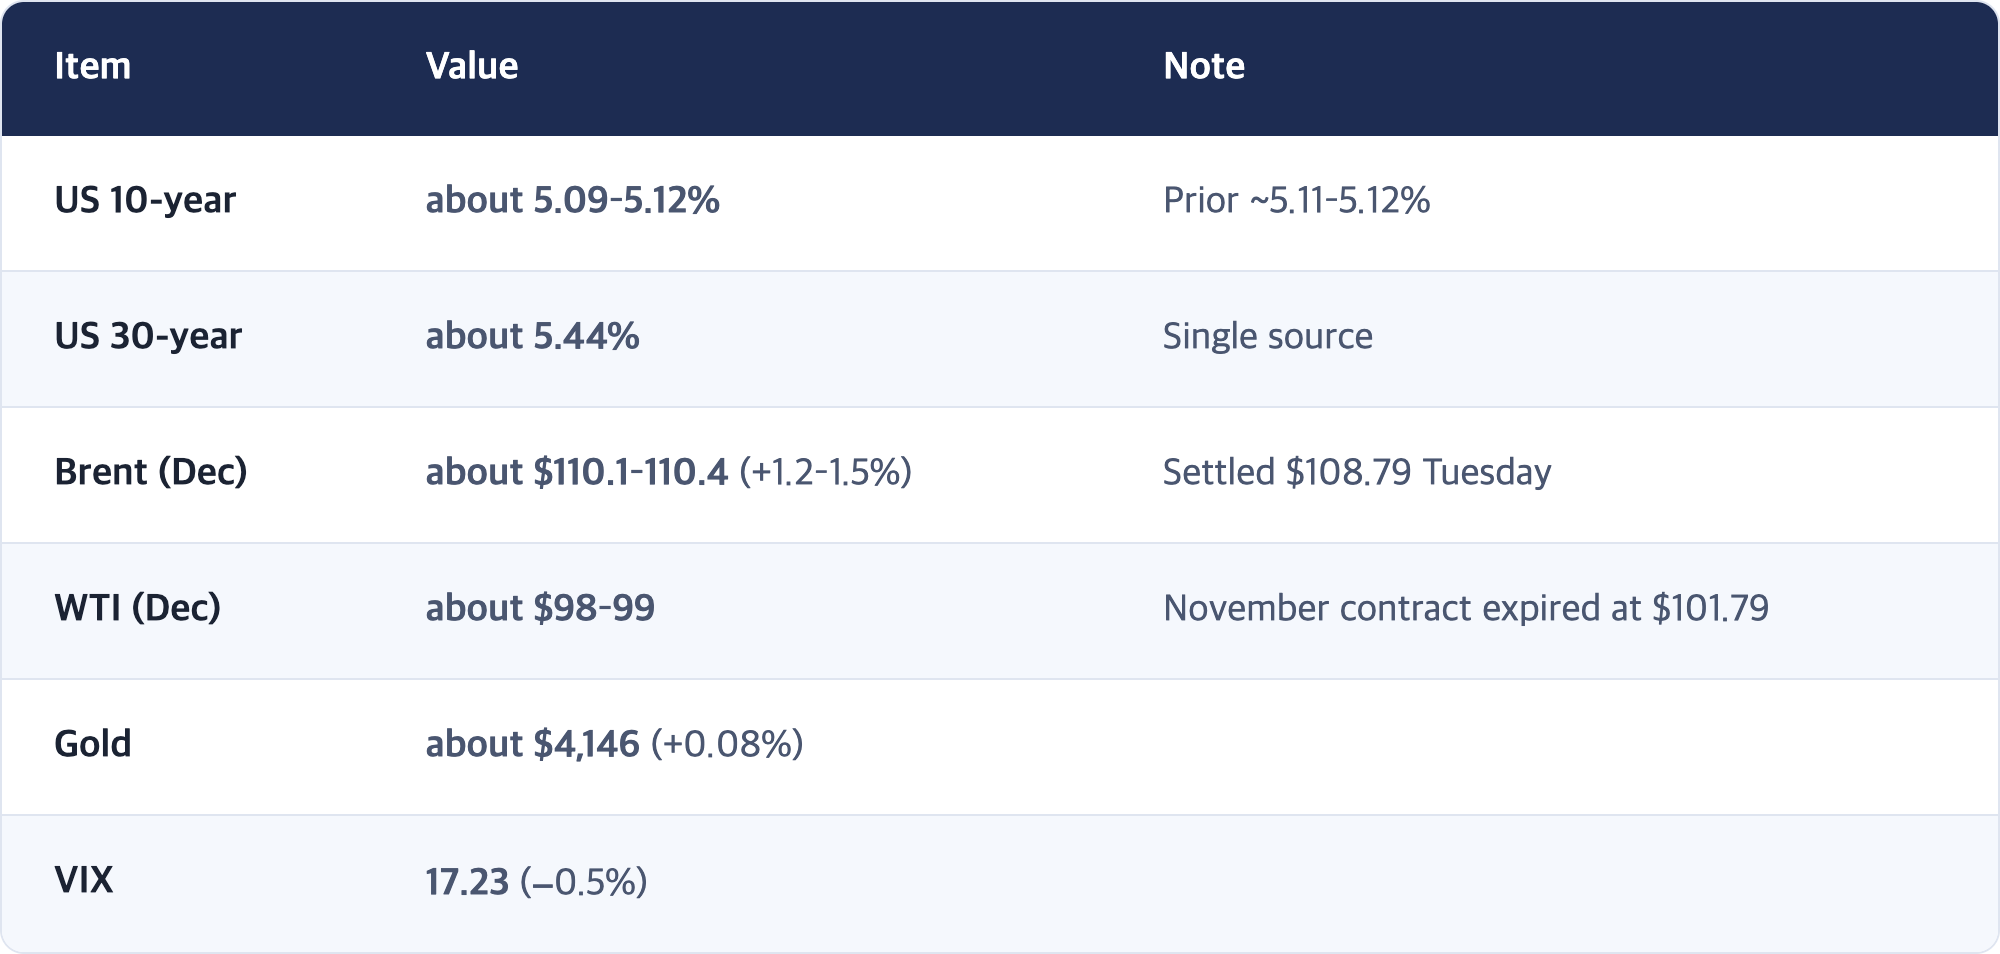
[Fact] What pushed oil back up
- More reports of tanker attacks near the Strait of Hormuz; Yemen's Houthis claimed strikes on Saudi oil sites (not confirmed by Saudi Arabia).
- Iran's foreign minister said Saudi Arabia and the Houthis had not responded to its mediation offer, cooling Tuesday's hopes for diplomacy.
- US distillate stocks are about 12% below the five-year average.
[Fact] Europe
- STOXX 600 opened flat to about +0.5% near 638–639; earnings optimism offset worries about unrest in France (Reuters).
- After weekend riots, France's CAC 40 fell 1.1% on Monday and the French 10-year yield rose to 4.93%.
★ [Interpretation] Rising oil with quiet yields gives stocks room
We've argued that oil is steering Treasury yields this week. Oil rebounded to $110 this morning, yet the 10-year barely moved from 5.1%. When oil and yields rise together, stocks take two hits. When yields hold, stocks can focus on earnings. The real test is if Brent breaks Tuesday's $111.99 high and yields still hold.
5. Today's US Session (Wed 10/21): Checkpoints
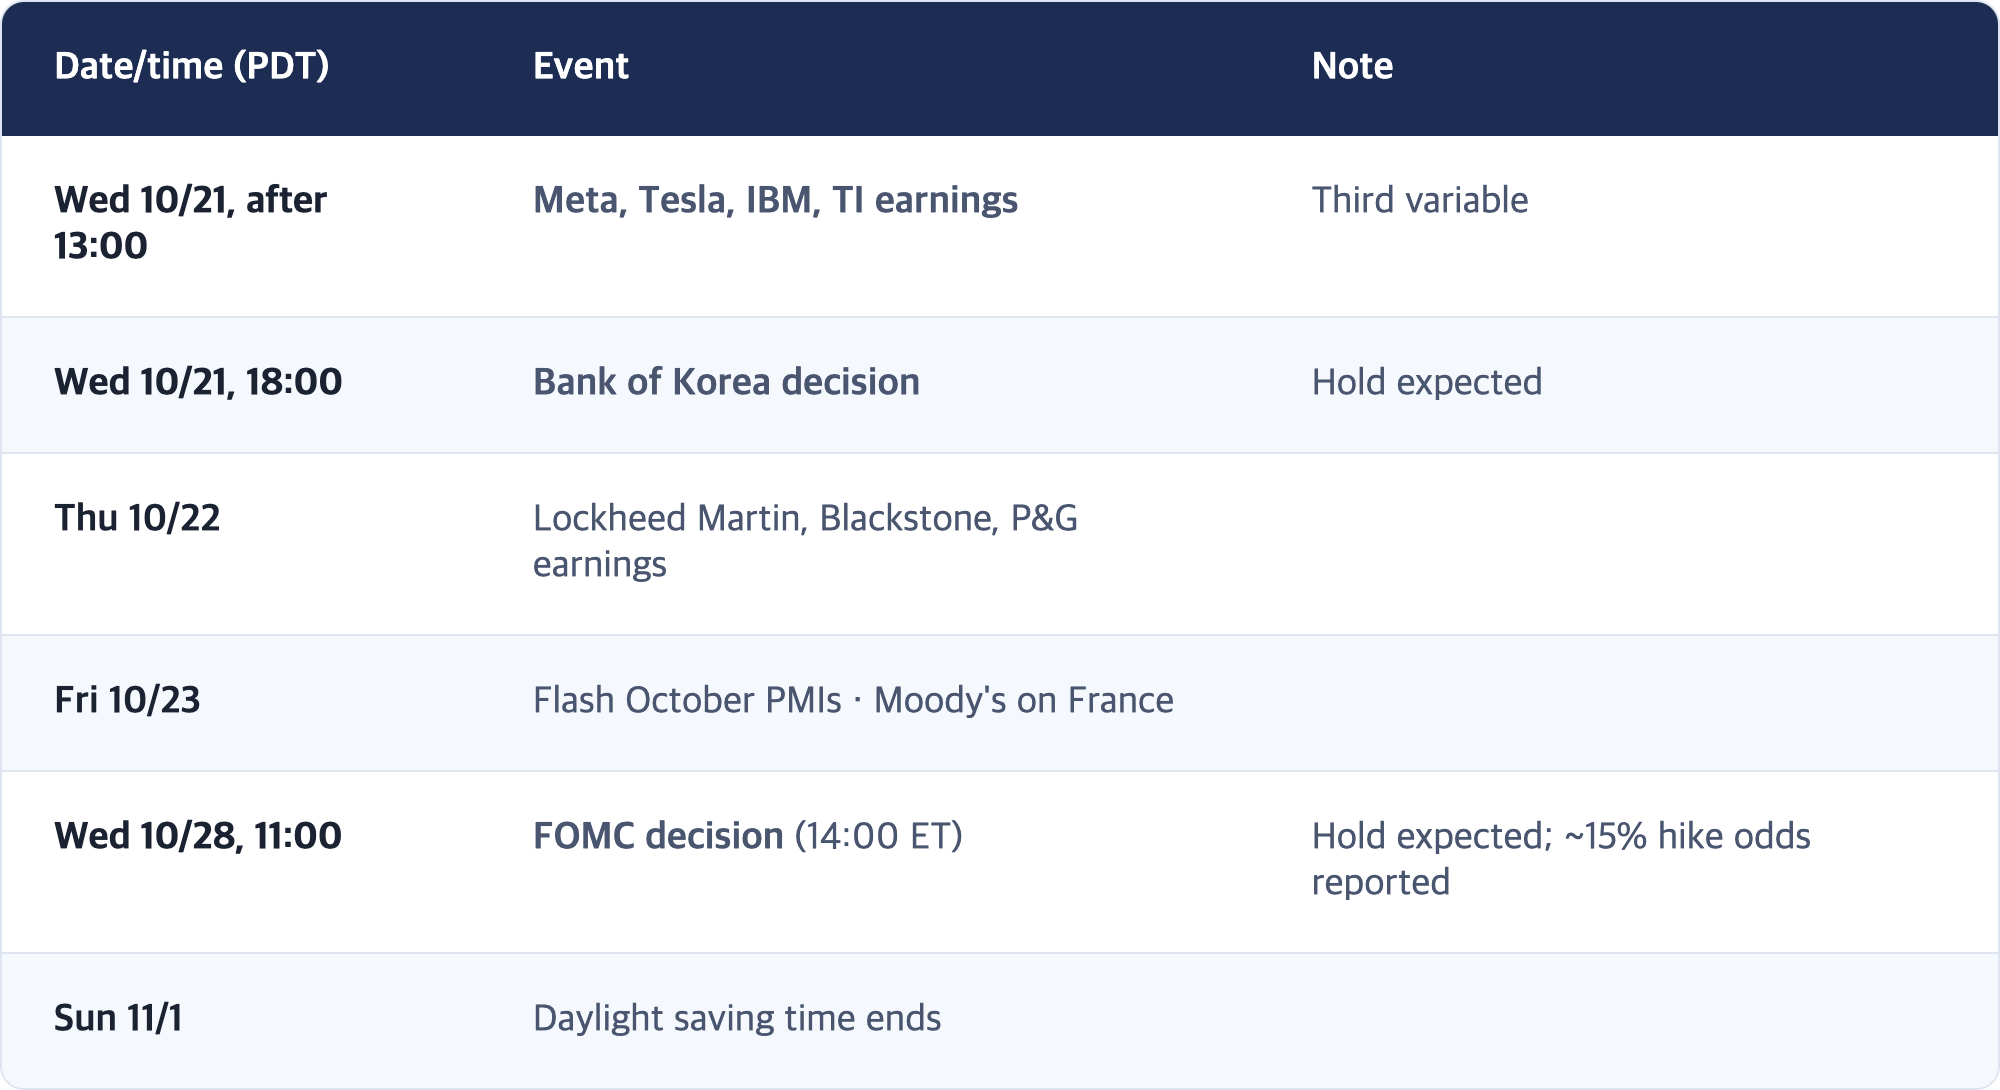
[Observation] Remaining schedule (PDT)
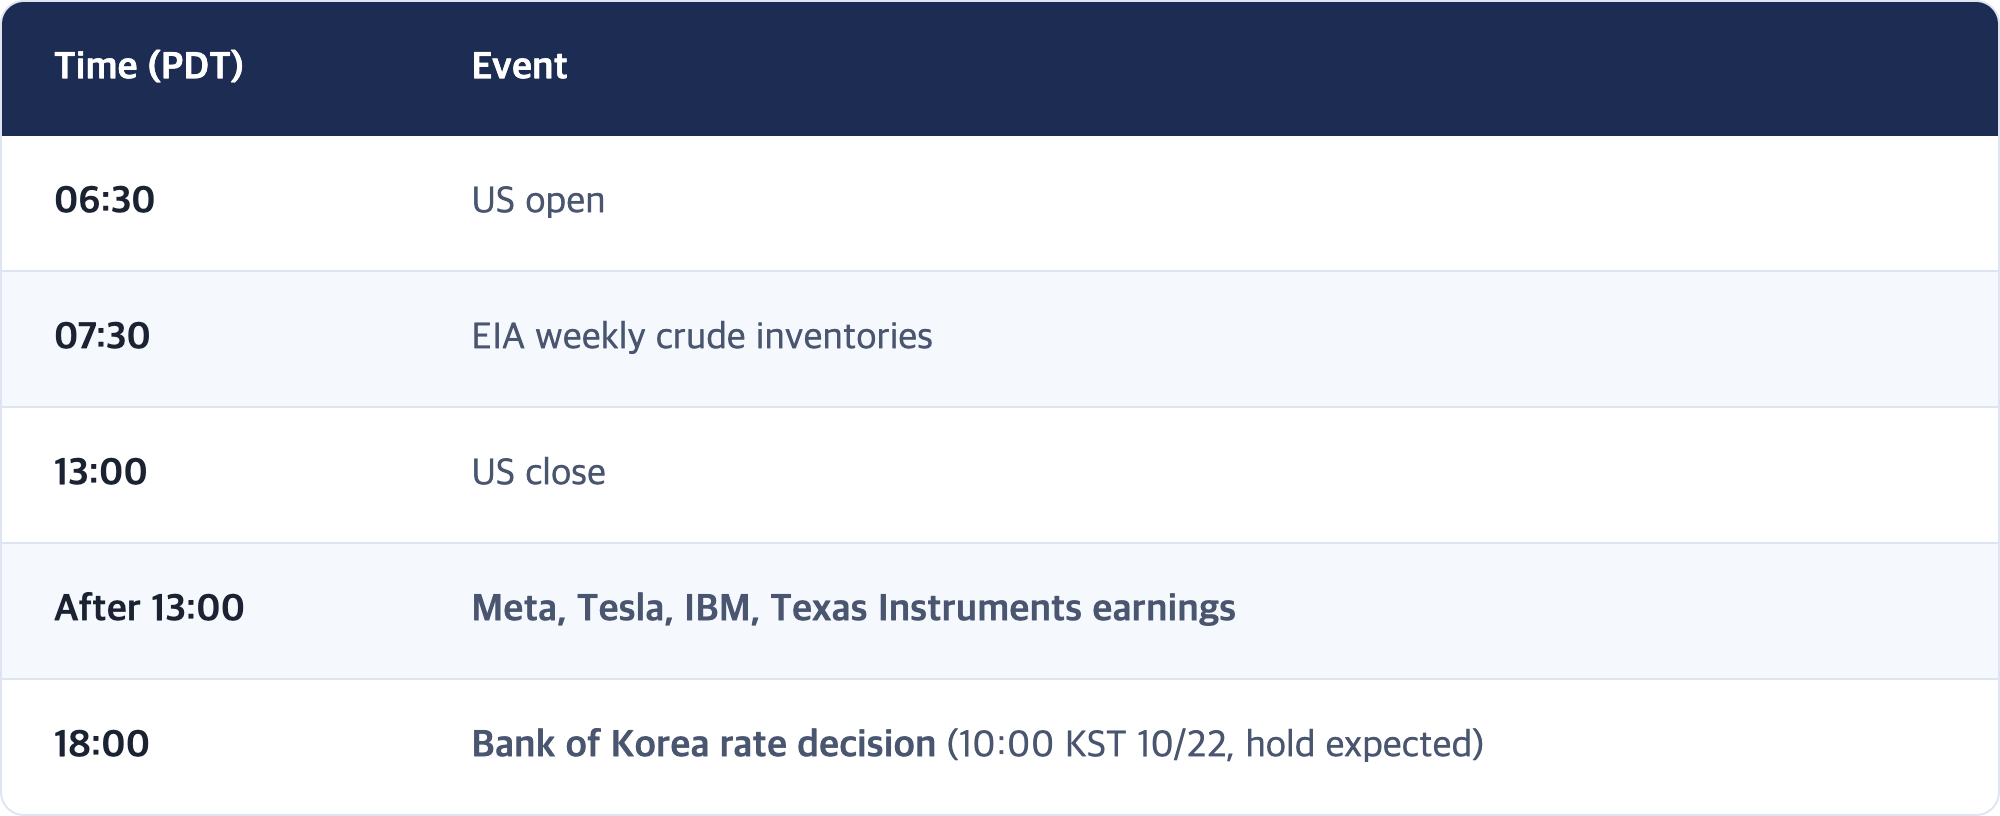
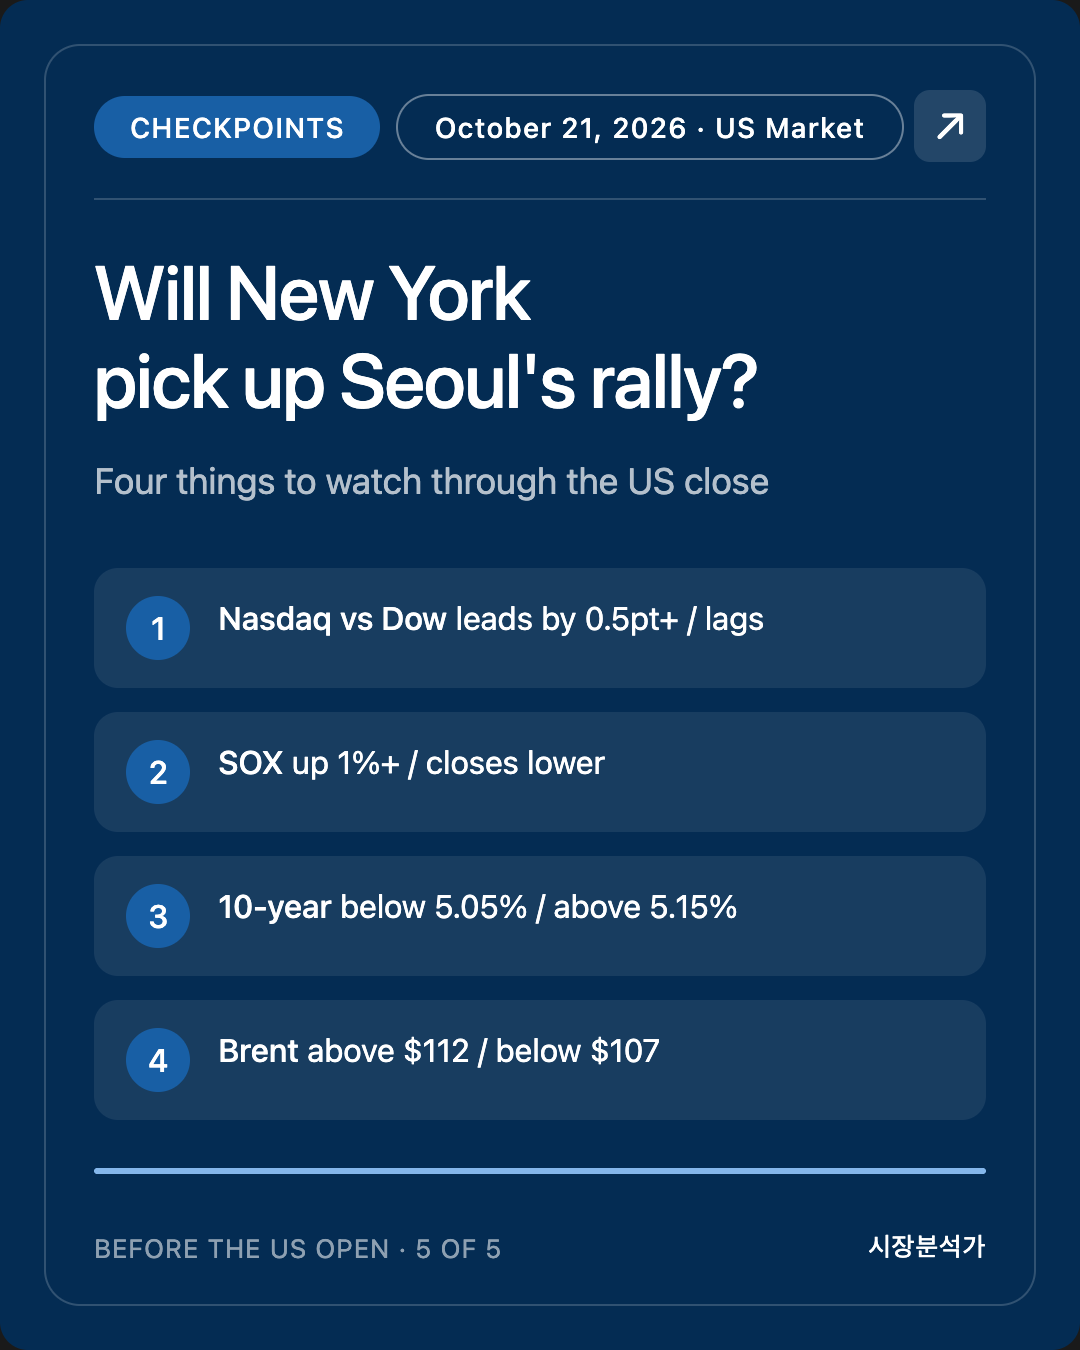
✅ Four checkpoints (through today's US close)
The question: does New York pick up Seoul's chip rebound, or pause ahead of Meta? The third variable is Meta's capital-spending guidance after the close.
- Nasdaq beats the Dow by more than 0.5 points / the Dow beats the Nasdaq. Does the two-day rotation away from AI end? (Most important)
- SOX up more than 1% / closes negative. How much of Seoul's 5% chip rally carries over?
- US 10-year below 5.05% / above 5.15%. Do yields hold even as oil rises?
- Brent above $112 (new five-month high) / below $107.
[Interpretation] If 1 and 2 both land on the positive side, this week's AI scare becomes a case of Seoul overreacting and data settling it. If the Nasdaq leads but the SOX closes lower, the buying is about SpaceX and Tesla headlines, not chips. If Brent tops $112 and the 10-year breaks 5.15%, oil and rates take the wheel back from earnings. And if Meta raises capex again tonight, that becomes tomorrow's fuel for Korean chipmakers.
6. Study Note: The "working-day effect"
Concept
Working days are the days factories and ports actually operate. The same "October 1–20" window can contain more or fewer of them depending on weekends and holidays, and more working days automatically inflate totals. That's why trade data also reports exports per working day.
Analogy
If a shop's monthly sales doubled from last year, but it was closed ten days last year and open every day this year, it isn't really doing twice as well. Divide by days open to see the real performance.
Today's example
Korean exports rose 105.4% in October 1–20. But this year had 13 working days versus 10.5 last year, when the Chuseok holiday fell in that window. Per working day, exports grew 65.9%. Smaller, but still very strong.
Why it matters
Markets react to headlines first, then re-examine per-day and by-product numbers. The full-month data on November 1 will show whether the per-day pace holds.
One-line summary
When reading export growth, look at per working day first.
7. Corrections & Open Items
Corrections
- None.
Source discrepancies (values adopted)
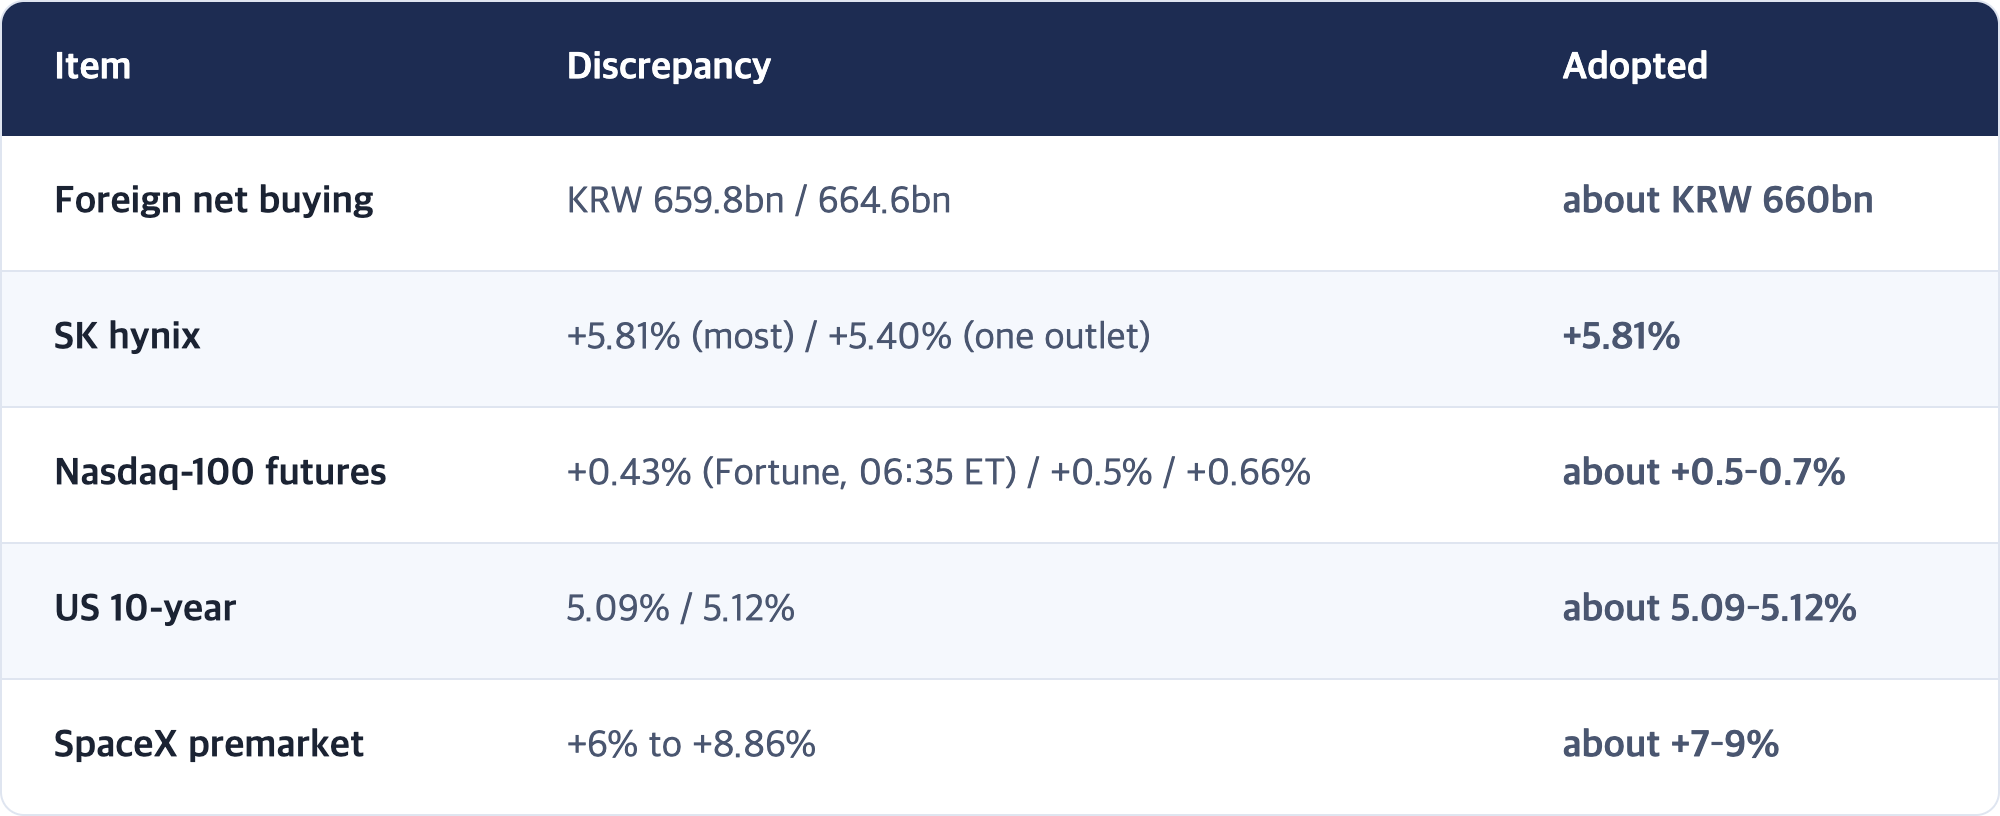
🔲 Not confirmed
8. Event Calendar (PDT)
Sources
- KOSPI closes up 3.3% as foreigners return | Businesskorea
- Foreign buying lifts KOSPI | Korea Economic Daily
- Short-selling briefing, Oct 21 | Topstar News
- Oct 1–20 exports hit record $61.6bn | Asia Economy
- Tech futures rise in premarket trading as SpaceX stock rockets overnight | Fortune
- Stock market today: S&P 500, Nasdaq futures rise as earnings roll in | Yahoo Finance
- US futures mostly higher as Wall Street digests SpaceX, Netflix | Local10/AP
- Today's Market Movers: SpaceX jumps, Netflix falls | CoinCentral
- Earnings live: All eyes on Musk and Meta | Yahoo Finance
- Hang Seng closes down 0.8% | 24/7 Wall St.
- European shares flat as earnings offset French unrest | Reuters via Investing.com
- Brent tops $110 as tanker attacks threaten Gulf supply | OilPrice
- US 10-Year Treasury Yield | Trading Economics
- French stocks slide after violent protests | HL
Market Analyst · This report does not recommend buying or selling any individual security. It offers macro context and interpretation.
📌 More market briefs
※ This post is market observation and organization intended to support your own judgment. It is not a recommendation to buy or sell any security. Figures are as of the time of writing and may differ between sources.
If this was useful, bookmark it or pass it along. It genuinely helps me write the next one.
I can survive. We can survive.