October 1, 2026 US Market Brief — Nasdaq and S&P 500 Before the Open
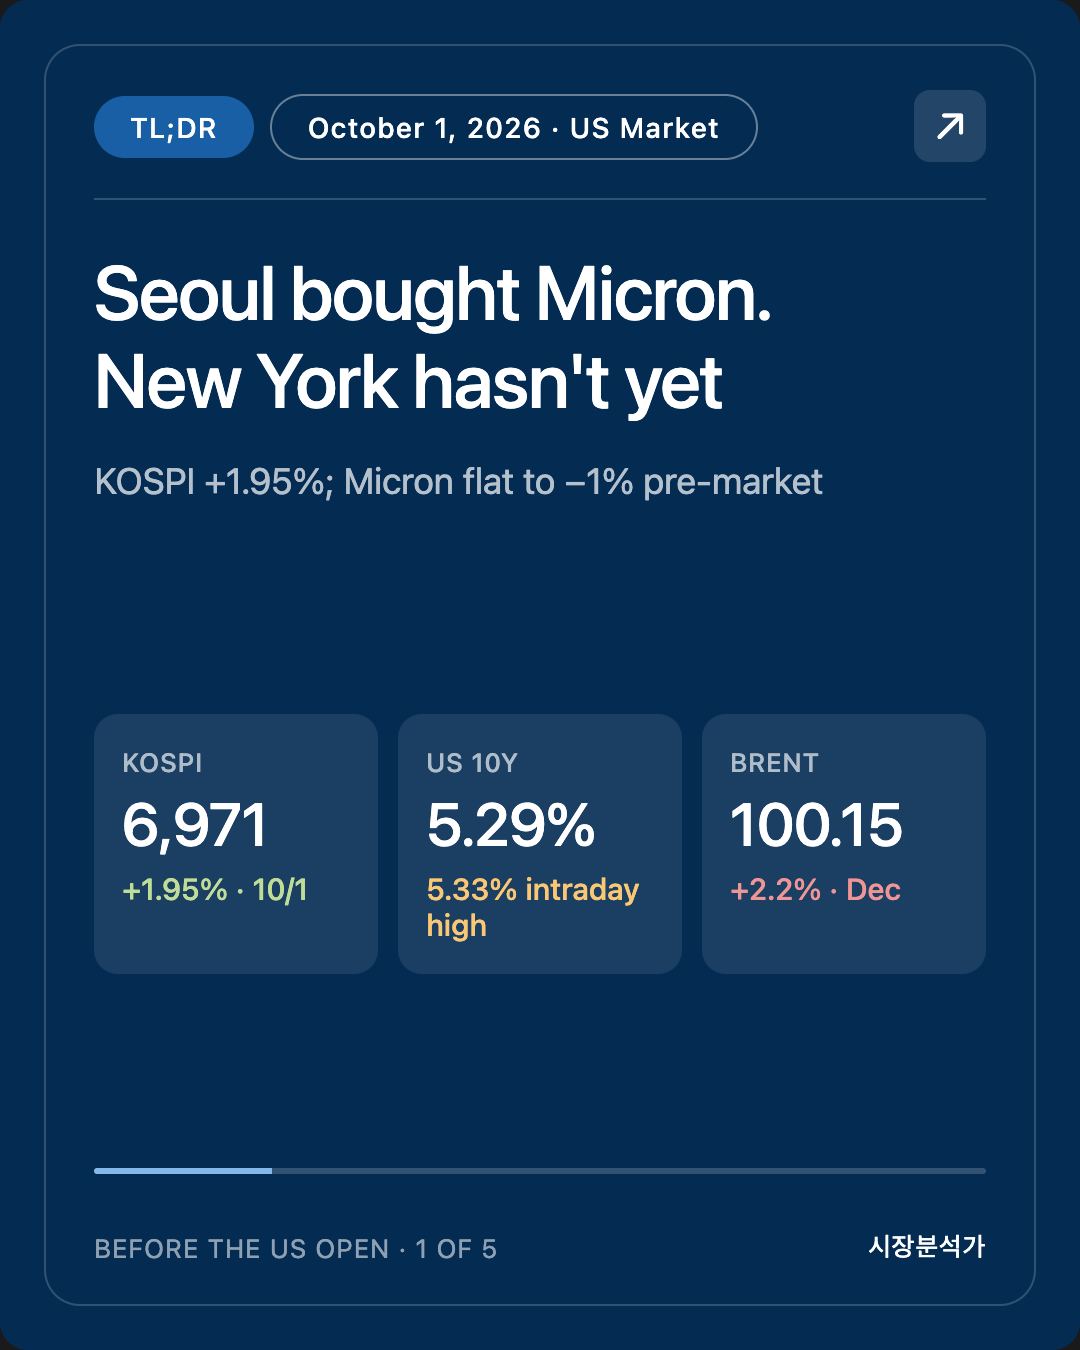
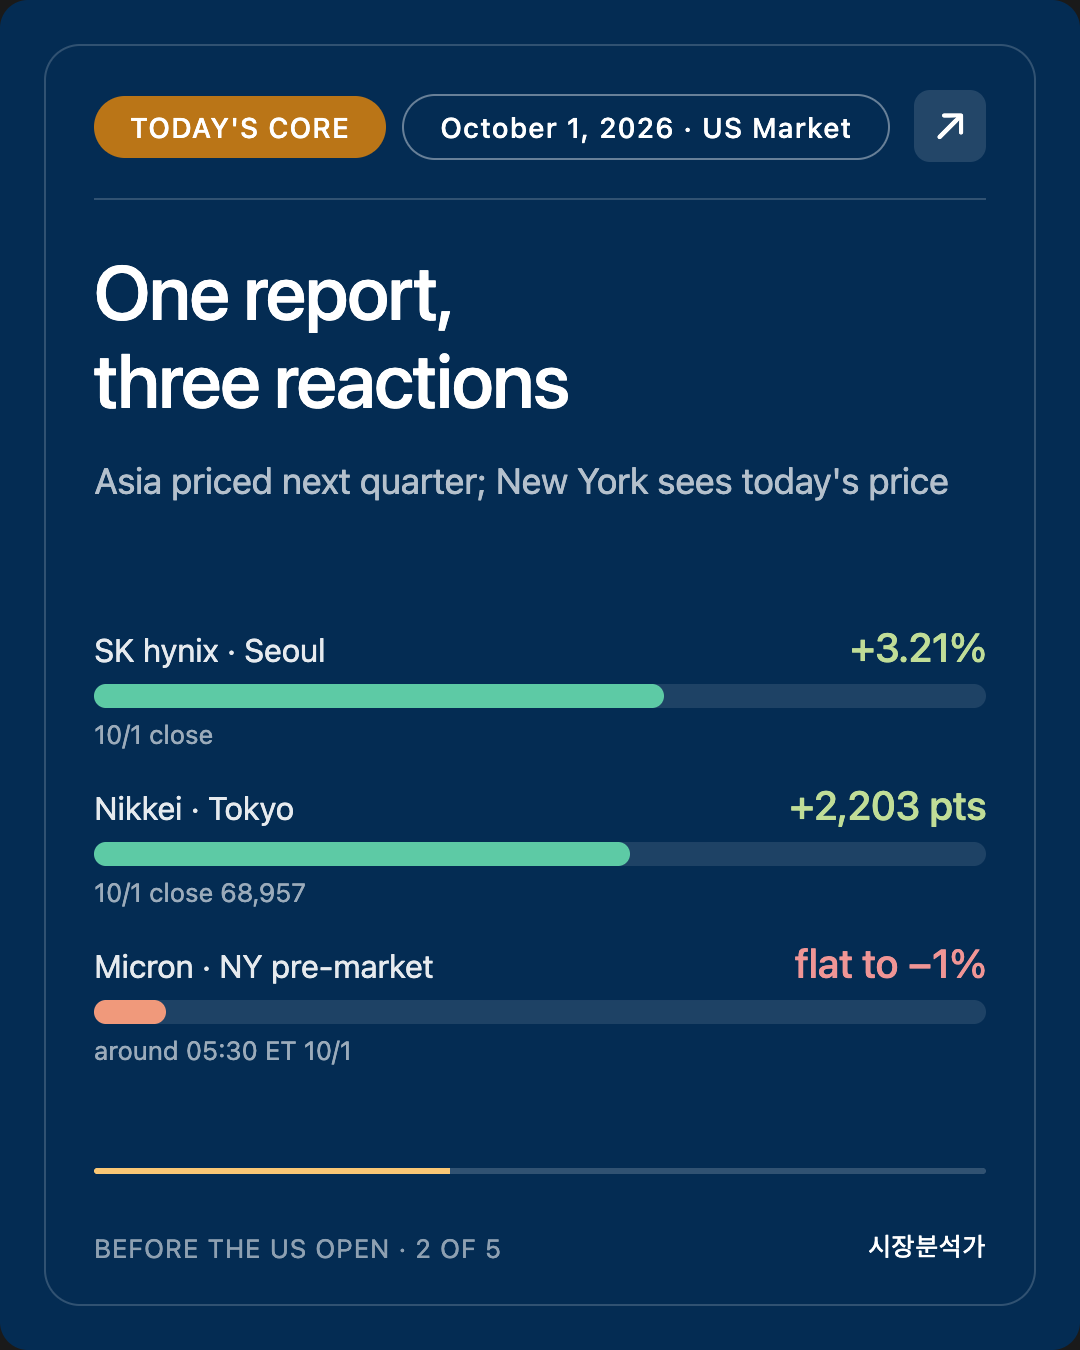
- ★ Seoul and Tokyo bought Micron. KOSPI 6,971.35 (+1.95%), reversing from an intraday low of 6,765.06. Samsung Electronics ₩276,000 (+2.79%) · SK hynix ₩1,833,000 (+3.21%) · KOSDAQ 894.29 (+4.48%). Nikkei 68,957 (+2,203 pts).
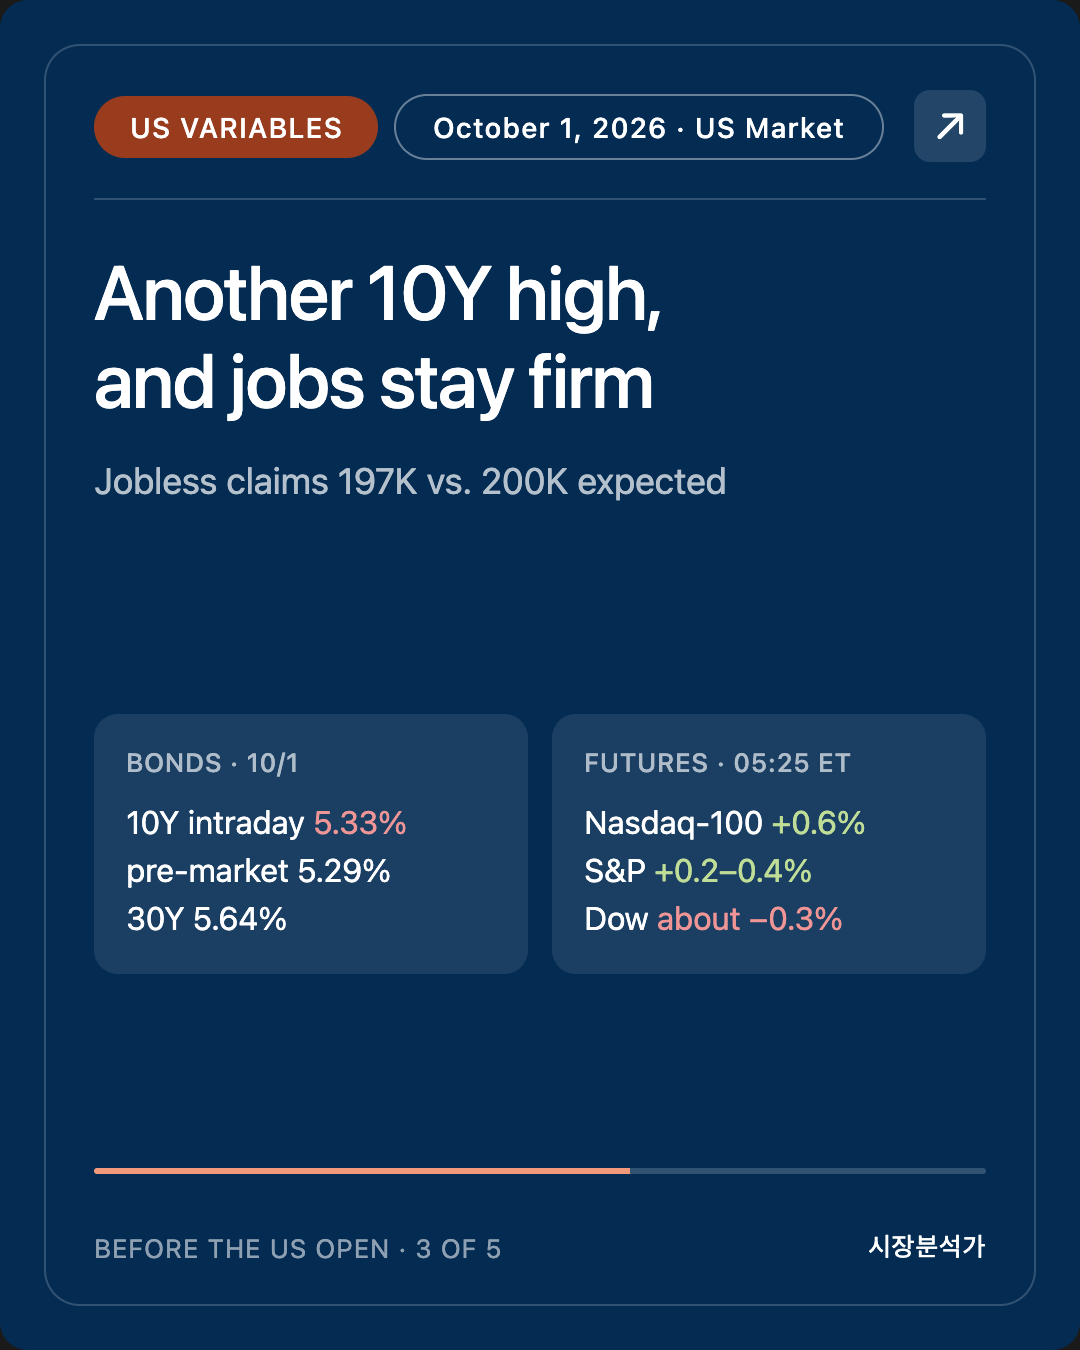
- ★ New York hasn't bought it yet. Micron is flat to −1% pre-market. Nasdaq-100 futures +0.6% reflect AI megacaps; Dow futures about −0.3% (05:25 ET, a three-month low).
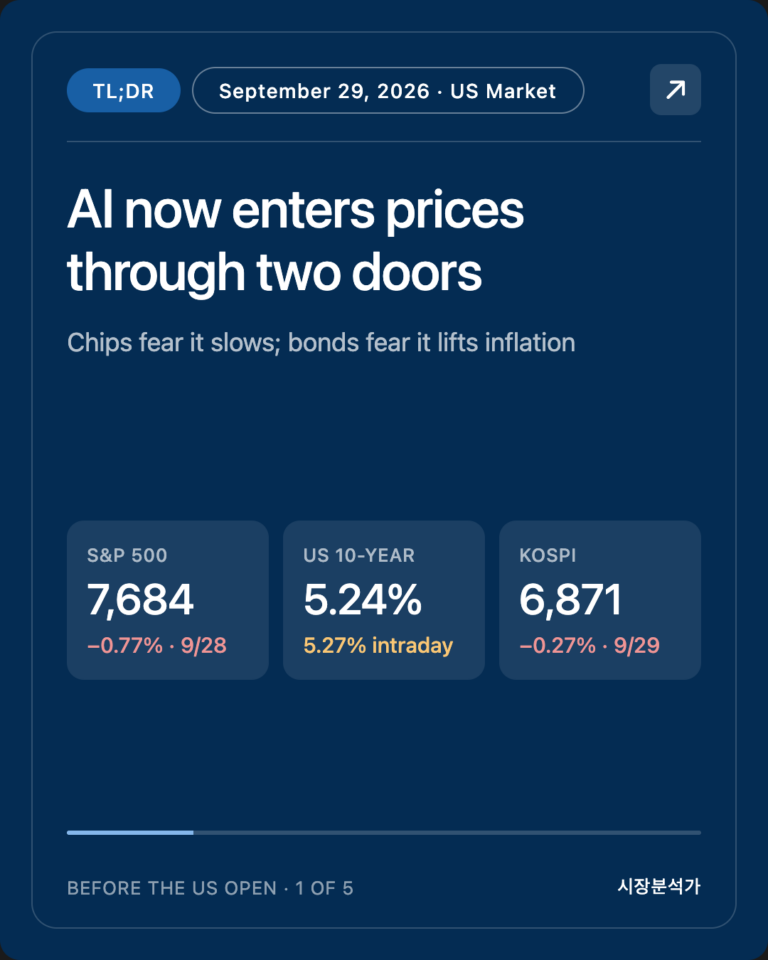
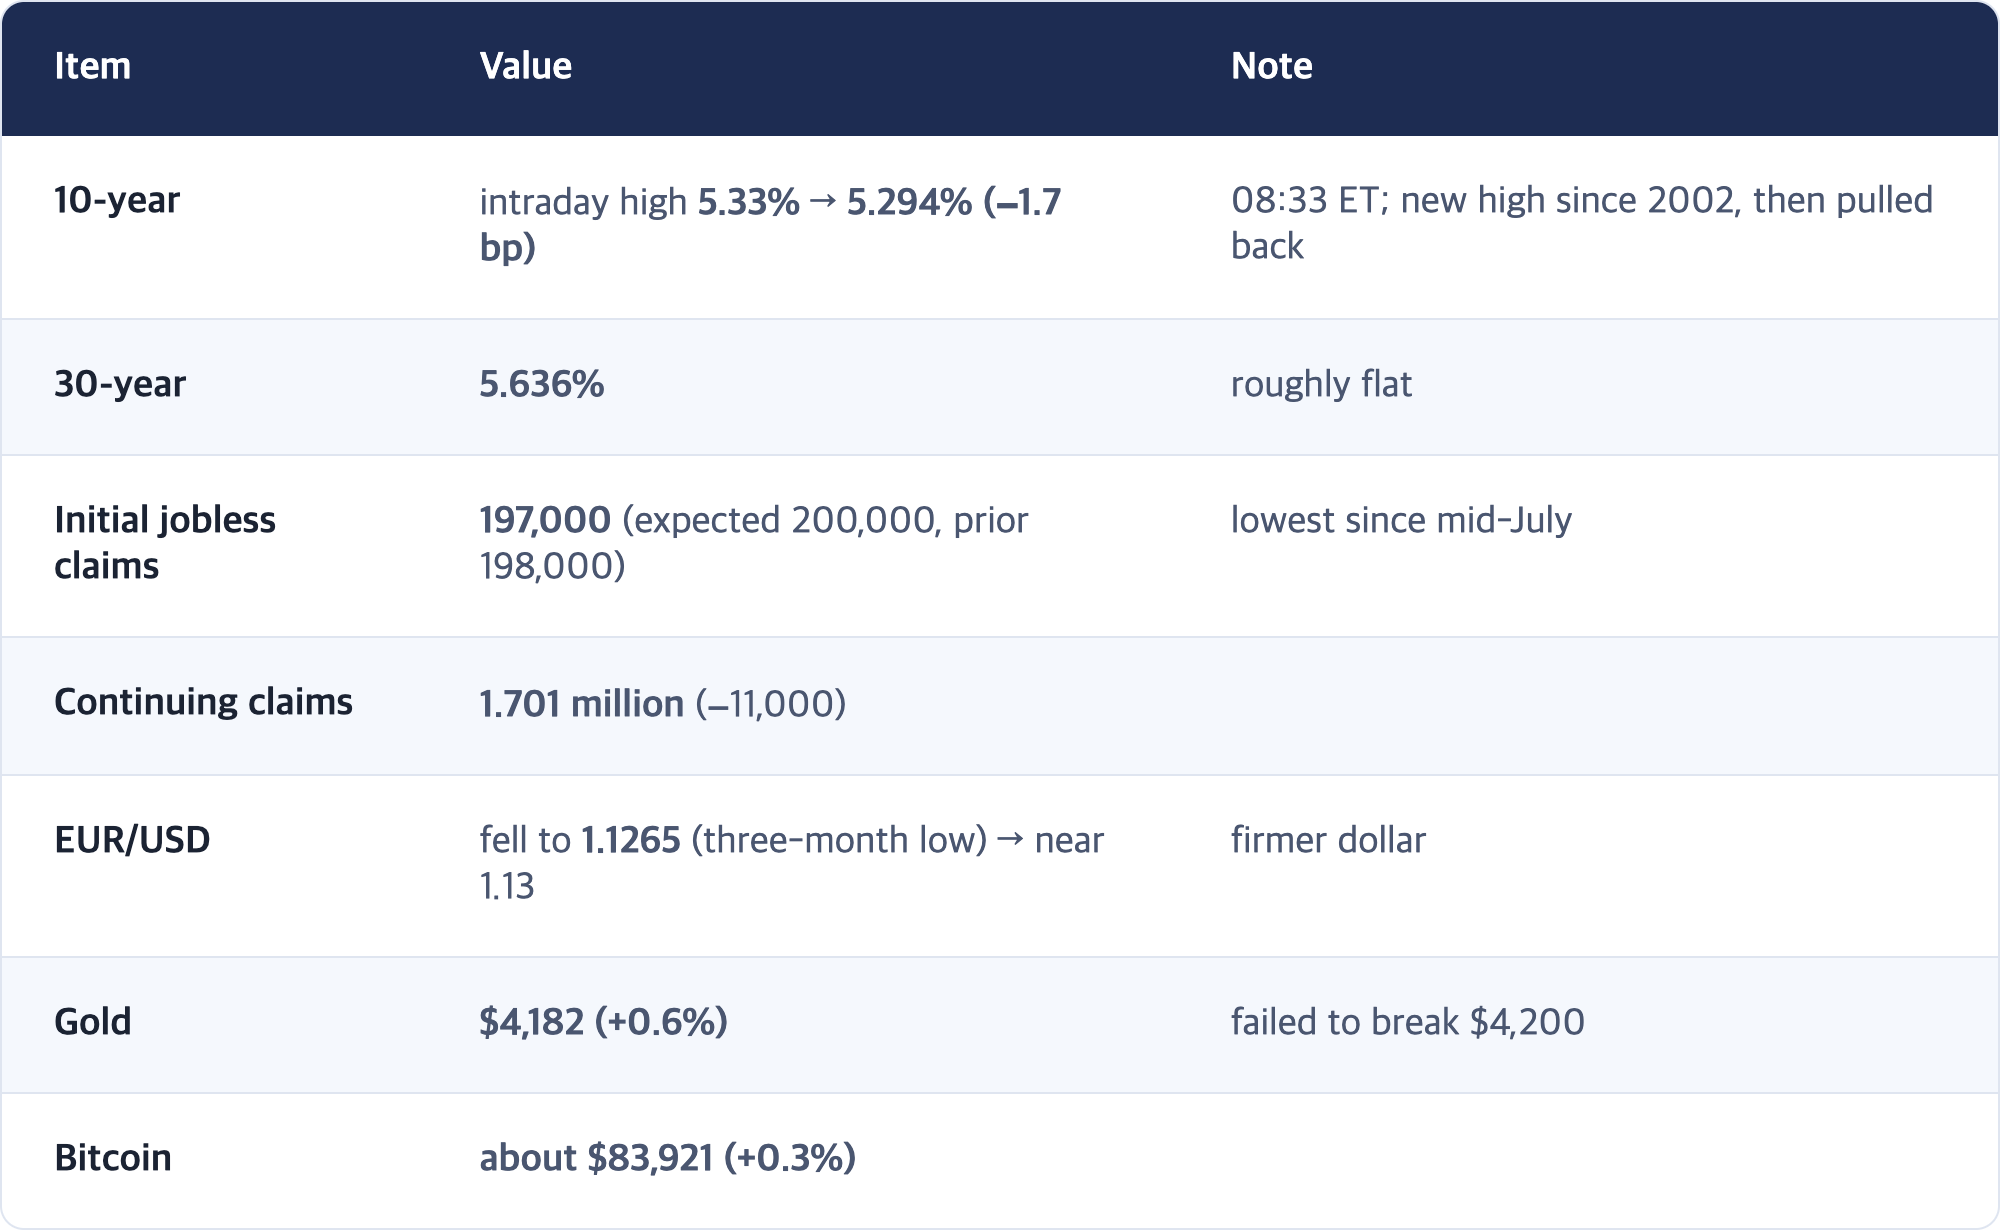
- Long yields climbed again. 10-year hit 5.33% intraday (highest since 2002), now 5.29%. 30-year 5.64%. Initial jobless claims 197,000 (expected 200,000): the labor market is still firm.
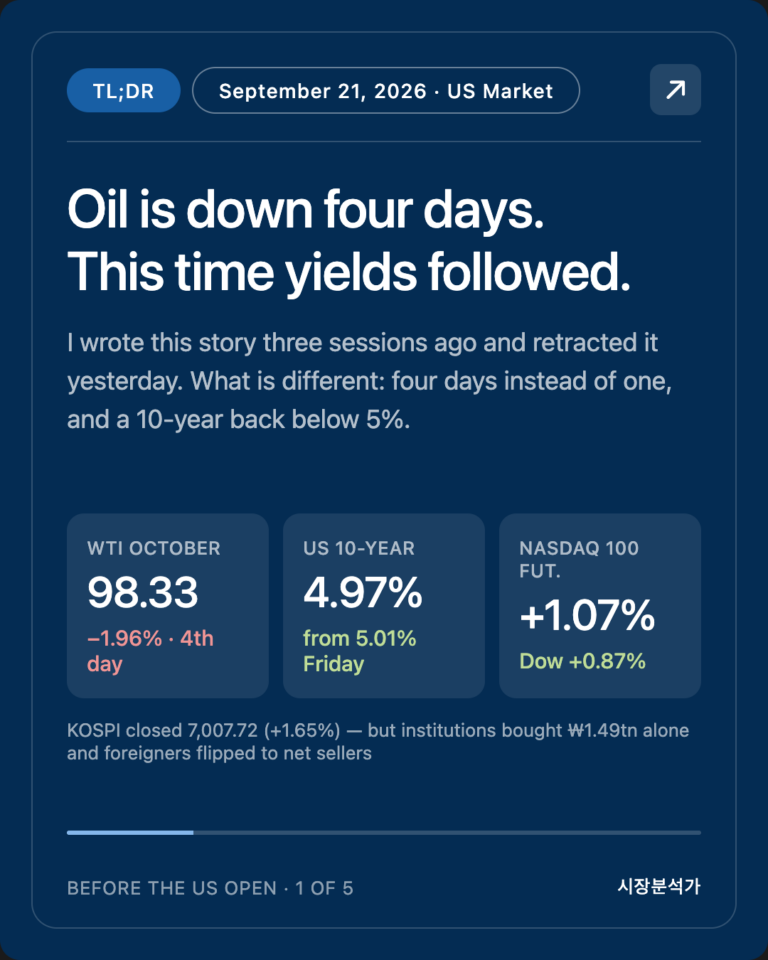
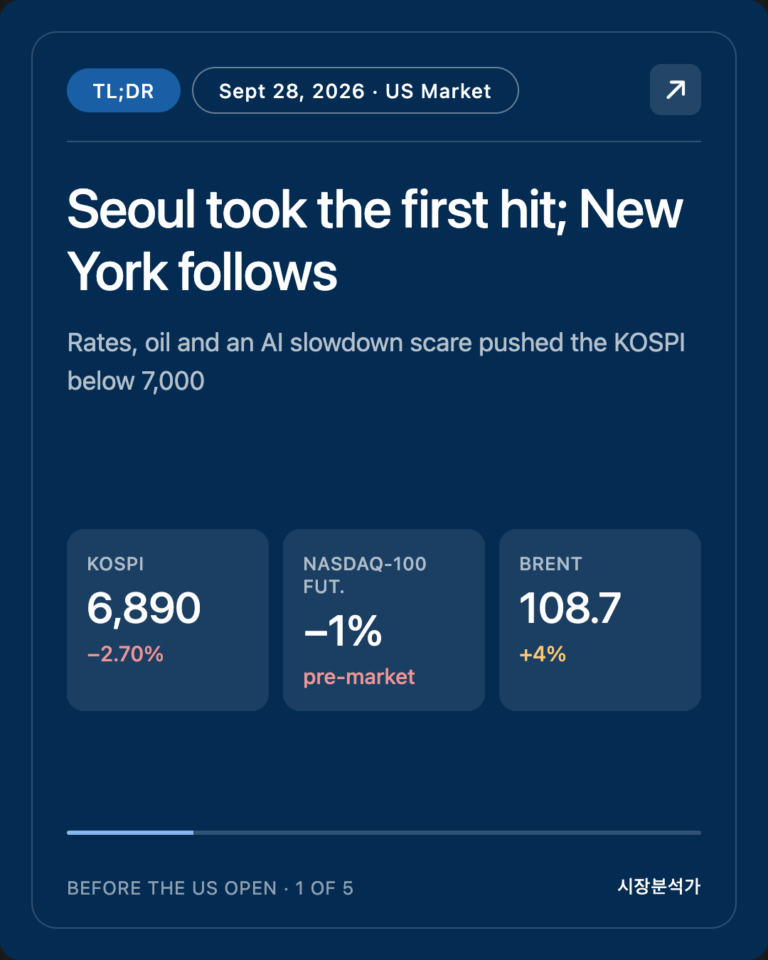
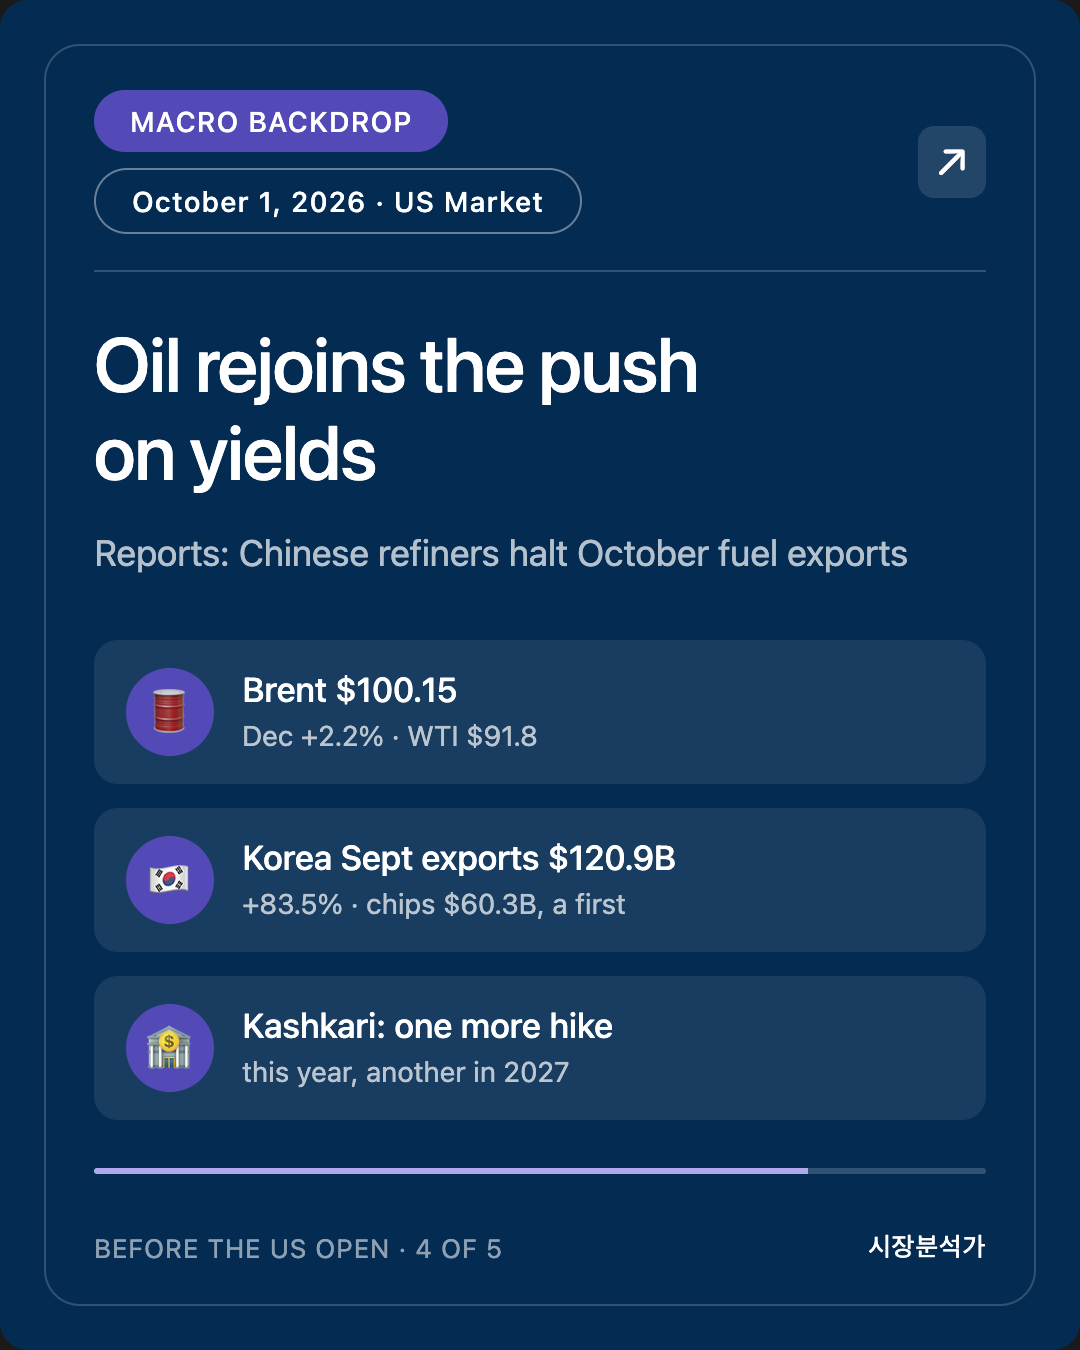
- Oil is back. Brent December $100.15 (+2.2%), WTI $91.7–91.8 (+1.5%), on reports that Chinese refiners halted October fuel exports and with US-Iran talks stalled.
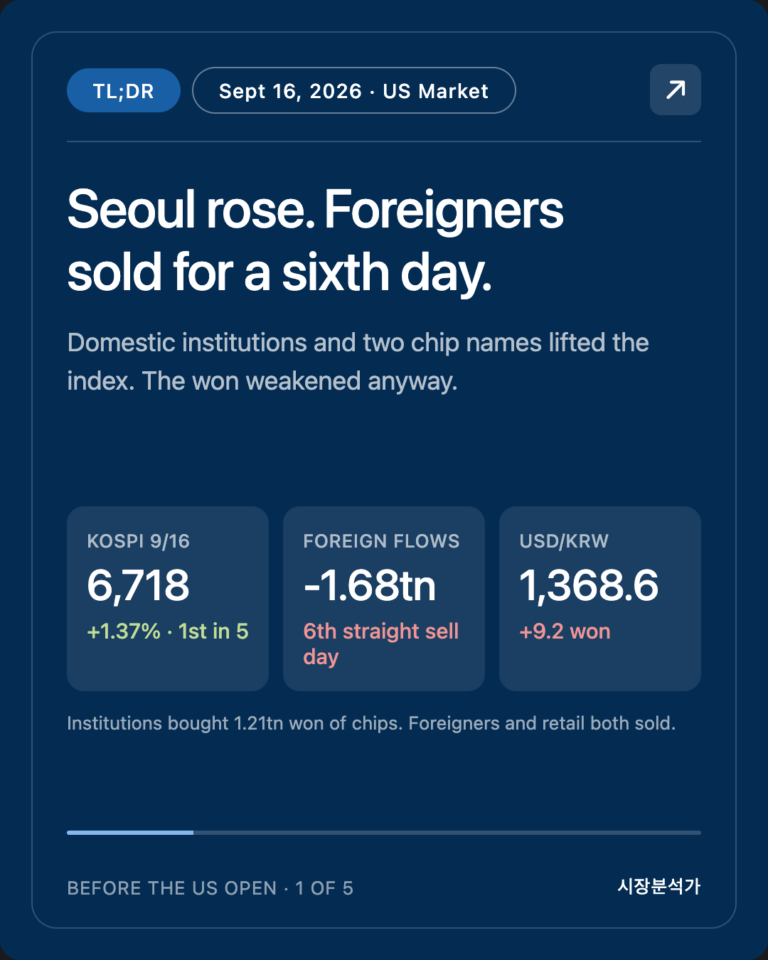
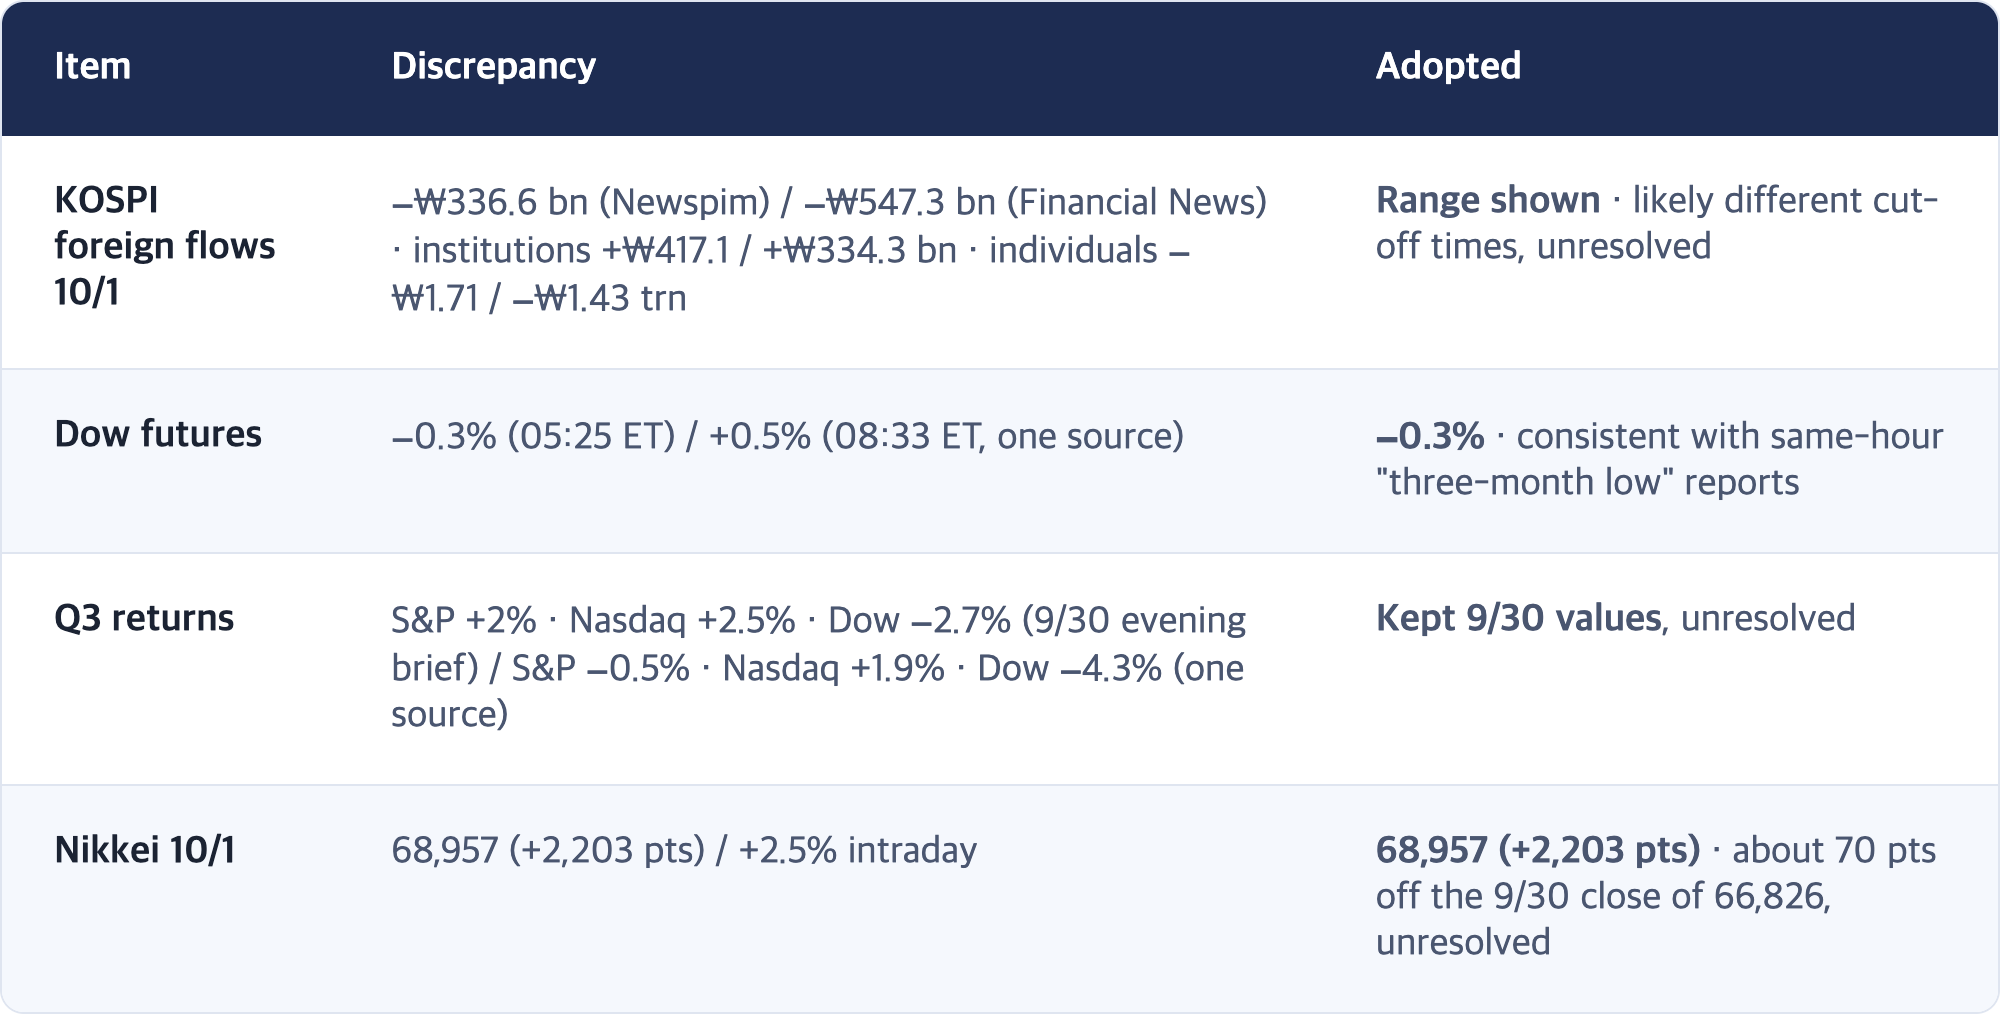
- Foreign investors sold Korean stocks for a fifth straight day, but at a quarter of the pace or less. Net foreign selling ₩336.6–547.3 billion (sources differ) · USD/KRW 1,358.4 (+5.6).
This is Mr. Can. Here is the October 1, 2026 brief ahead of the US market open.
Written: 2026-10-01 05:50 PDT (Seoul 10/1 21:50 KST)
Basis: US 9/30 final closes + Seoul and Tokyo 10/1 closes (Hong Kong and Shanghai closed for China's National Day) + Europe 10/1 intraday + US 10/1 pre-market (just after the 05:30 PDT jobless claims release)
🟢 Scheduled for 05:30 PDT, started 05:43 PDT. US figures are pre-market.
This edition scores the four Seoul checkpoints set in the 9/30 evening brief. No corrections; four source discrepancies are listed in section 7.
SEO Intro
Asia bought Micron's blowout quarter. Korea's KOSPI fell as low as 6,765 in the morning, then reversed to close at 6,971.35 (+1.95%); the small-cap KOSDAQ jumped 4.48%. Korea's September exports, released at the open, hit a record $120.9 billion (+83.5% y/y), with semiconductors alone at $60.3 billion (+262.8%), the first time a single product has topped $60 billion in a month. Japan's Nikkei gained 2,203 points.
New York is less convinced. Micron shares are flat to −1% in pre-market trading. The US 10-year Treasury yield touched 5.33% in the European session, another high going back to 2002, and Brent crude is back above $100. Today's question for Wall Street: will the home market of the company that delivered the news pay for it, or discount it at 5.3% yields?
1. Checkpoint Scorecard
The four set in the 9/30 evening brief (Seoul close, 10/1)
The axis was: does Seoul follow Micron's memory beat, or react more to the 5.3% US 10-year?
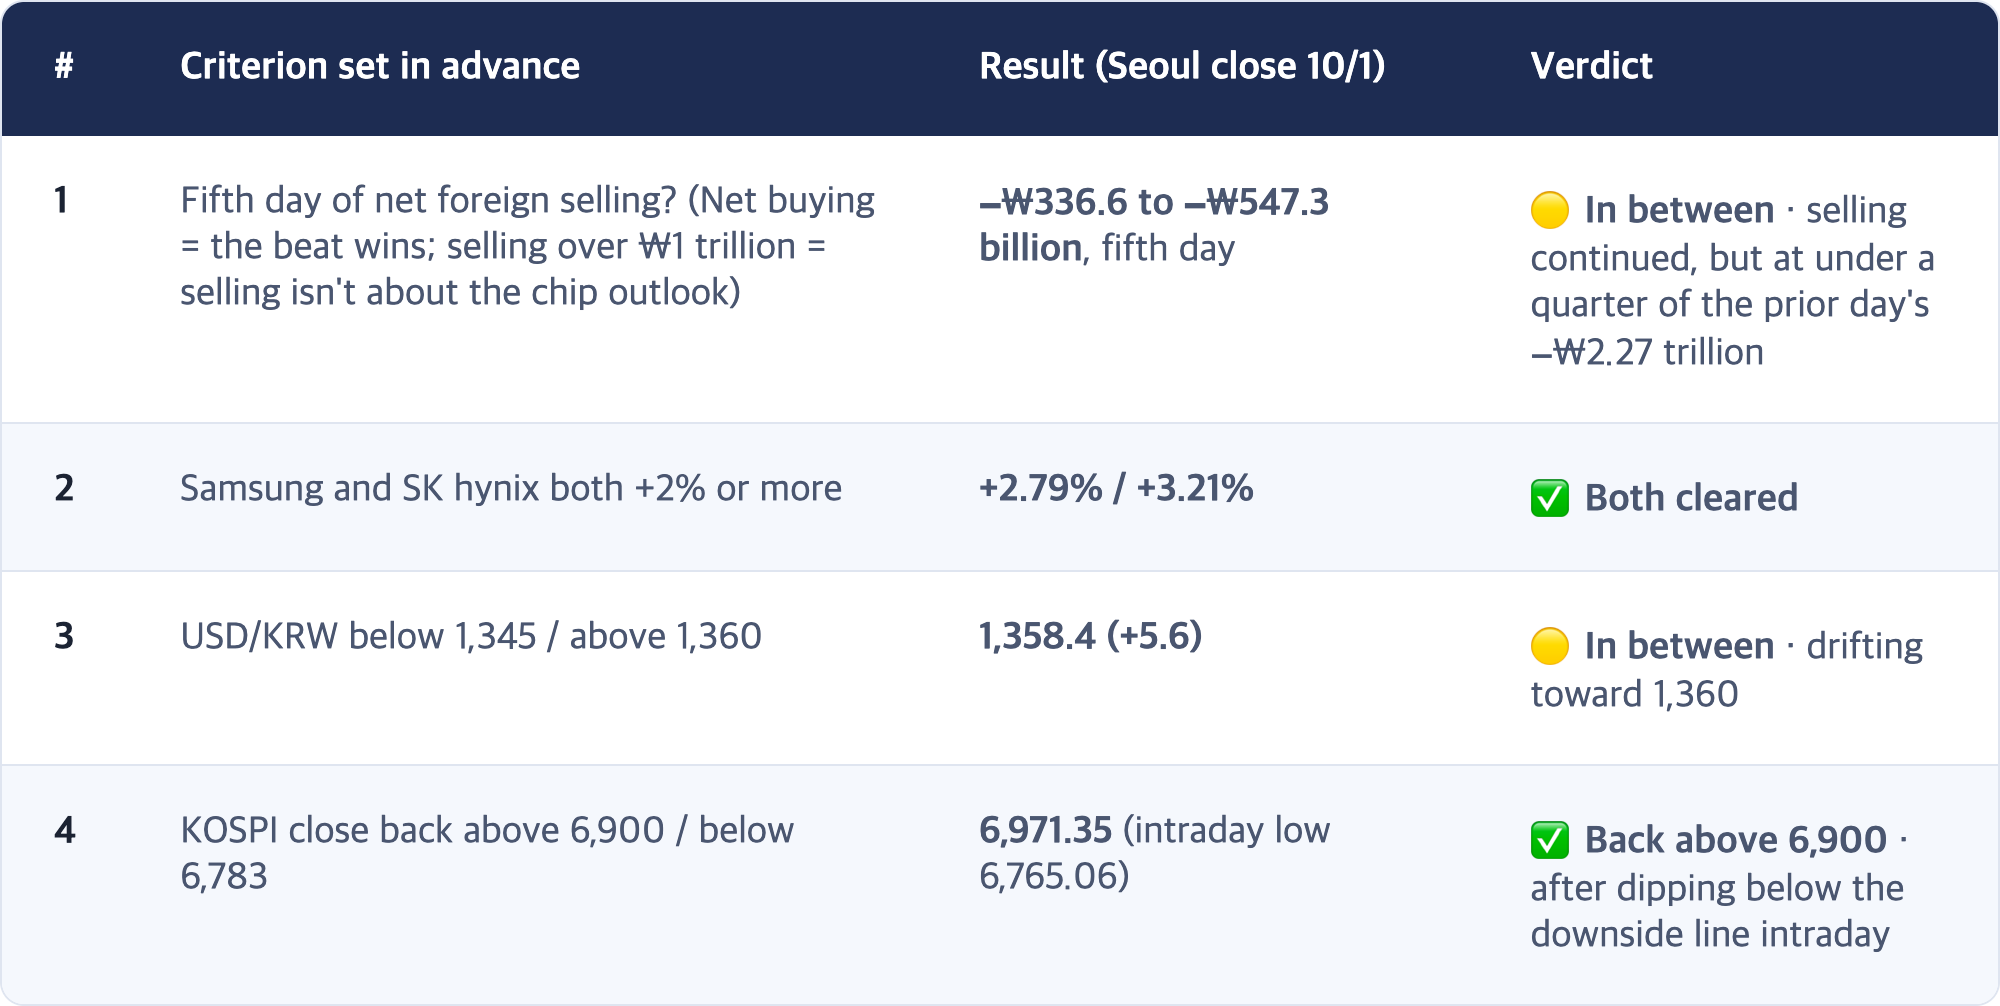
[Interpretation] The chip outlook wasn't why foreigners sold; yields set how hard they sell
Checkpoint 1 carries the most information. Foreign investors still sold, but far below ₩1 trillion, so by the pre-set rule it's an undecided middle reading. Still, selling shrinking from ₩2.27 trillion to ₩0.3–0.5 trillion in a day suggests sellers stepped back sharply once the chip outlook improved.
Checkpoints 2 and 4 are clear. The index sank to 6,765 (about −1.1%) in the morning, then reversed with the export data. [Interpretation] Inside Seoul, rates were priced in the morning and earnings in the afternoon, the exact reverse of 9/30 (chip rebound in the morning, rate pressure in the afternoon).
Checkpoint 3 adds a caveat: the won weakened for the first time in three days (1,352.8 → 1,358.4). A stronger dollar during European hours may have contributed; this edition could not pin down the cause.
2. Today's Core: Asia bought the memory beat, New York is discounting it
[Fact] One earnings report, three reactions
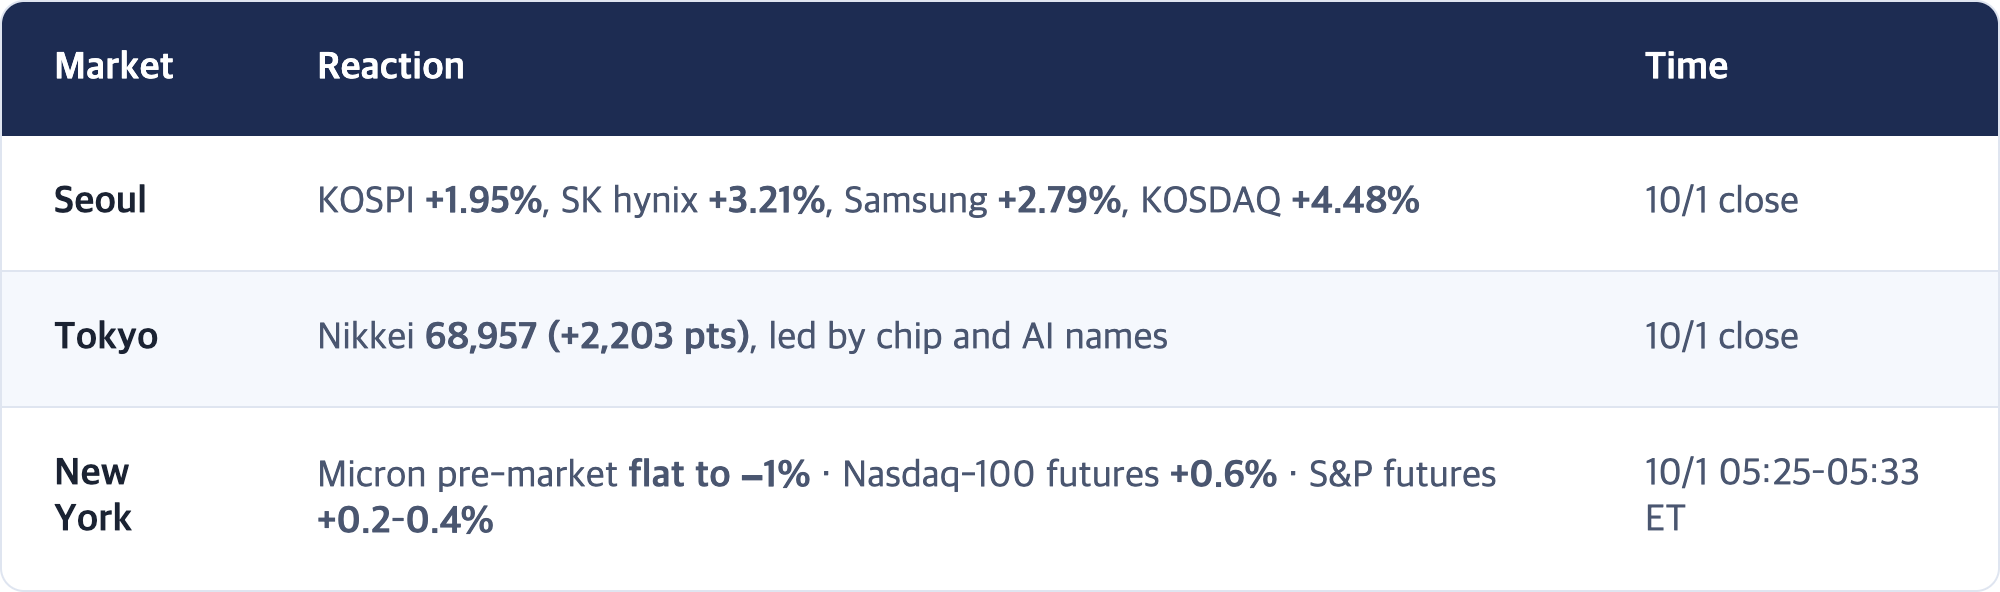
- Micron recap: revenue $54.23 billion (expected $51.07 billion); next-quarter revenue guidance $60–63 billion (midpoint $61.5 billion); customer commitments under long-term supply agreements raised to $32 billion (reported).
- Micron shares had more than tripled this year (reported).
[Fact] Korea's September exports (released 09:00 KST 10/1)
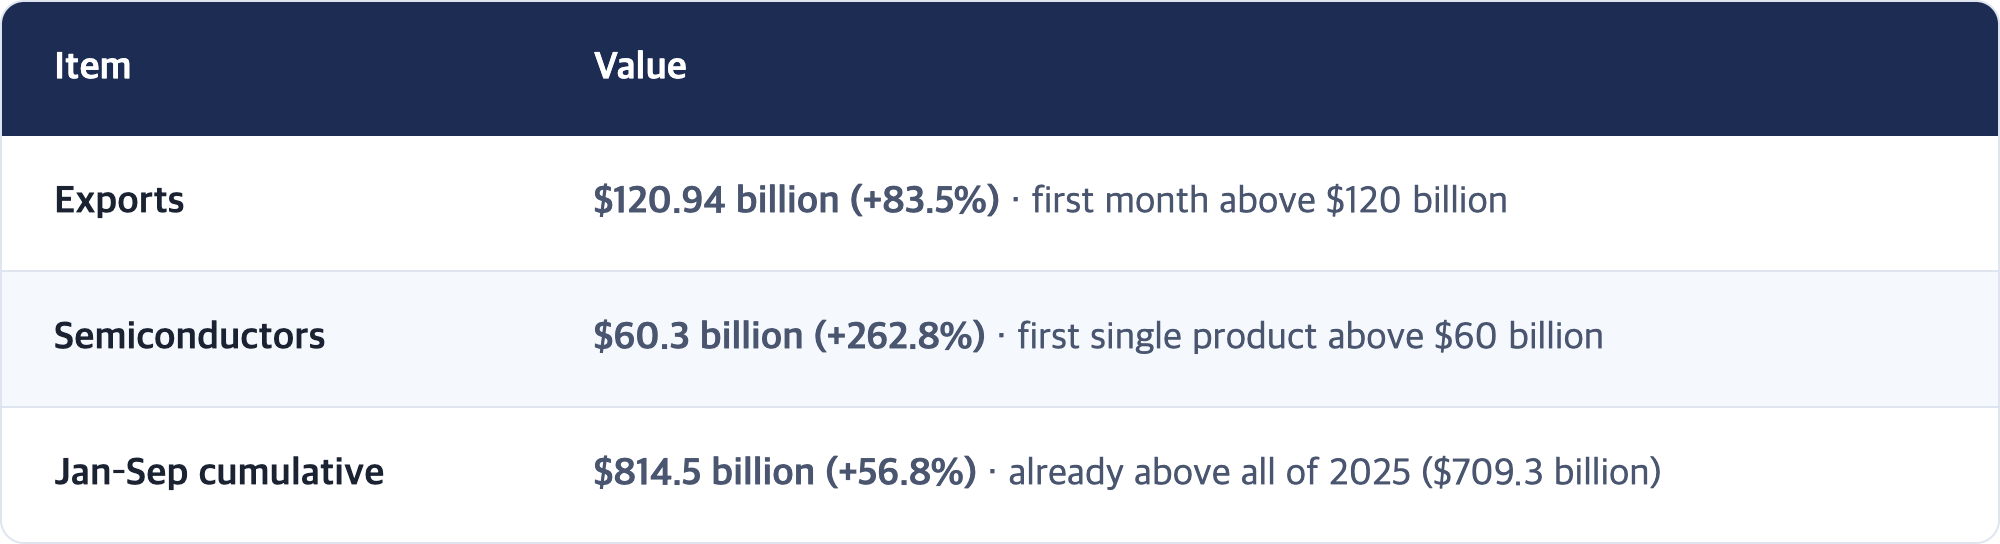
★ [Interpretation] Same numbers, different readings: how much was already priced in, and at what discount rate
For Seoul and Tokyo, Micron's results are a preview of next quarter for Samsung, SK hynix and Japanese chip-equipment makers. Seoul had also just absorbed more than ₩8 trillion of foreign selling over four days, so there was room to snap back on good news.
In New York, Micron is in a different position: up threefold this year and more than 50% in September alone. [Interpretation] As the 9/30 evening brief put it, this was closer to "confirming expectations" than "beating them." And the rate used to discount those expectations, the 10-year yield, hit another high this morning.
[Observation] Where Micron and the Philadelphia Semiconductor Index (SOX) close today will decide whether Seoul has grounds to hold today's gain tomorrow (10/2). If New York doesn't confirm, Seoul's +1.95% stays an "Asia-only" day.
3. US Variables: a 5.33% 10-year and a firm labor market
[Fact] US 9/30 final closes (reconfirmed)
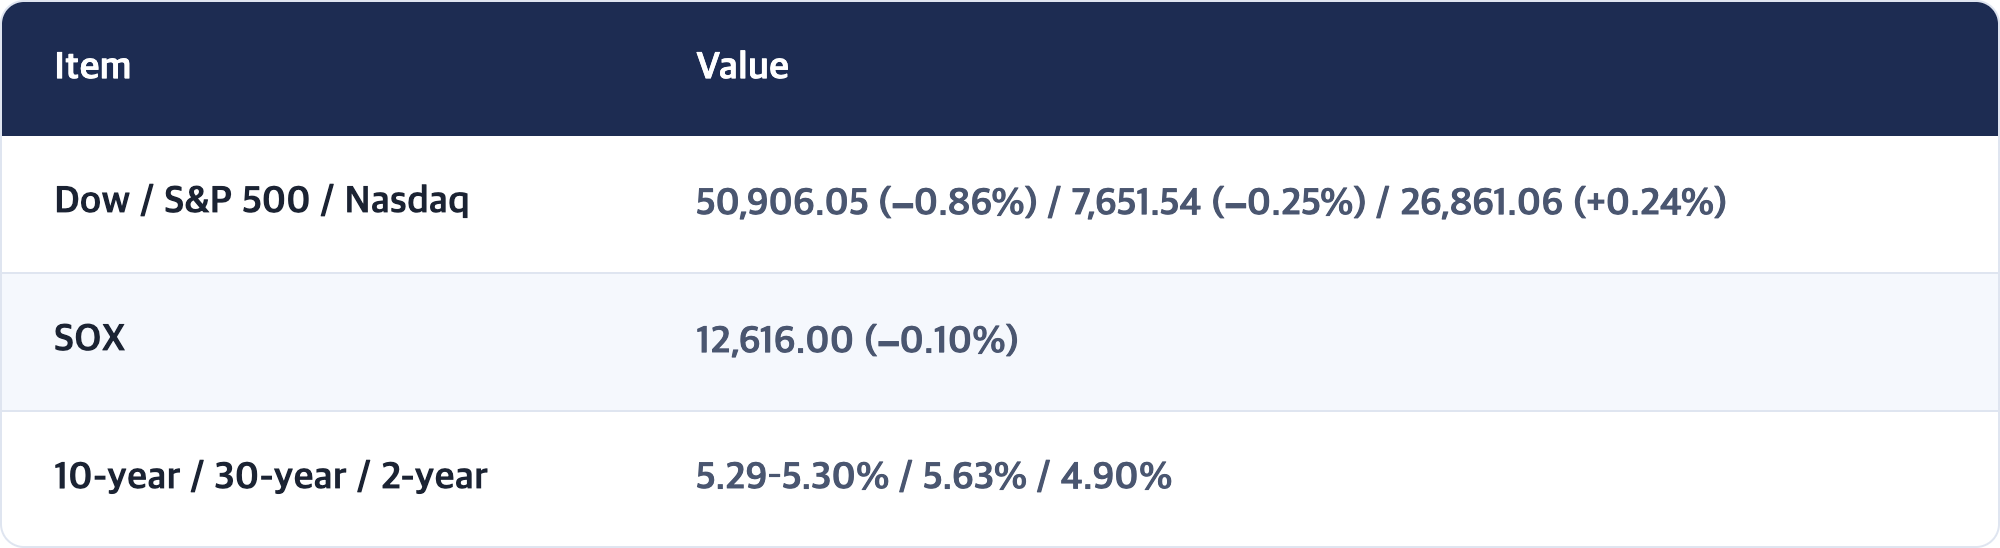
[Fact] Overnight and pre-market 10/1
[Observation] Fed voices
- Minneapolis Fed President Neel Kashkari (reported): inflation, at about 3%, is still too high; he pencils in one more hike this year and another in 2027.
- That fits the 9/30 evening reading that the next hike has shifted from October to December rather than disappeared.
[Interpretation] With jobs still solid, long yields have no reason to rest
Claims stayed under 200,000. For the Fed, that's "inflation is cooling, but jobs are fine": no rush, but no reason to stop either. Tomorrow's (10/2) 05:30 PDT September jobs report will either confirm or break that picture.
4. Macro Backdrop: Brent is back at $100
[Fact]
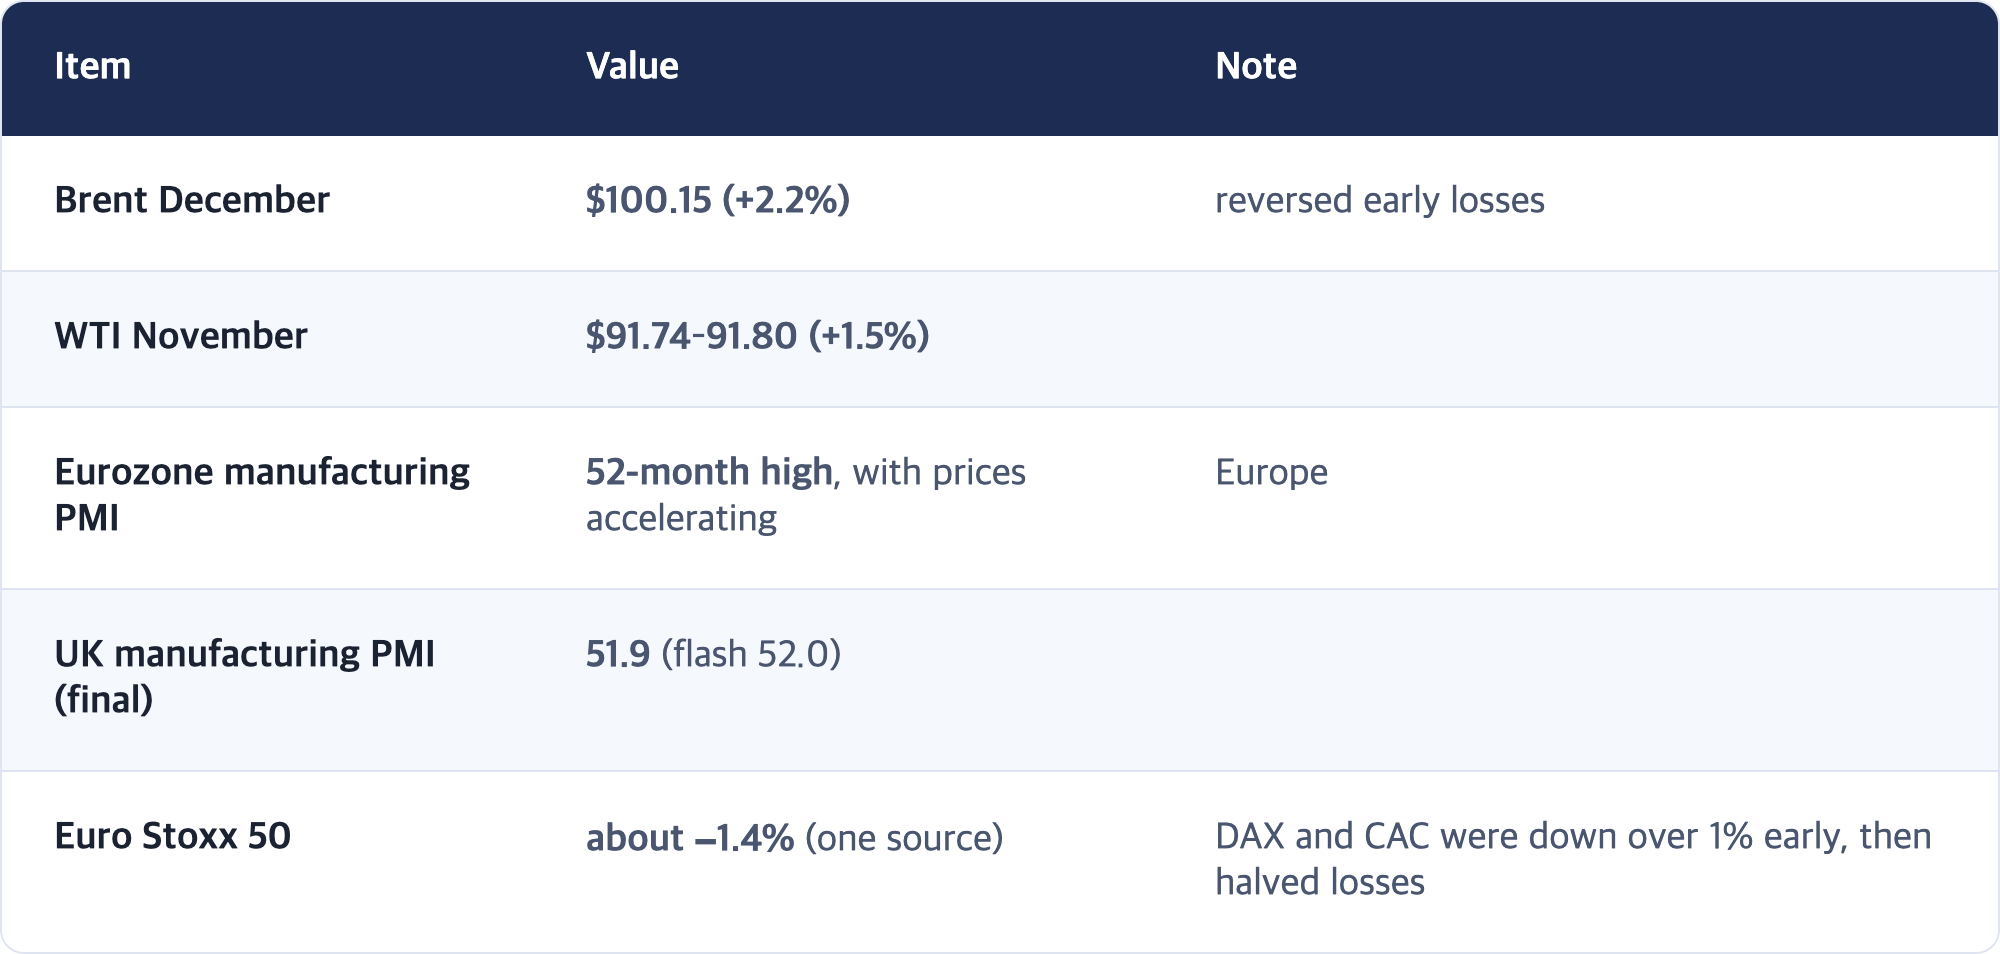
- Why oil reversed (reported): Chinese refiners suspended October fuel exports to protect domestic supply. US-Iran talks are stalled; Secretary of State Rubio reportedly ordered Iran's UN delegation to leave New York.
- The 9/30 morning brief flagged diesel rising while crude fell (global transport-fuel tightness). Today that signal got a concrete driver: China's fuel export halt.
[Interpretation] Another hand may be pushing yields up
This week, long yields rose on a day oil fell (9/29) and on a day inflation cooled (9/30); fiscal worries and the term premium were the main story. Today, oil rejoined. Europe's PMI showing faster price increases points the same way. [Interpretation] This morning has fewer reasons for yields to fall and more reasons for them to rise.
5. Today's US Session (Thu 10/1, PDT) Preview
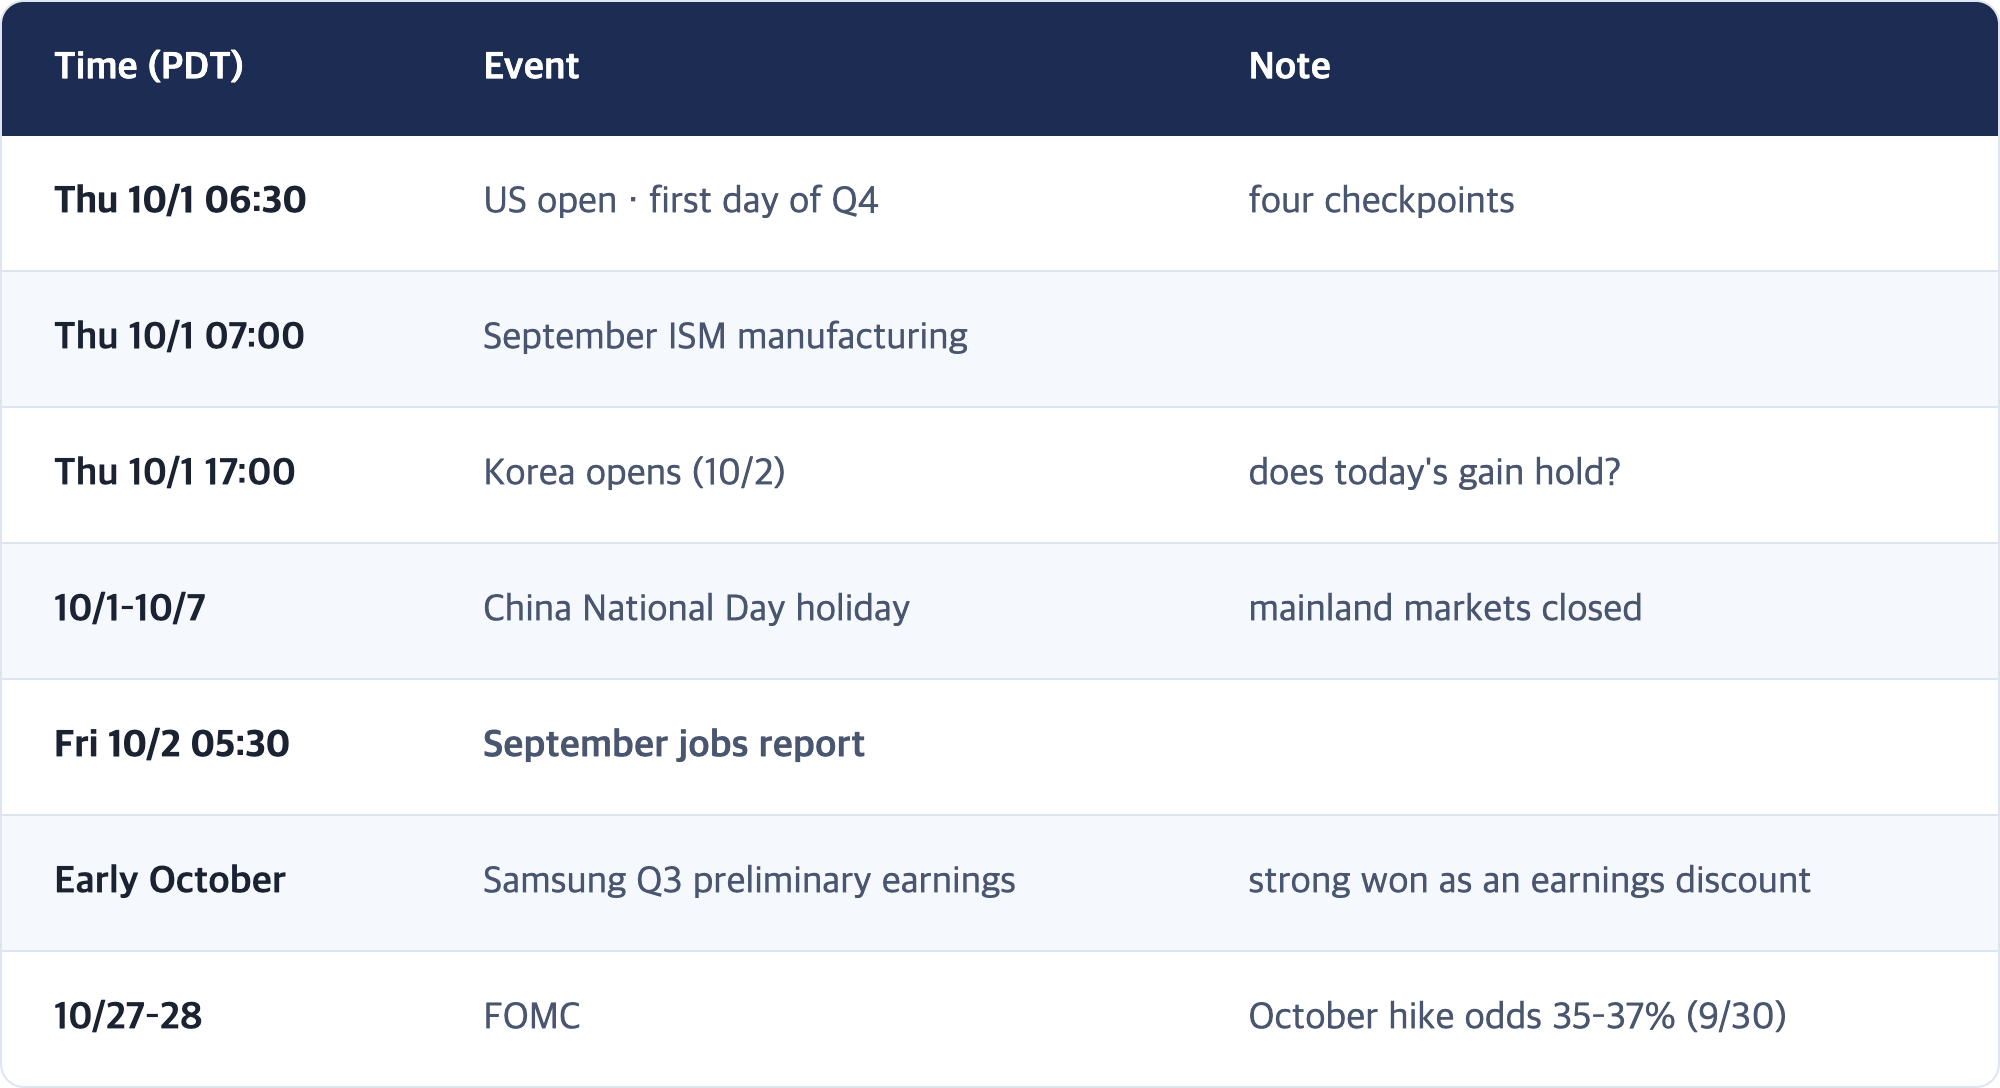
[Observation] Schedule (PDT)
- 06:30 US open · first trading day of Q4
- 07:00 September ISM manufacturing (consensus not secured in this edition)
- Fri 10/2 05:30 September jobs report
- Fri 10/2 Korea opens after seeing today's US session
✅ Four checkpoints (through today's US close)
The axis first: these four test whether New York buys the memory beat like Asia did, or discounts it at 5.3% long yields. The answer decides whether Seoul has grounds to hold today's +1.95% tomorrow.
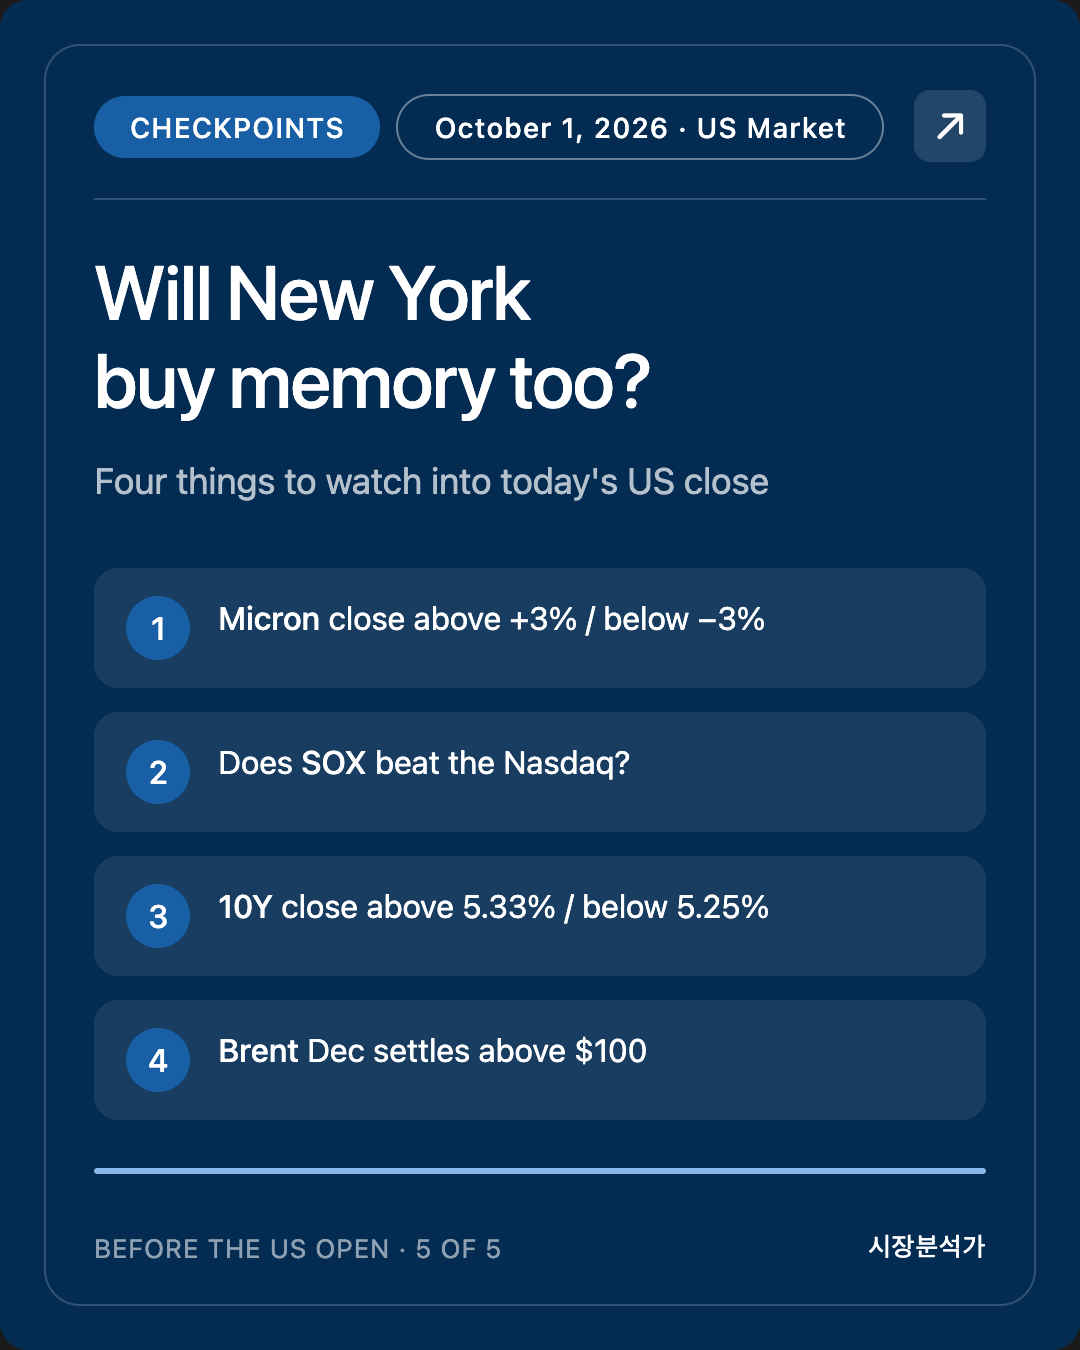
- Micron's regular-session close above +3% / below −3%. Above = New York bought the results too; below = "confirm and take profits" won. (Most important)
- Does SOX outperform the Nasdaq? Chips beating AI megacaps means the memory story is alive; lagging means today's Nasdaq gain belongs to AI platforms.
- 10-year close above 5.33% / below 5.25%. Above = a new closing high; below = the first pause in this week's rate pressure.
- Does Brent December settle above $100? Above = oil has rejoined the forces pushing yields; below = today's jump was one headline.
[Interpretation] Checkpoint 1 matters most. Seoul bought Micron's next quarter; New York is looking at Micron's current share price. If the two diverge, watch whether foreign investors return to heavy selling in Seoul tomorrow.
6. Study Note: Same results, different reactions. What does "priced in" mean?
Concept
Priced in means good news is already reflected in the share price before it's officially announced. Markets don't react to the reported number itself, but to how much better it is than what everyone expected. And "what everyone expected" includes not only the official consensus but also the unspoken expectation (the "whisper number") built up by how far the stock has already risen.
Analogy
Before an exam, a rumor spreads among classmates: "She's going to score 95 this time." The teacher's official expectation was 85. If she scores 92, the teacher sees an impressive result, but her classmates shrug: "Less than I thought."
Today's example
- Micron's official consensus for next-quarter revenue: about $57 billion. Actual guidance: $61.5 billion. By the official yardstick, a big surprise.
- But the stock had tripled this year and gained over 50% in September. New York responded with "we knew that" (flat to −1% pre-market).
- Seoul was different. Foreign investors had sold over ₩8 trillion in four days, so expectations were depressed. The same numbers read as "better than we thought."
One-line summary
The same results can land very differently depending on how much expectation had already built up. When reading earnings or data, look not only at "versus consensus" but also at how far the price moved before the release (the same lesson as the 9/11 brief: "measure surprises against price, not consensus").
7. Corrections and Open Items
Corrections
- None.
Source discrepancies (adopted values noted)
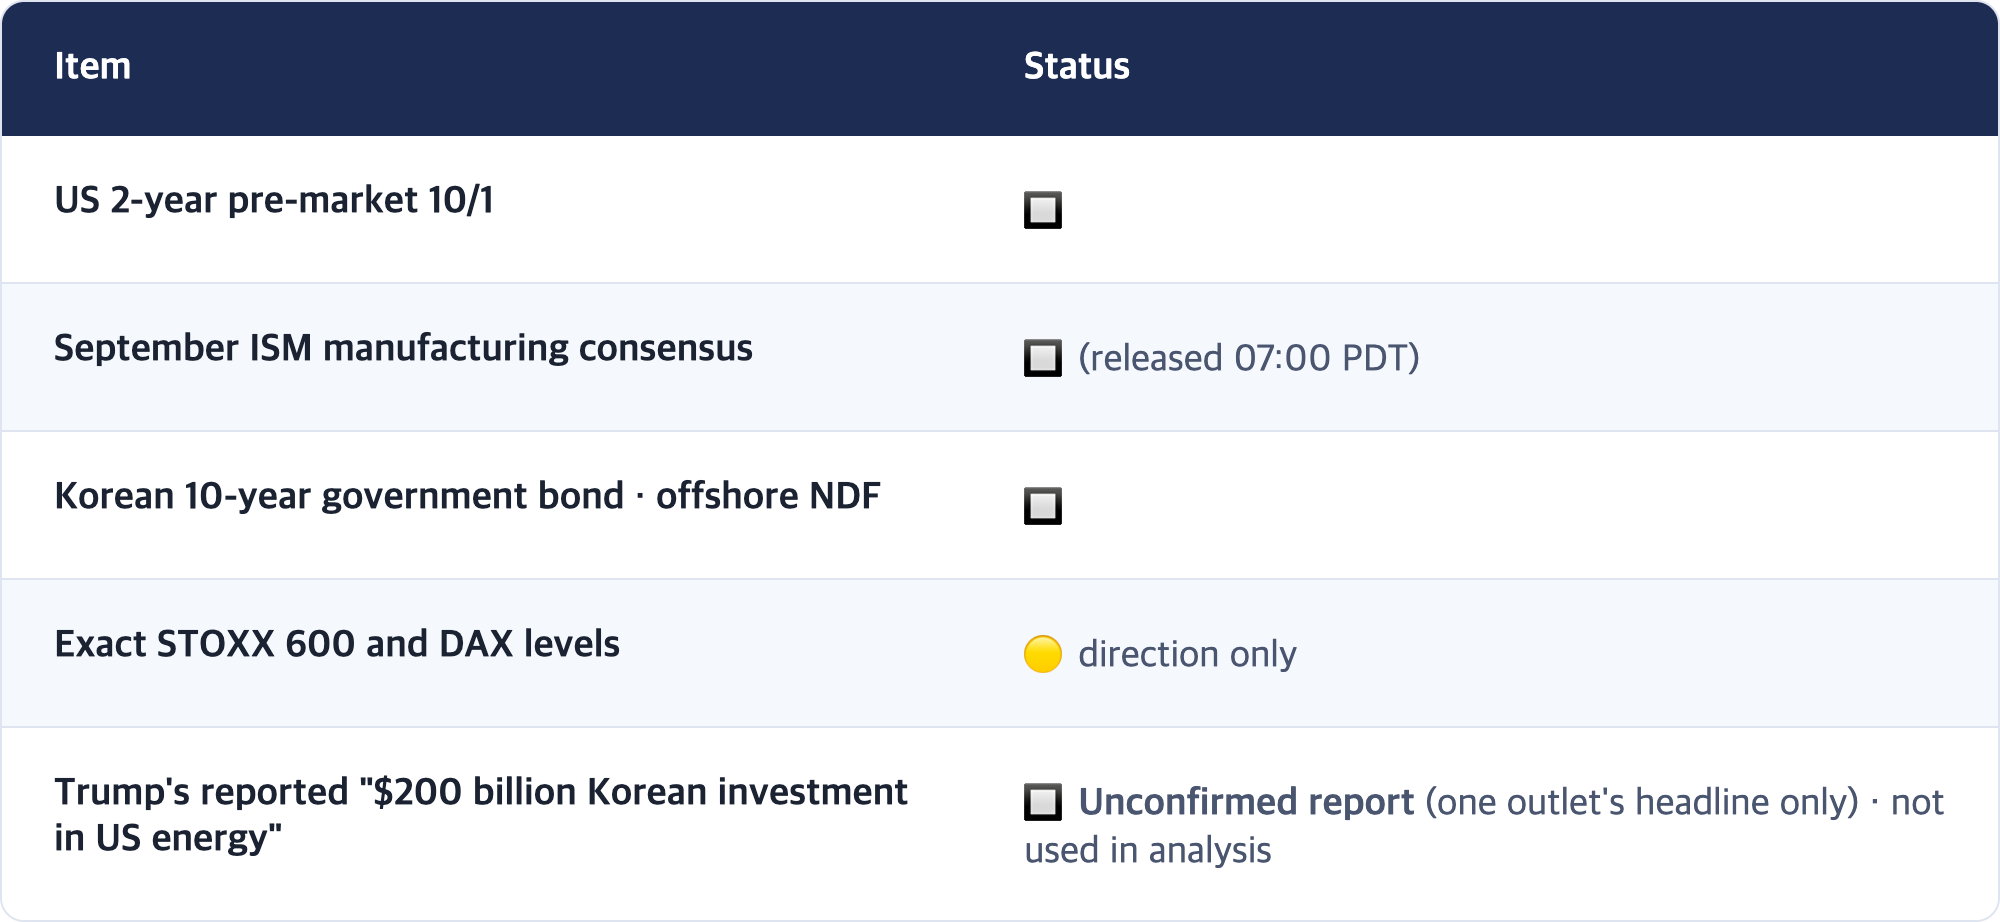
🔲 Not confirmed
8. Event Calendar (PDT)
Sources
- KOSPI rises 1.95% on Micron tailwind | Newspim
- KOSPI rebounds 1.95%, nears 7,000 | Financial News
- Micron tailwind sparks intraday reversal in KOSPI | Businesskorea
- September exports hit record $120.9bn; chips top $60bn | Financial News
- September exports up 83.5%; chips +262.8% | Money Today
- Nikkei Surges 2,203 Points as Micron Outlook Revives AI Trade | News On Japan
- investingLive Asia-Pacific market news: Yen weakens, Nikkei jumps | investingLive
- investingLive European session wrap: Dollar firms as Treasury yields threaten fresh 2002 highs | investingLive
- Dow Futures Hit Three-Month Low as Yields Surge, Micron Earnings Offer Support | U.S. News
- U.S. stock futures extend gains following strong Micron earnings | Investing.com
- Stock futures rise to kick off October as AI-related stocks gain | CNBC
- Oil prices rise as Chinese refiners reportedly ban October fuel exports; Brent back above $100 | CNBC
- United States Initial Jobless Claims | Trading Economics
- Euro Area Stock Market Index | Trading Economics
Market Analyst · This brief does not recommend buying or selling individual stocks. It provides macro context and interpretation.
📌 More market briefs
※ This post is market observation and organization intended to support your own judgment. It is not a recommendation to buy or sell any security. Figures are as of the time of writing and may differ between sources.
If this was useful, bookmark it or pass it along. It genuinely helps me write the next one.
I can survive. We can survive.