Oct 27, 2026 US Market Brief — Nasdaq and S&P 500 Before the Open
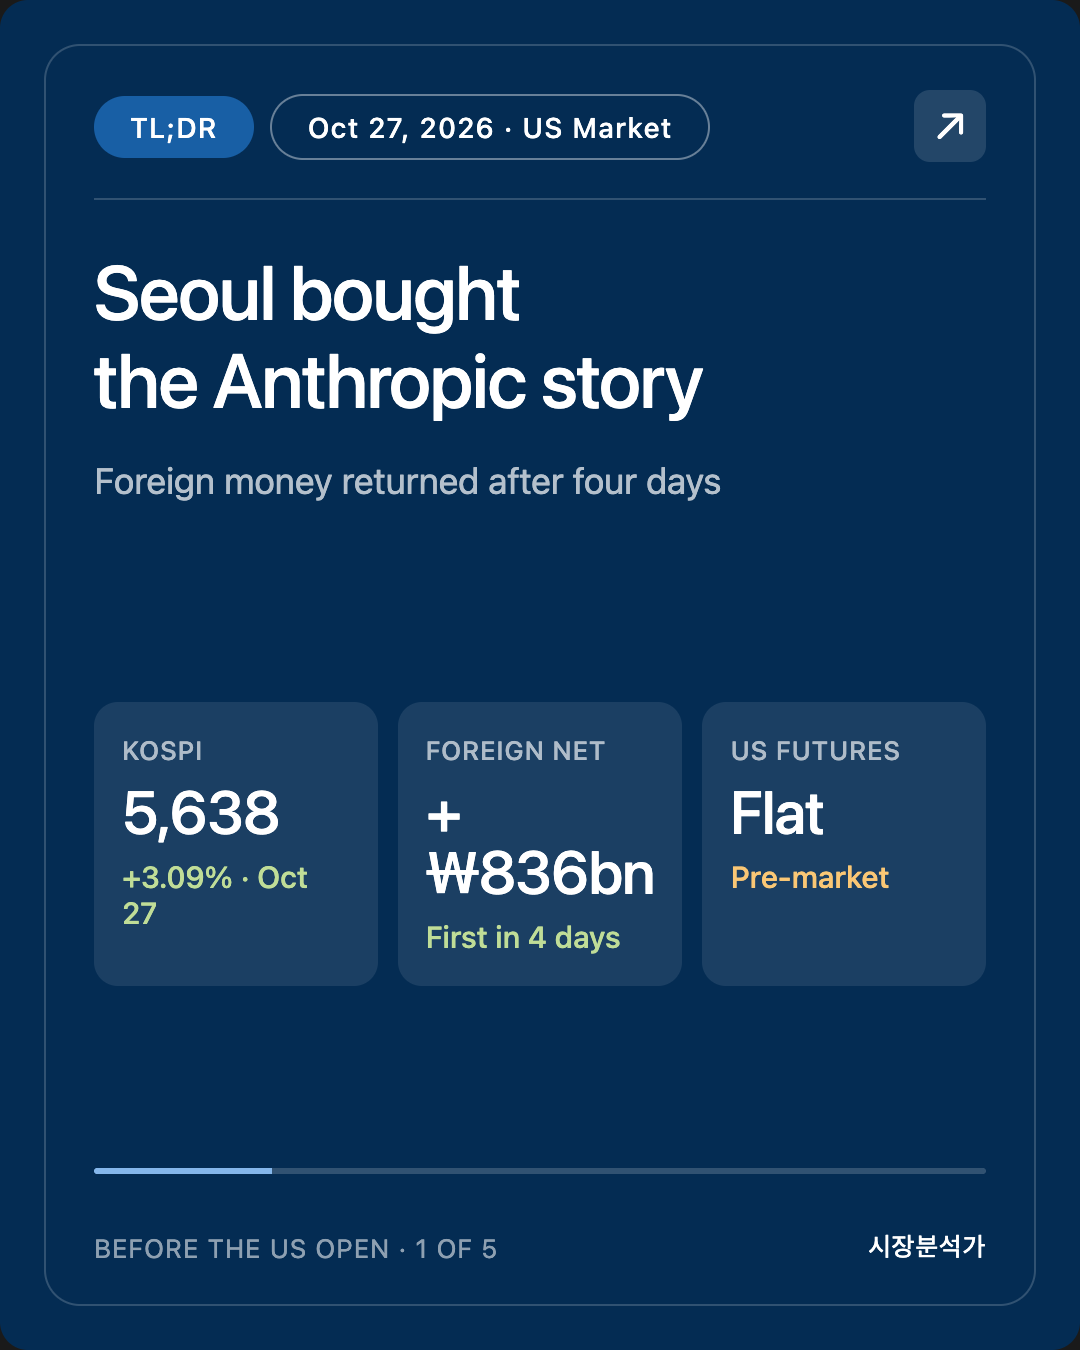
On Tuesday, Seoul bought the "answer in numbers" that Anthropic's IPO filing gave the AI trade. The KOSPI closed at 5,638.34 (+3.09%), and foreign investors turned net buyers for the first time in four sessions, buying about ₩836 billion (roughly $630 million). The index touched about 5,737 intraday, triggering a "sidecar" (a five-minute pause on program buying when futures jump 5%). It then gave back about 100 points, while retail investors sold ₩1.4 trillion.
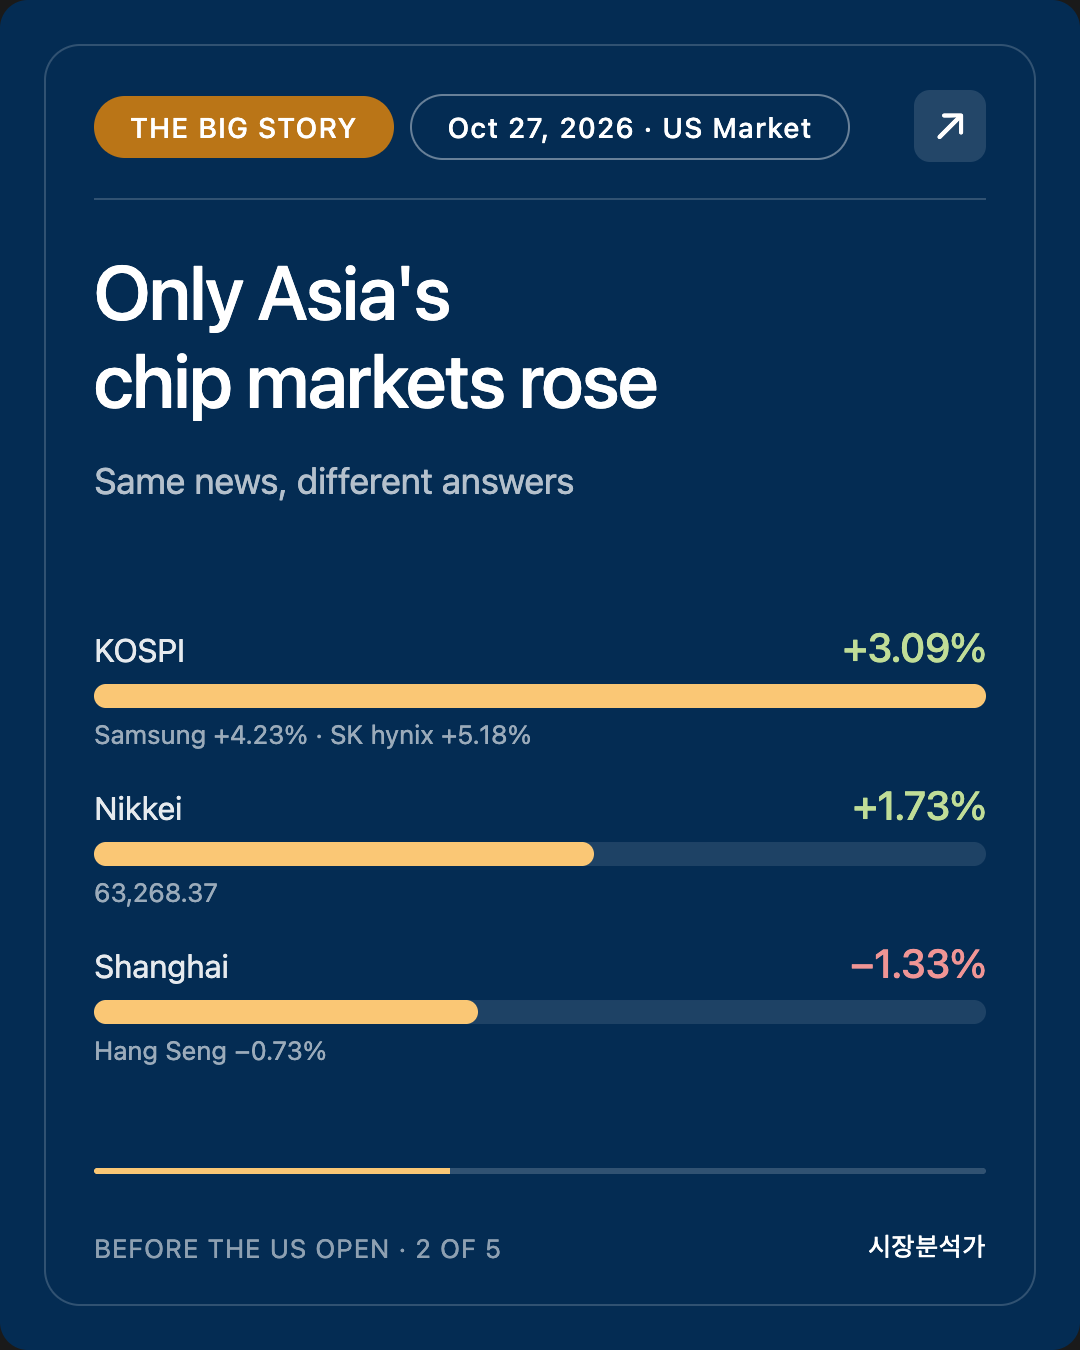
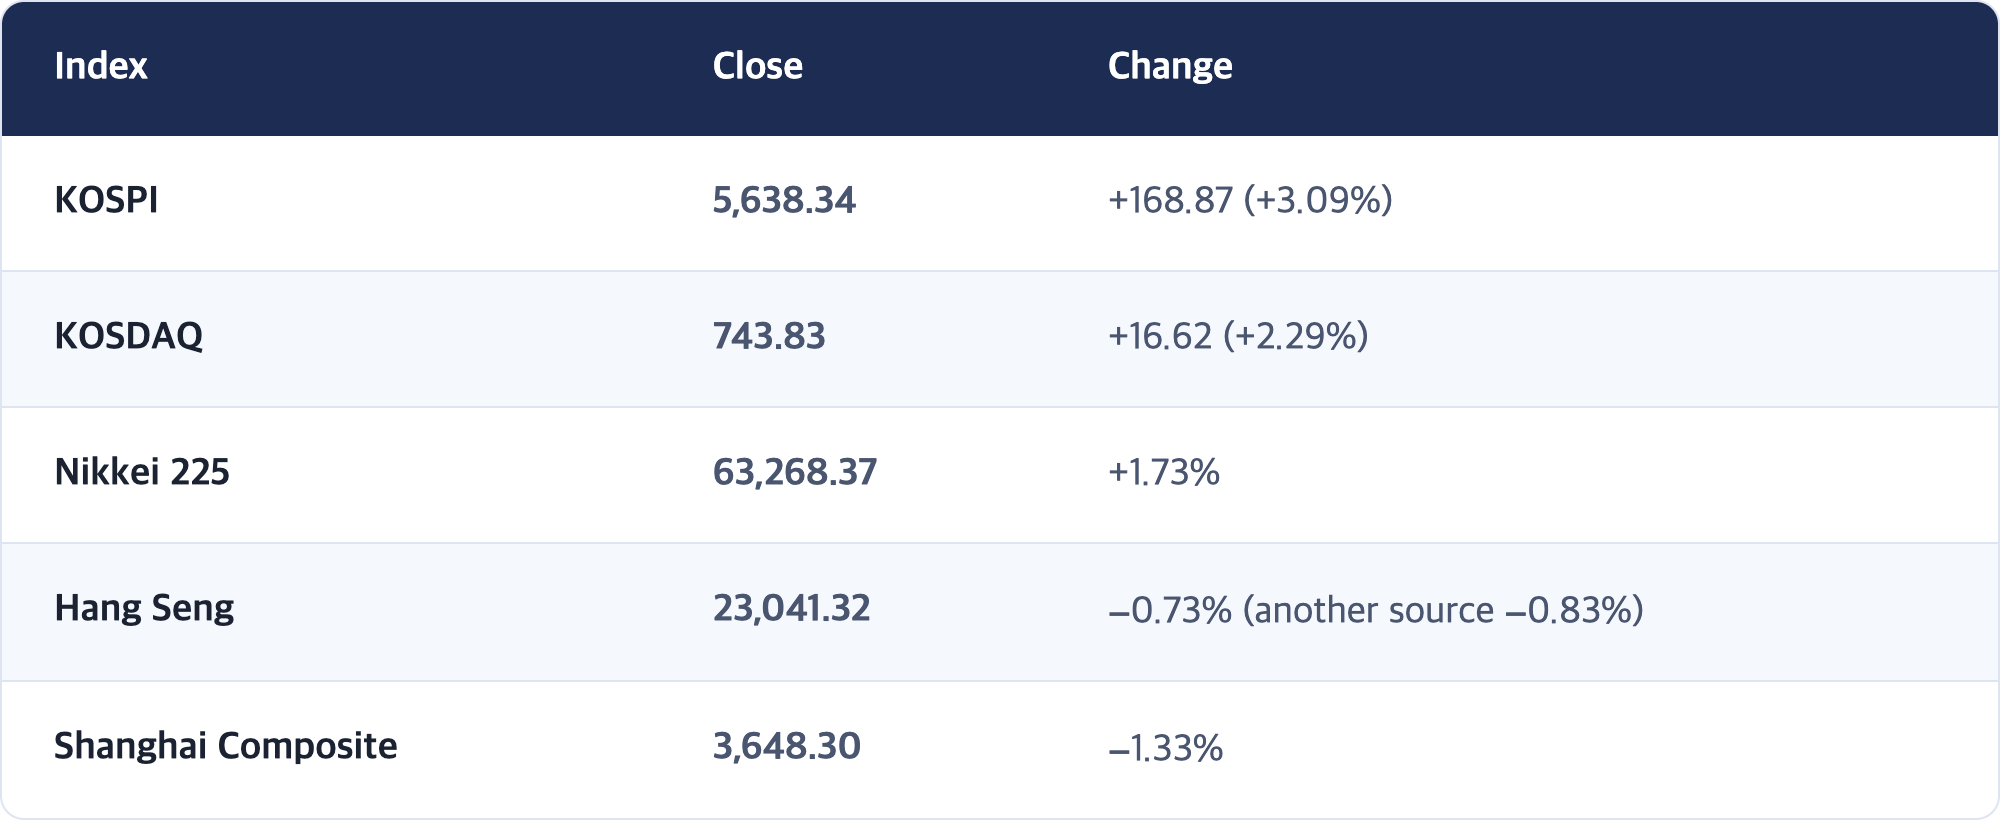
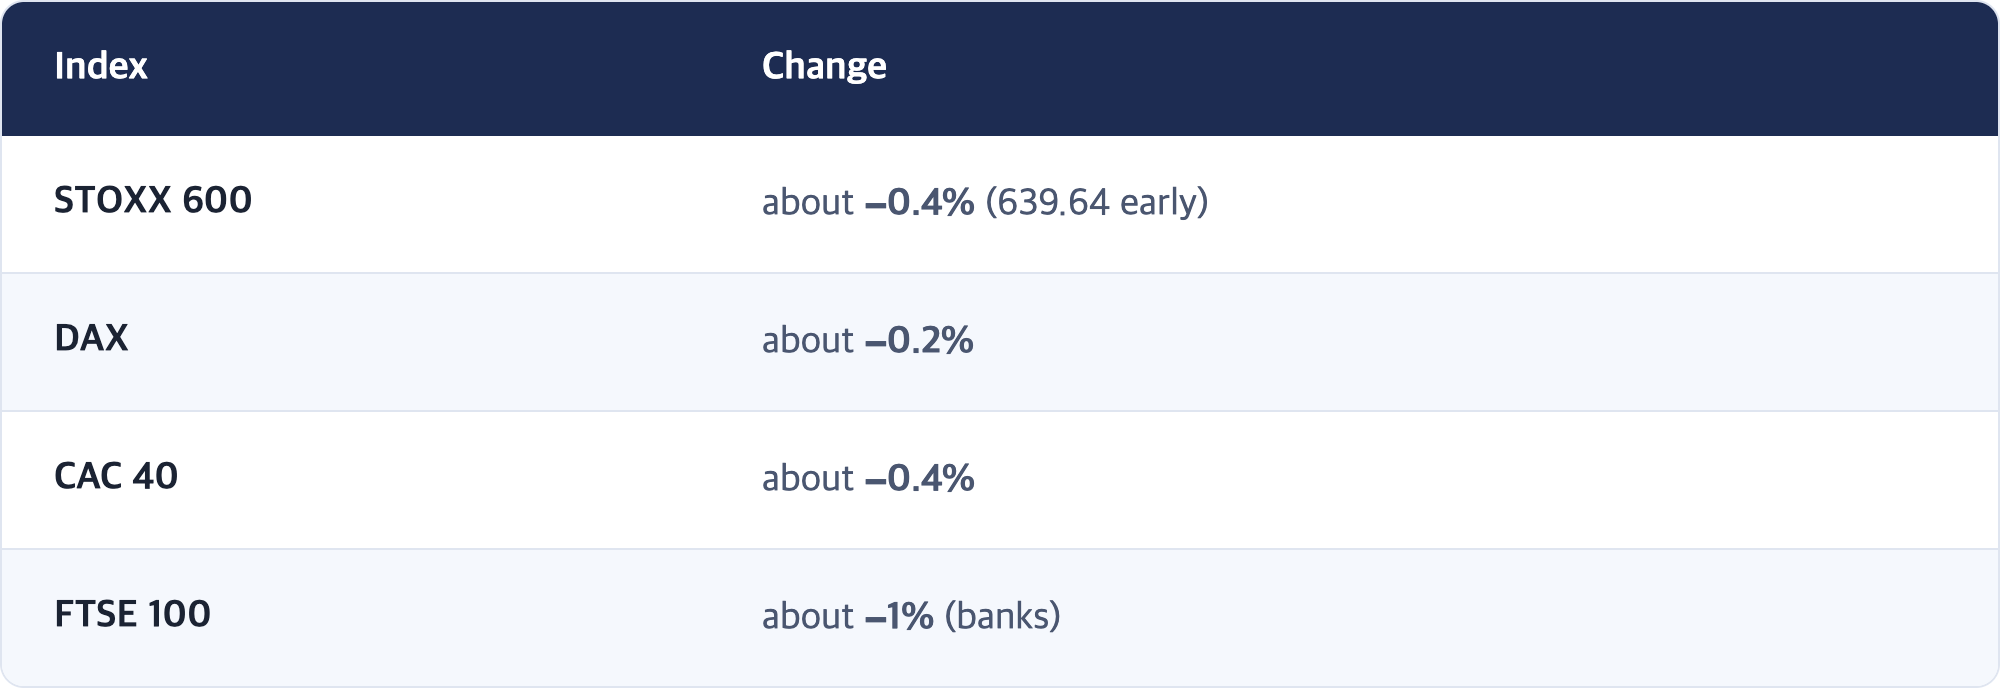
Asia split along chip lines. Japan's Nikkei rose 1.73% with Korea; Hong Kong's Hang Seng (−0.73%) and Shanghai (−1.33%) fell. In Europe, a disappointing HSBC quarter (about −7% pre-market) pulled the STOXX 600 down about 0.4%.
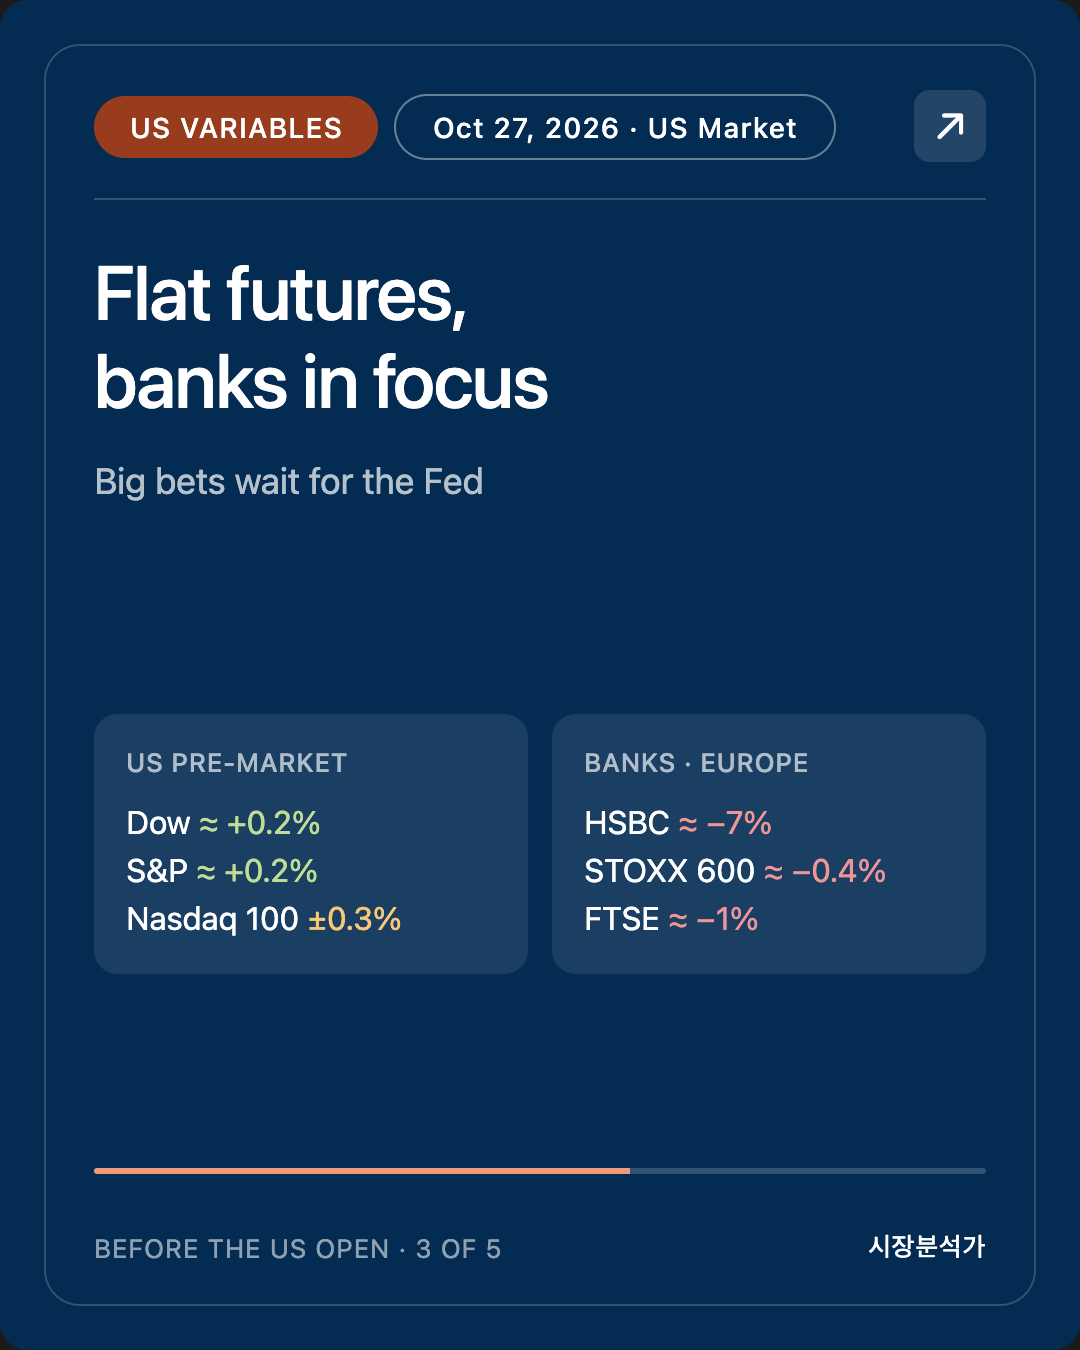
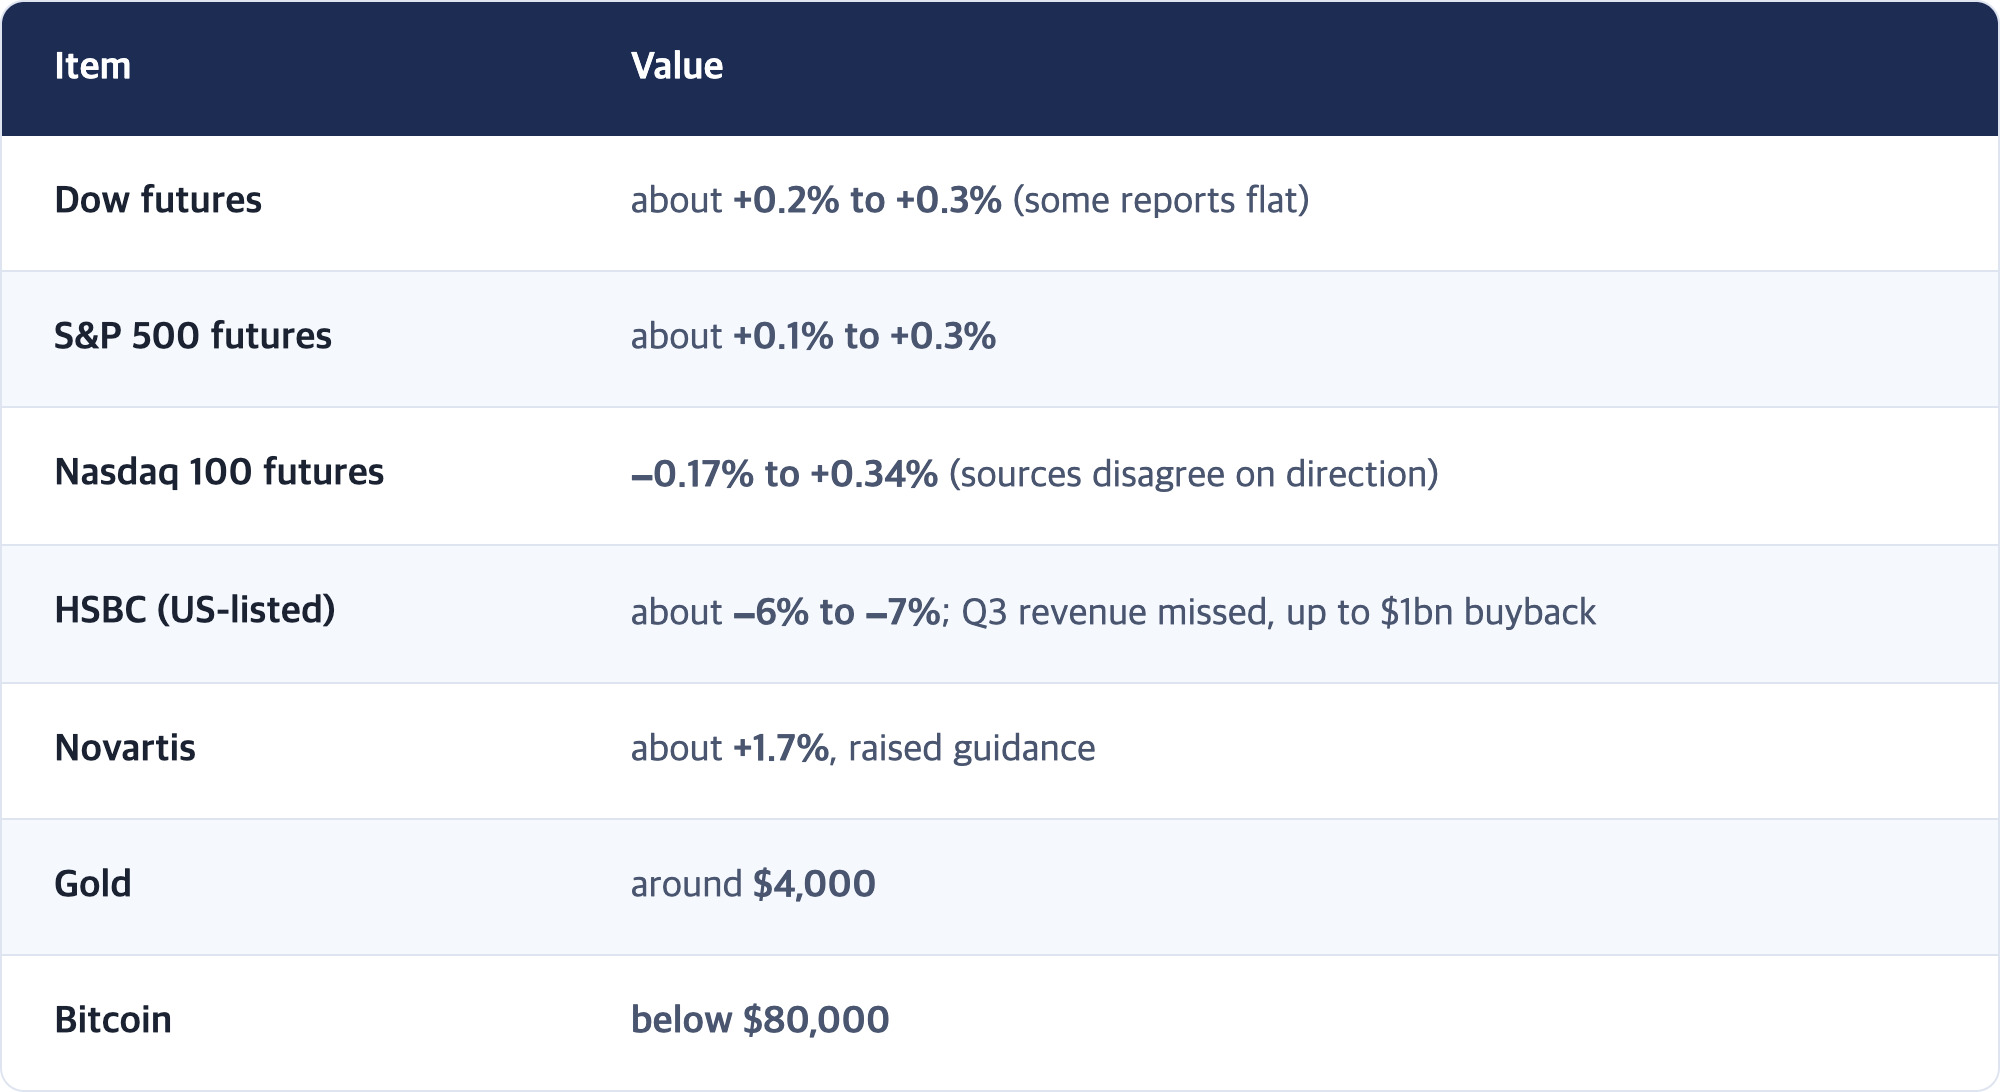
US futures are roughly flat as the Fed's two-day meeting begins, with a decision on Wednesday. Today's question for Wall Street: can the chip rally Anthropic lit on Monday hold for another day ahead of the Fed?
This is Mr. Can. Here is the Oct 27, 2026 brief ahead of the US market open.
Written: 2026-10-27 07:40 PDT (Seoul 10/27 23:40 KST) · Work started 05:37 PDT
Basis: Korea, Japan, Hong Kong and China closes on 10/27 + European trading + US pre-market + overnight Treasuries
🔴 Scheduled for 05:30 PDT; data gathering and card rendering ran late, so this goes out after the US open (06:30 PDT). US figures are pre-market; post-open prices are not included.
🔴 Missed edition: 10/26 AM. The previous edition was 10/26 PM (Korea open preview, published late).
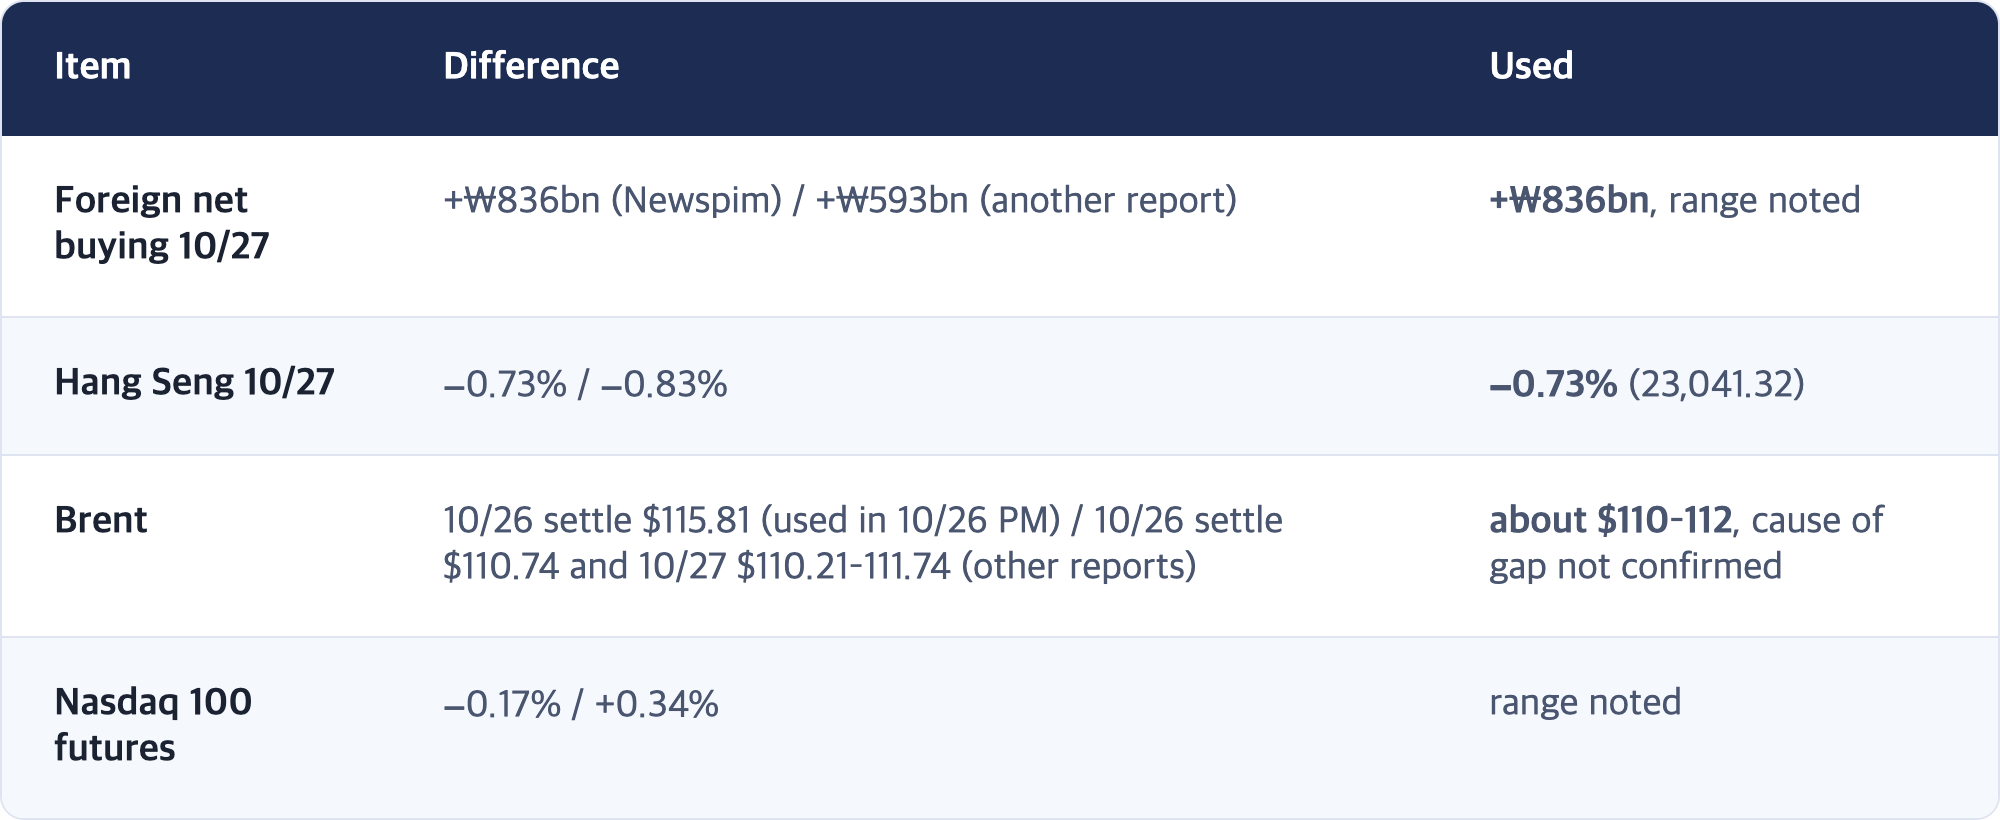
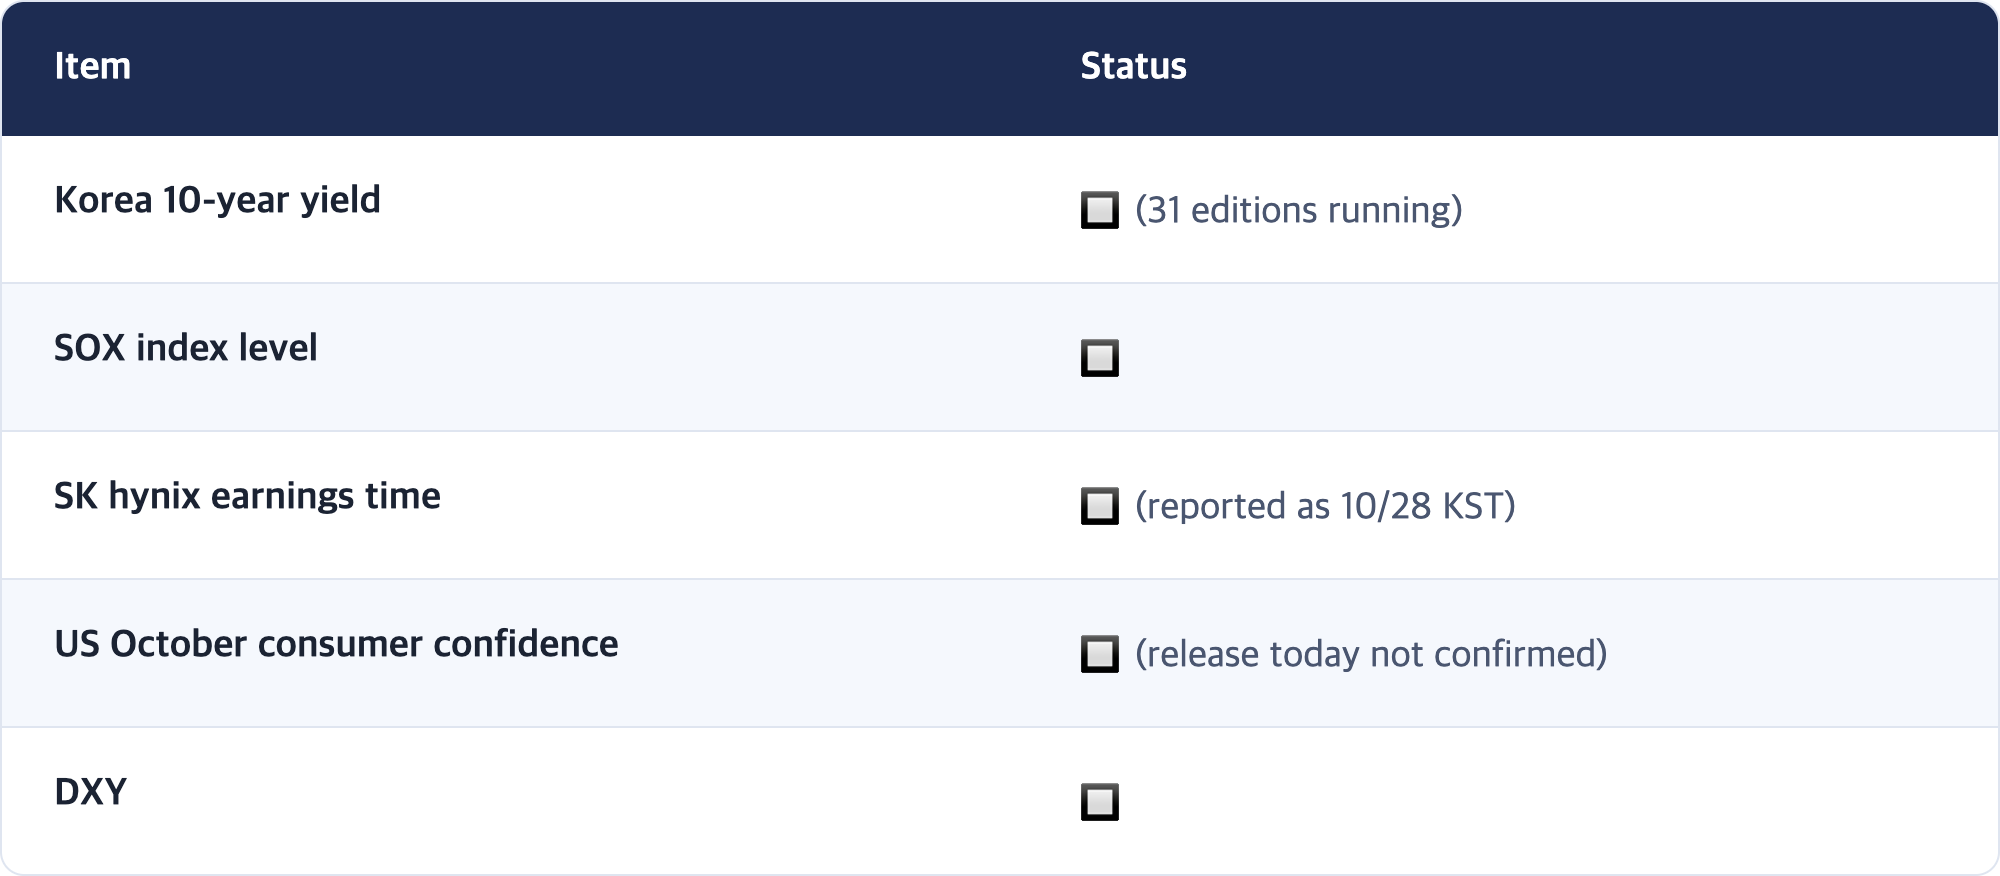
🟡 Sources disagree on foreign net buying in Seoul and on the Brent price (see section 6). Korean 10-year government bond yields were again unavailable.
⚡ TL;DR
- ★ Seoul believed the Anthropic numbers. KOSPI 5,638.34 (+3.09%), intraday about 5,737, buy sidecar at 10:13. Samsung Electronics +4.23%, SK hynix +5.18%. KOSDAQ 743.83 (+2.29%).
- ★ Foreign money came back. Foreigners +₩836bn (another tally: +₩593bn), institutions +₩419bn, retail −₩1.40tn. First joint cash-and-futures buying in four sessions. Won at 1,323.7 per dollar.
- Asia split on chips. Nikkei 63,268.37 (+1.73%) vs. Hang Seng 23,041.32 (−0.73%) and Shanghai 3,648.30 (−1.33%).
- US futures flat, European banks heavy. US futures roughly −0.2% to +0.3% depending on source and time. HSBC about −7% pre-market; STOXX 600 about −0.4%, FTSE 100 about −1%.
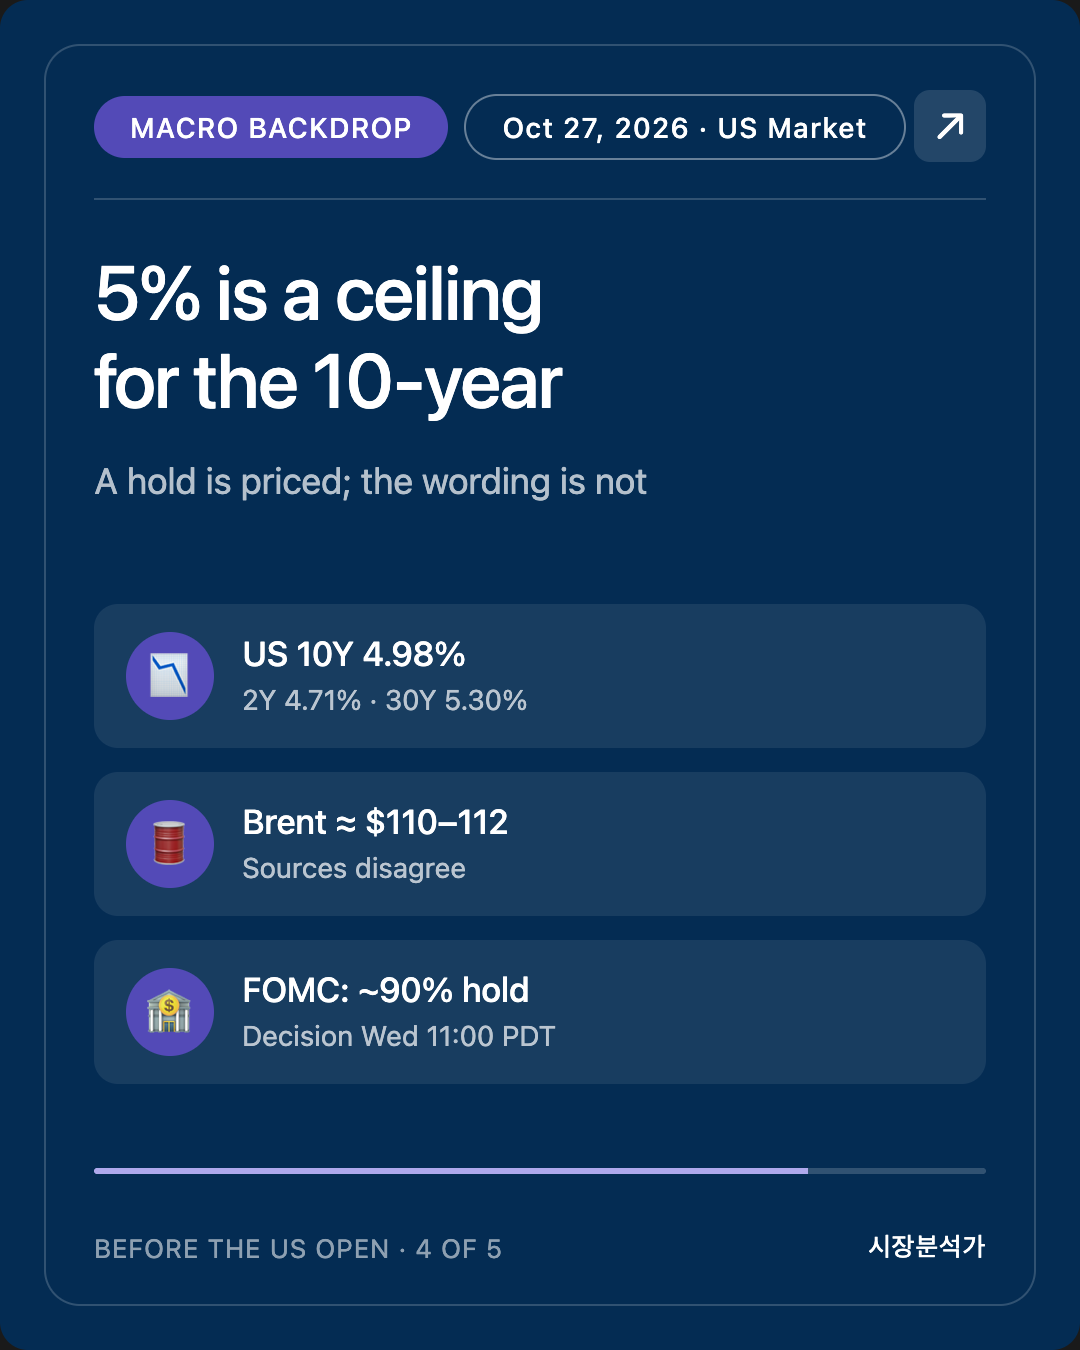
- Rates and oil paused. US 10-year 4.98%, 2-year 4.71%, 30-year 5.30%. Brent about $110–112. CME puts a hold at about 90%; decision Wednesday 10/28.
1. Scoring yesterday's checkpoints
The four set in the 10/26 PM edition (Seoul close, 10/27)
The axis was "Will foreign investors trust Anthropic's numbers and return, or is this just locals trading among themselves?" The open slot for a third variable was whether the US 10-year broke 5%.
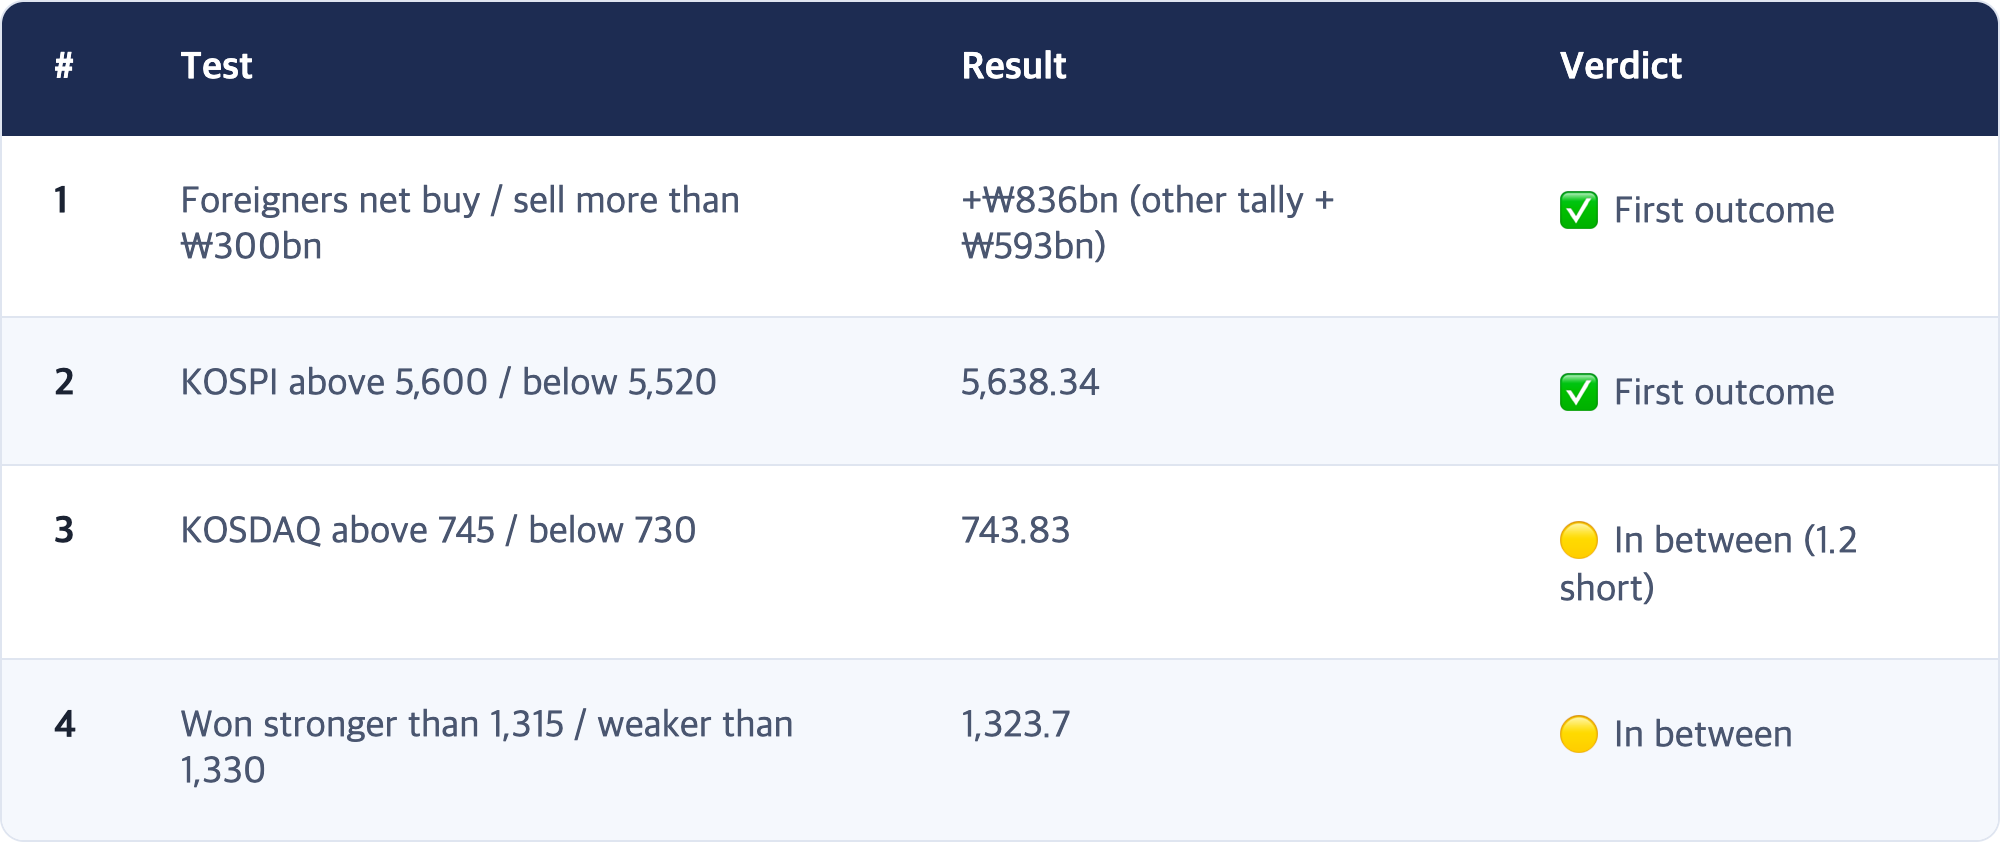
Third variable: the US 10-year stayed at 4.98%, below 5%. Nothing outside the axis changed the picture this time.
★ [Interpretation] Foreigners came back; retail used the bounce to leave
Checks 1 and 2 both landed on the first outcome. By the 10/26 PM framing, this is the first day Seoul shifted weight from "AI doubt" to "AI numbers." Foreigners bought both cash shares and futures for the first time in four sessions.
Two caveats. The index gave back about 100 points from its intraday high, so the heat faded in the afternoon. And retail investors, who held on through a 20%-plus slide this month, sold ₩1.4 trillion into the bounce. Whether foreign buying lasts a second day matters more than the size of today's gain.
2. The big story: only the Asian markets with chips went up
[Fact] Asia closes, Tuesday 10/27
[Fact] Seoul flows and large caps (main board, Newspim)
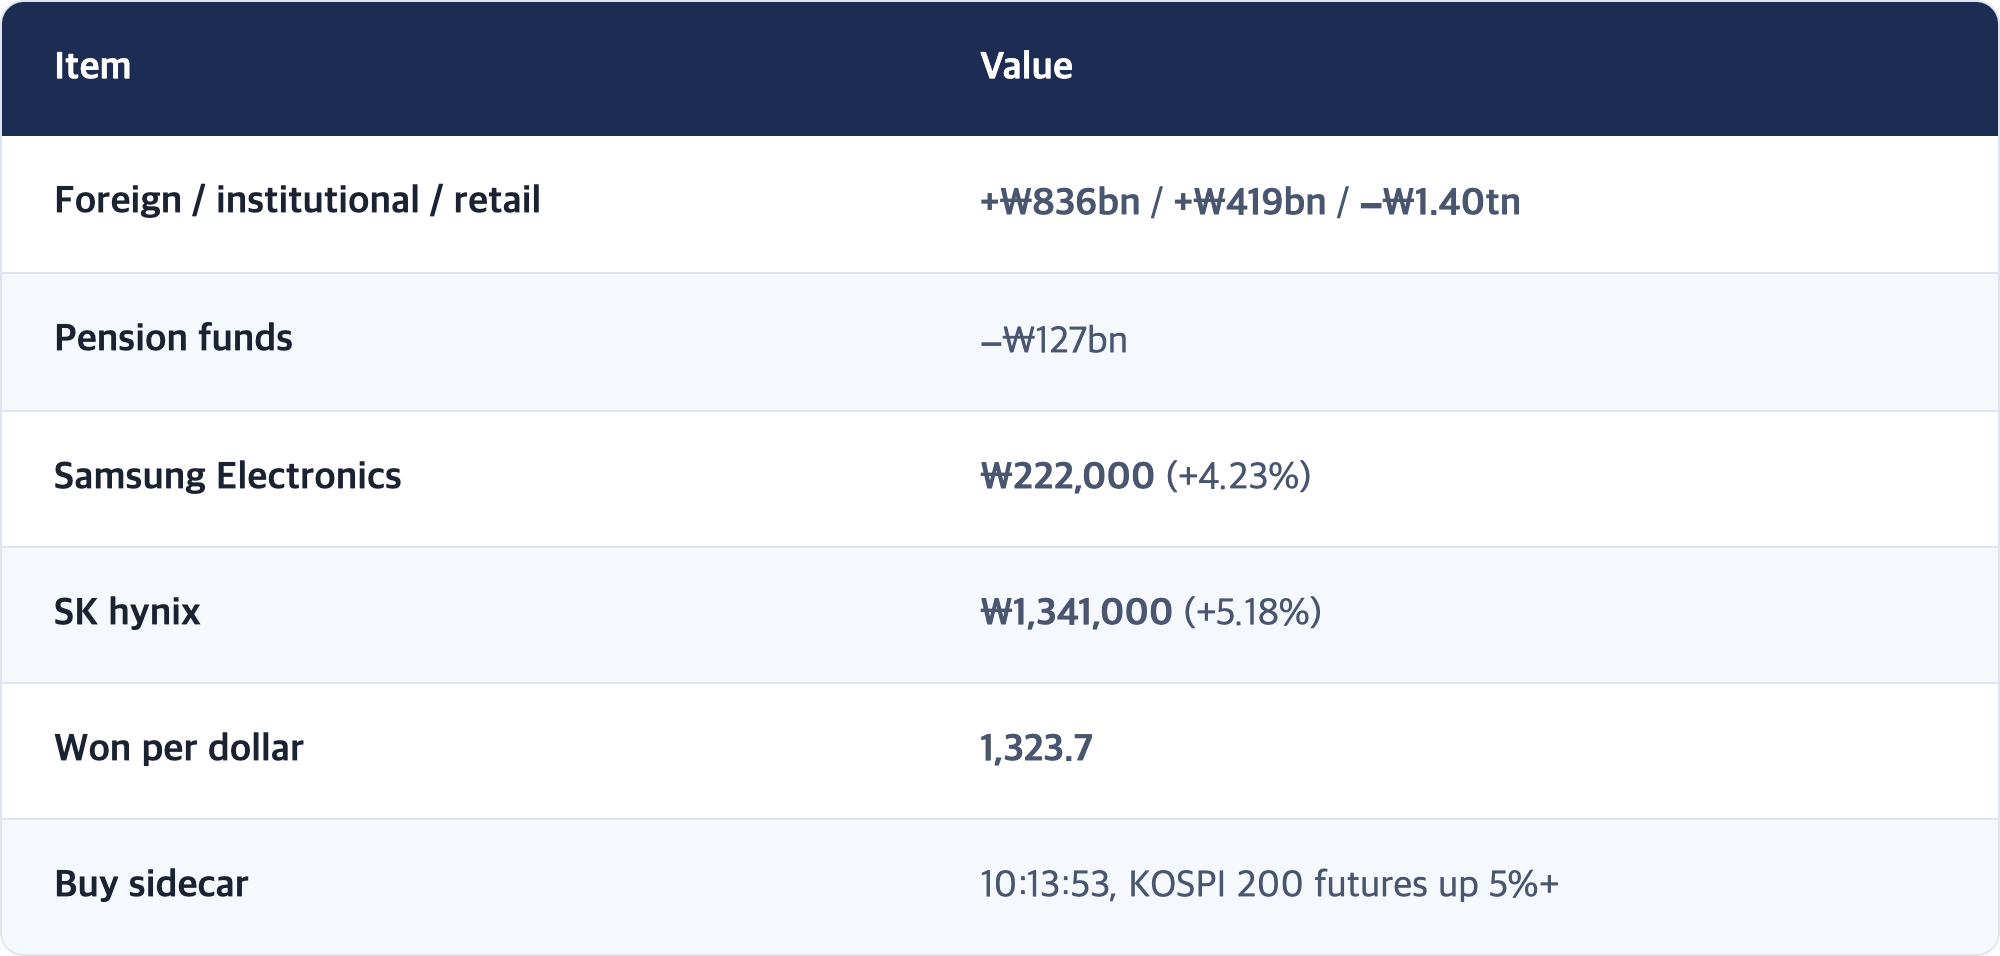
[Fact] A Daishin Securities analyst, citing Anthropic's S-1, noted revenue per dollar of compute rose to $2.10 in Q2 and operating profit turned positive at $970 million (quoted by Newspim).
★ [Interpretation] Same news, different answers
- The Anthropic filing was good news mainly for those who sell AI chips. Seoul (memory) and Tokyo (equipment and materials) rose; Hong Kong and Shanghai, with little chip weight, fell. Markets priced "the money flows to chips" more than "AI makes money."
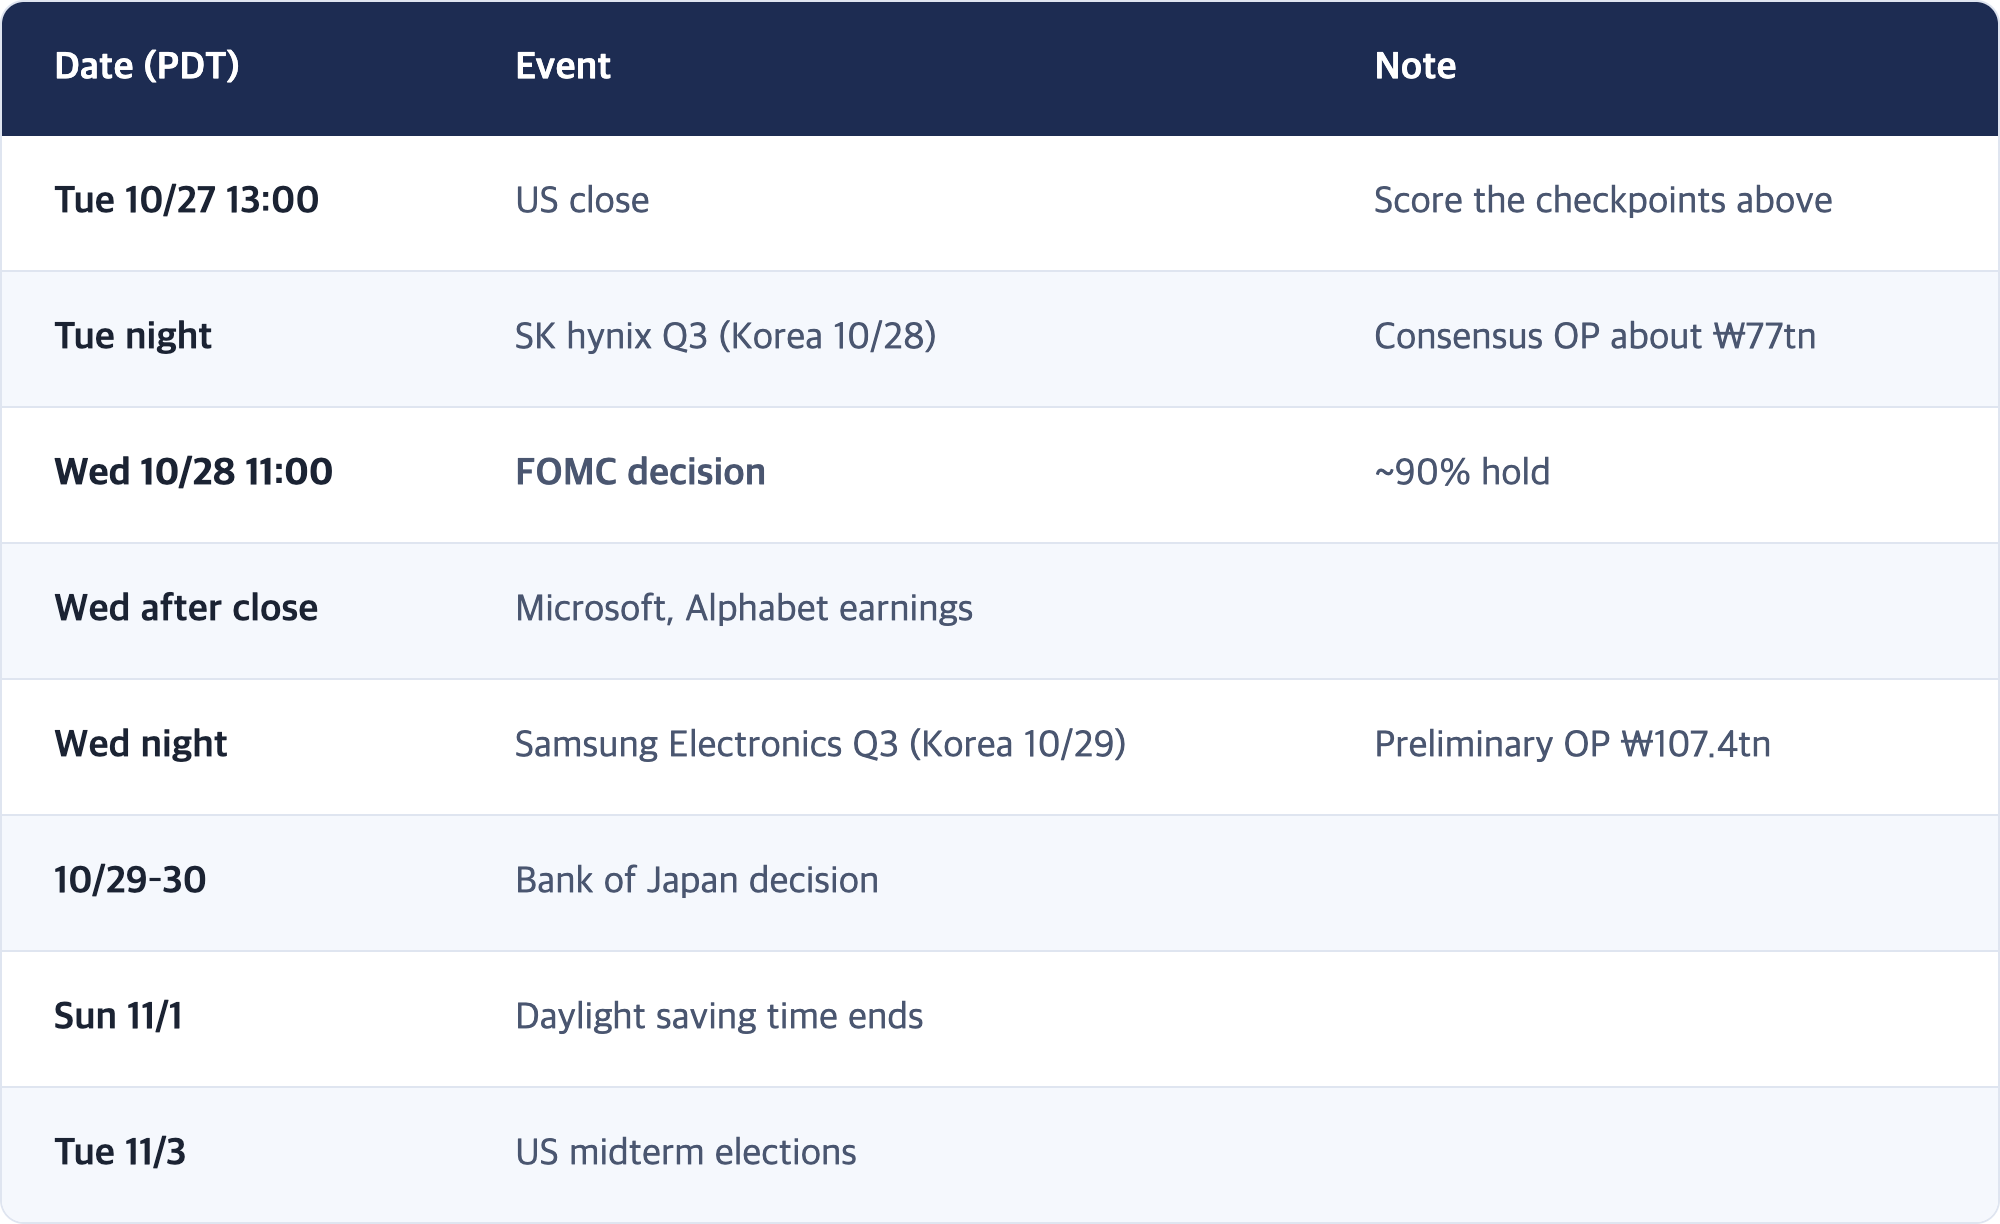
- Seoul's afternoon fade looks like waiting for SK hynix earnings. Consensus operating profit is about ₩77 trillion (₩77–78tn by source). Expectations rose with the stock.
- New York already priced this on Monday (SOX +2.82%). Today's question is not the news but how much positioning holds before the Fed.
3. US variables: flat futures, banks as the new variable
[Fact] US pre-market, 10/27 (varies by source and time)
[Fact] Europe, 10/27 intraday
★ [Interpretation] Today's new variable is banks
Until yesterday, AI and oil drove New York. This morning, HSBC and energy-inflation worries are weighing on Europe. US banks could actually benefit from a "hawkish hold," so it is unclear whether the HSBC hit spreads across the Atlantic. Flat futures suggest the market is holding off on big bets until Wednesday afternoon's decision.
4. Macro backdrop: yields under 5%, a hold expected
[Fact]
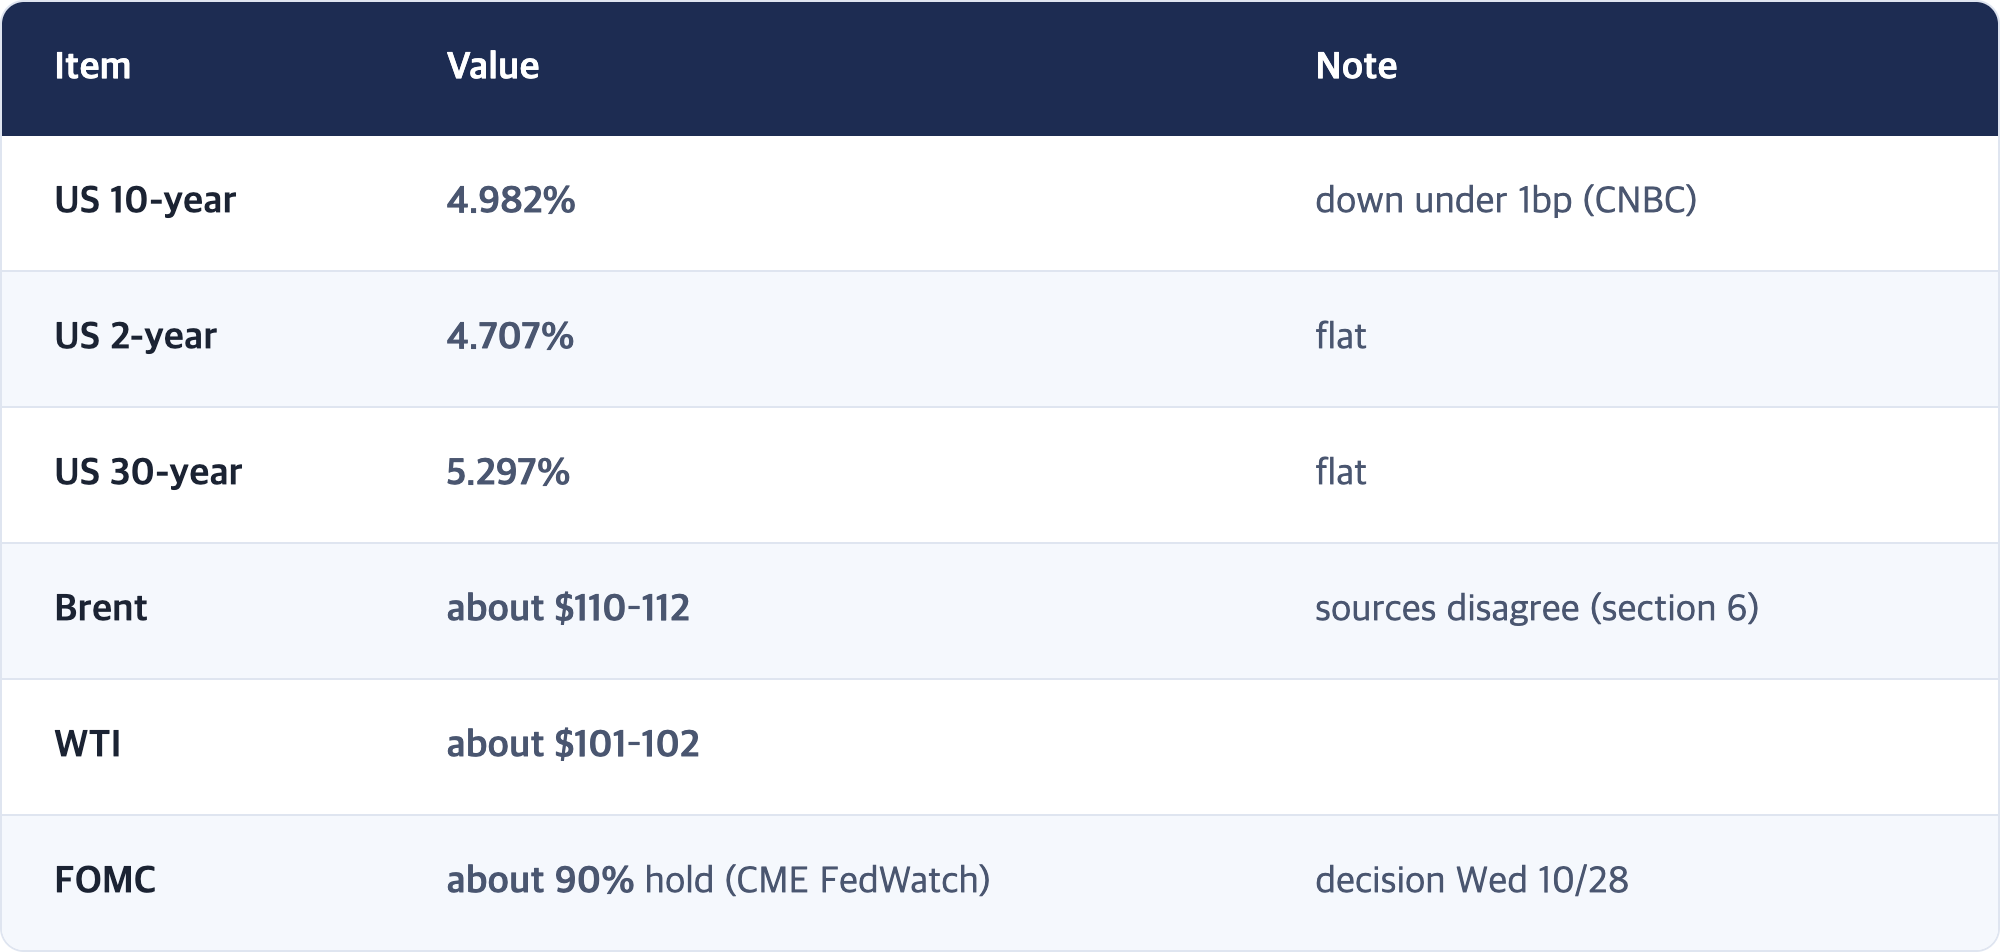
★ [Interpretation] 5% is acting like a ceiling on the 10-year
The third variable we left open (a 10-year break above 5%) did not arrive. The 10-year has sat just under 5% for more than a week. With a hold nearly certain, the market is watching Chair Warsh's wording. If he keeps the door open to another hike, the 10-year may test 5% again, and the chips that rallied Monday and Tuesday would likely feel it first.
5. Today's US session: checkpoints
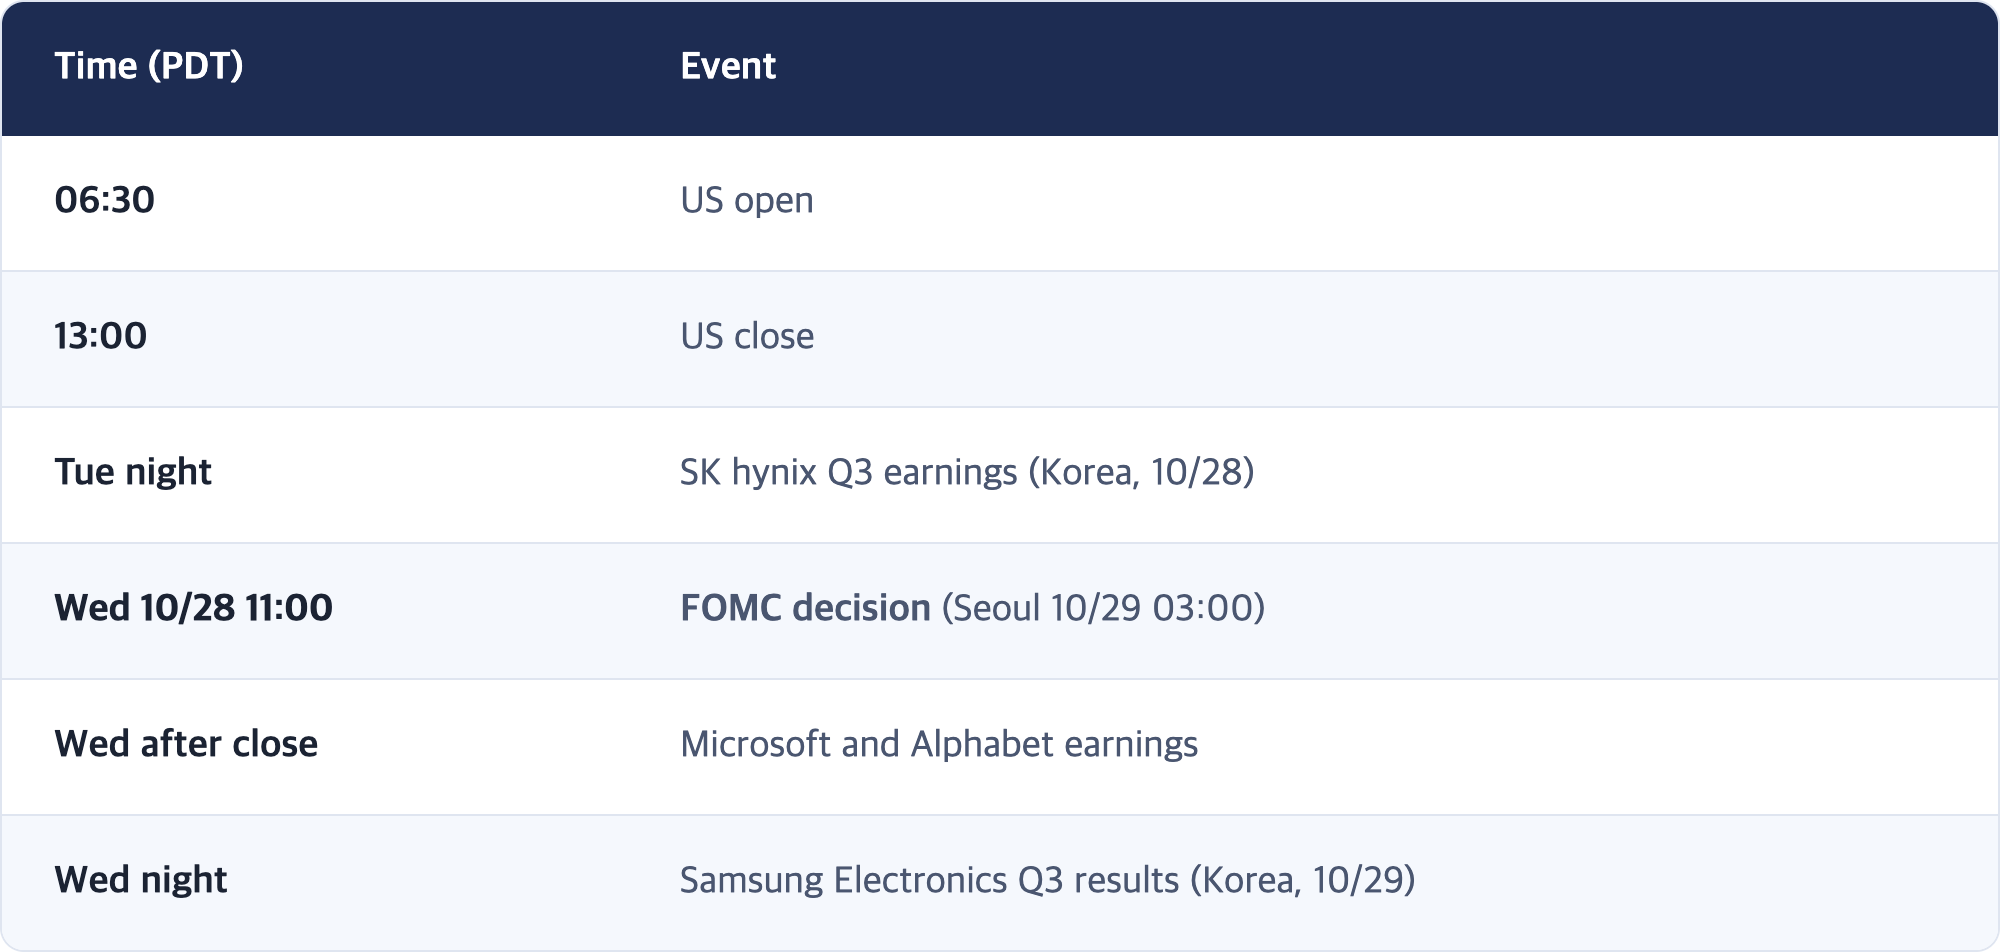
[Observation] Schedule (PDT)
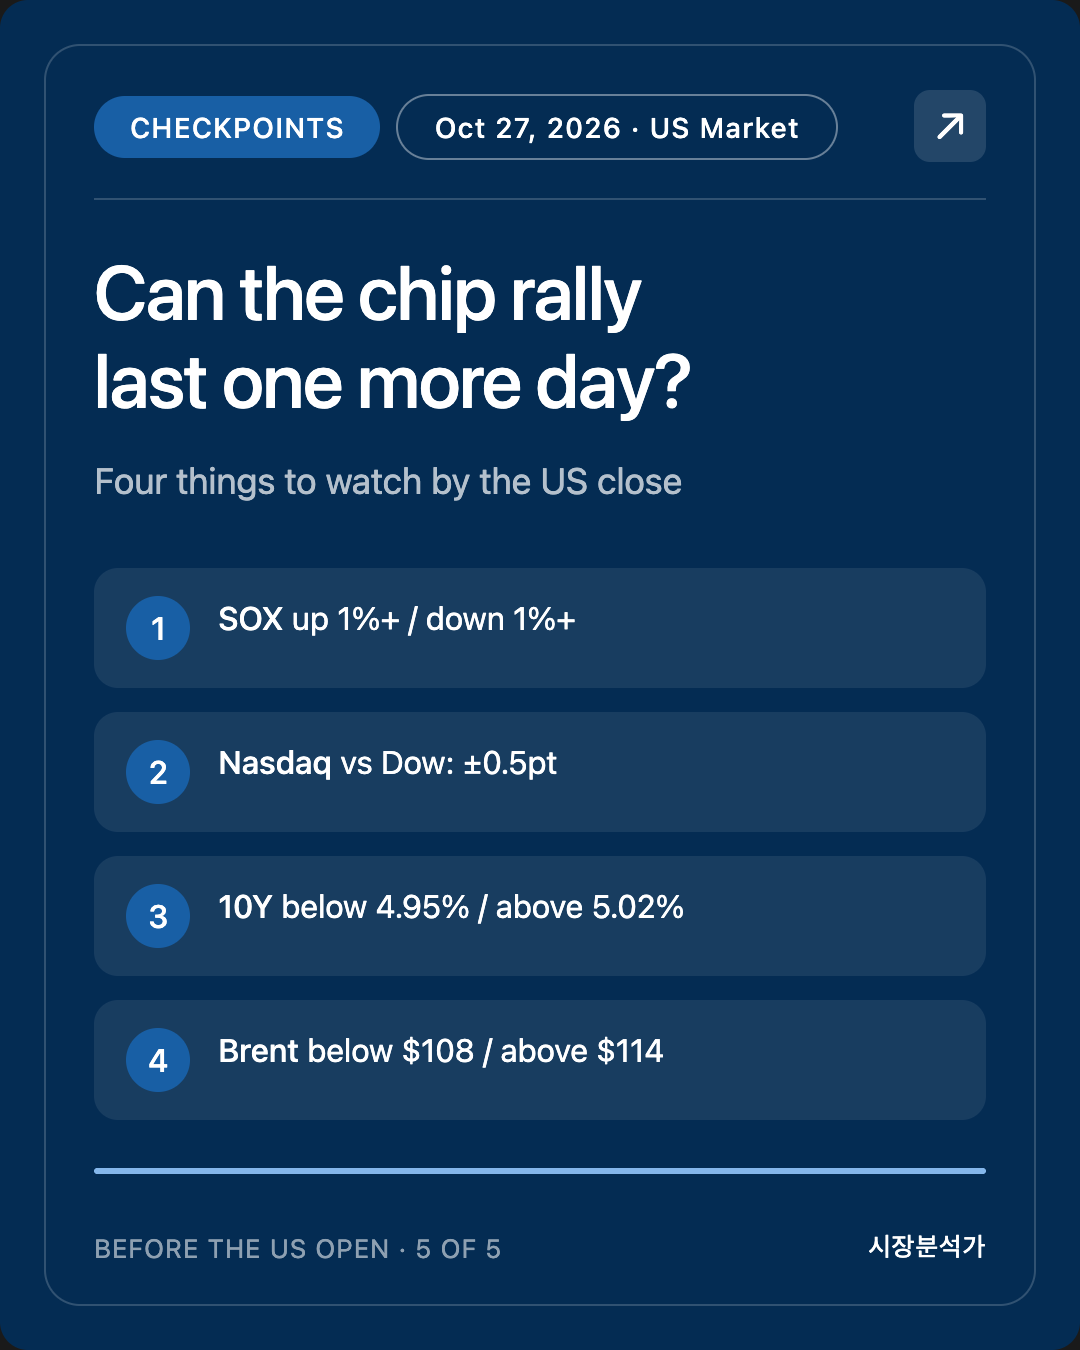
✅ Four checkpoints (by today's US close)
The axis: does Monday's Anthropic-driven chip rally hold one more day ahead of the Fed, or cool on profit-taking? The open slot for a third variable is whether HSBC-led bank weakness spreads.
- SOX up more than 1% / down more than 1%. (Most important) It rose 2.82% Monday.
- Nasdaq beats the Dow by 0.5 points+ / trails by 0.5+.
- US 10-year below 4.95% / above 5.02%. Now 4.98%.
- Brent below $108 / above $114.
[Interpretation] If 1 and 2 land on the first outcome, the "AI numbers" story held a second day, and Seoul can treat SK hynix's results as a confirmation. If check 1 lands on the second, Seoul's afternoon fade carried into New York, and Seoul will be more sensitive to flows than to the earnings themselves.
6. Corrections and open items
Corrections
- None.
Source differences (value used in this report)
🔲 Not confirmed
7. Event calendar (PDT)
Sources
- Foreign net buying lifts KOSPI 3% | Newspim (Korean)
- Foreigners net buy nearly ₩1tn | Newspim (Korean)
- KOSPI closes up 3% after sidecar | Korea Economic Daily (Korean)
- Sidecar triggered but 5,700 not held | Digital Daily (Korean)
- US Futures and Asian Stocks Advance Following a Rally on Wall Street | US News (AP)
- Hang Seng Closes Down 0.83% as Shanghai Drops 1.3% | 24/7 Wall St.
- European shares fall as HSBC slump and energy fears offset AI glow | Investing.com
- Europe shares fall as HSBC weighs | Business Recorder
- U.S. Treasury yields are flat ahead of the Fed meeting | CNBC
- Futures Trade Mixed as Fed Begins Its Two-Day Meet | Benzinga
- US Pre-Market: Gold Around $4,000, Bitcoin Below $80,000 | TradingKey
Market Analyst · No buy or sell recommendations on individual stocks. This report covers macro trends and interpretation.
📌 More market briefs
※ This post is market observation and organization intended to support your own judgment. It is not a recommendation to buy or sell any security. Figures are as of the time of writing and may differ between sources.
If this was useful, bookmark it or pass it along. It genuinely helps me write the next one.
I can survive. We can survive.