October 23, 2026 US Market Brief — Nasdaq and S&P 500 Before the Open
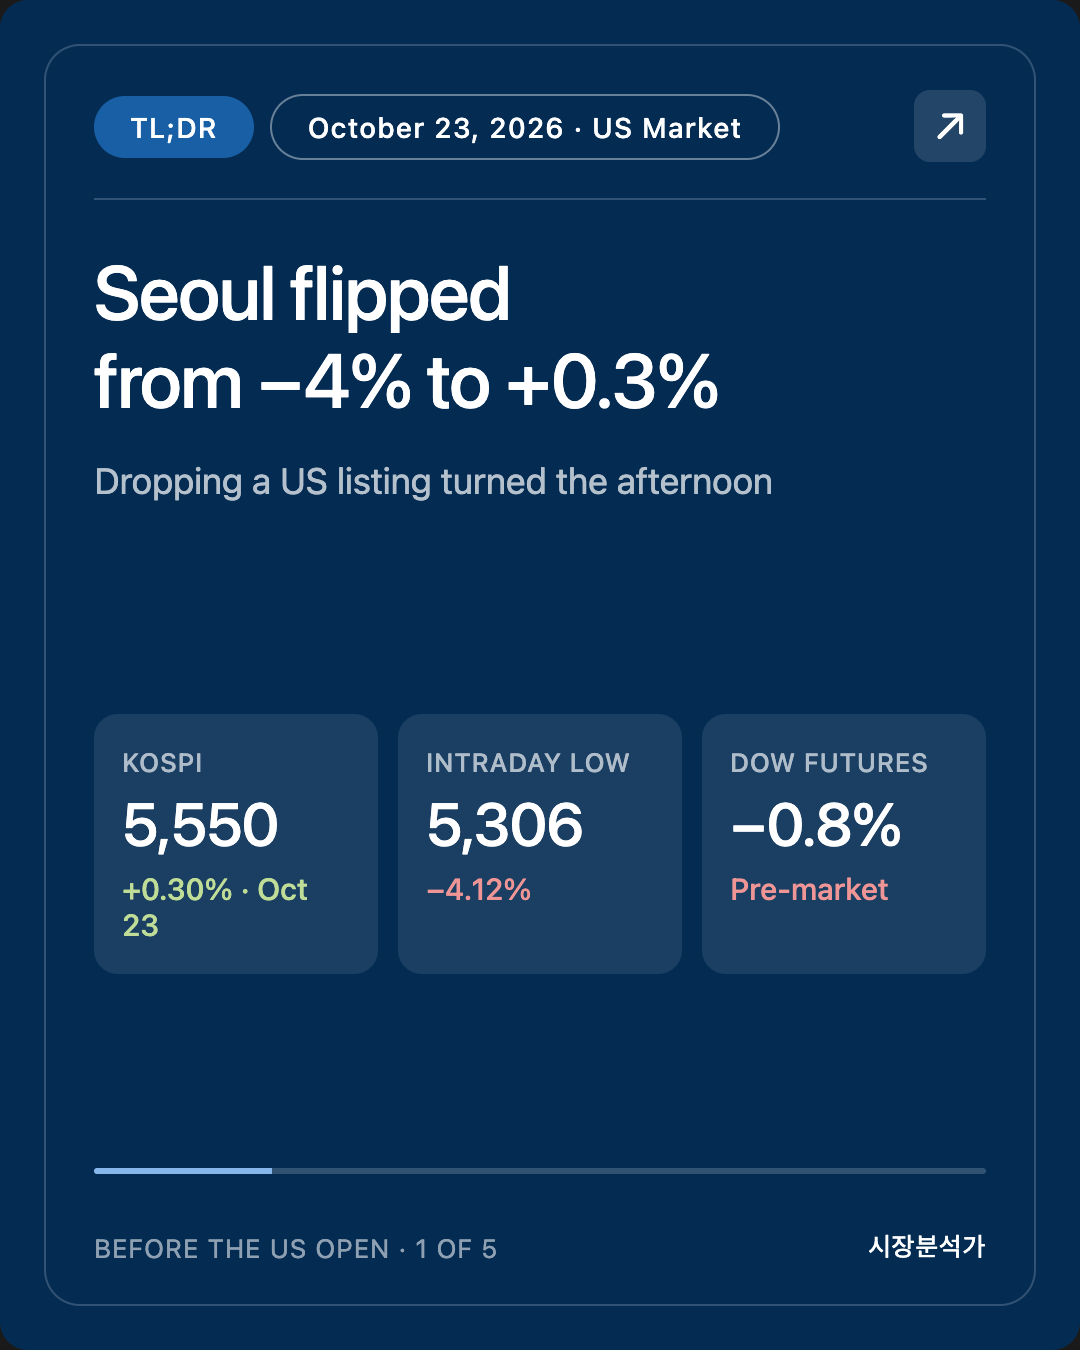
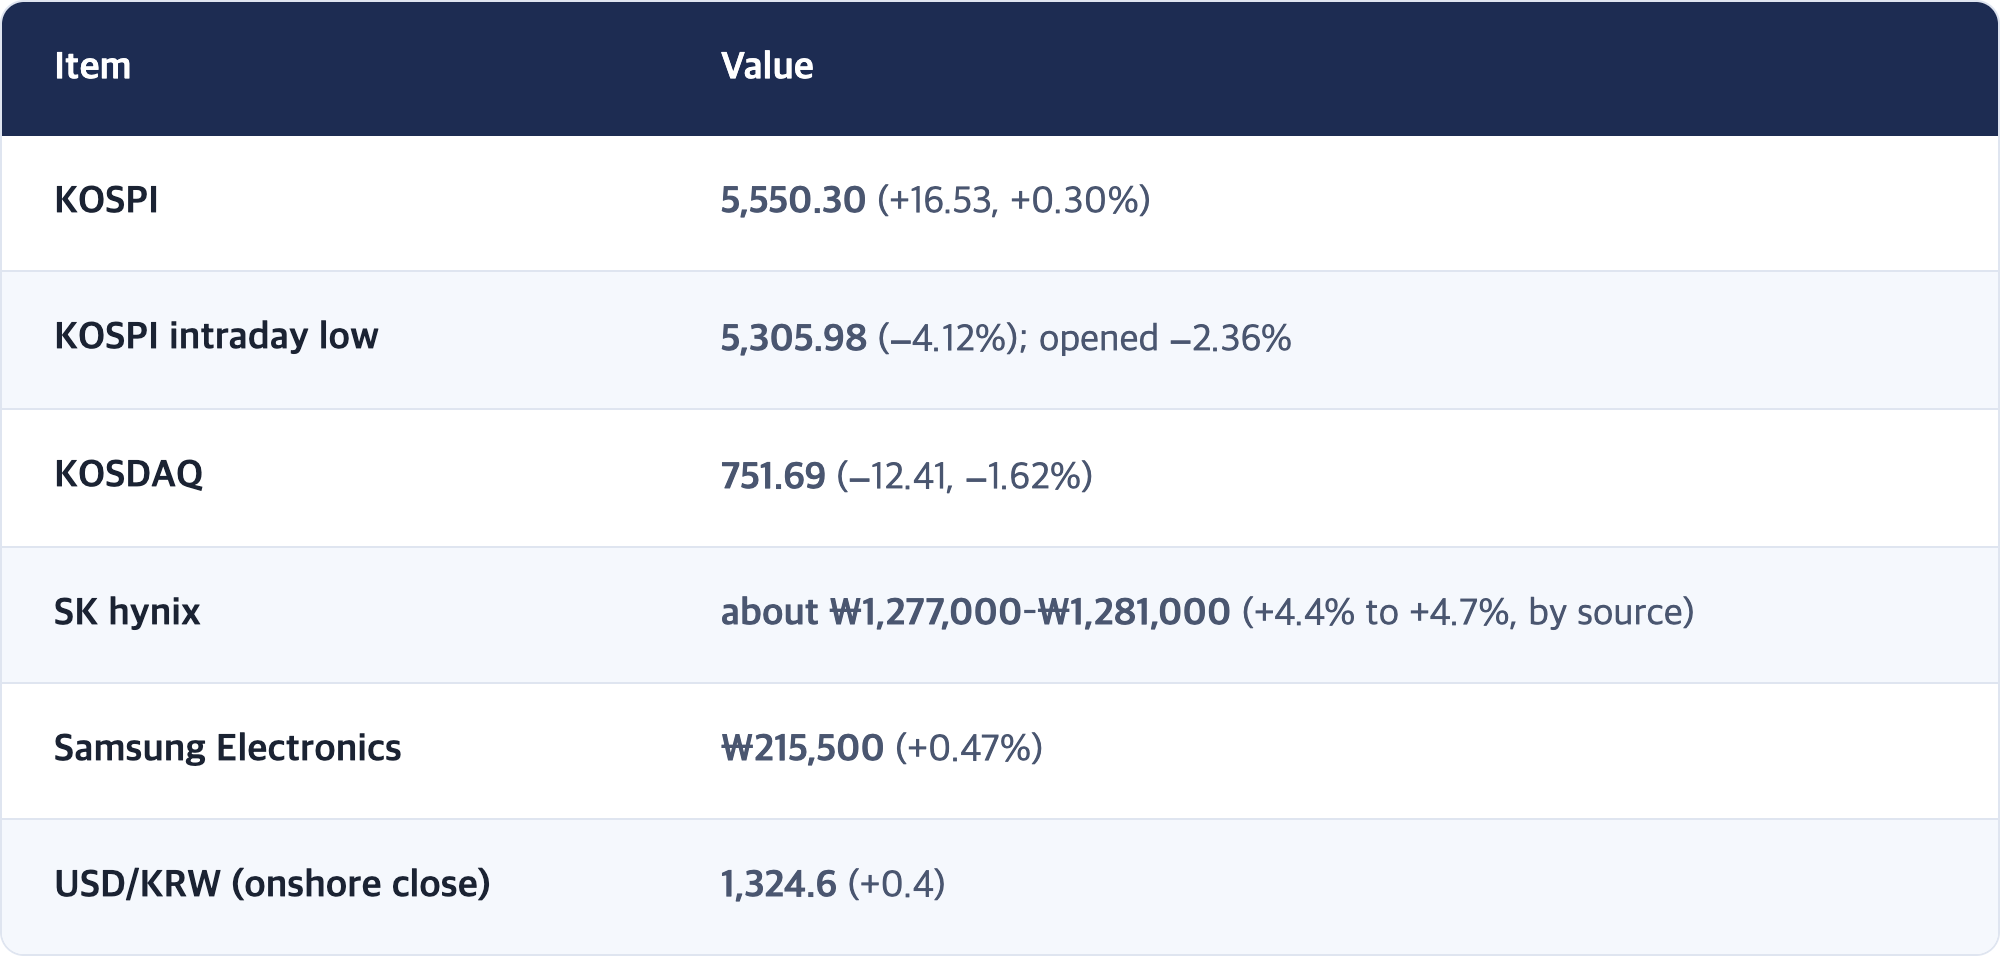
- ★ Seoul flipped from −4% to +0.3%. KOSPI 5,550.30 (+0.30%), intraday low 5,305.98 (−4.12%). SK hynix +4.4% to +4.7%, Samsung Electronics +0.47%, Samsung Biologics +7.71%. KOSDAQ 751.69 (−1.62%).
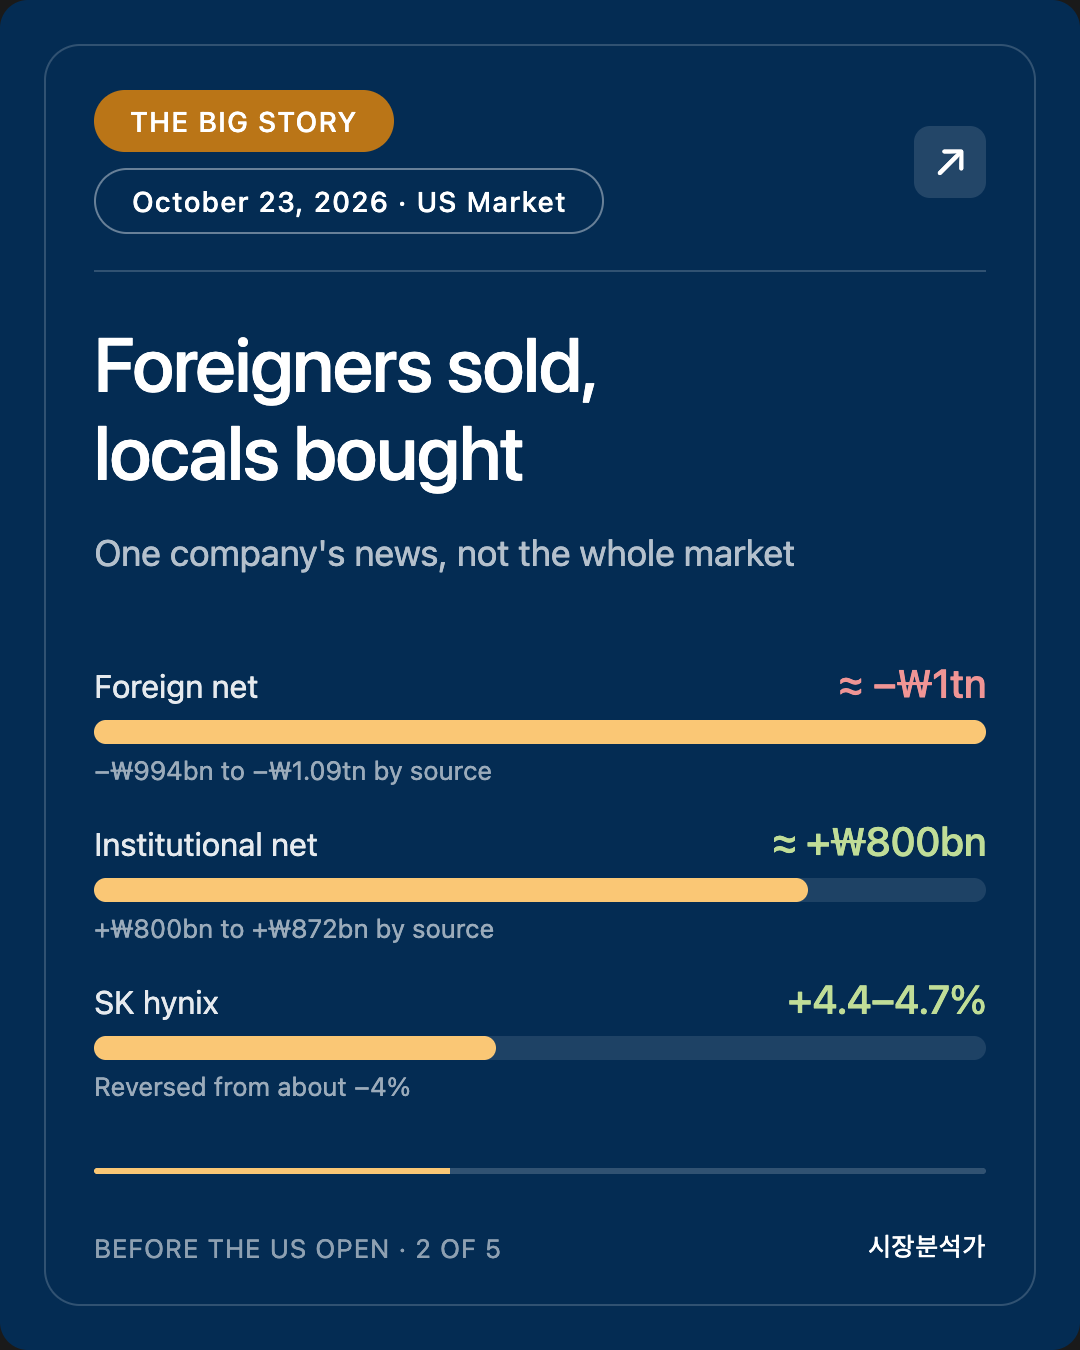
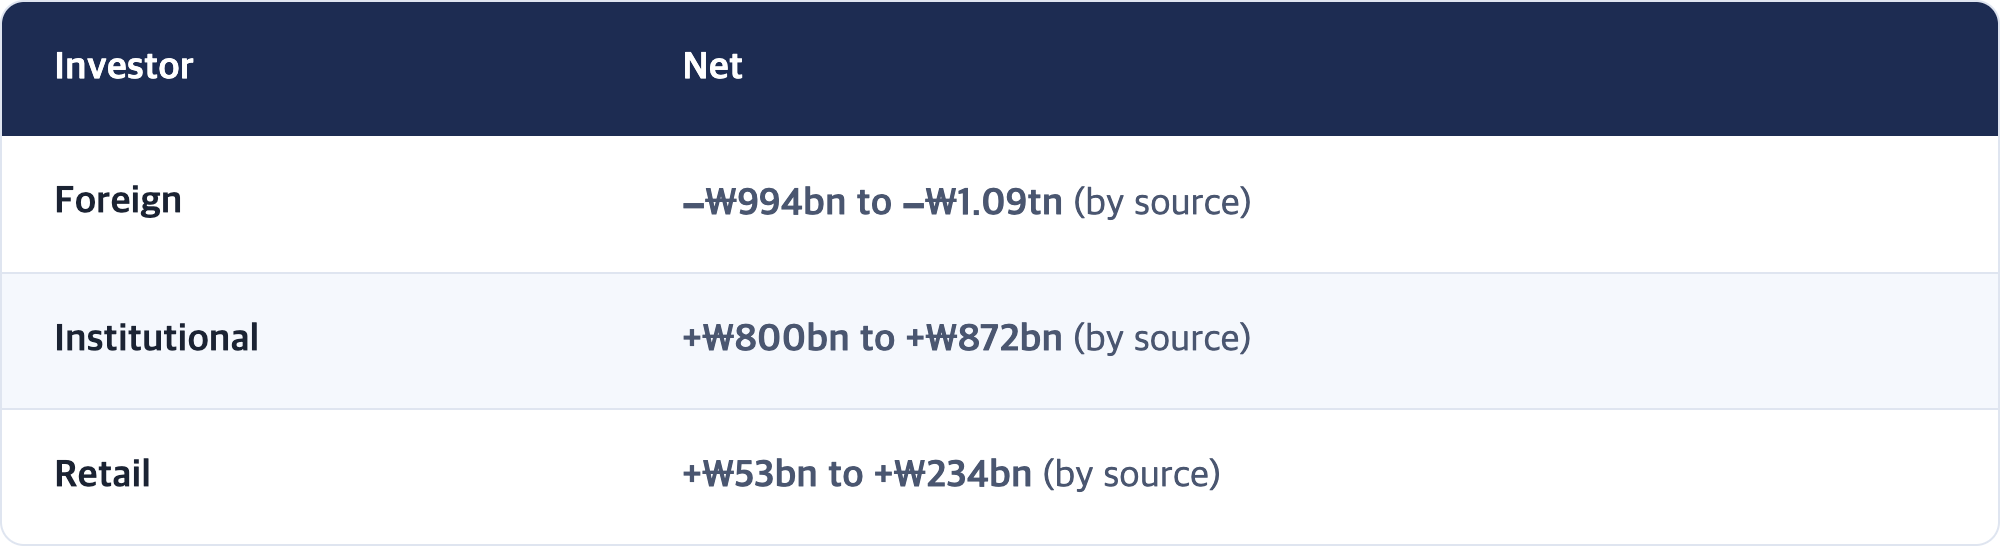
- ★ Flows diverged. Foreigners −₩994 billion to −₩1.09 trillion (by source), institutions +₩800 billion to +₩872 billion, retail slightly positive. USD/KRW 1,324.6 (+0.4), ending a five-day run of won strength.
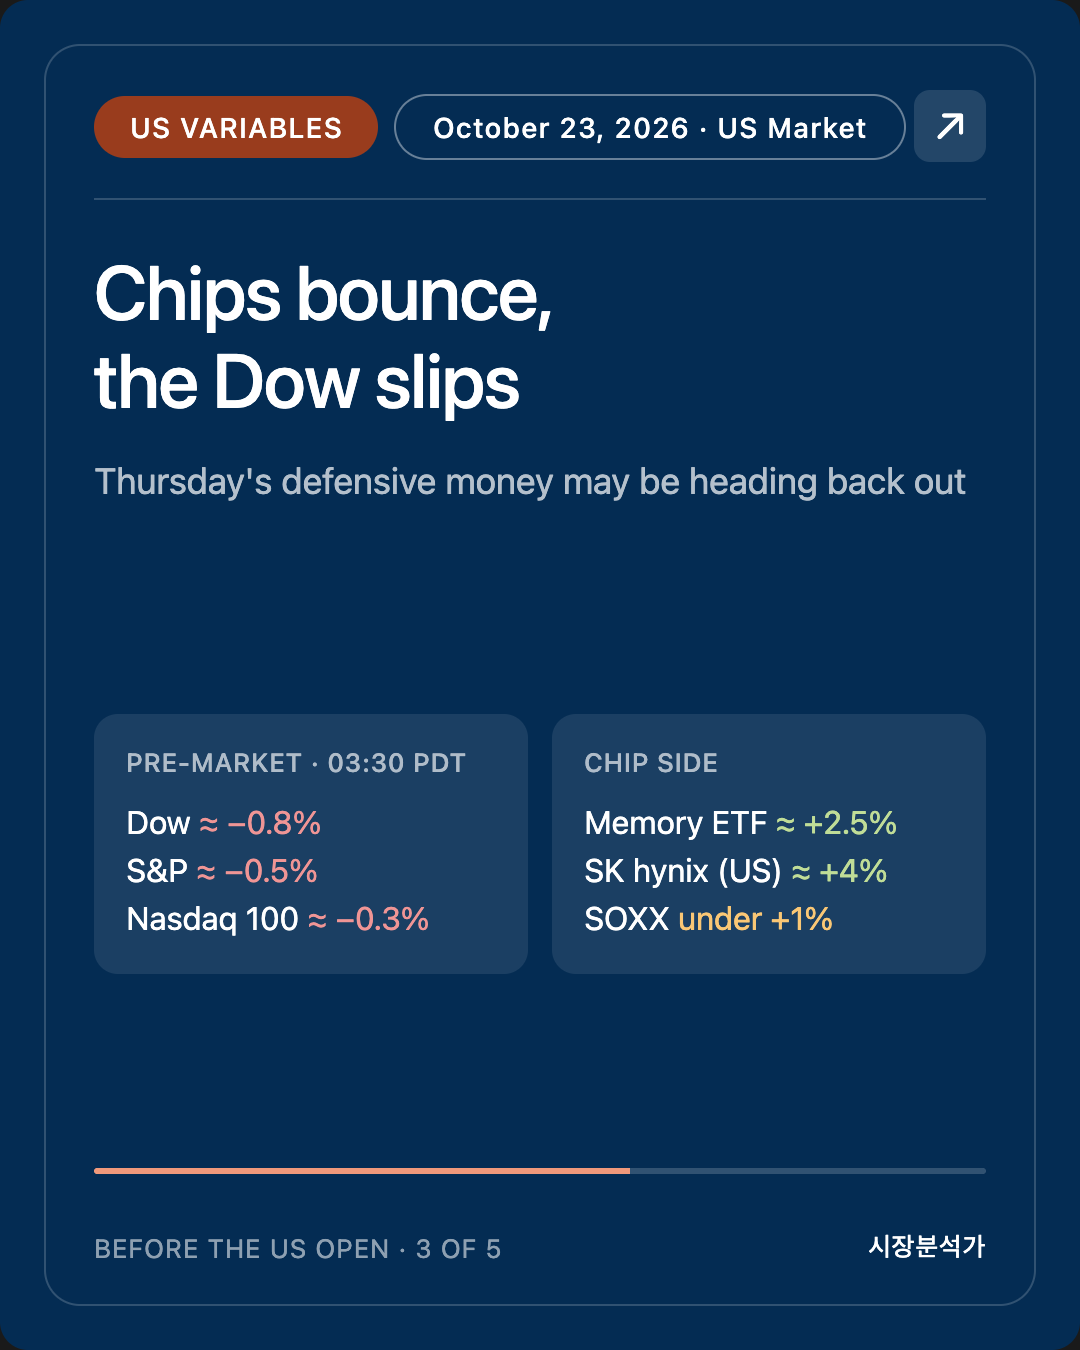
- ★ US futures: chips up, Dow down. Dow about −0.8%, S&P 500 about −0.5%, Nasdaq 100 about −0.3% (around 03:30 PDT). Memory ETF about +2.5%, SK hynix US-traded shares about +4%. Moderna down another 3.5%.
- Asia and Europe were mixed. Nikkei 62,693.11 (−0.34%), Hang Seng +0.84%, Shanghai reported both −1.3% and +0.9%. Europe's STOXX 600 about −0.4%, DAX about −0.5%, Kering down more than 11% on a 6% drop in Gucci sales.
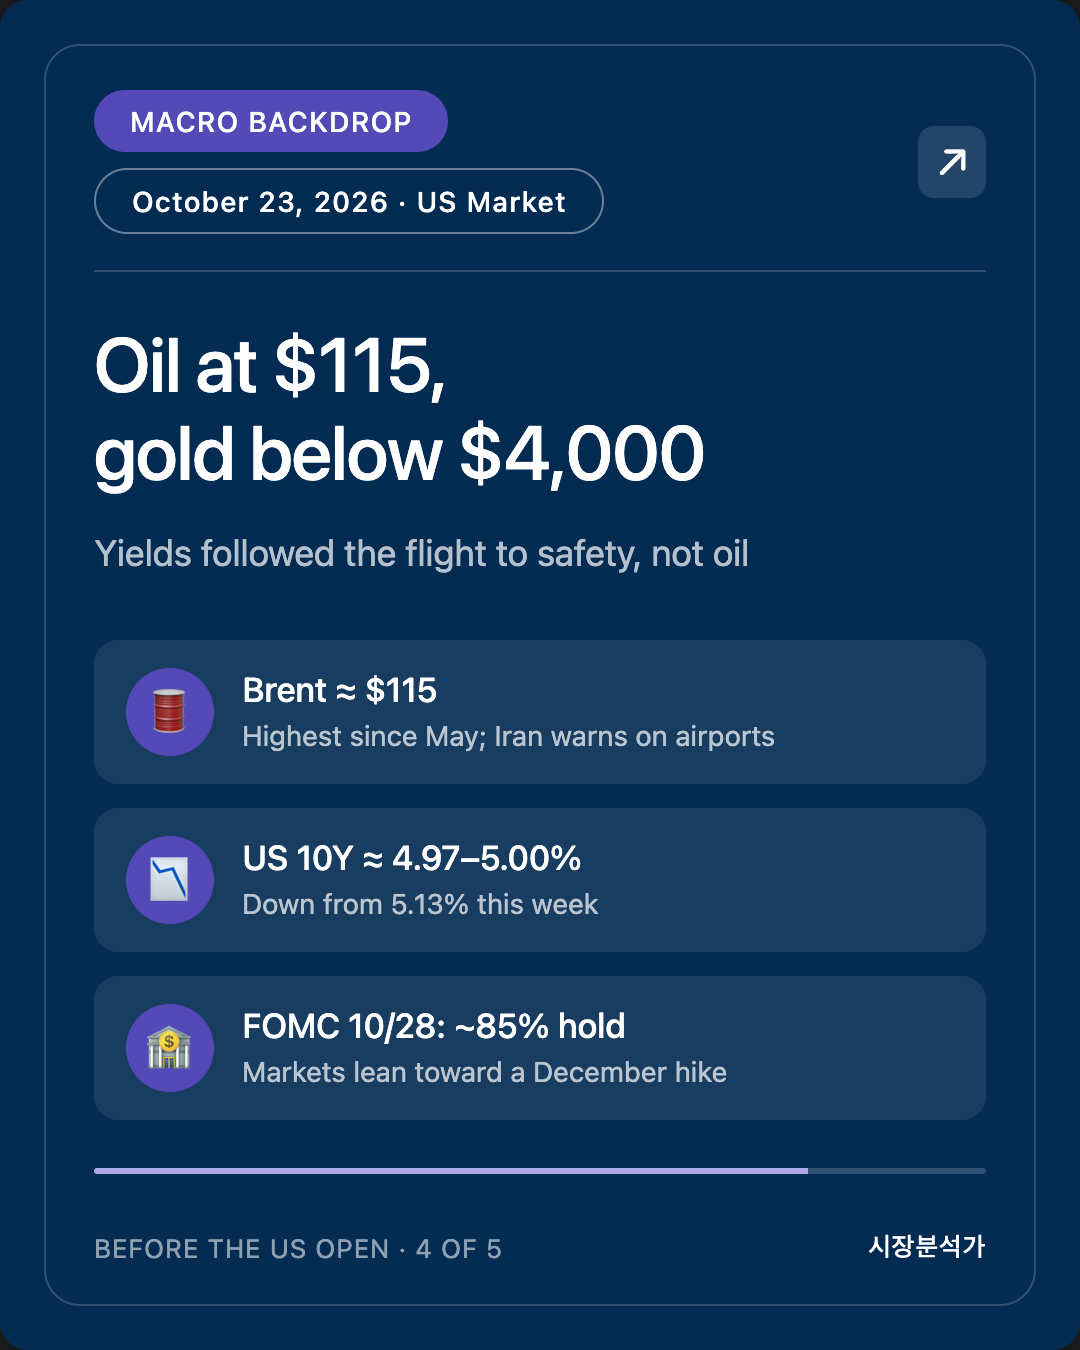
- Oil climbed again; gold lost $4,000. Brent about $114.7–$115, WTI about $101. US 10-year yield about 4.97–5.00%. Gold dipped below $4,000 for the first time since July, now around $4,030.
This is Mr. Can. Here is the October 23, 2026 brief ahead of the US market open.
Written: 2026-10-23 08:43 PDT (Korea 10/24 00:43 KST) · Work started 05:37 PDT
Basis: Korea, Japan, Hong Kong and China closes on 10/23 + Europe intraday 10/23 + US pre-market (around 03:30 PDT) + overnight Treasury moves
🔴 Scheduled for 05:30 PDT. Work began at 05:37 PDT but finished after the US open (06:30 PDT). US figures in this report are pre-market. Post-open prices are not included.
🟢 No missing editions. The previous edition was the 10/22 PM brief (Korea 10/23 preview).
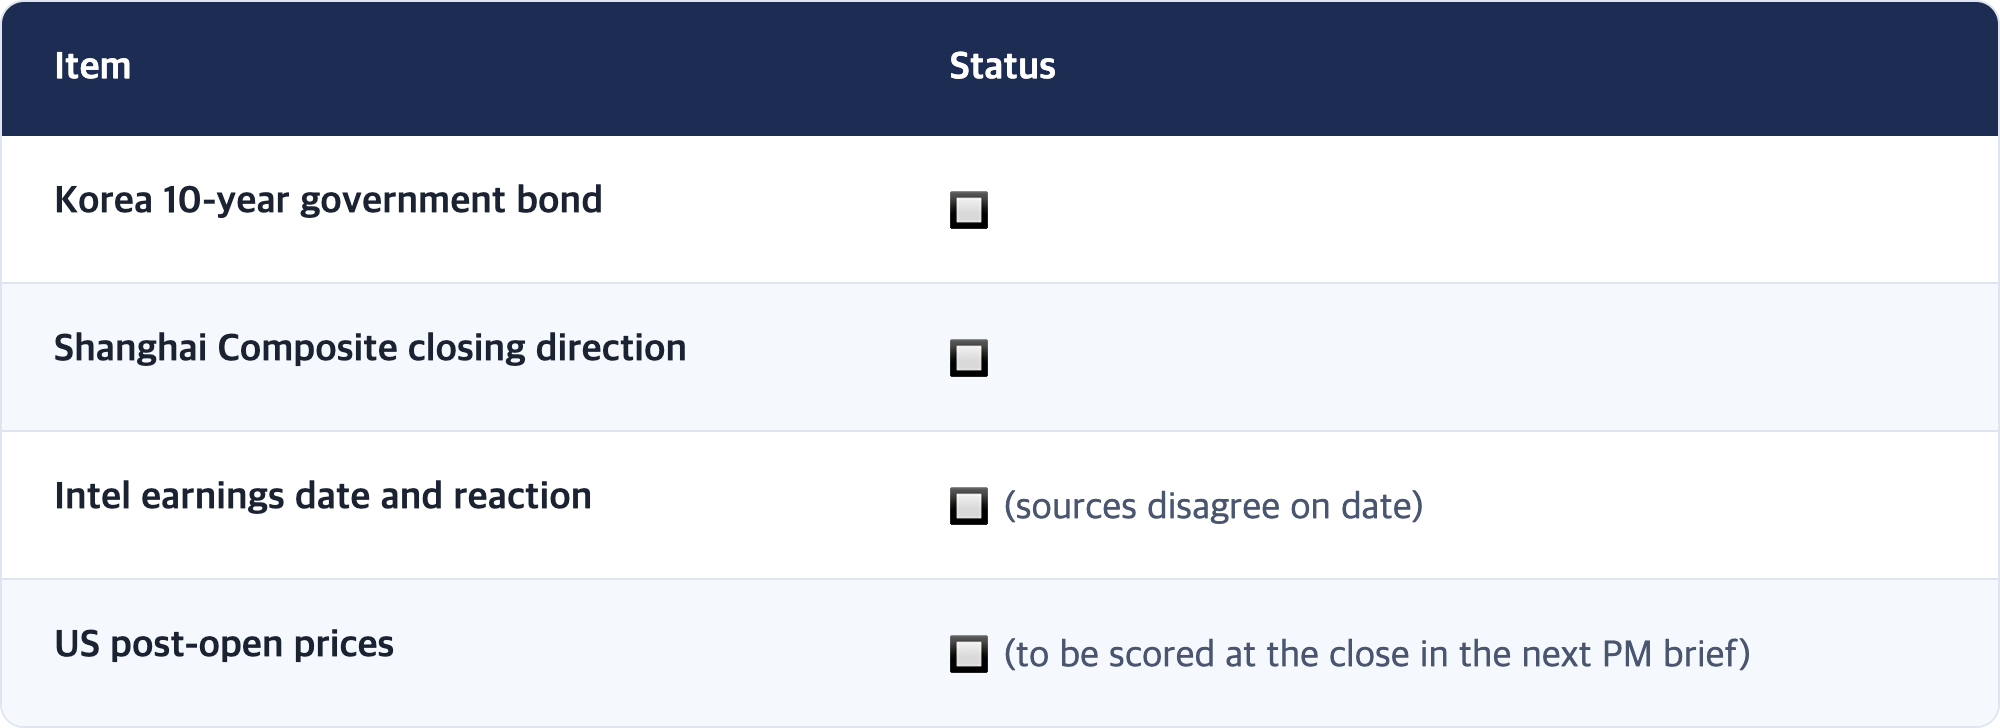
🟡 Sources disagree on the size of foreign selling in the KOSPI, SK hynix's exact gain, and even the direction of the Shanghai Composite (see section 7). Korea's 10-year government bond yield was again not available.
SEO Intro
Seoul changed its mind twice in one Friday session. The KOSPI took the full hit from Thursday's US chip rout (Philadelphia Semiconductor Index −6.72%) and fell as low as 5,305.98 (−4.12%), then climbed back to close at 5,550.30 (+0.30%), a recovery of roughly 4.6% from the low. The trigger was SK hynix, the world's second-largest memory chipmaker. It said it had dropped plans to list its US subsidiary Solidigm, and the stock swung from about −4% to more than +4%.
The money flows split. Foreign investors sold roughly ₩1 trillion (about $750 million), and Korean institutions bought about ₩800 billion to absorb it. The tech-heavy KOSDAQ missed the rebound, closing at 751.69 (−1.62%).
US futures paint the reverse of Thursday. Chips are bouncing pre-market, while Dow futures are the weakest at about −0.8%. Brent crude is near $115, its highest since May, and Iran has warned it will strike airports in neighboring countries if the US and Israel resume air strikes. Today's question for Wall Street: does the money that rotated out of AI into defensive stocks on Thursday come back, or does it stay put ahead of a risky weekend in the Middle East?
1. Checkpoint Scorecard
The four markers set in the 10/22 PM brief (Korea 10/23 close)
The framing was "Had Seoul's −3.5% on Thursday already priced in New York's −6.7% chip drop?" The open slot for a third variable was whether the Strait of Hormuz tanker reports were true.
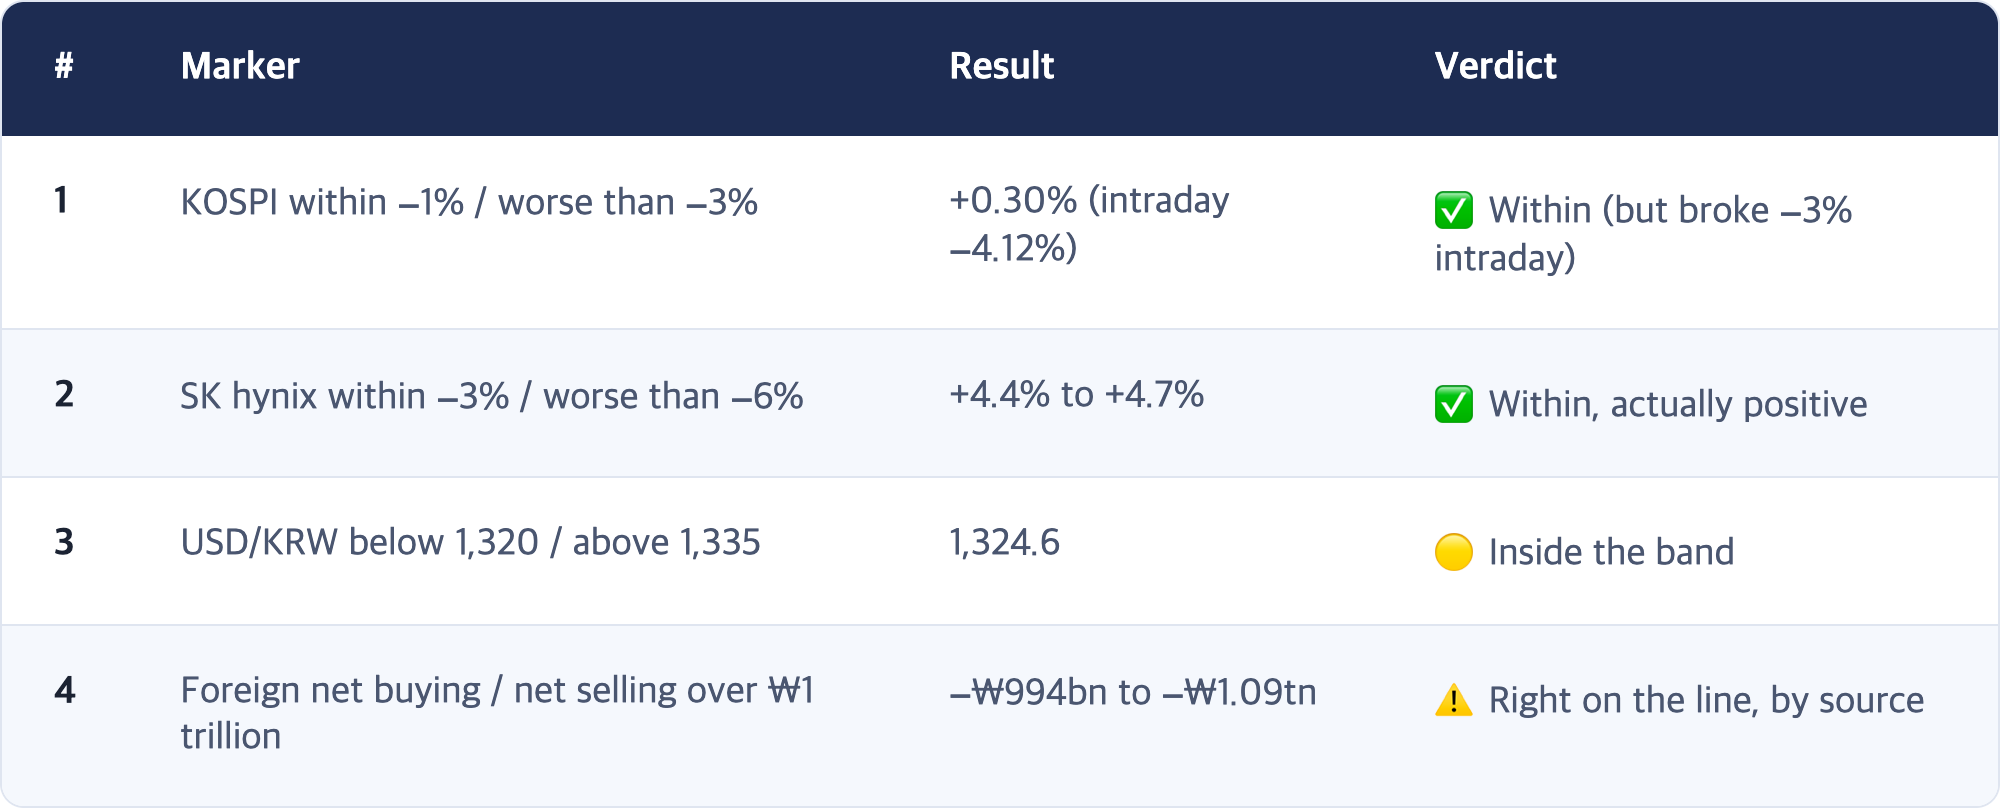
★ [Interpretation] The close said "already priced in." The intraday said "there was more to pay."
On closing prices, markers 1 and 2 landed on the "within" side: Seoul had panicked a day early and took less damage. But the −4.12% intraday low blew past the −3% line. The morning paid New York's remaining bill; the afternoon reversed it with a different catalyst.
That catalyst was the Solidigm listing cancellation. The PM brief mentioned it only briefly as a Korea-side item. It ended up setting the day's direction. Once again, the verdict was right but a third variable did the explaining. Not the open slot (Hormuz), but an item already on the page that we had underweighted.
2. The Big Story: Seoul's Intraday Reversal, Foreigners Sold and Locals Bought
[Fact] Korea close, 10/23 (Fri)
[Fact] KOSPI net buying by investor type
[Fact] Gainers and decliners
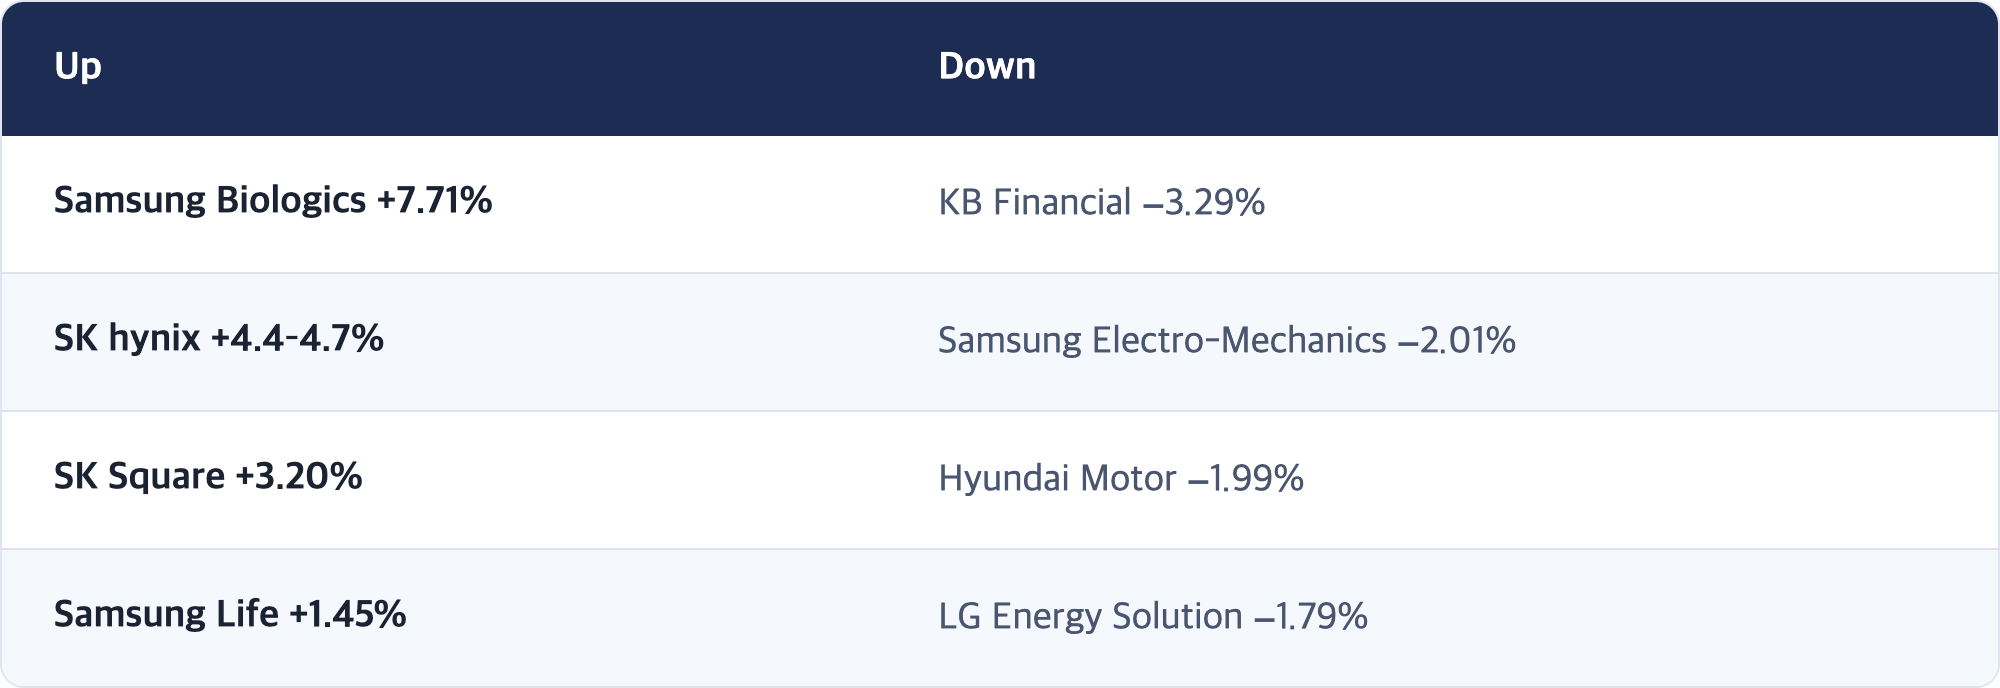
On the KOSDAQ, most large caps fell, including battery-materials makers EcoPro (−5.83%) and EcoPro BM (−5.50%).
★ [Interpretation] The rebound came from one company's news, not the whole market
- SK hynix did not rally because AI worries eased. Korean investors dislike "split listings," where a parent spins off a valuable subsidiary onto a separate exchange and existing shareholders lose part of that value. Dropping the Solidigm US listing removed that worry. This was a corporate-governance catalyst, not a chip-cycle one.
- That is why the KOSDAQ did not follow. Two names, SK hynix and Samsung Biologics, lifted the KOSPI, while batteries, financials and autos stayed weak. The index was positive, but many stocks were down.
- Foreign selling of about ₩1 trillion continued. The won's winning streak also ended. Domestic institutions created the rebound. Foreign investors trimming their Korean chip exposure is still the underlying trend; local institutions simply absorbed it today.
[Observation] US pre-market agrees: SK hynix's US-traded shares are up about 4% and a memory-chip ETF about 2.5%. Seoul's afternoon reversal is carrying into New York's pre-market.
3. US Variables: Does the Rotated Money Come Back?
[Fact] US close, 10/22 (Thu)
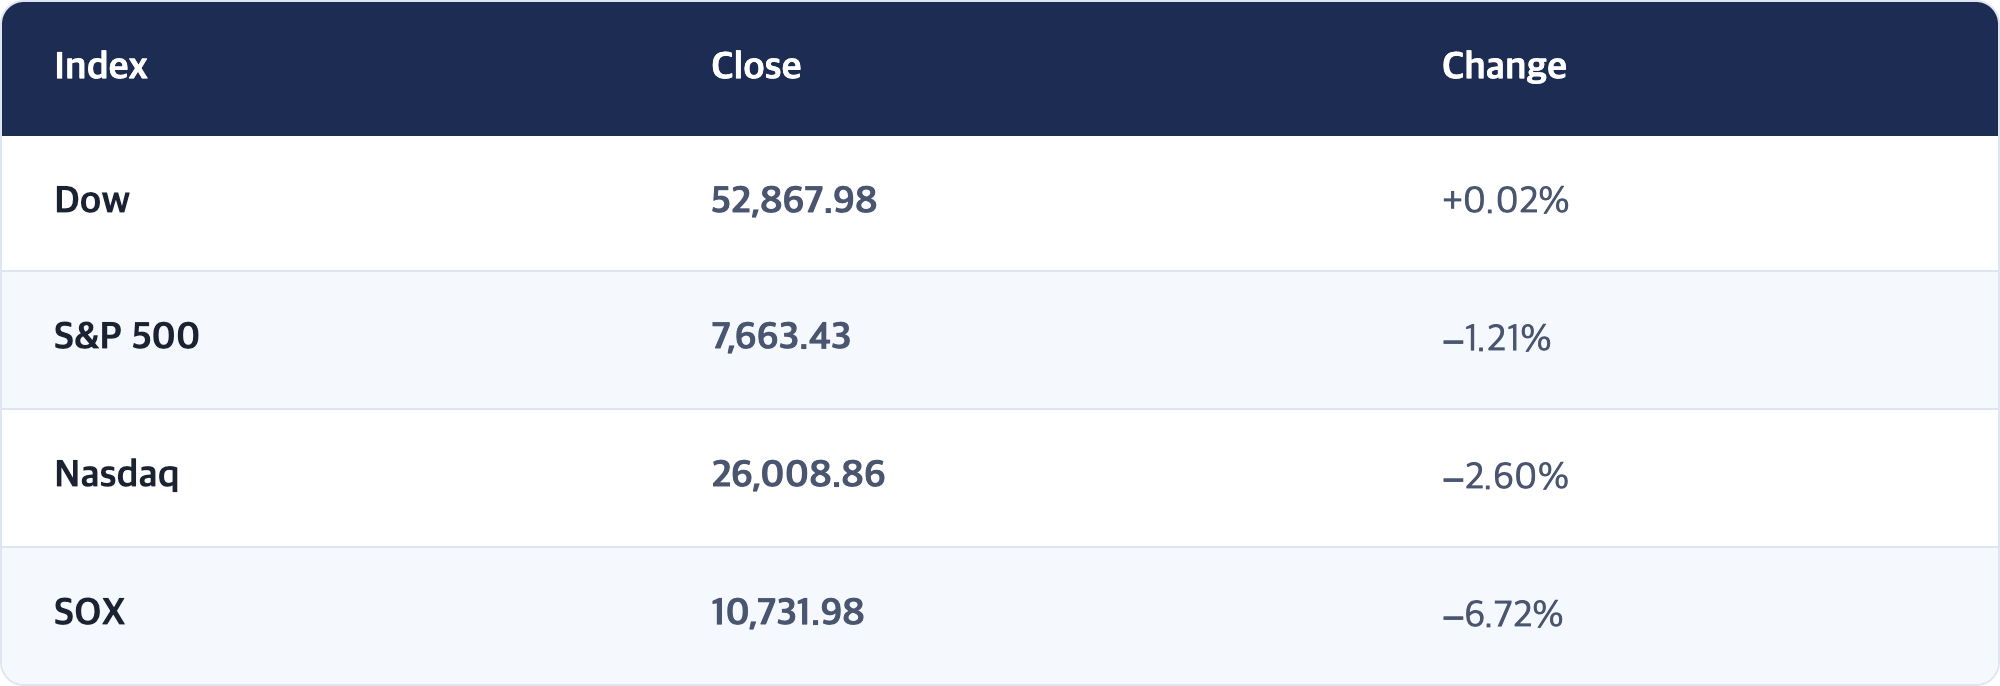
[Fact] US pre-market (around 03:30 PDT, Yahoo Finance)
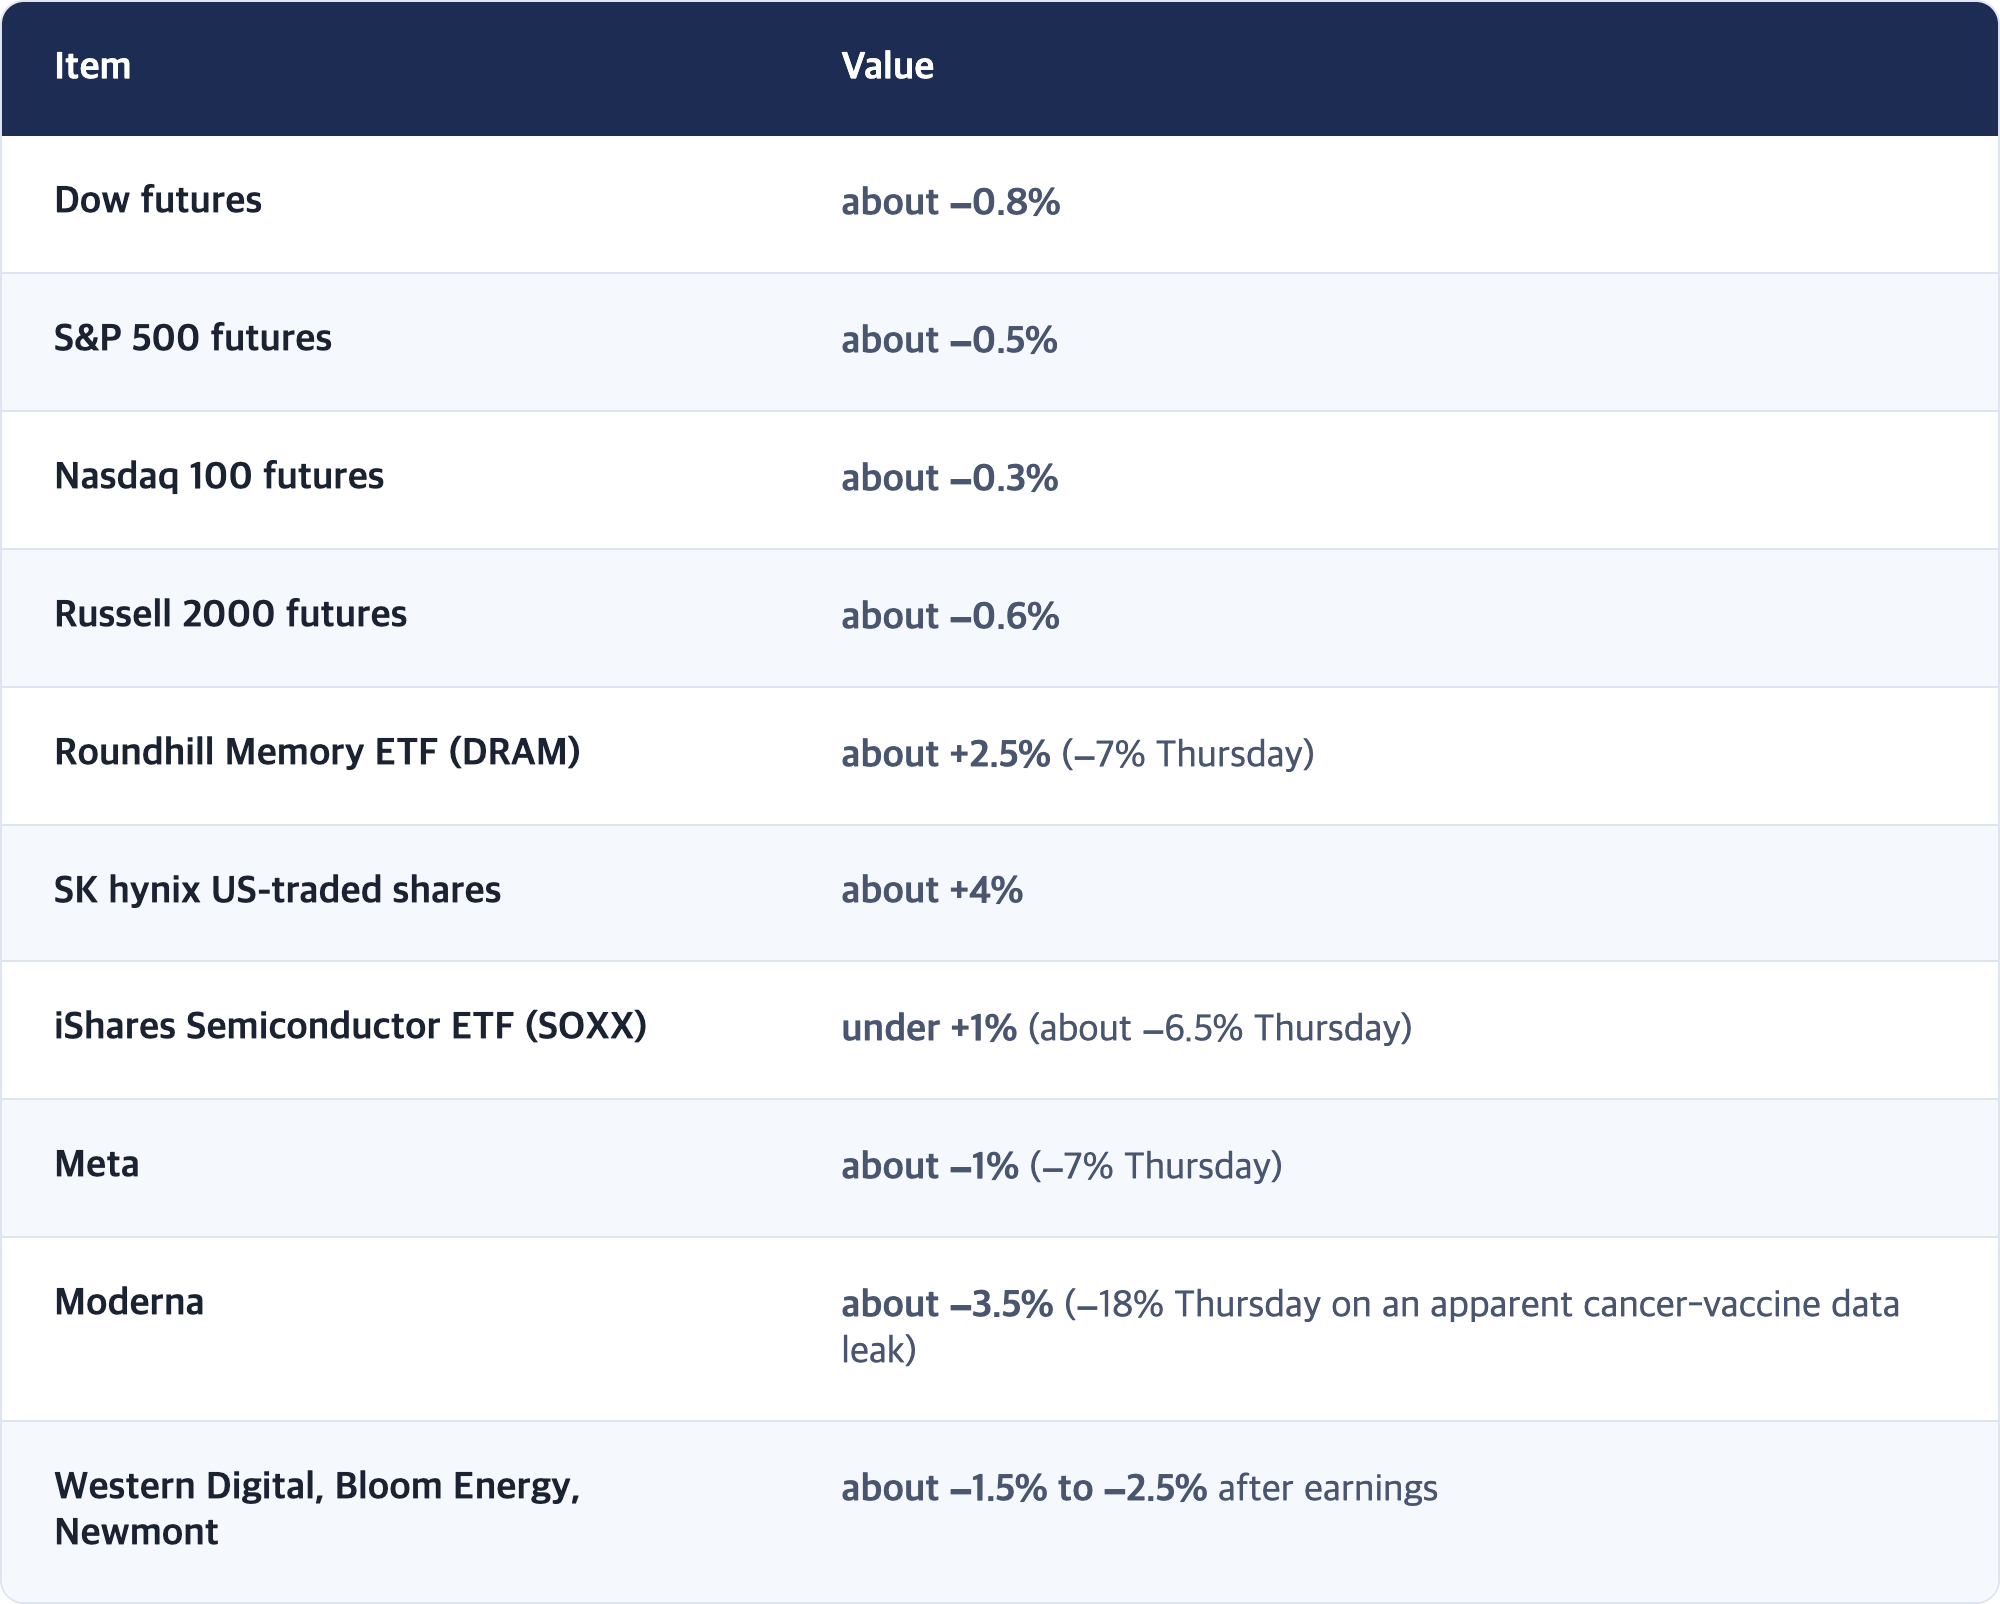
[Fact] Week to date through Thursday: Dow +1.7%, S&P 500 +0.1%, Nasdaq −0.5% (Yahoo Finance).
★ [Interpretation] The order is reversed from Thursday
Thursday's New York was "sell AI, buy defensives." This morning's pre-market is "buy a little chip, sell the Dow." The Dow being weakest may reflect some of Thursday's defensive inflows heading back out. But Nasdaq 100 futures are still negative, so it is too early to call it a return to AI. Whether the chip bounce survives the open is today's first test.
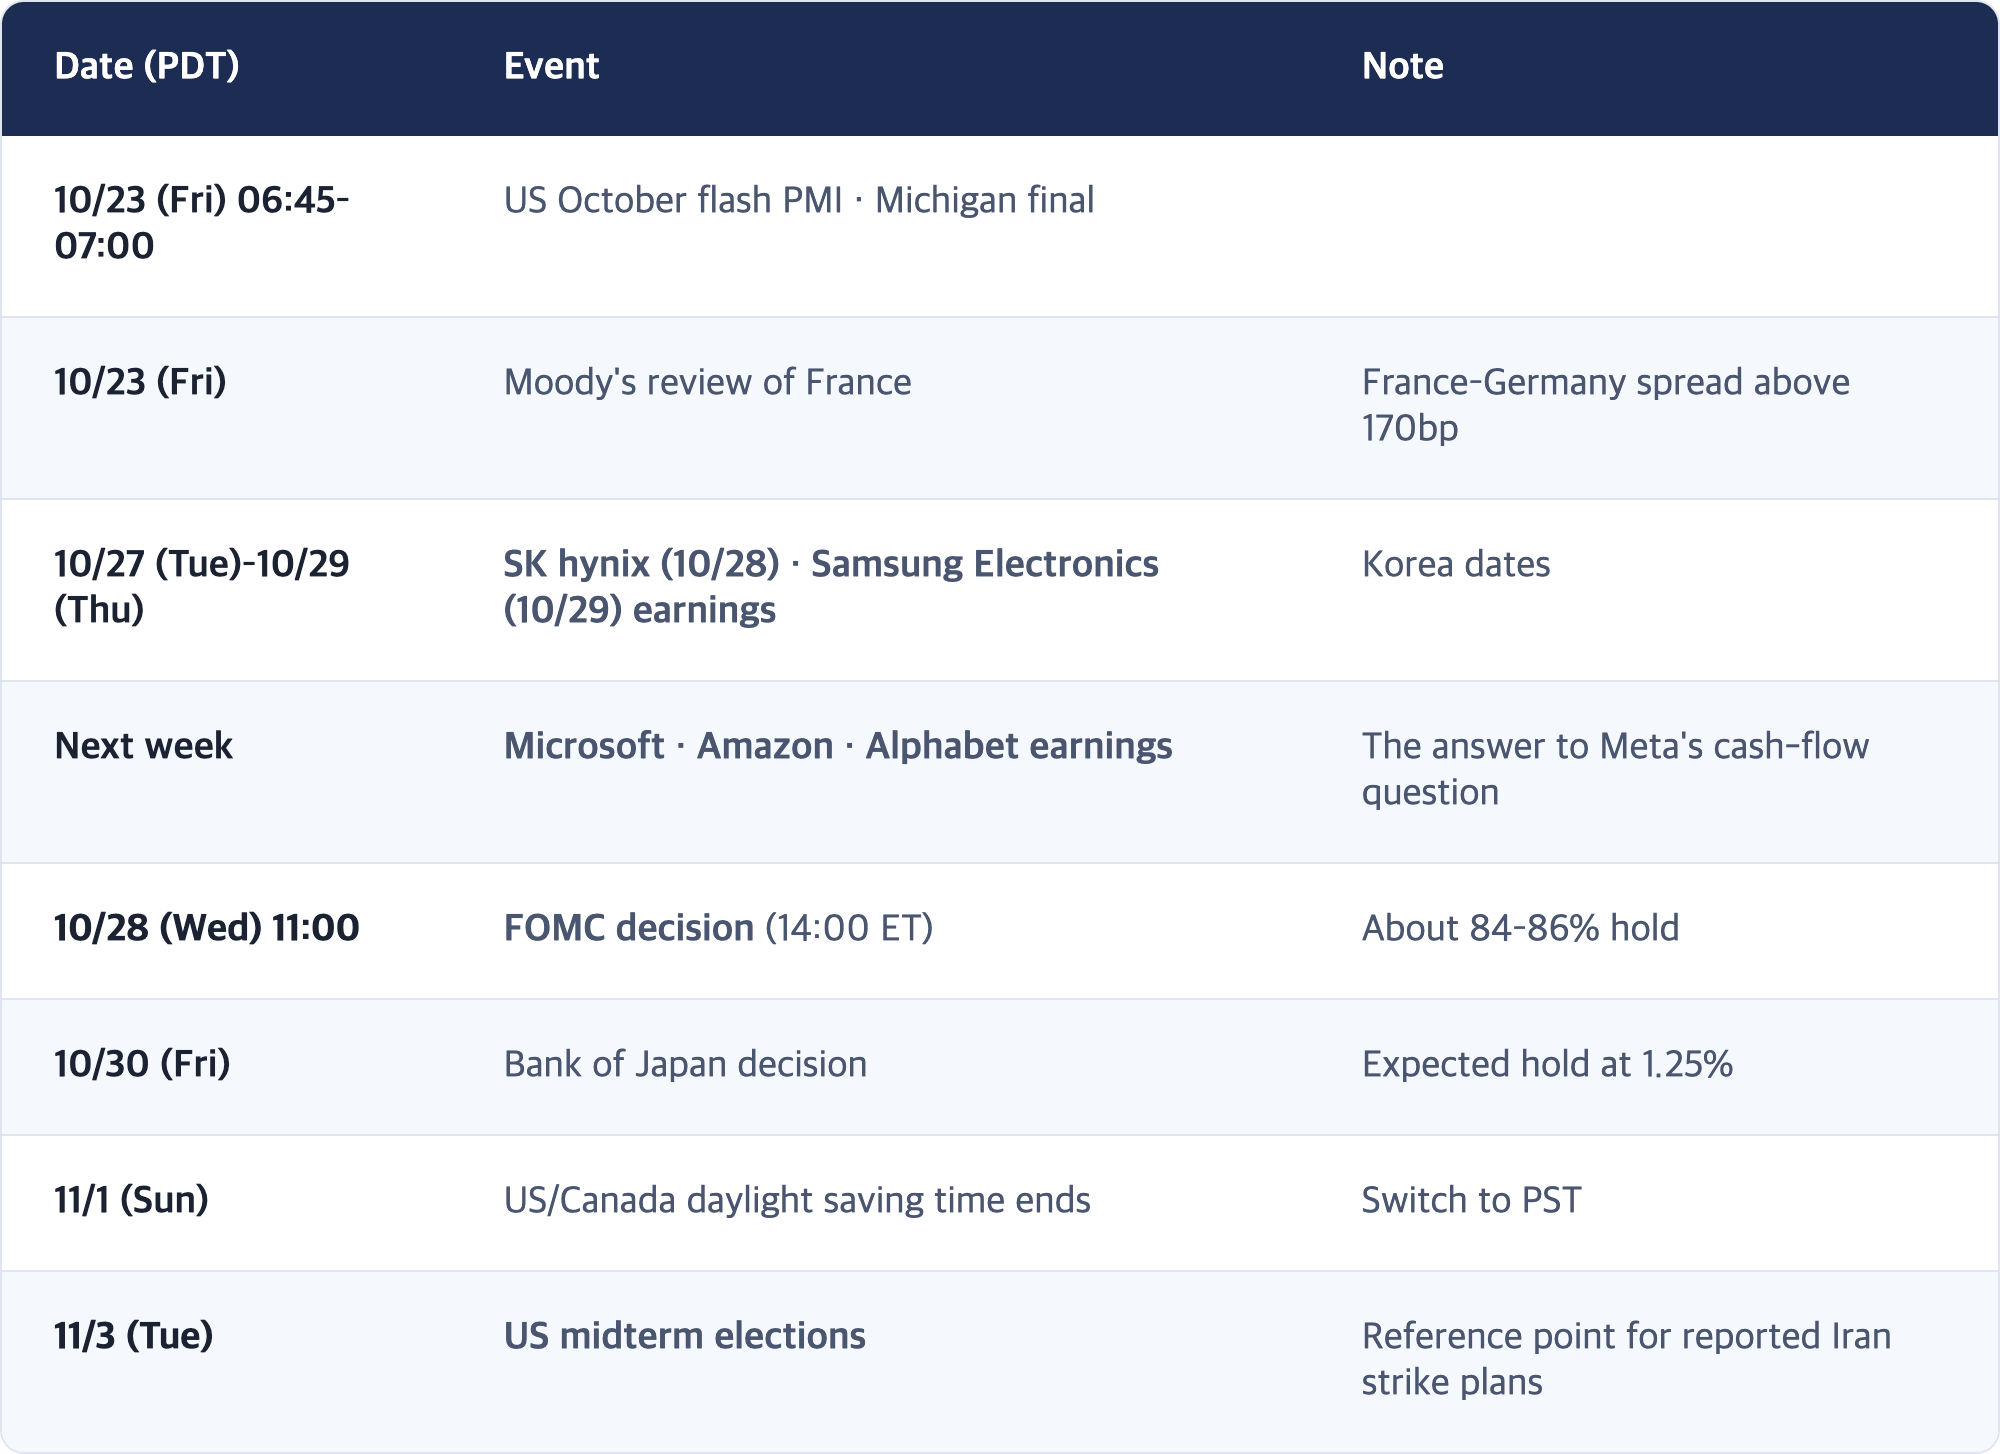
Next week is the real exam. Microsoft, Amazon and Alphabet report, and the Fed decides on Wednesday, 10/28. How the rest of Big Tech answers Meta's "cash flow" question will define what this selloff really was.
4. Macro Backdrop: Oil at $115, Yields Near 5%, Gold Below $4,000
[Fact]
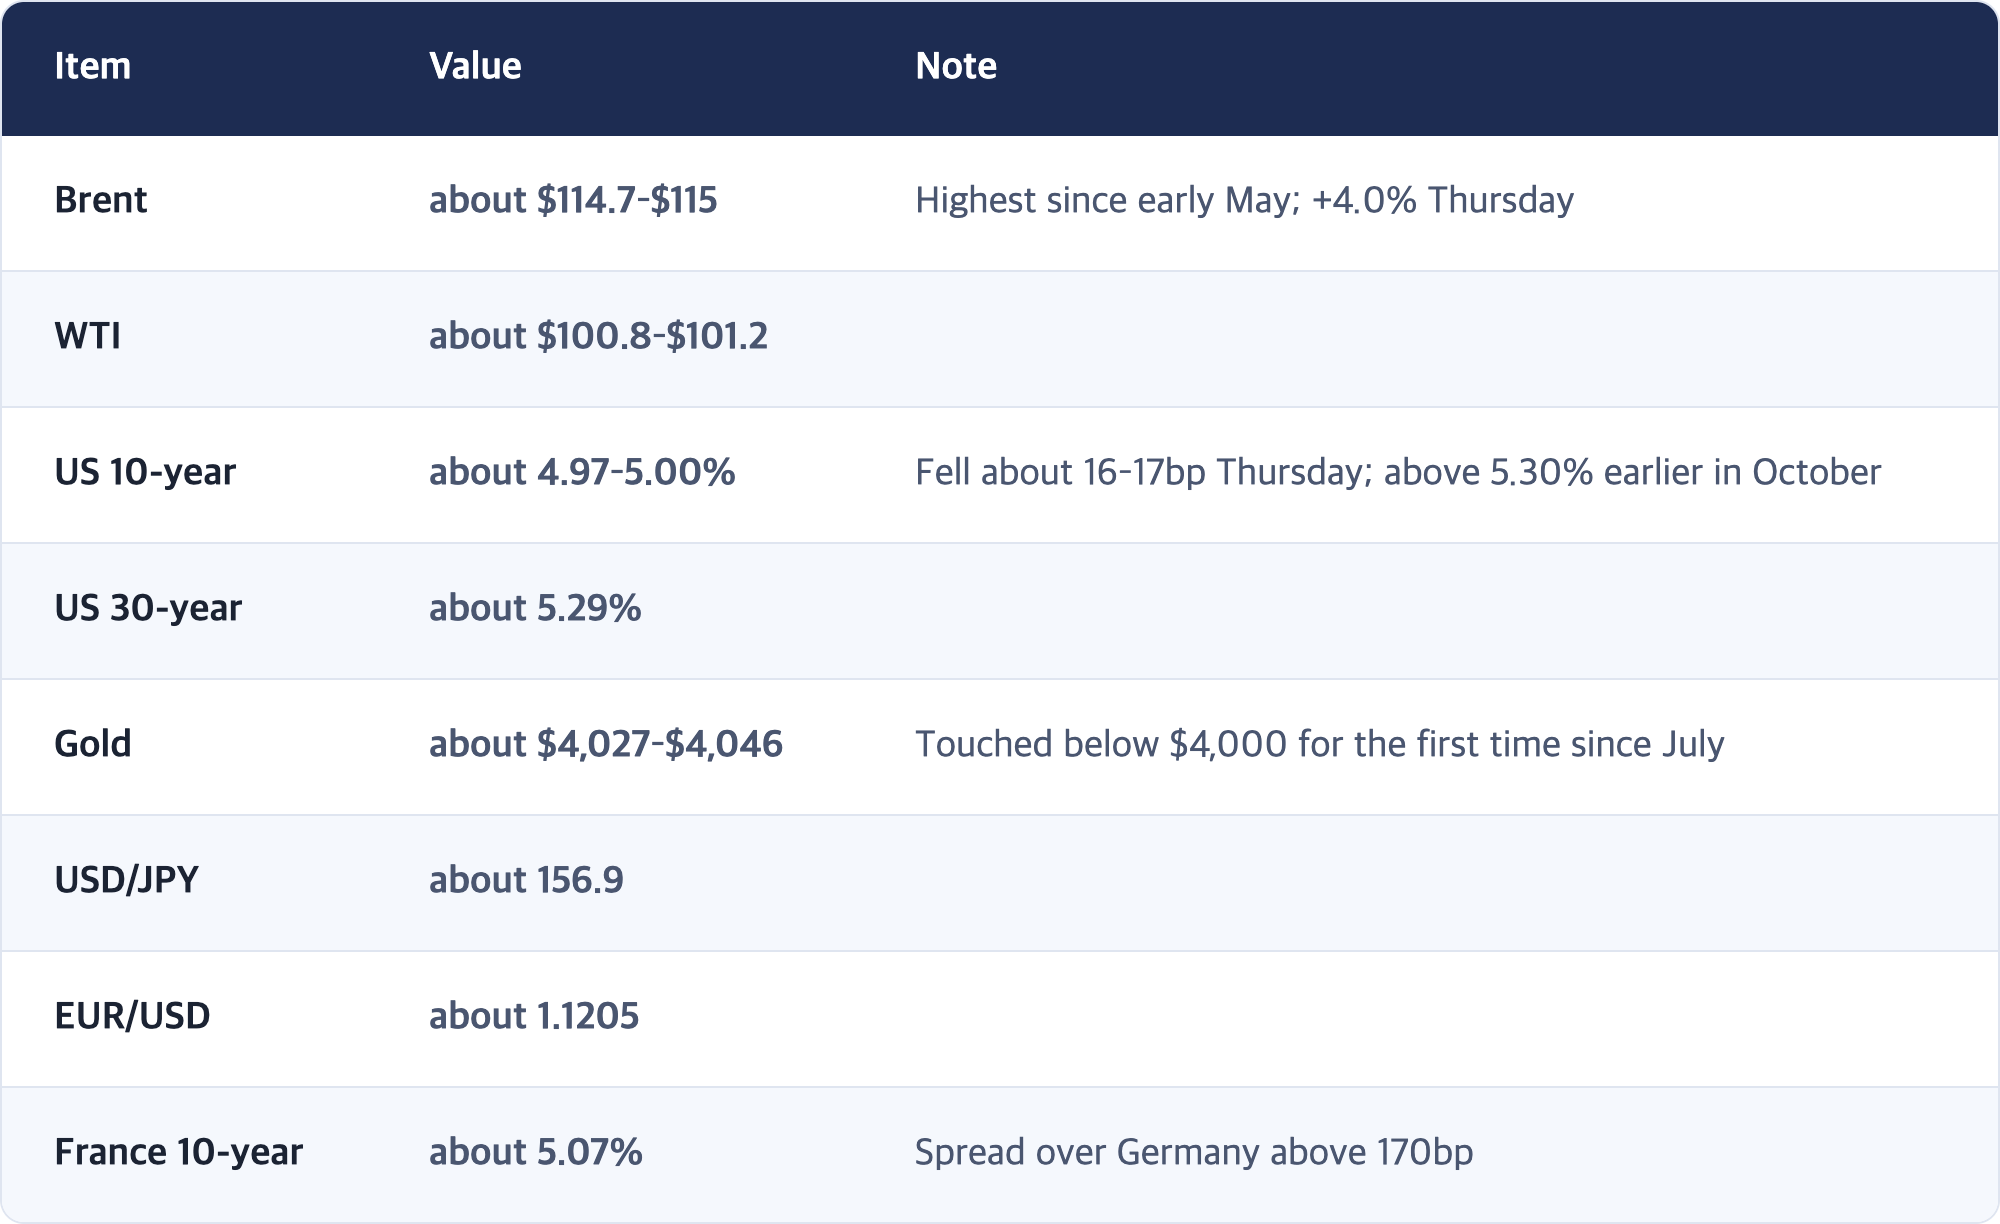
[Fact] Geopolitics and policy
- Iran: Warned it would hit airports and other civilian targets in neighboring countries if the US and Israel resume strikes. Deadly attacks in Saudi Arabia added to fears of a wider regional conflict.
- Fed: The 10/28 FOMC is priced at about 84–86% hold (CME and prediction markets, 10/20–22). Markets see a December hike as more likely. Current target range 3.75–4.00%.
- Japan: September core CPI 2.1%, back above the 2% target. The Bank of Japan is expected to hold at 1.25% on 10/30.
- US labor: Weekly jobless claims 194,000, lowest since July.
★ [Interpretation] This week, yields followed "flight to safety," not oil
Normally rising oil pushes yields up on inflation fears. This week Brent climbed to $115 while the 10-year fell from 5.13% to around 5%. The bond market is reading oil as a growth and risk-off signal more than an inflation one. Gold falling at the same time is also unusual. Lower yields usually help gold; this looks more like investors selling whatever they can, gold included, to raise cash.
5. Today (Fri 10/23) in the US: Checkpoints
[Observation] Today's schedule (PDT)
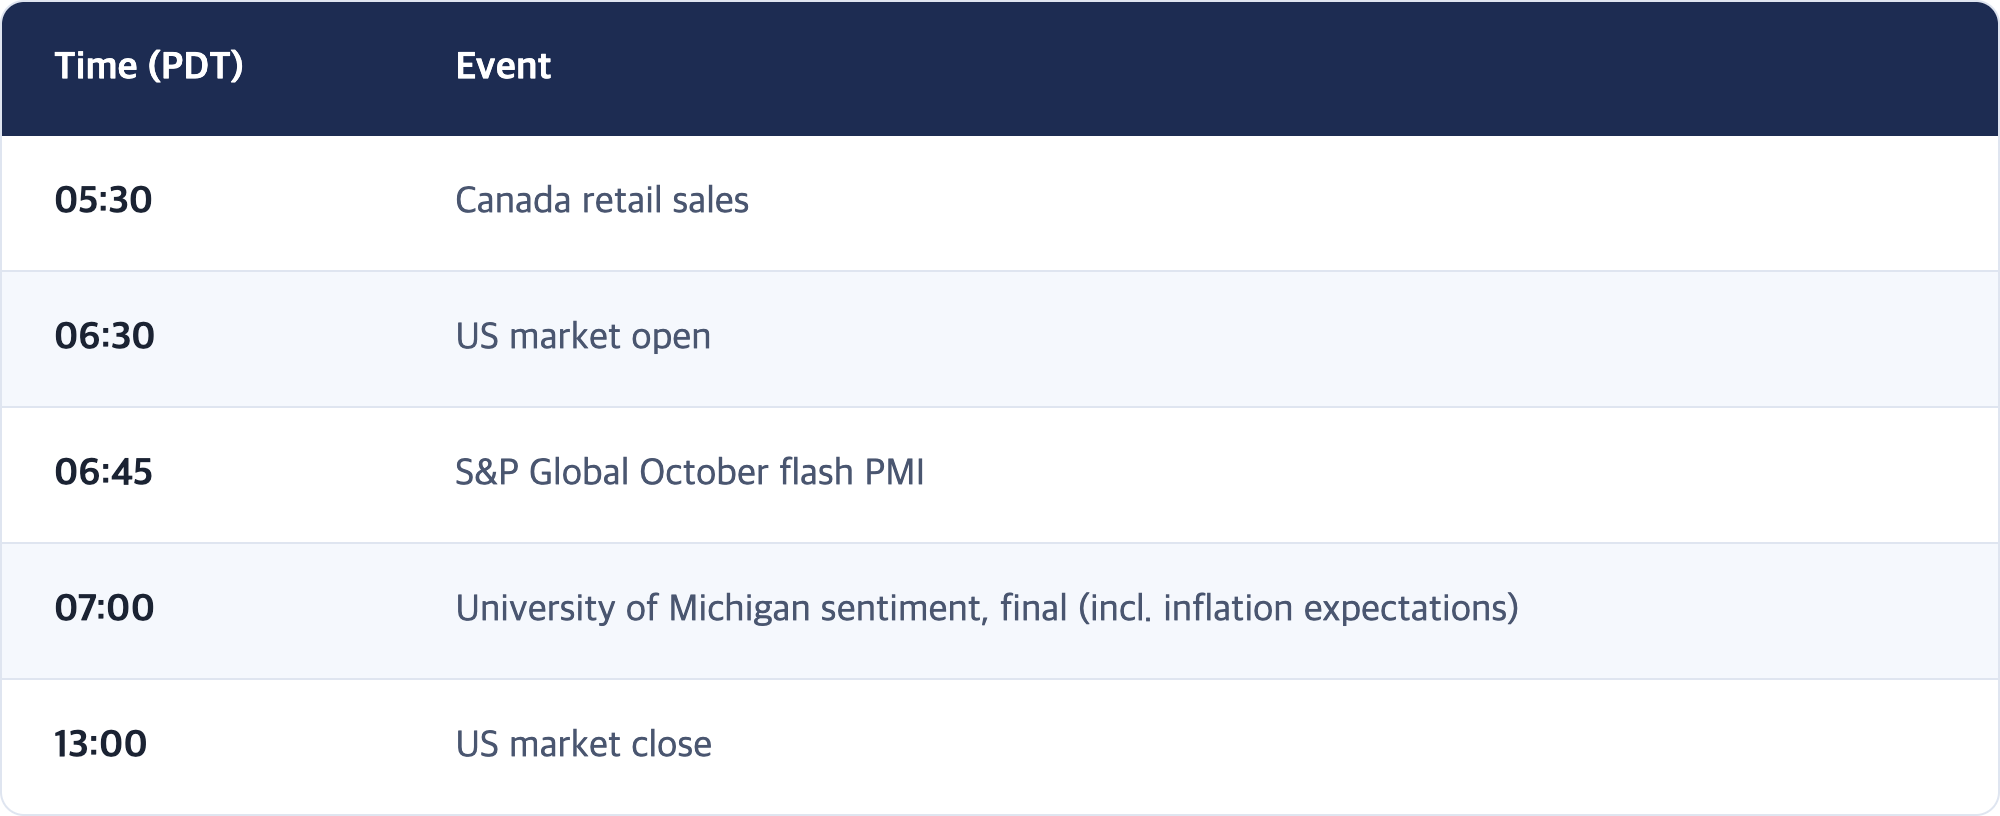
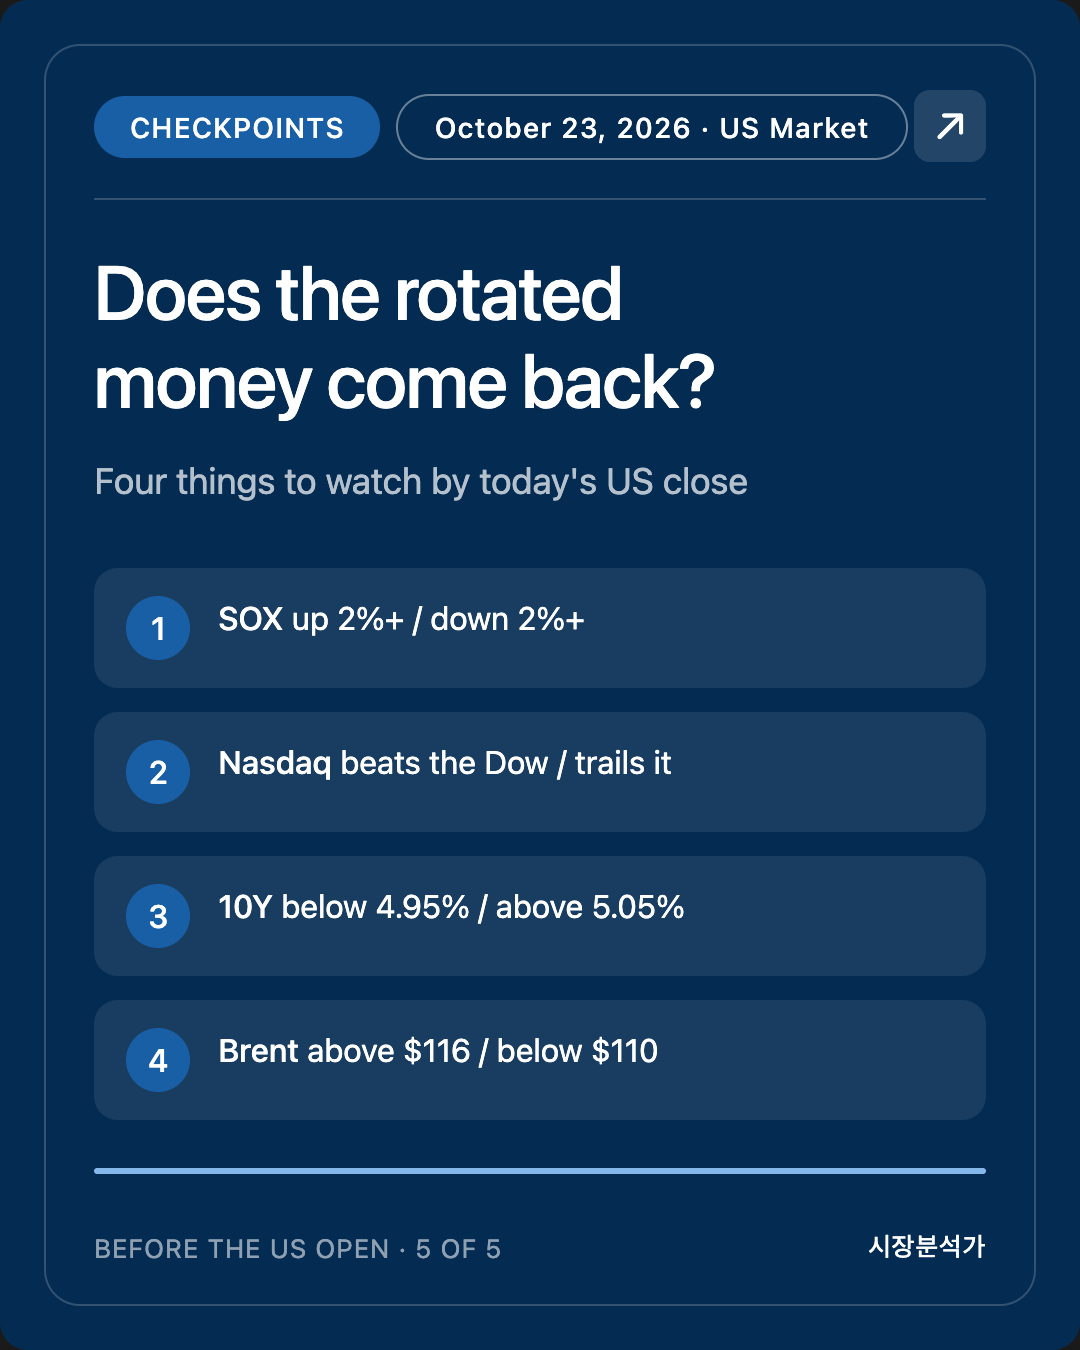
✅ Four checkpoints (by today's US close)
The framing: "Does the money that moved from AI into defensives come back, or stay?" The open slot for a third variable is weekend Middle East risk (Iran's airport-strike warning).
- SOX up more than 2% / down more than 2%. Does the chip bounce from Seoul and pre-market hold in the regular session? (Most important)
- Nasdaq beats the Dow / Dow beats the Nasdaq. Nasdaq ahead means "coming back"; behind means "staying put."
- US 10-year below 4.95% / above 5.05%. Does the flight to safety continue, or do oil-driven inflation worries win again?
- Brent above $116 / below $110. Friday's close shows how much weekend risk traders are buying in advance.
[Interpretation] If 1 and 2 both land on the first side, this week's AI selloff gets filed as a Meta cash-flow shock, and the market moves into "show me the numbers" mode with next week's Big Tech earnings. If 1 is negative and Brent tops $116, risk reduction ahead of the weekend has won. In that case, Monday's first question for Seoul is whether foreign selling extends to a third day.
6. Study Note: "Intraday Reversals" and "Wicks"
Concept
An intraday reversal is when an index or stock moves sharply one way during the day and then turns around to close on the other side. On a candlestick chart it leaves a long line hanging below the body, called a lower wick (or tail). A long lower wick is evidence that, at those low prices, buyers outnumbered sellers.
Analogy
Picture a fish market where prices crash in the morning, then a group of restaurant owners arrives at lunch and buys everything, so the day ends higher than yesterday. The key is that the morning sellers and the lunchtime buyers are different people.
Today's example
The KOSPI fell as much as −4.12% in the morning and closed +0.30%. The morning sellers were mainly foreign investors (about ₩1 trillion); the afternoon buyers were domestic institutions (about ₩800 billion). The spark was SK hynix's announcement that it had dropped the Solidigm listing.
Why it matters
A long lower wick is often read as "the bottom is in." But you should also ask who bought. When the rebound comes from one or two company-specific stories and foreigners keep selling, as today, one wick is not enough to call a change in trend. The real confirmation is whether the market avoids retesting that low in the following sessions.
One-line summary
A long lower wick is a signal, but always ask who bought to make it.
7. Corrections and Open Items
Corrections
- None.
Source discrepancies (value used in this report)
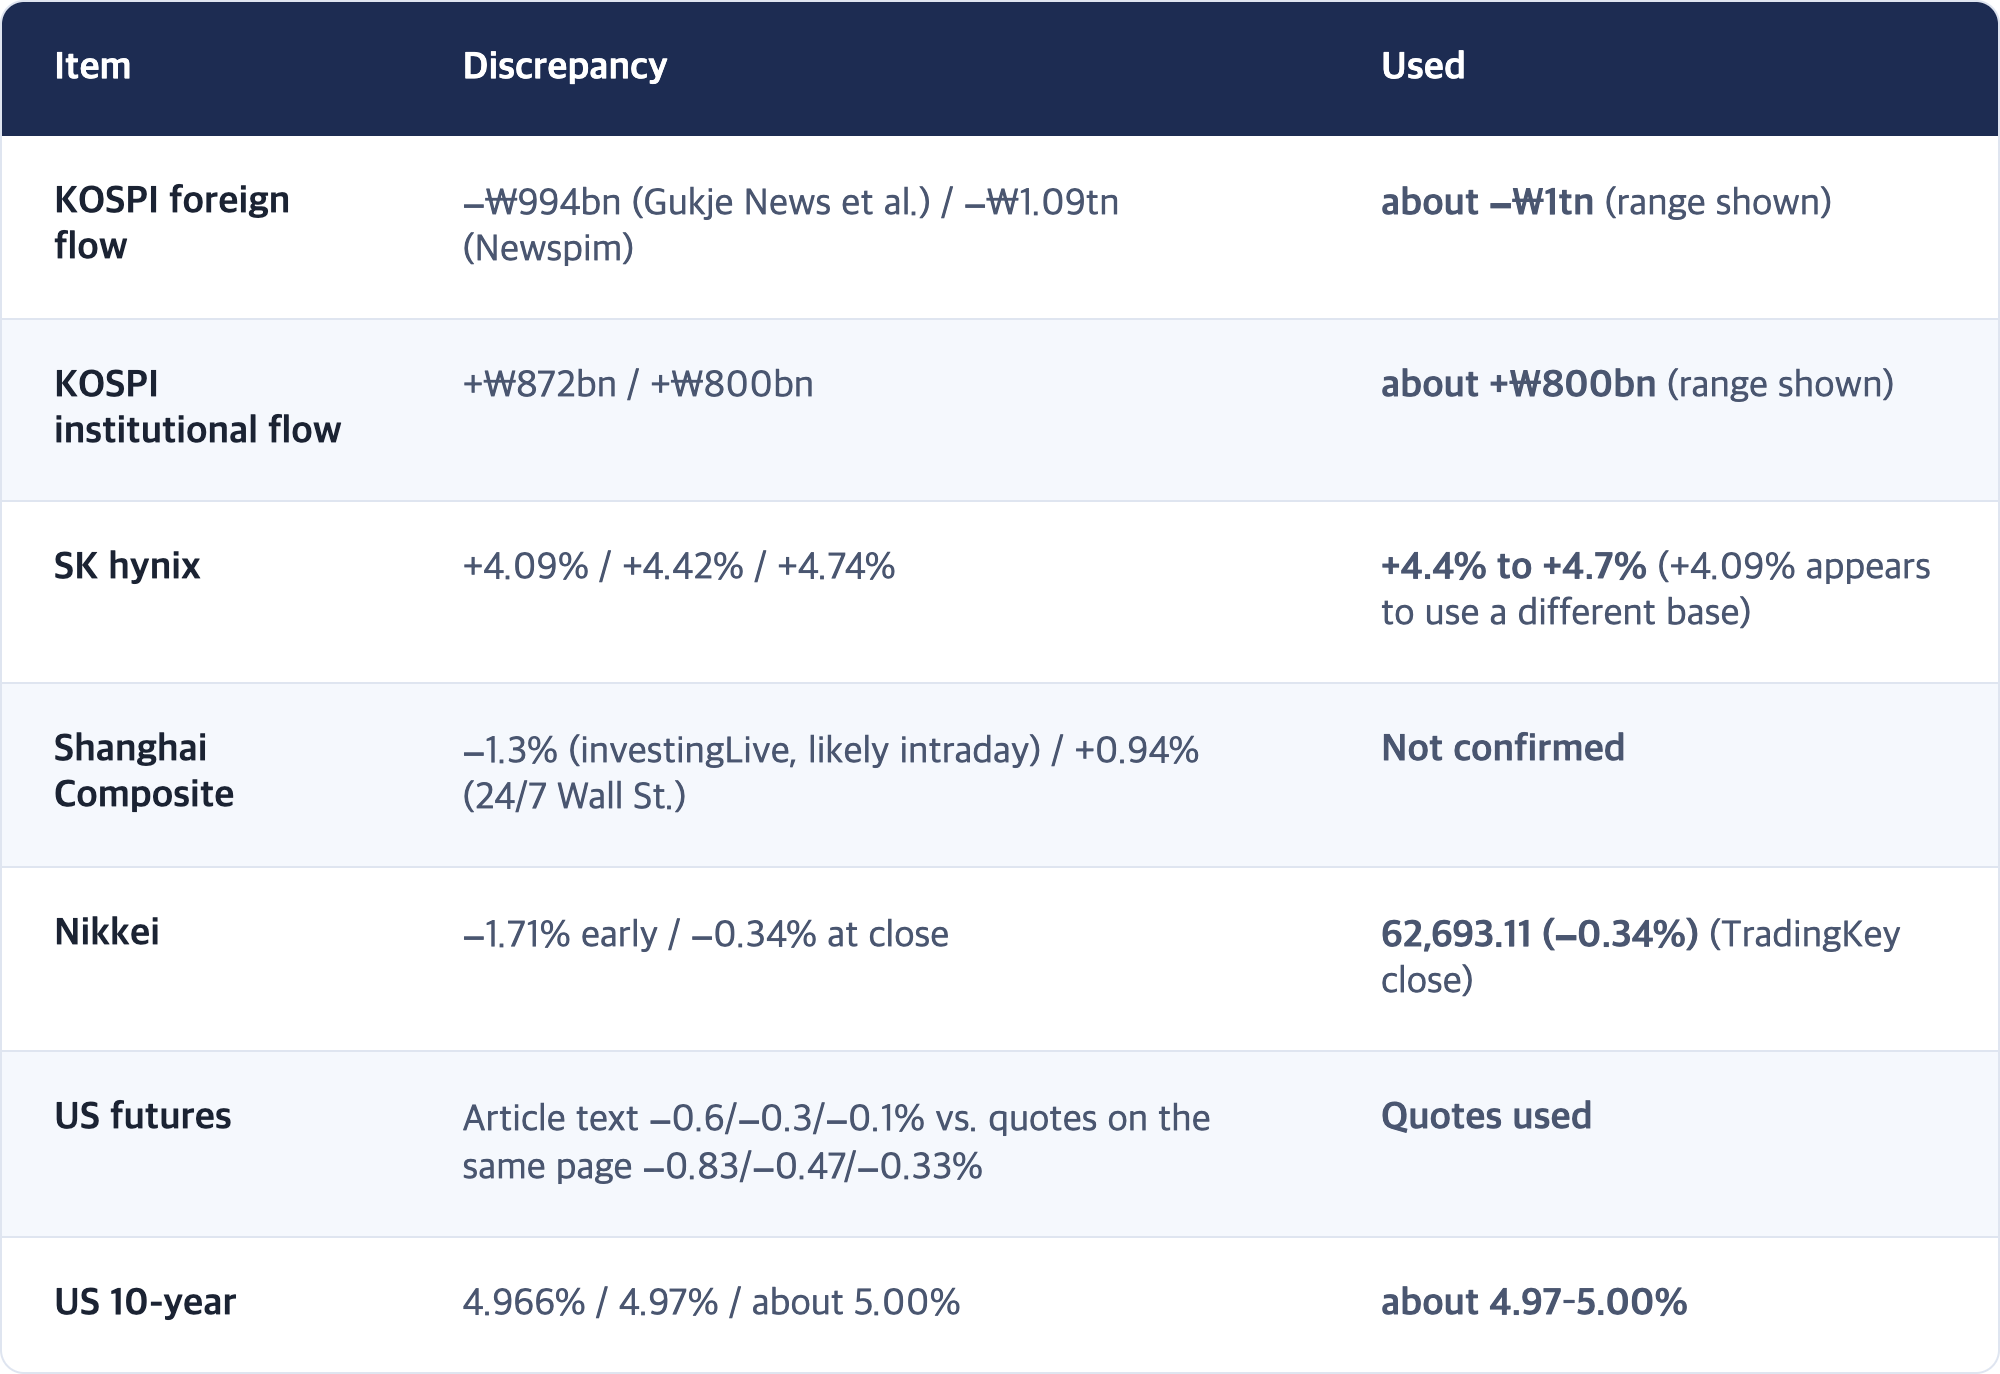
🔲 Unconfirmed
8. Event Calendar (PDT)
Sources
- Market close: KOSPI rebounds from 4% intraday drop; SK hynix +4.42% | Newspim
- KOSPI closes up 0.30% on SK hynix and Samsung Biologics | Gukje News
- SK hynix flips from −4% to +4%; KOSPI closes up 0.3% | Seoul Shinmun
- KOSPI holds 5,500 despite ₩1tn foreign selling | Financial Post Korea
- Japan, South Korea Stocks Close Mixed: Kospi Bounces From Lows | TradingKey
- Hang Seng Closes Up 0.84% as Hong Kong and Mainland Rally Together | 24/7 Wall St.
- investingLive Asia-Pacific market news: Asian stocks slide as chip rout spreads | investingLive
- Stock Market Today: Futures Head Lower at End of Wild Week as Oil Prices Rise Further | Yahoo Finance
- Nasdaq Futures Rise After Chip Selloff While S&P 500, Dow Track Mixed Open | Yahoo Finance
- Stock market today: Dow, S&P 500, Nasdaq futures slip after sharp tech sell-off | Yahoo Finance
- Oil tops $114 as European shares fall and Kering tumbles | Euronews
- STOXX 600 extends fall as Kering slumps, oil climbs | Reuters via Yahoo Finance
- Fed October Rate Hold Odds at 83.9%, December Hike Expected | Phemex
- Fed Rate Odds Today: 86% Hold, 13% Hike at the Oct 28 FOMC | Prediction Markets Picks
Market Analyst · This brief does not recommend buying or selling individual stocks. It covers macro trends and interpretation.
📌 More market briefs
※ This post is market observation and organization intended to support your own judgment. It is not a recommendation to buy or sell any security. Figures are as of the time of writing and may differ between sources.
If this was useful, bookmark it or pass it along. It genuinely helps me write the next one.
I can survive. We can survive.