October 28, 2026 US Market Brief — Nasdaq and S&P 500 Before the Open
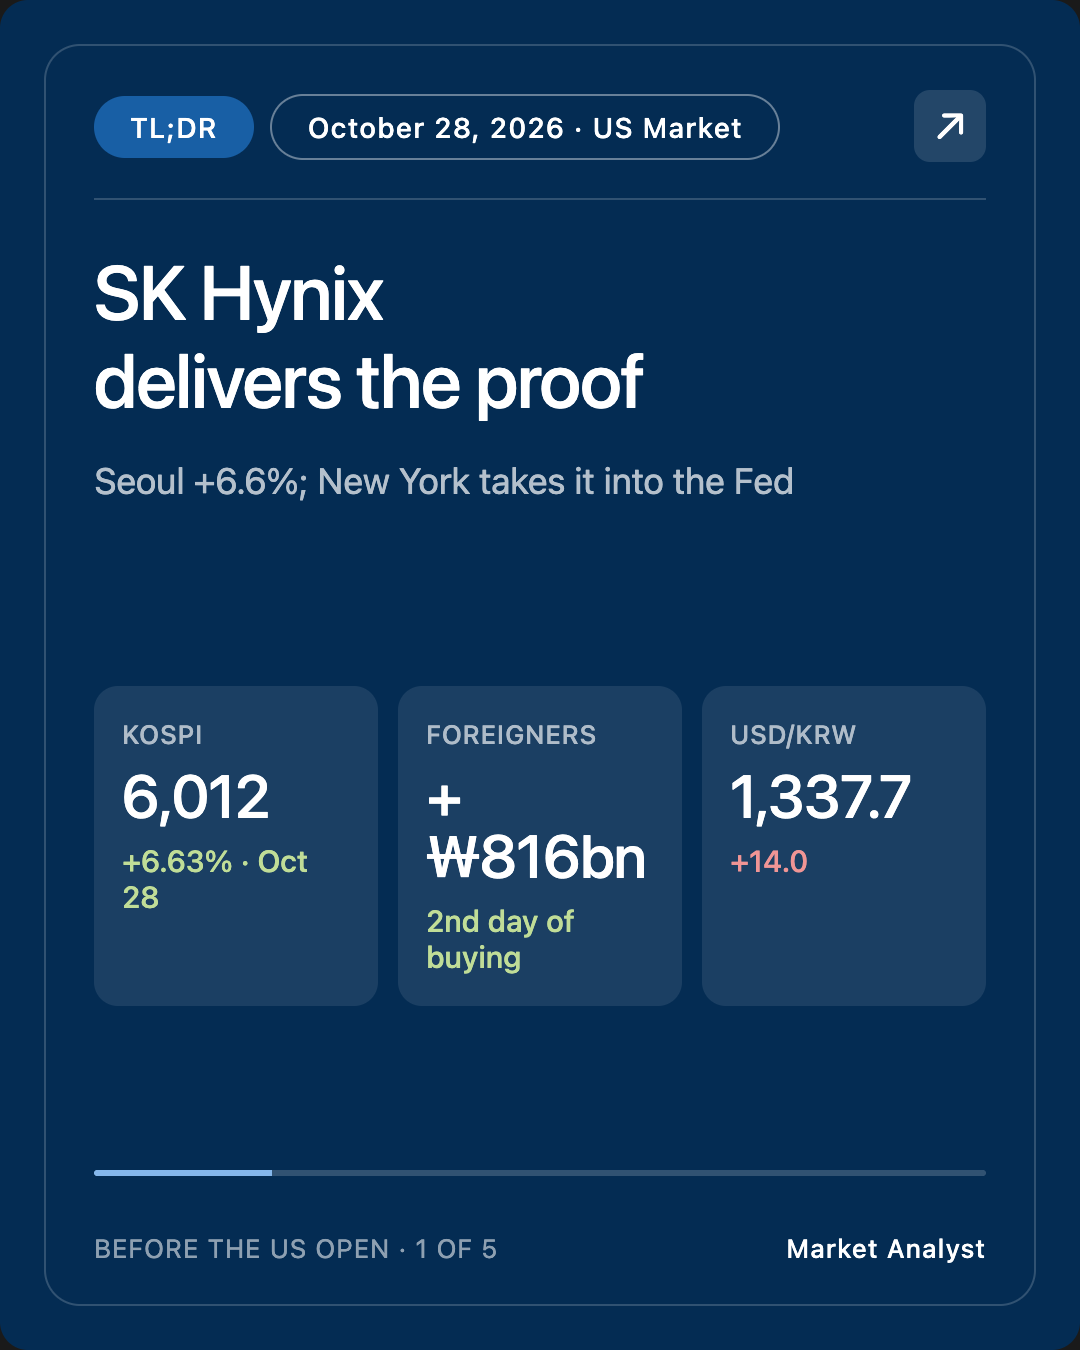
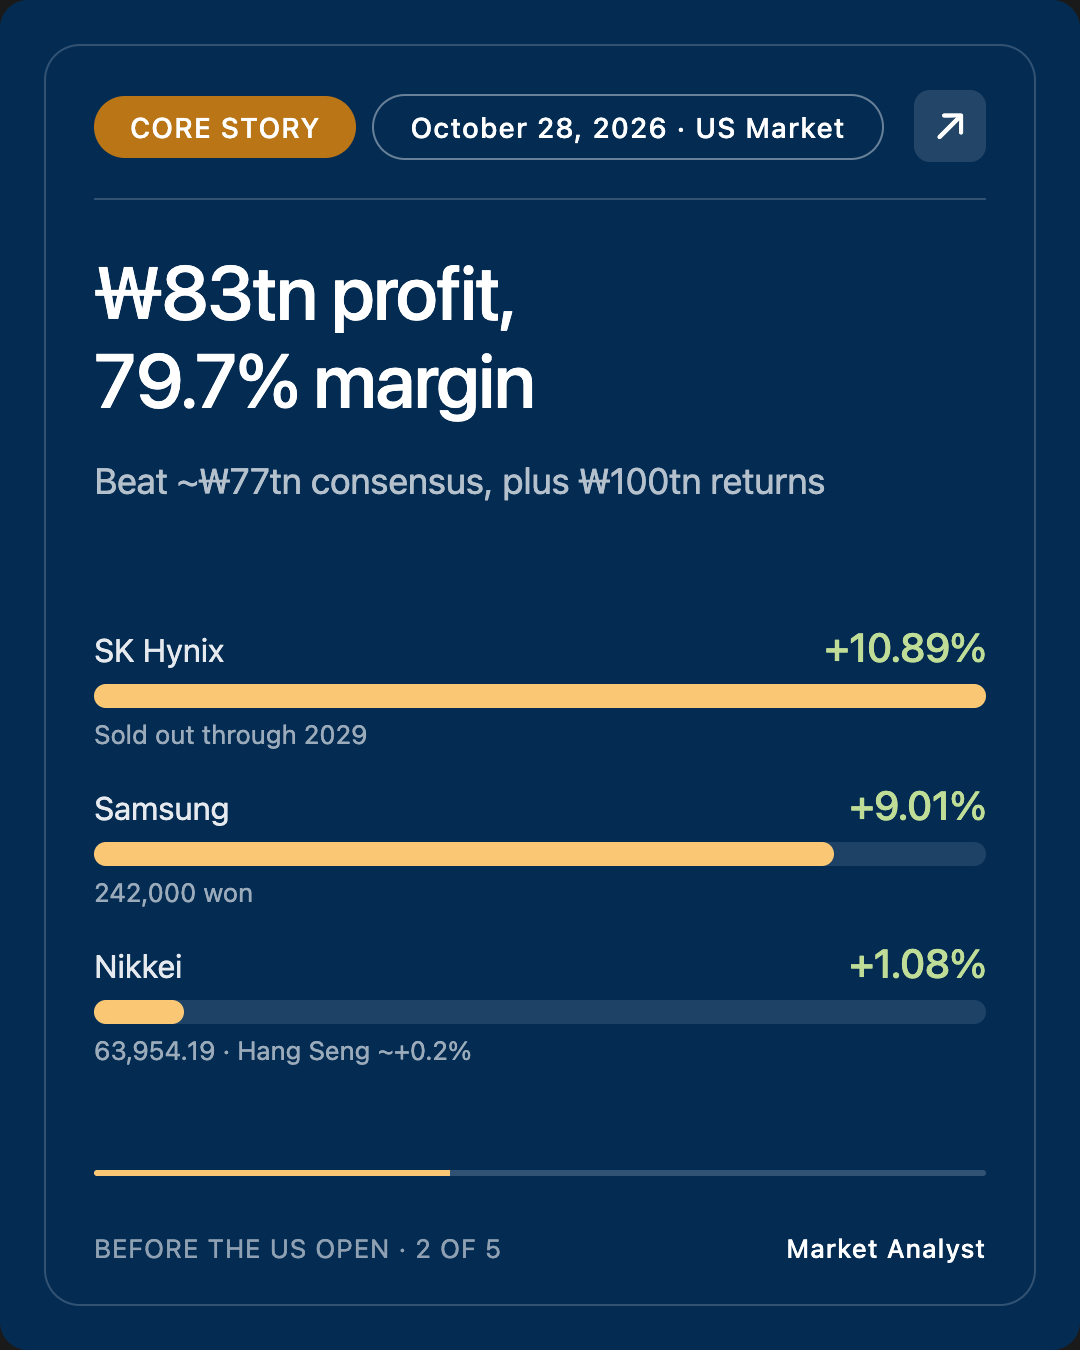
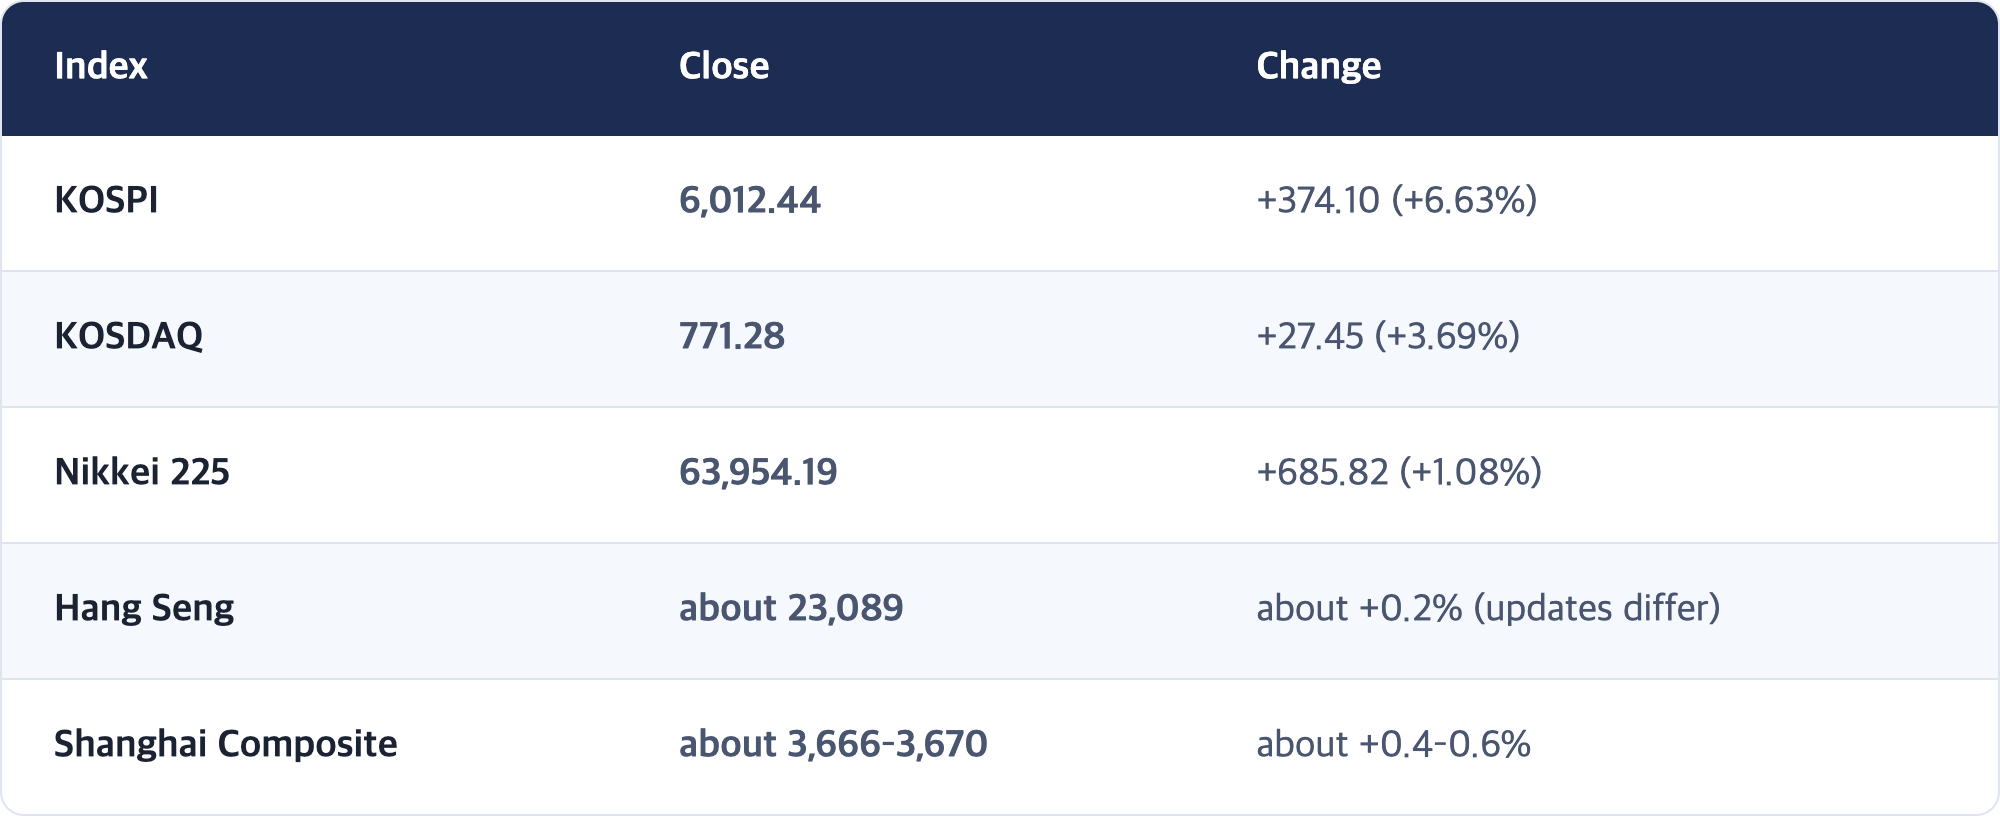
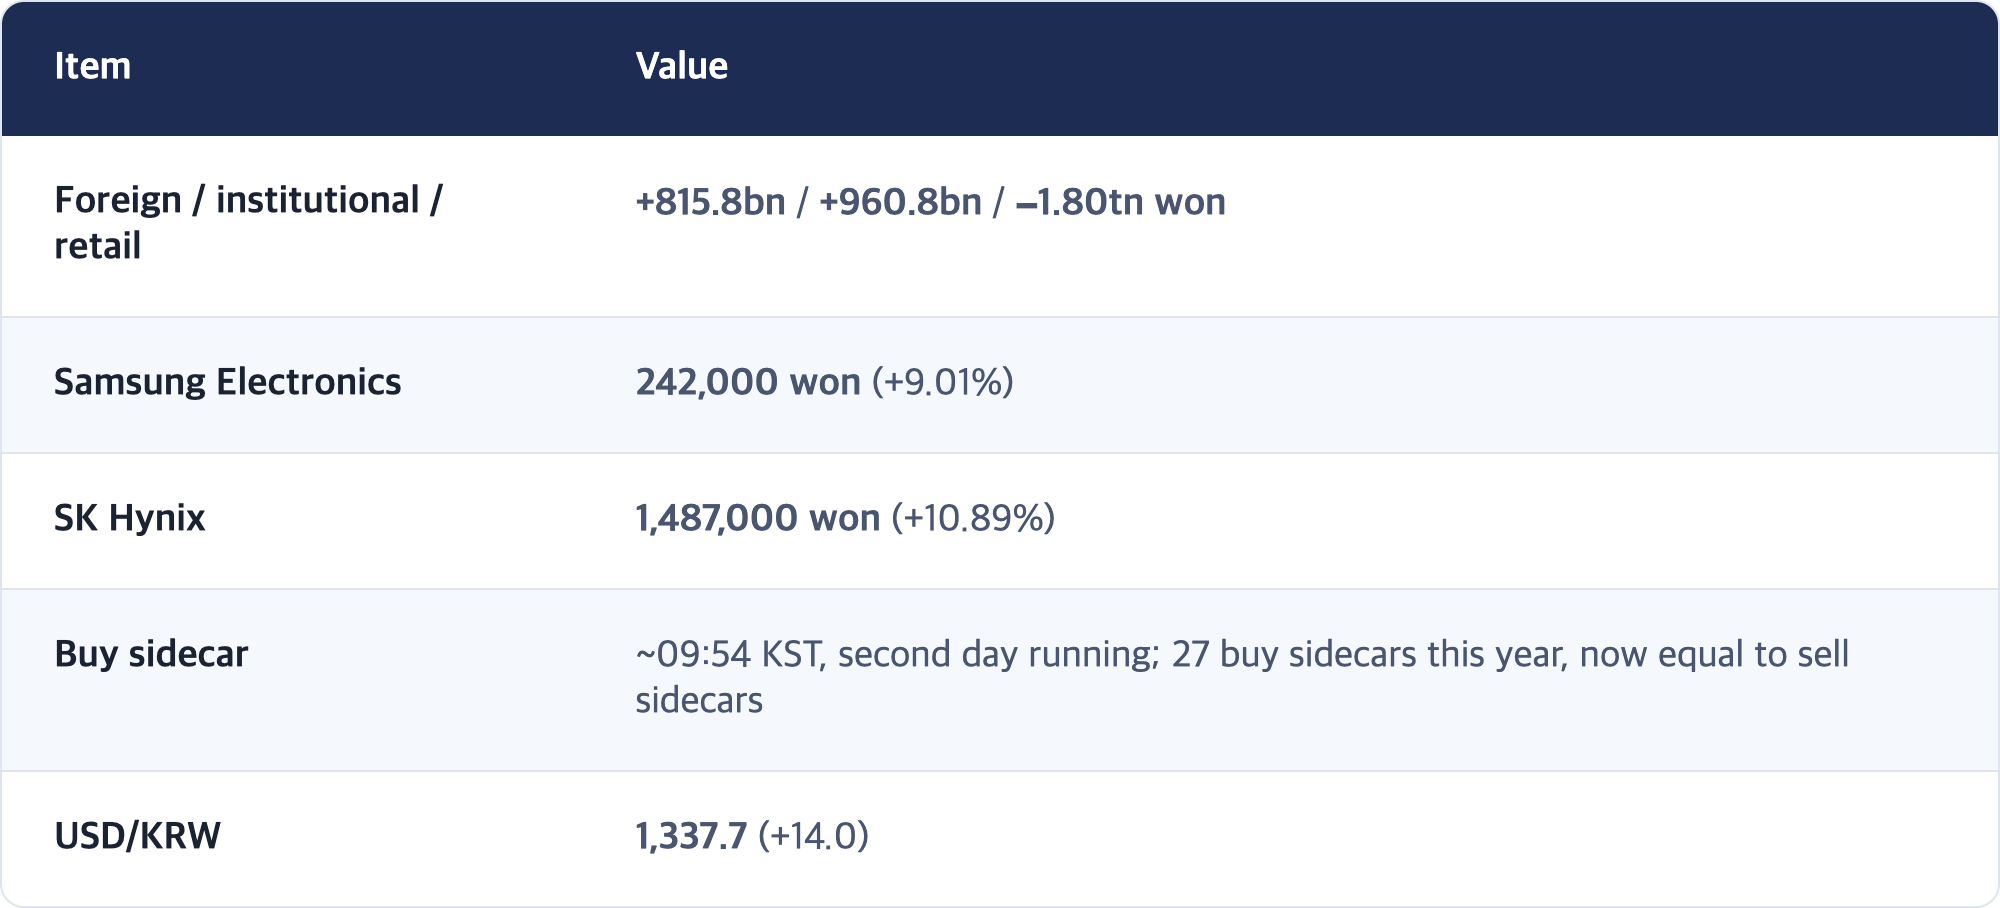
Seoul answered SK Hynix's earnings in a big way on Wednesday. The KOSPI jumped 6.63% to 6,012.44, reclaiming 6,000 for the first time in ten sessions and triggering a buy-side circuit pause ("sidecar") for a second straight day. SK Hynix, the world's leading supplier of high-bandwidth memory (HBM) for AI chips, reported third-quarter operating profit of 83.33 trillion won (about $62.7 billion) at a 79.7% margin, and laid out roughly 100 trillion won of shareholder returns for the year. The stock rose 10.89%. Foreign investors bought a net 815.8 billion won, institutions 960.8 billion won.
Yet the won weakened to 1,337.7 per dollar (+14.0). Overnight, Yemen's Houthi rebels claimed a missile strike on Saudi Aramco's Ras Tanura refinery, and Brent climbed back to $115–116.
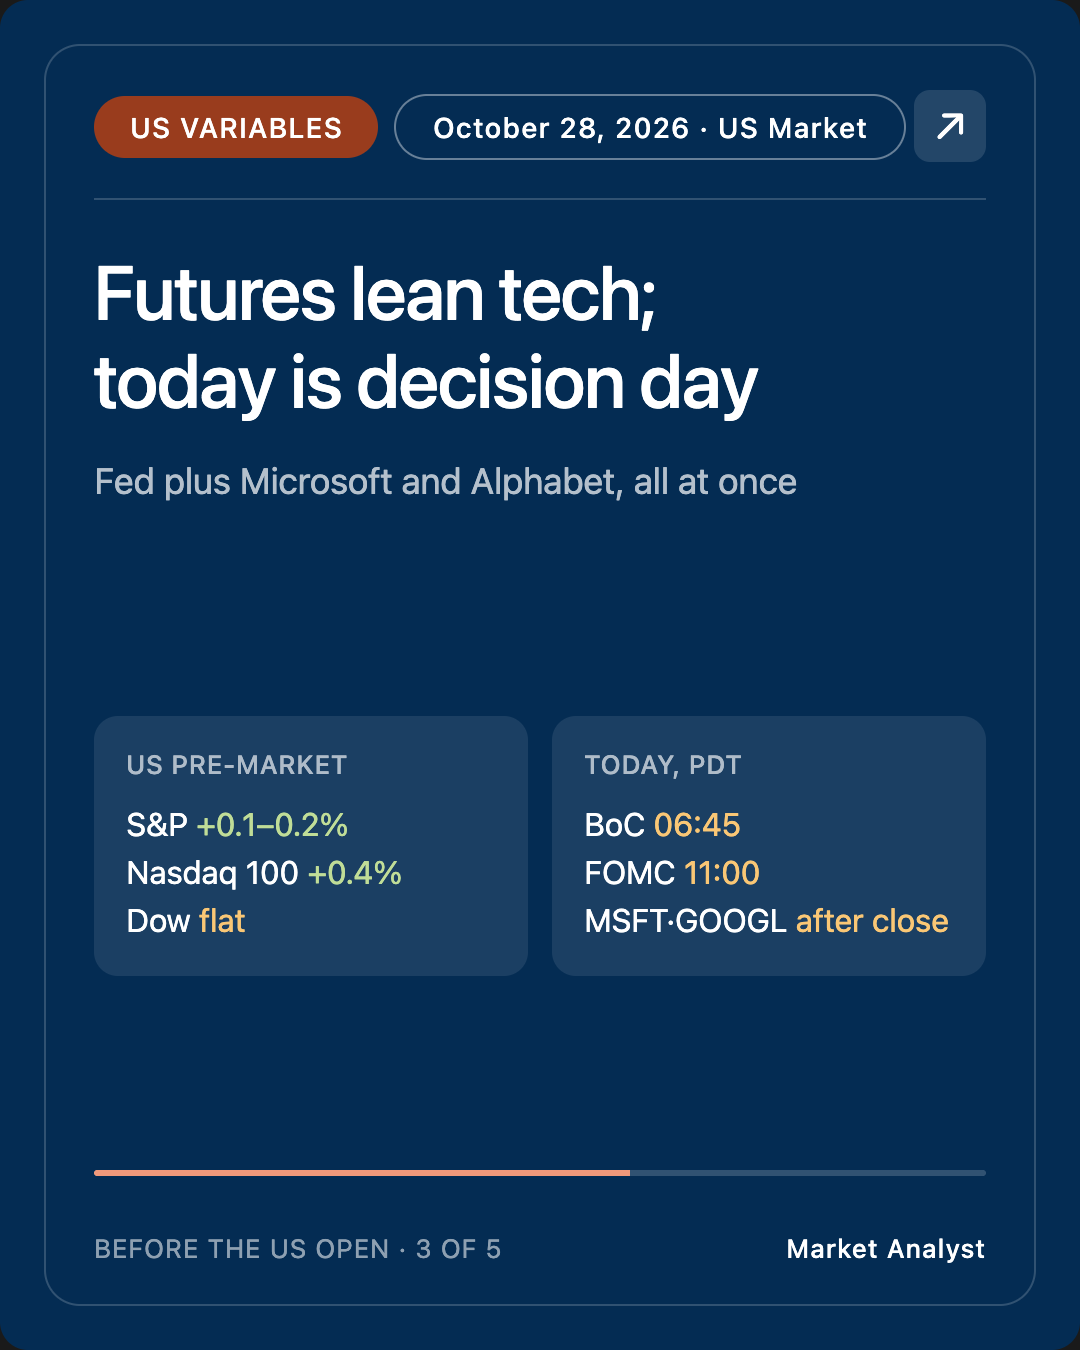
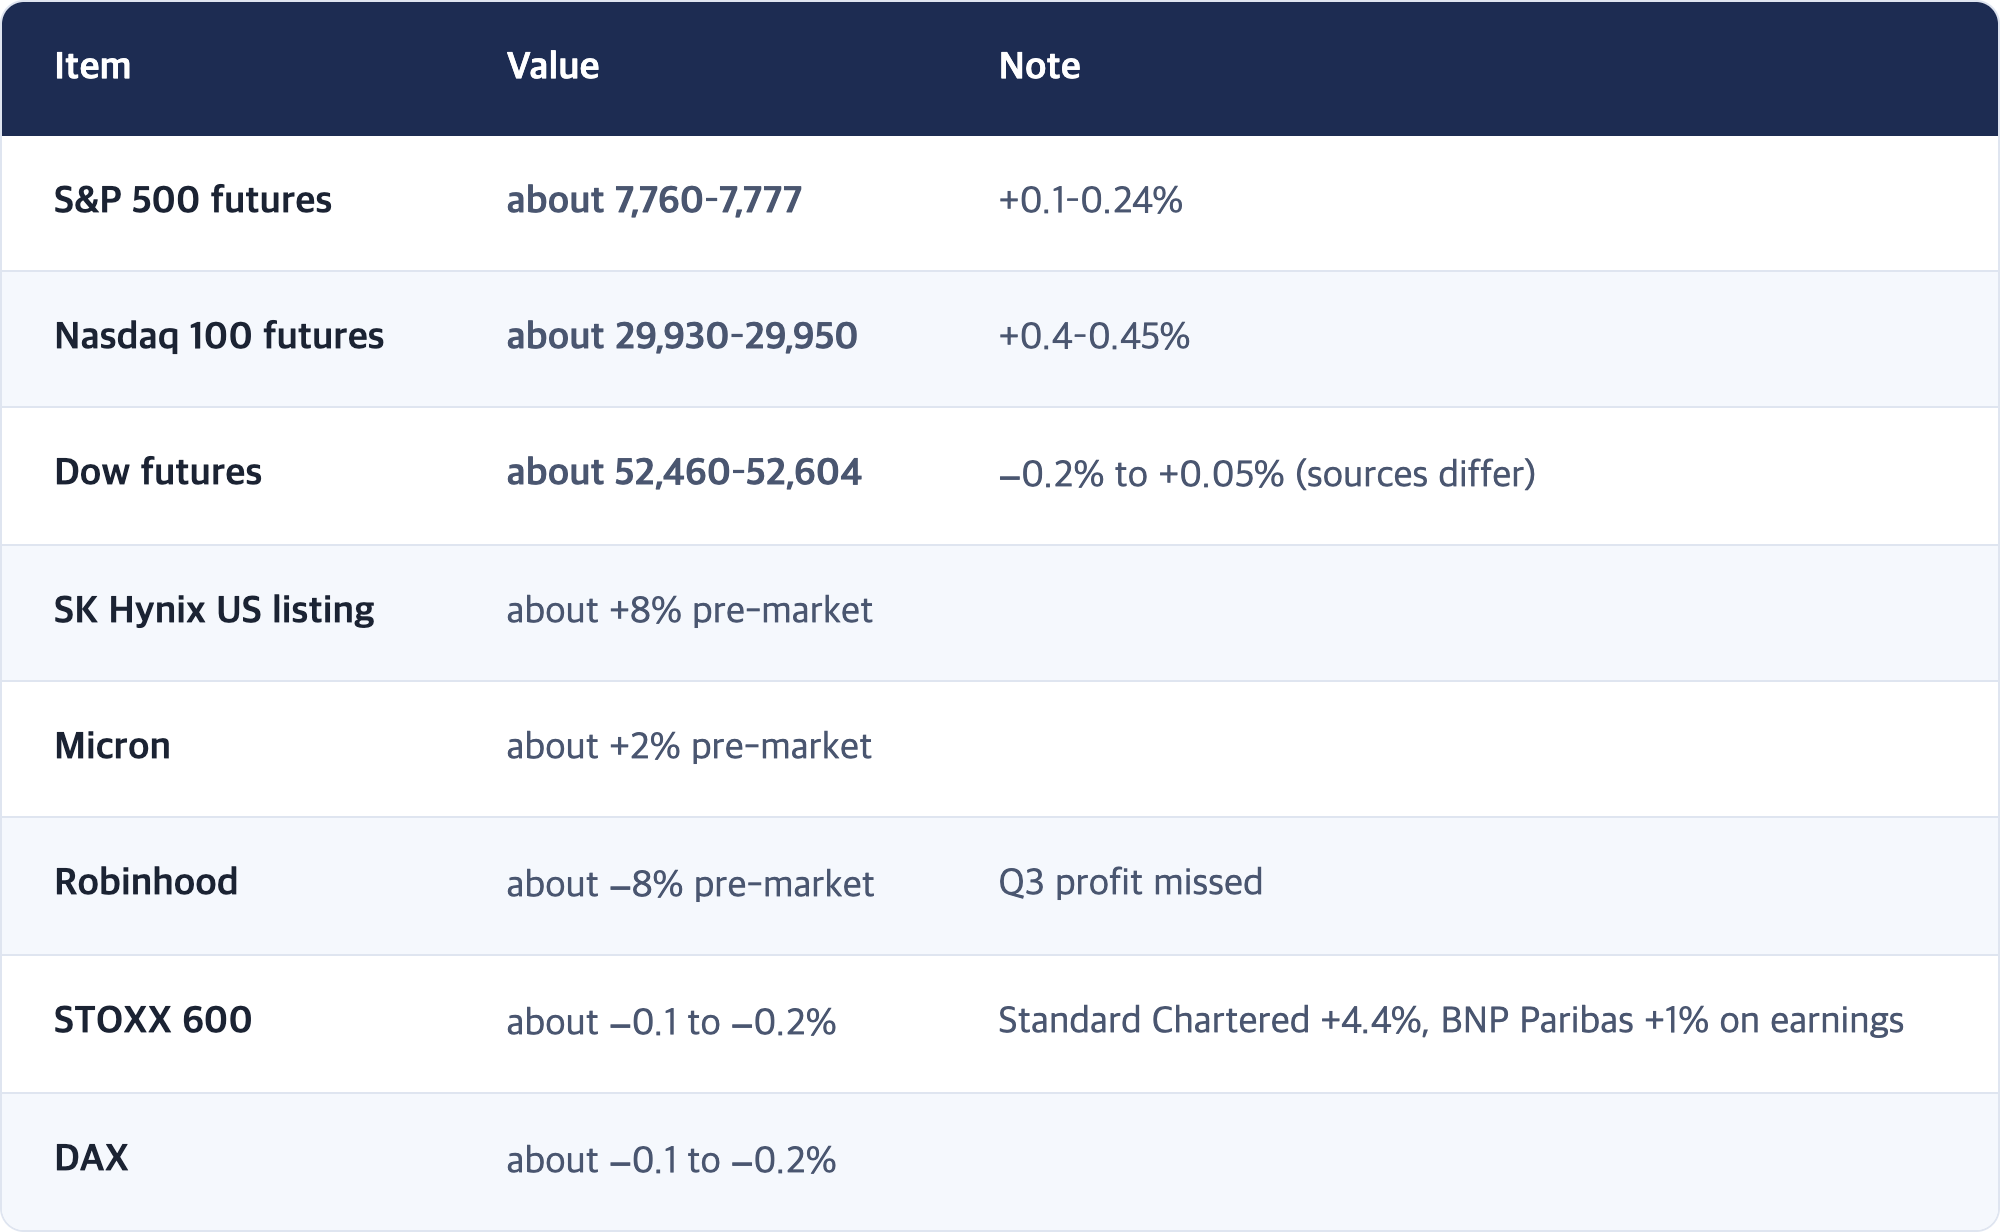
US futures lean toward tech: Nasdaq 100 about +0.4%, the Dow roughly flat. Today stacks the Fed decision (11:00 PDT) on top of Microsoft and Alphabet earnings after the bell. The question for Wall Street: does it pick up the AI-memory numbers Seoul just confirmed, or do a "hawkish hold" from Chair Kevin Warsh and pricier oil smother them?
This is Mr. Can. Here is the October 28, 2026 brief ahead of the US market open.
Written: 2026-10-28 05:48 PDT (Korea 10/28 21:48 KST) · Work started 05:43 PDT
Based on: Korea, Japan, Hong Kong and China closes on Oct 28 + Europe intraday + US pre-market + overnight Treasuries
🔴 Scheduled for 05:30 PDT; work began at 05:43 PDT. This goes out around the US open (06:30 PDT), so all US figures are pre-market.
🟡 Hang Seng figures differ even between updates of the same AP story (see section 6). We could not source the dollar index or Korea's 10-year government bond yield.
⚡ TL;DR
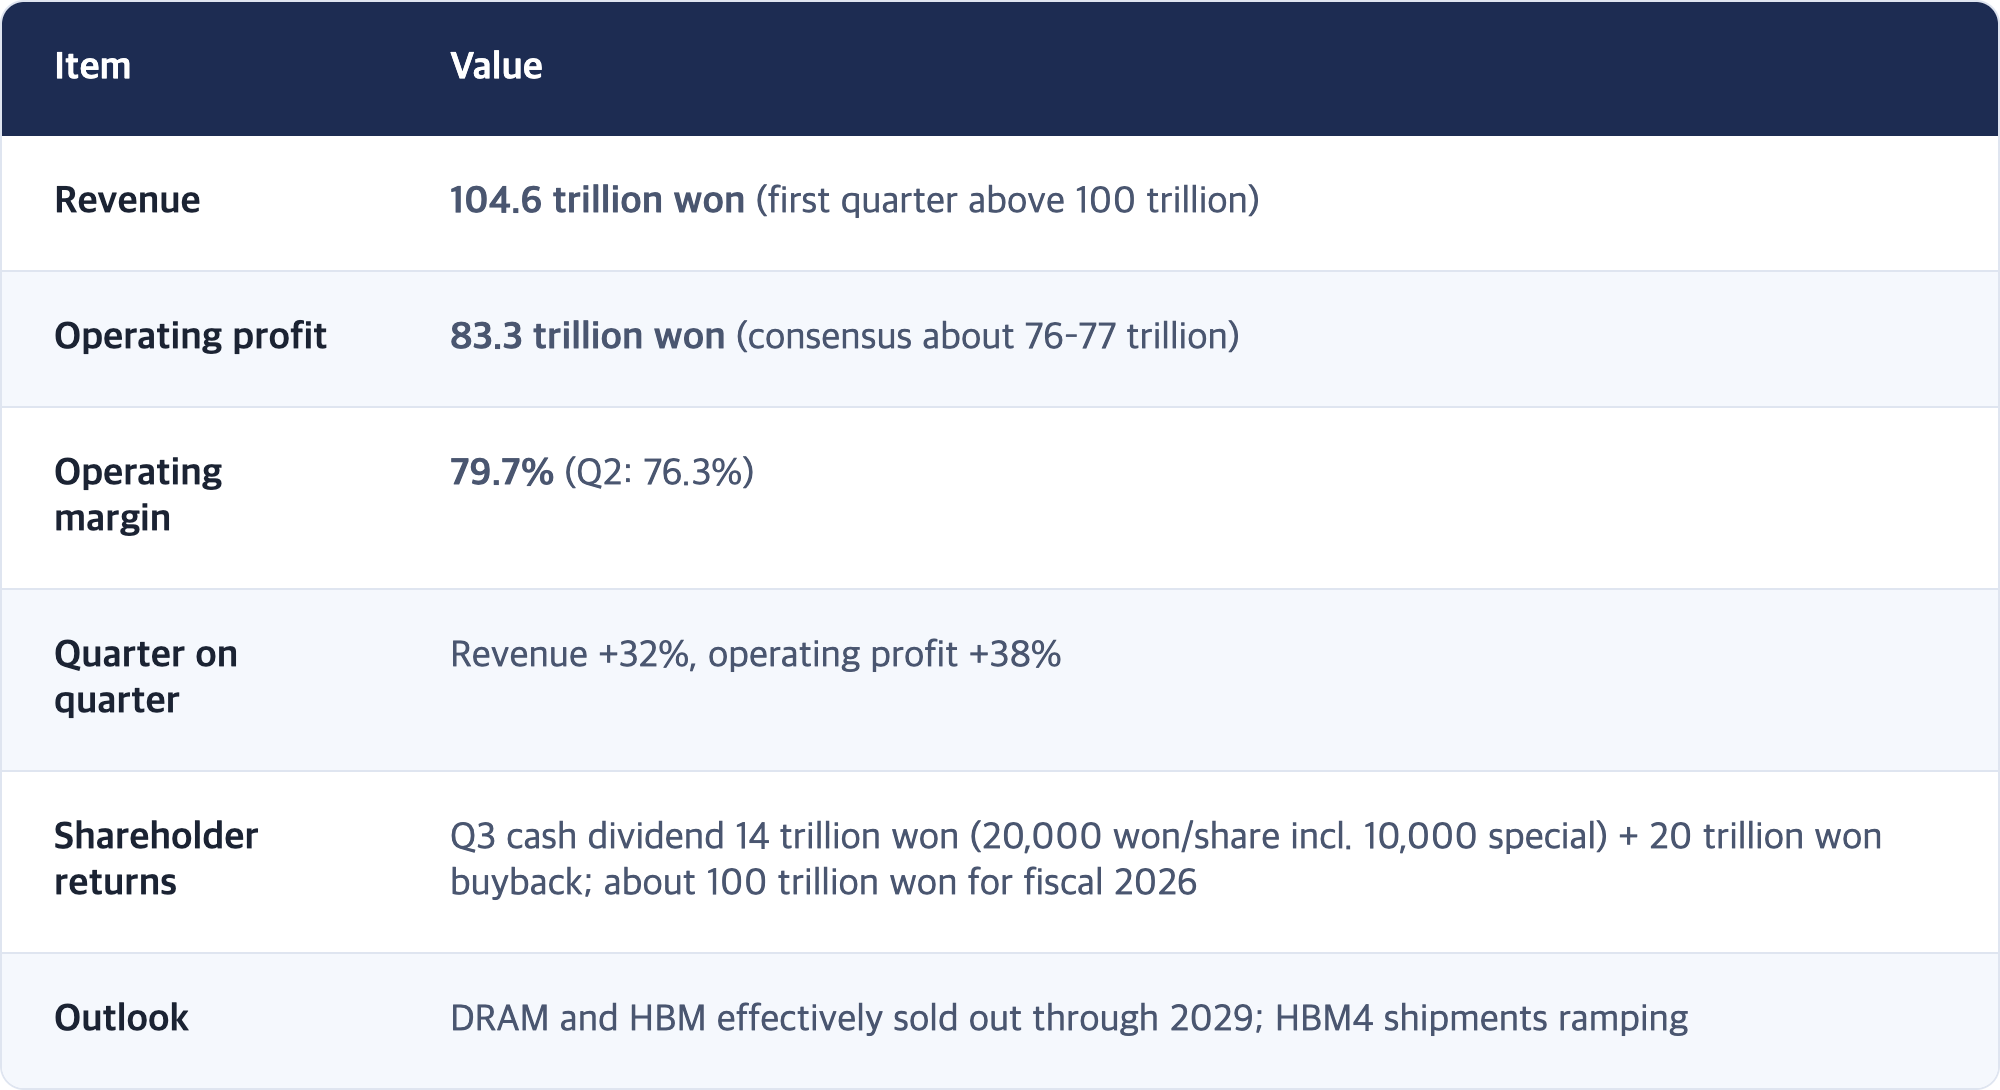
- ★ SK Hynix delivered the proof. Q3 revenue 104.6 trillion won, operating profit 83.3 trillion won (vs. consensus near 77 trillion), margin 79.7%. DRAM and HBM supply effectively sold out through 2029. Q3 dividend of 14 trillion won (20,000 won a share, including a 10,000-won special) plus a 20-trillion-won buyback; about 100 trillion won of total returns for fiscal 2026.
- ★ Seoul erupted. KOSPI 6,012.44 (+6.63%); Samsung Electronics +9.01%, SK Hynix +10.89%. Foreigners +815.8bn won (second straight day of buying), institutions +960.8bn, retail −1.80 trillion won.
- But the won slipped. USD/KRW 1,337.7 (+14.0). Equity inflows and a weaker currency on the same day point to oil and pre-Fed caution (our interpretation).
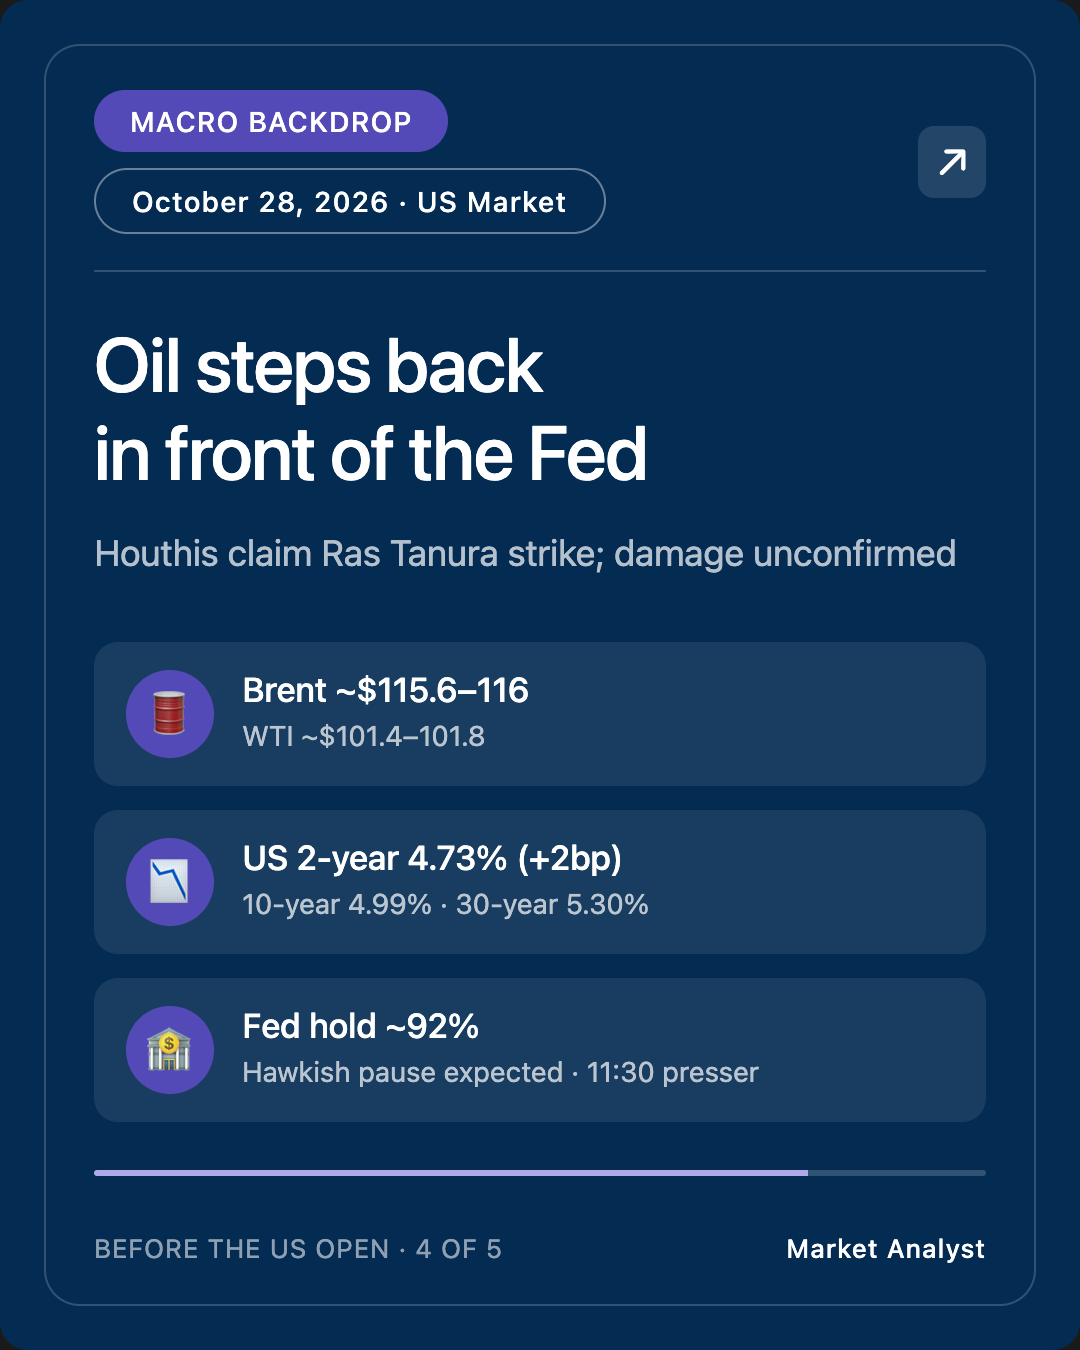
- Oil is back up. The Houthi claim on Ras Tanura (damage unconfirmed) lifted Brent to about $115.6–116 and WTI to about $101.4–101.8, undoing Tuesday's dip below $100.
- Three events land on one day in the US. FOMC decision 11:00 PDT (hold priced at about 92%), Bank of Canada at 06:45 PDT, Microsoft and Alphabet after the close. Futures: Nasdaq 100 +0.4%, S&P +0.1–0.2%, Dow flat to −0.2%. 10-year Treasury 4.99%.
1. Scoring Yesterday's Checkpoints
The four set by the Oct 27 PM brief (Seoul close, Oct 28)
The axis was: does SK Hynix's report extend foreign buying to a second day, or does "sell the news" take over once the numbers are out? The third-variable slot was pre-Fed paralysis (thin trading).
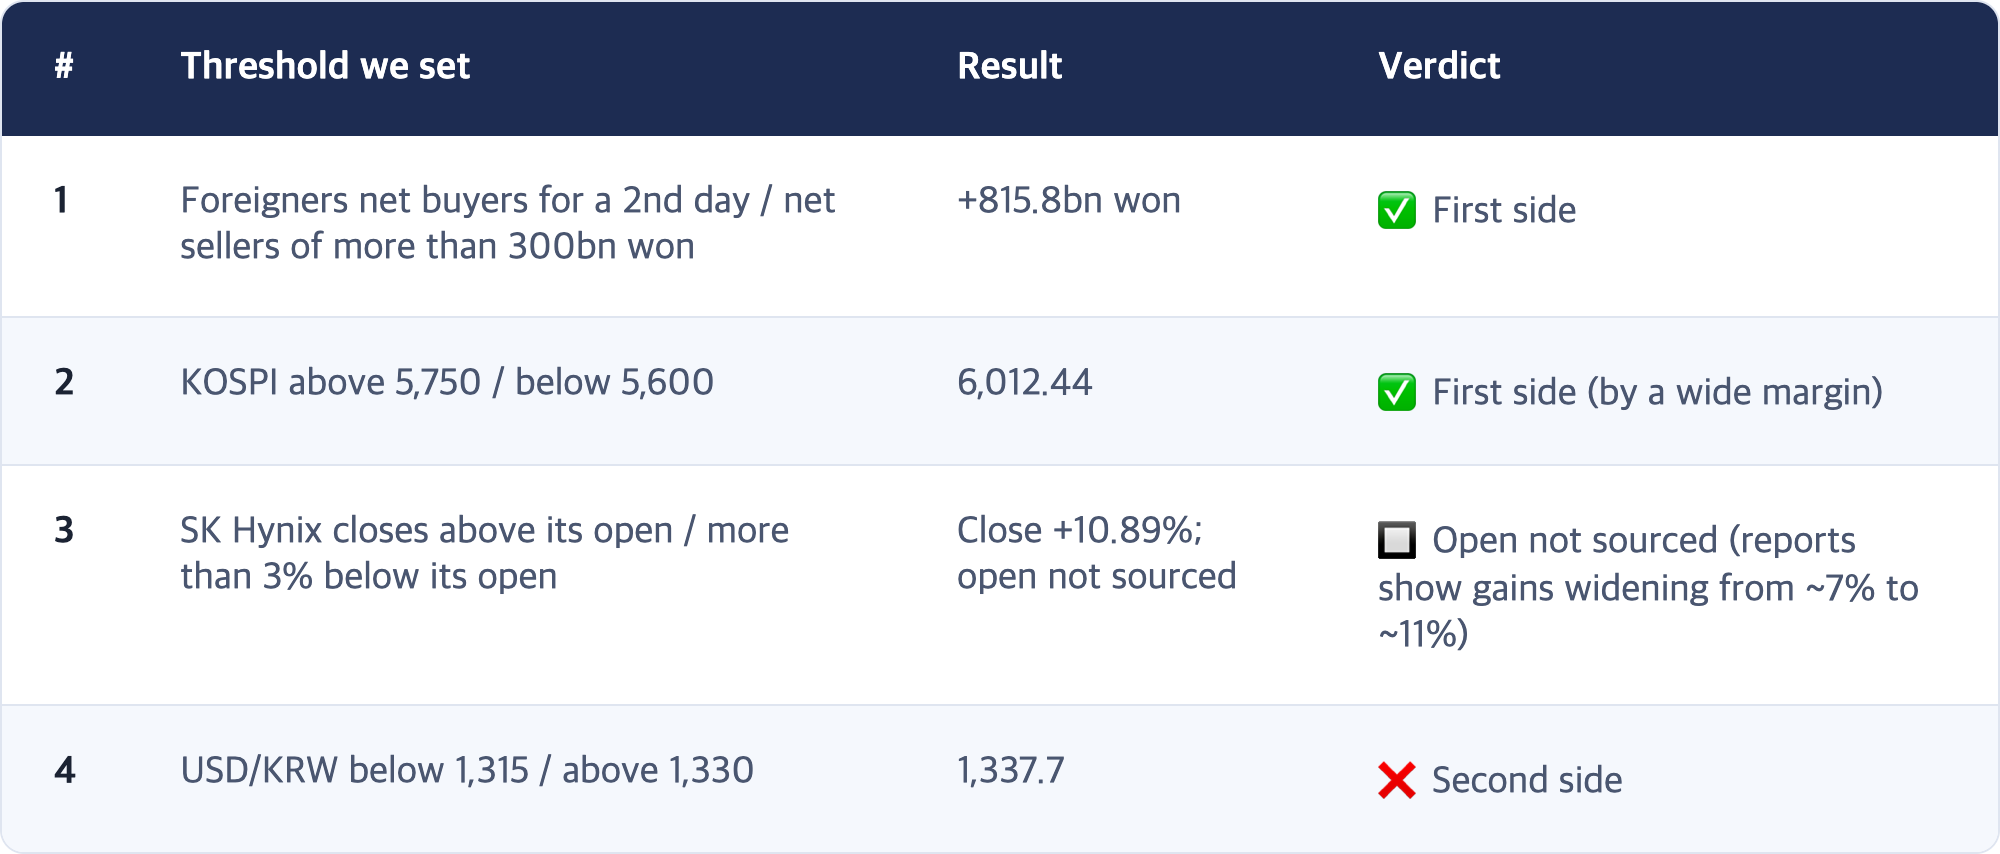
Third variable: the paralysis never came. Instead oil (Ras Tanura) arrived from outside the axis, and it showed up in the currency, not in stocks.
★ [Interpretation] Stocks and the currency gave different answers
Checkpoints 1 and 2 landed cleanly on the first side. There was no "sell the news." Checkpoint 4 went the other way: foreigners bought more than 800 billion won of stock for a second day, and the won still lost 14.
Two readings fit. (1) Brent back above $115 lifted dollar demand for import bills and general risk caution. (2) With the Fed a day away, hedging into dollars picked up. Today's data cannot separate them. What is clear is a pattern we have flagged before: on the same headline, different assets can price different realities. Stocks bought the earnings; the currency kept the oil.
2. Today's Core: Seoul Confirmed the "AI Memory Numbers"
[Fact] SK Hynix Q3 results (released Oct 28, preliminary)
[Fact] Asia closes, Wednesday Oct 28
[Fact] Seoul flows and large caps (main board)
★ [Interpretation] Three numbers in three days
Anthropic's S-1 on Oct 26 said "AI makes money." Broadcom's $63 billion financing on Oct 27 said "there's money to buy AI chips." SK Hynix on Oct 28 said "that money is now showing up as memory-maker profit." The "AI spending doubt" that drove this month's chip sell-off got three answers from three different places in three days.
A caution, though. The KOSPI is up about 10% in two sessions, while Korean retail investors sold roughly 3.2 trillion won over the same stretch. A rebound this sharp likely includes short covering. And the fact that buy and sell circuit pauses are now tied for the year says how violently this market swings in both directions.
3. The US Variable: Futures Lean Tech, but Today Is Decision Day
[Fact] US pre-market and Europe (around 05:00 PDT, Oct 28)
[Fact] Today's schedule (PDT)
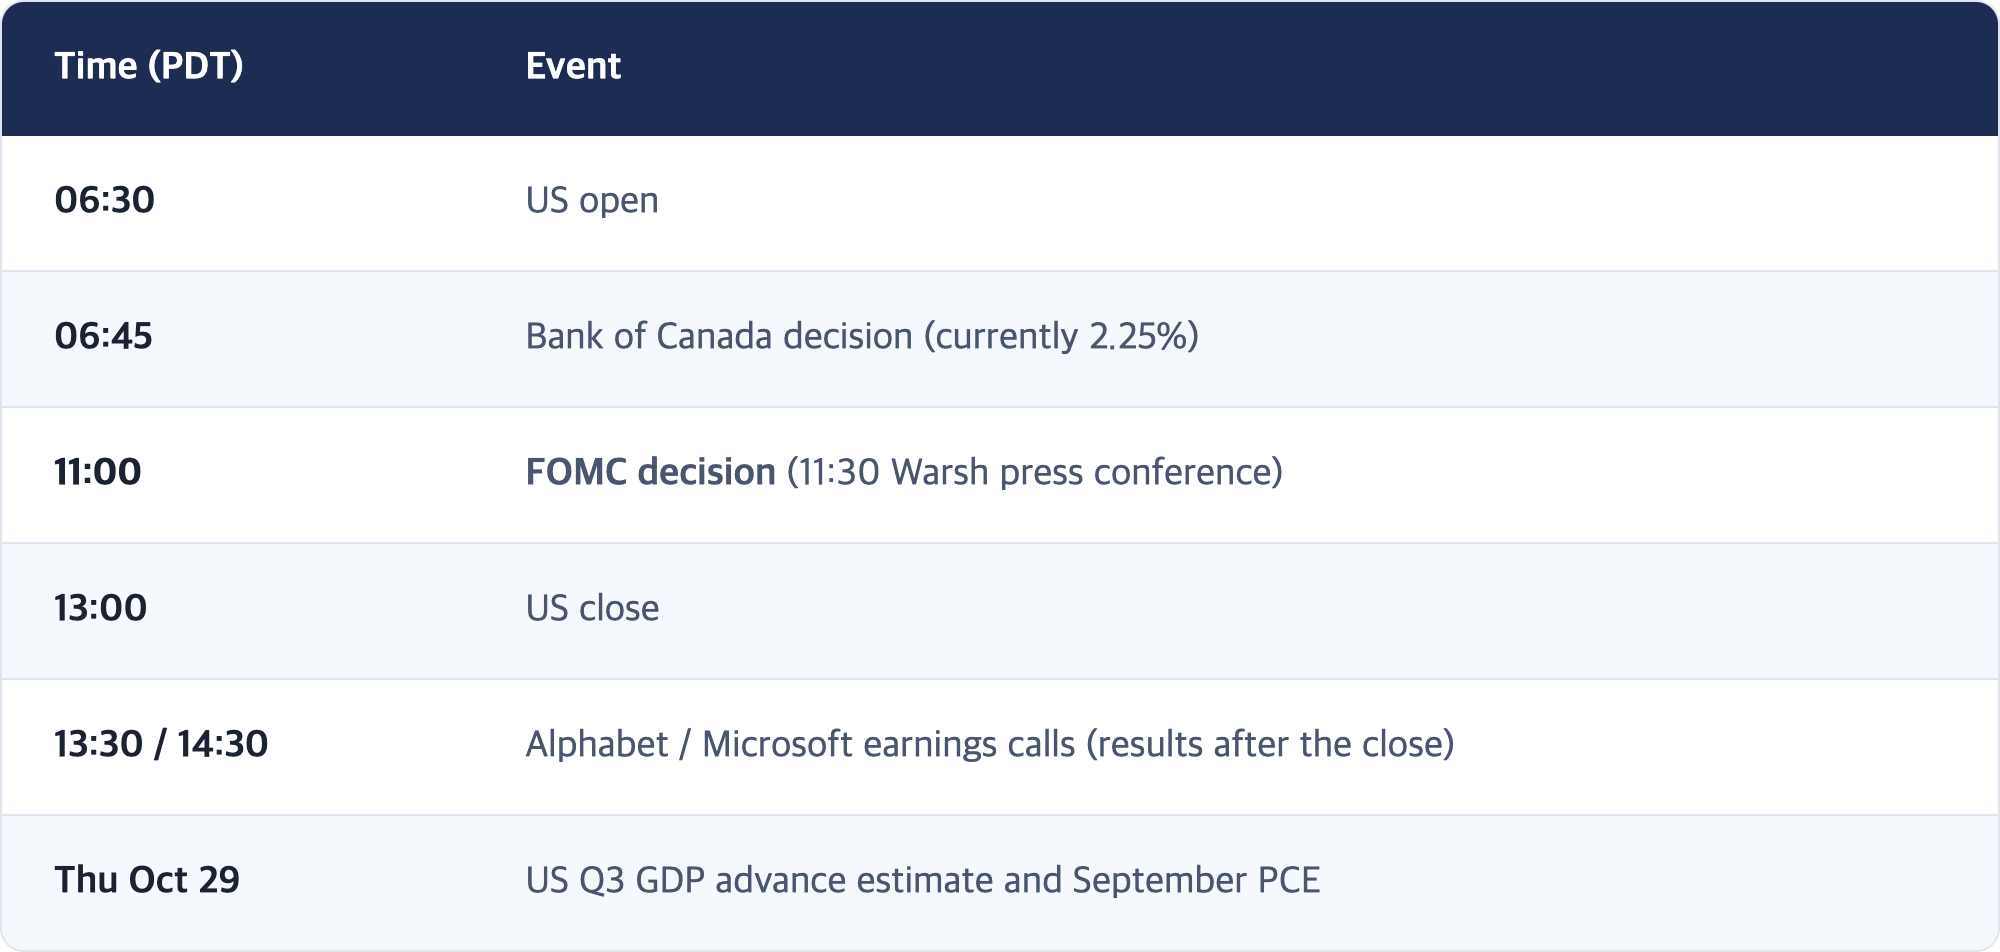
★ [Interpretation] Wall Street already owns half of Seoul's news
SK Hynix's US listing is up about 8% pre-market, but Micron is up only 2% and Nasdaq 100 futures 0.4%. US chips already ran on Tuesday, with the SOX up more than 3%. New York is unlikely to absorb today's news as forcefully as Seoul did; the test is whether early strength survives the afternoon press conference.
Former Fed Vice Chair Alan Blinder expects a "hawkish pause": rates on hold, with the door left open to more hikes. The hold itself is fully priced. How far Warsh's words move the 2-year yield is the real decision this afternoon.
4. Macro Backdrop: Oil Steps Back in Front of the Fed
[Fact]
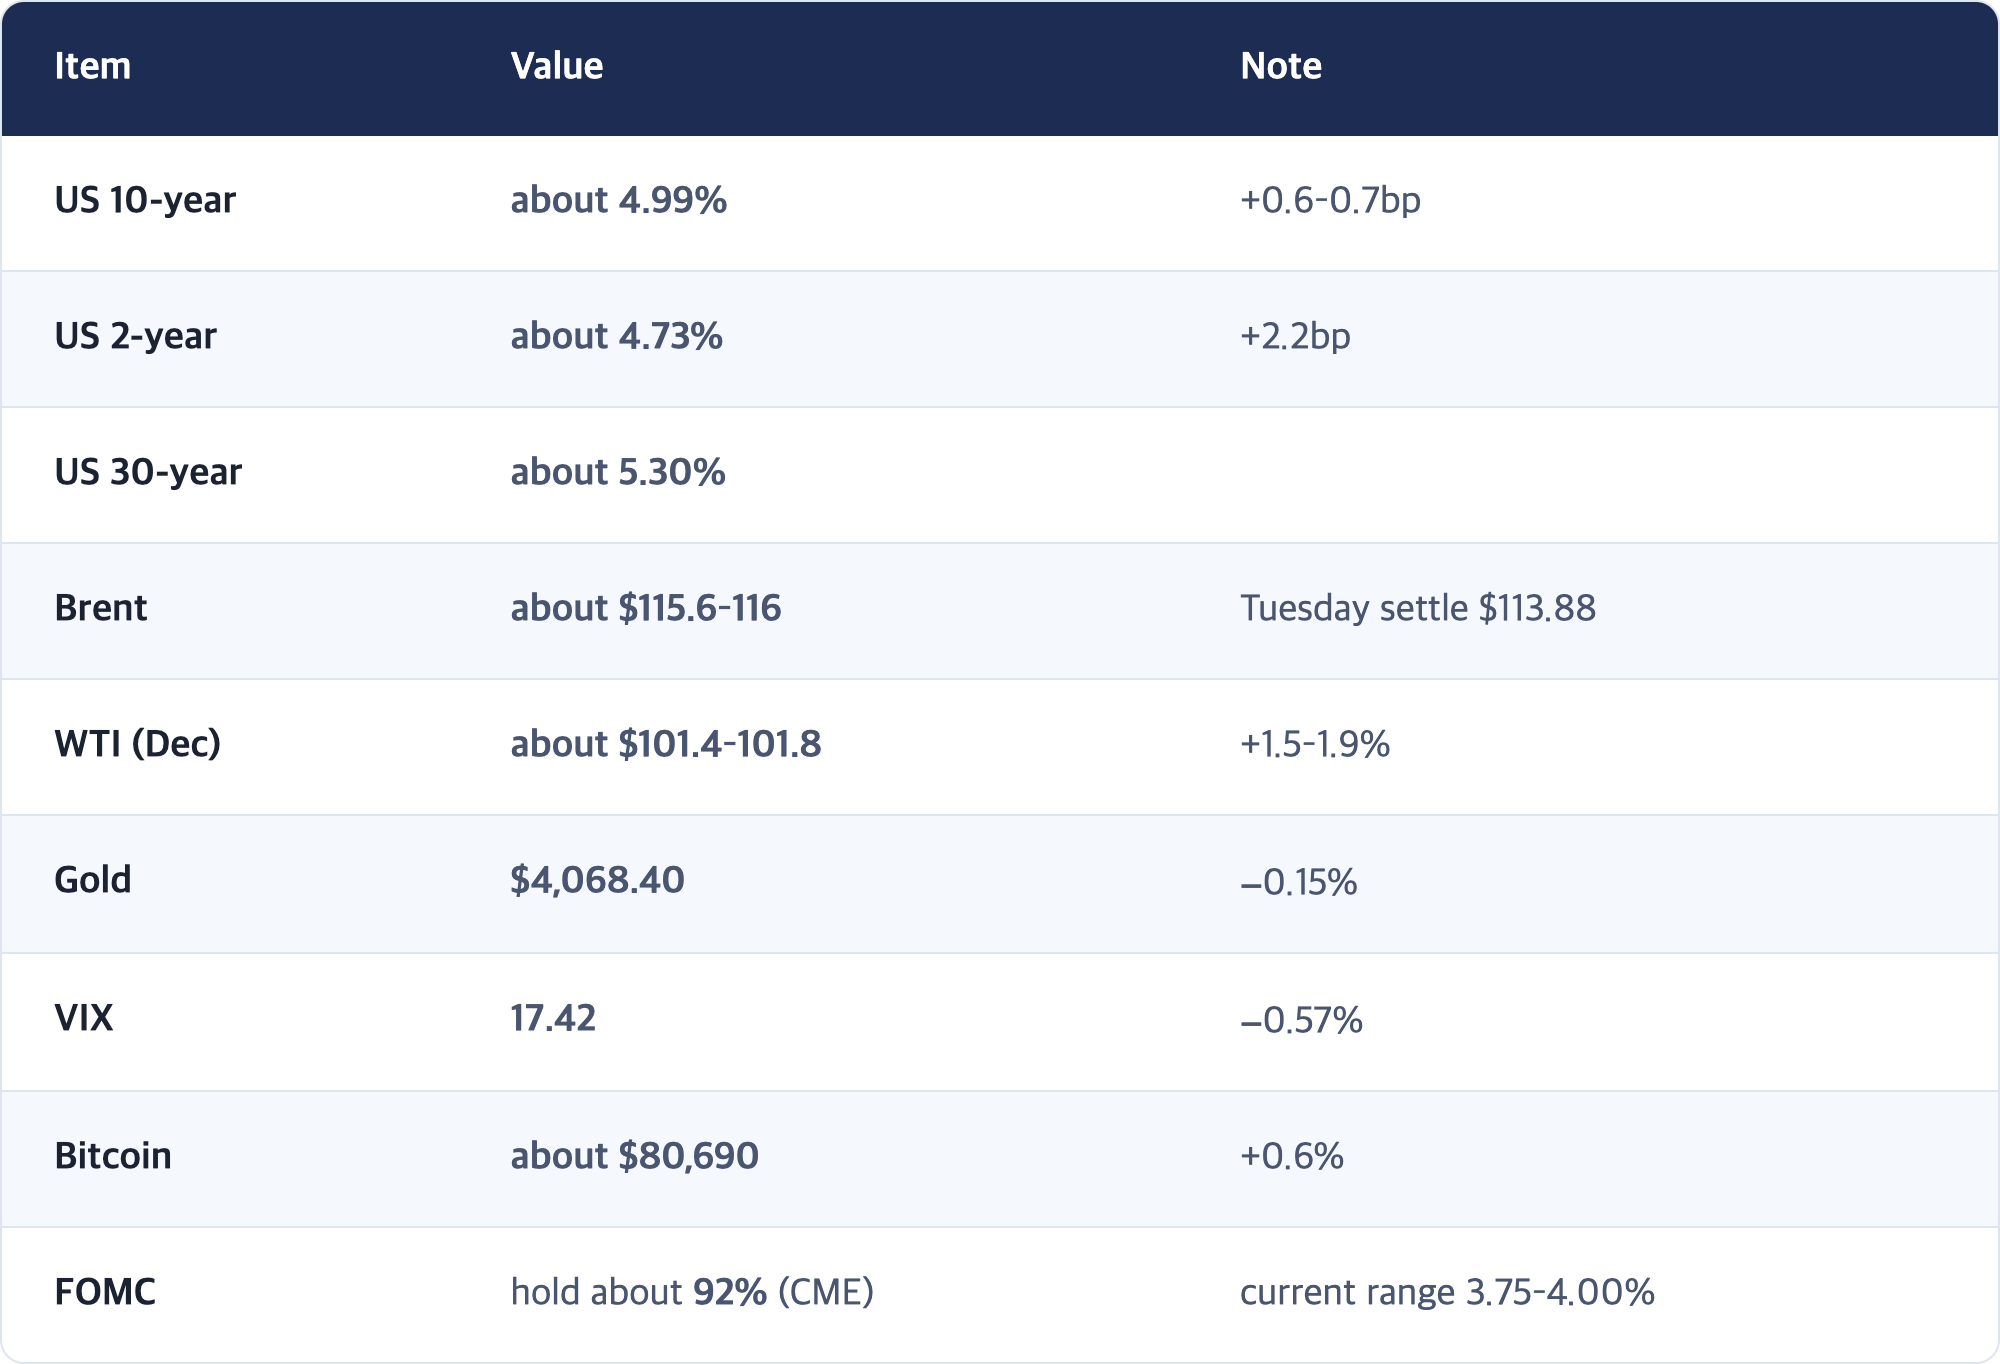
[Fact] The Houthis said on Tuesday they had struck Saudi Aramco's Ras Tanura refinery (about 550,000 barrels a day) with a ballistic missile. Saudi authorities did not immediately confirm damage; a fire was contained, and the Saudi-led coalition said it intercepted three missiles. Accounts of the damage vary.
★ [Interpretation] The Fed gets strong consumers and expensive oil at once
Tuesday's surprise jump in consumer confidence (91.7) is now joined by Brent back above $115. Both make it harder for the Fed to say the hiking cycle is over, and the 2-year's 2bp rise today points the same way.
One analysis put it well: claims against Saudi energy sites move oil for a session; confirmed damage moves it for a week. Whether Riyadh confirms damage is likely to set Brent's next leg.
5. Today's US Session: Checkpoints
✅ Four checkpoints (through today's US close)
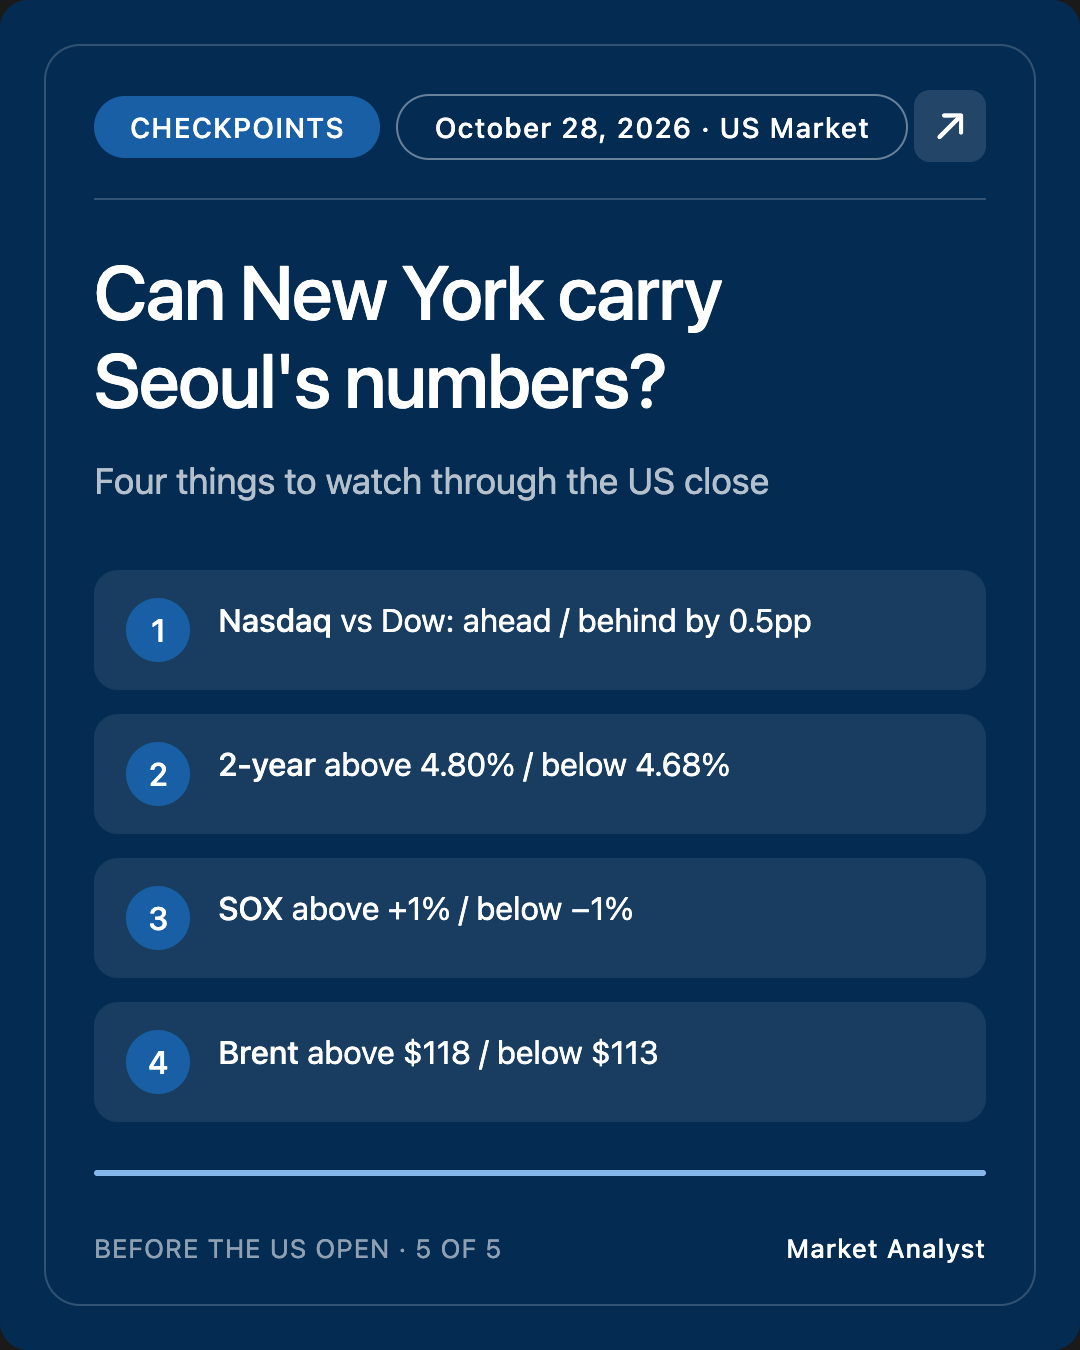
Axis: does New York carry forward the AI-memory earnings Seoul confirmed, or does a hawkish-hold press conference smother them? Third-variable slot: whether damage at Ras Tanura is confirmed (oil). Microsoft and Alphabet report after the close, so they are not part of this scorecard.
- Nasdaq beats the Dow by more than 0.5pp / trails it. (Most important) Pre-market gap is about 0.4–0.6pp.
- US 2-year above 4.80% / below 4.68%. Now 4.73%. Tells us which door the press conference opened.
- SOX above +1% / below −1%.
- Brent above $118 / below $113. Now about $115.6–116.
[Interpretation] If 1 and 3 land on the first side and the 2-year stays below 4.80%, the earnings story outran the Fed, and Seoul meets Samsung's results tomorrow on firmer footing. If the 2-year pushes above 4.80%, the "hawkish hold" has been priced, and a KOSPI that rose 10% in two days may be the first to wobble.
6. Corrections and Open Items
Corrections
- None. The Oct 27 PM brief left SK Hynix's release time unconfirmed; results came out during Seoul trading on Oct 28 (exact time not sourced).
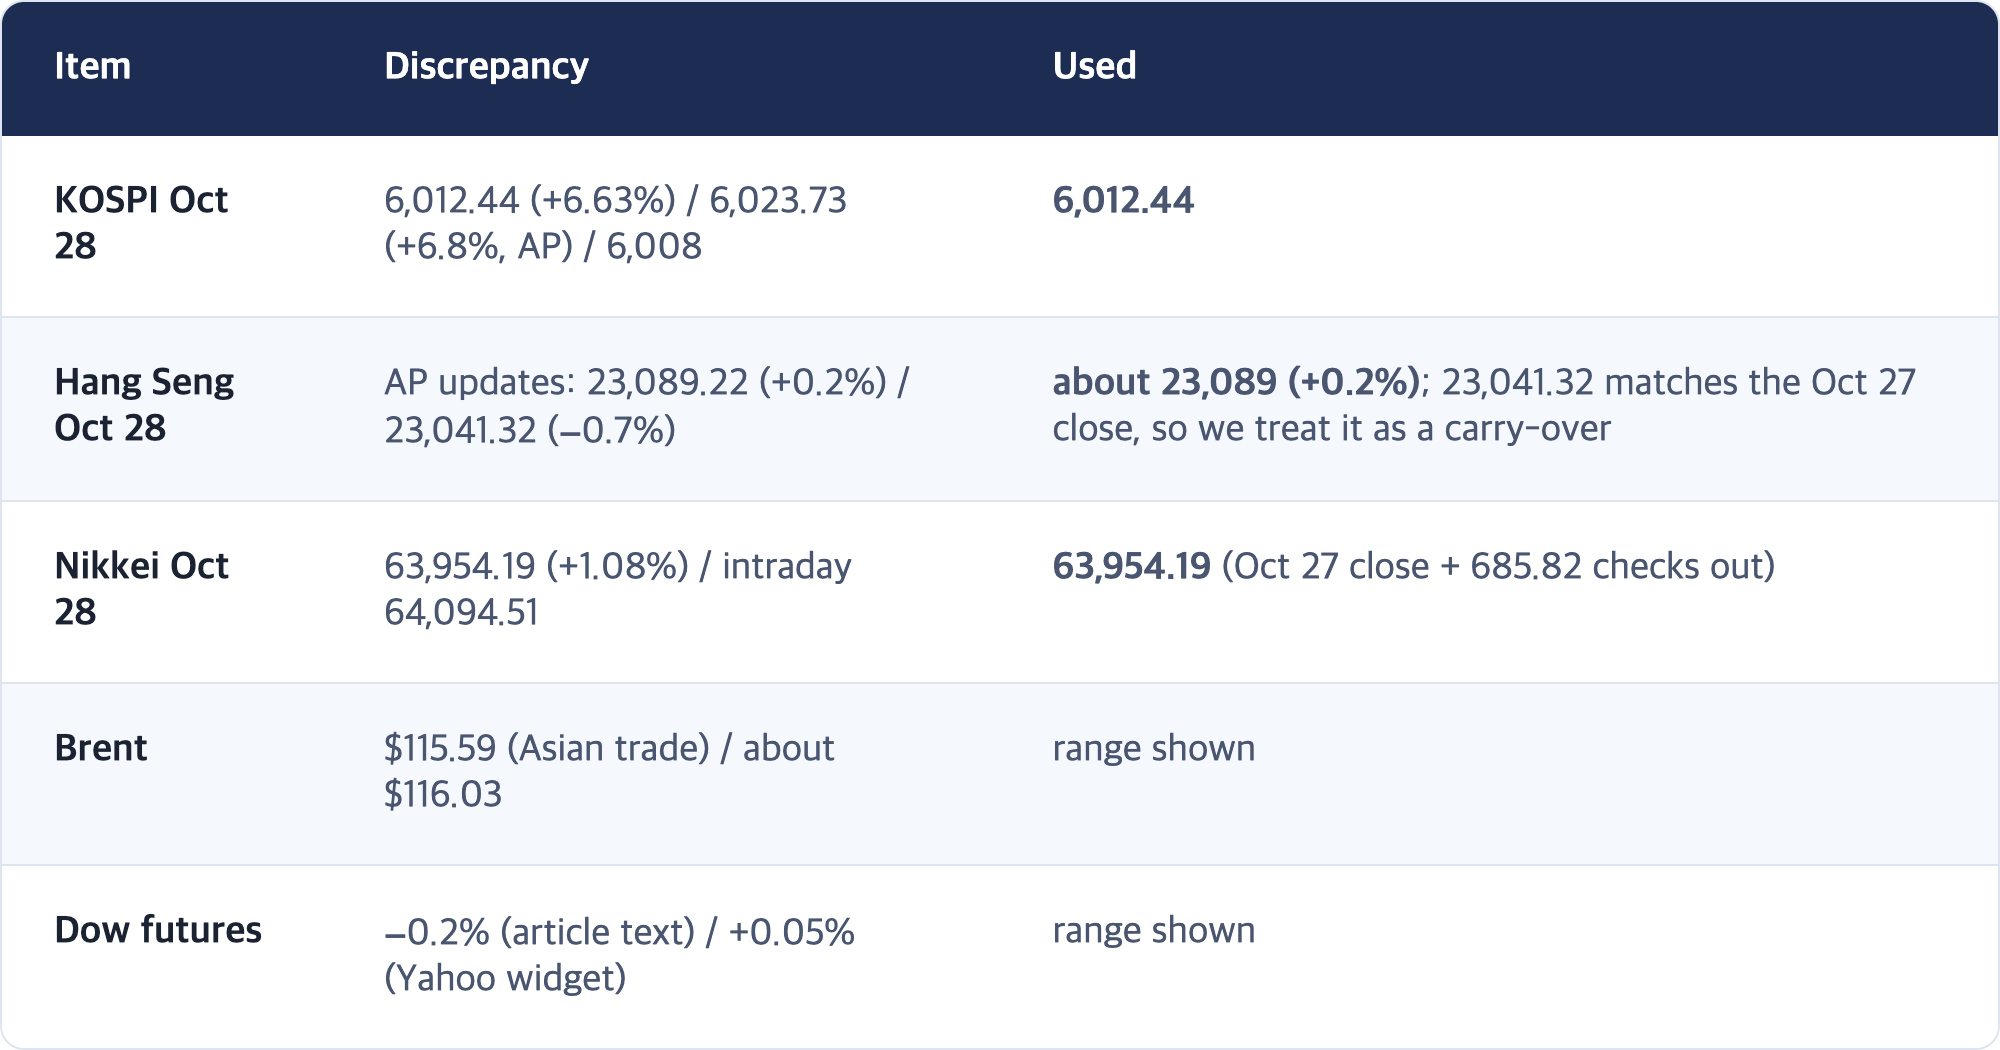
Source discrepancies (value used in this brief)
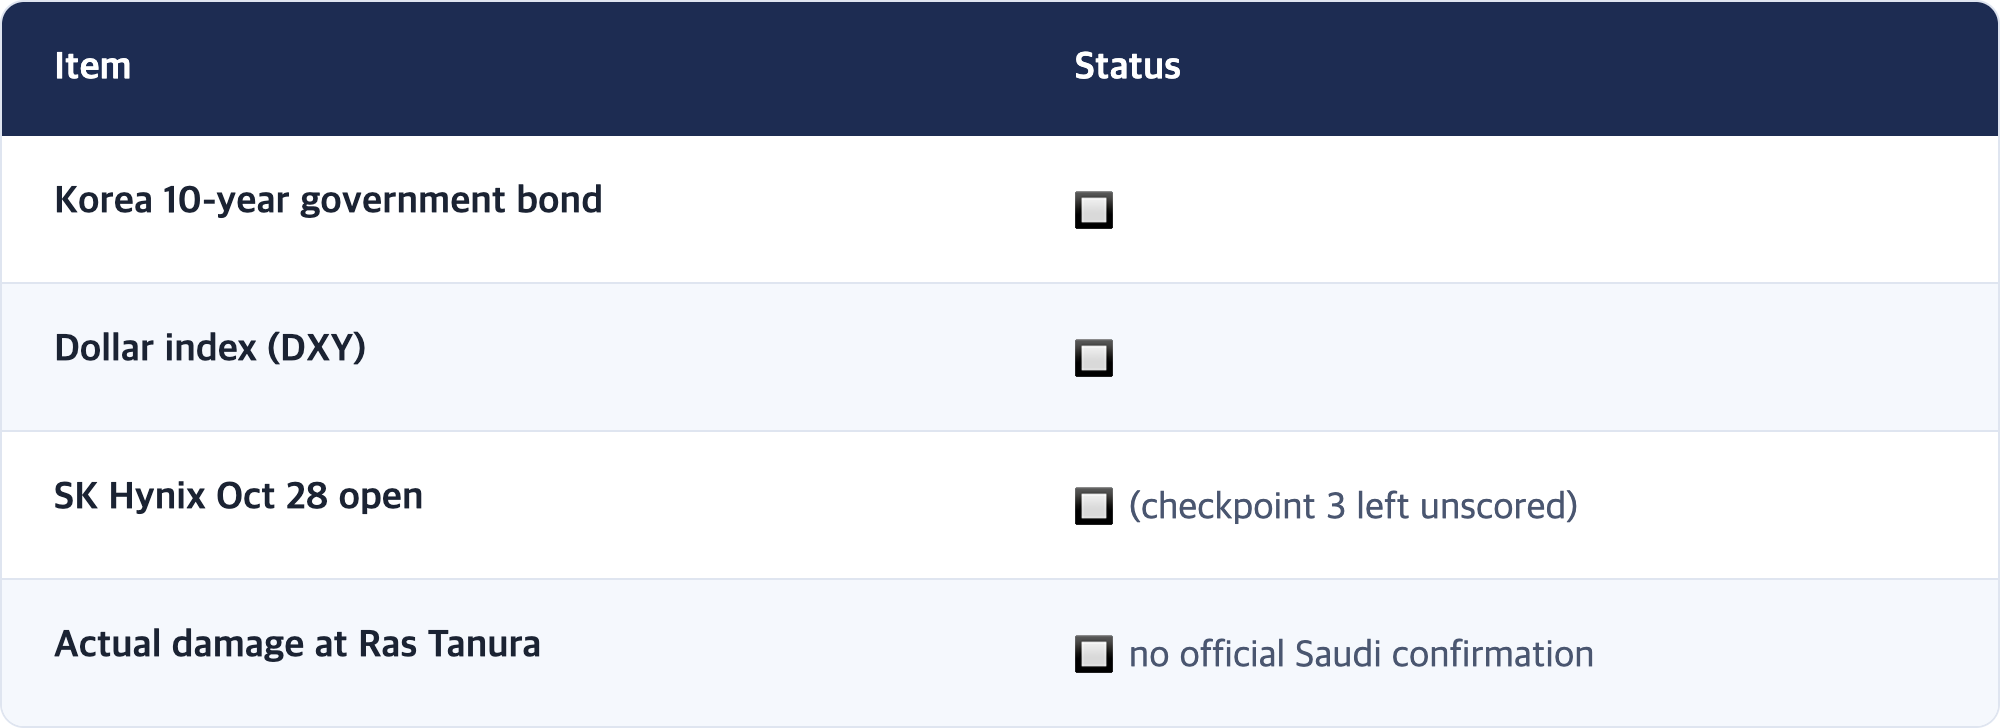
🔲 Not yet sourced
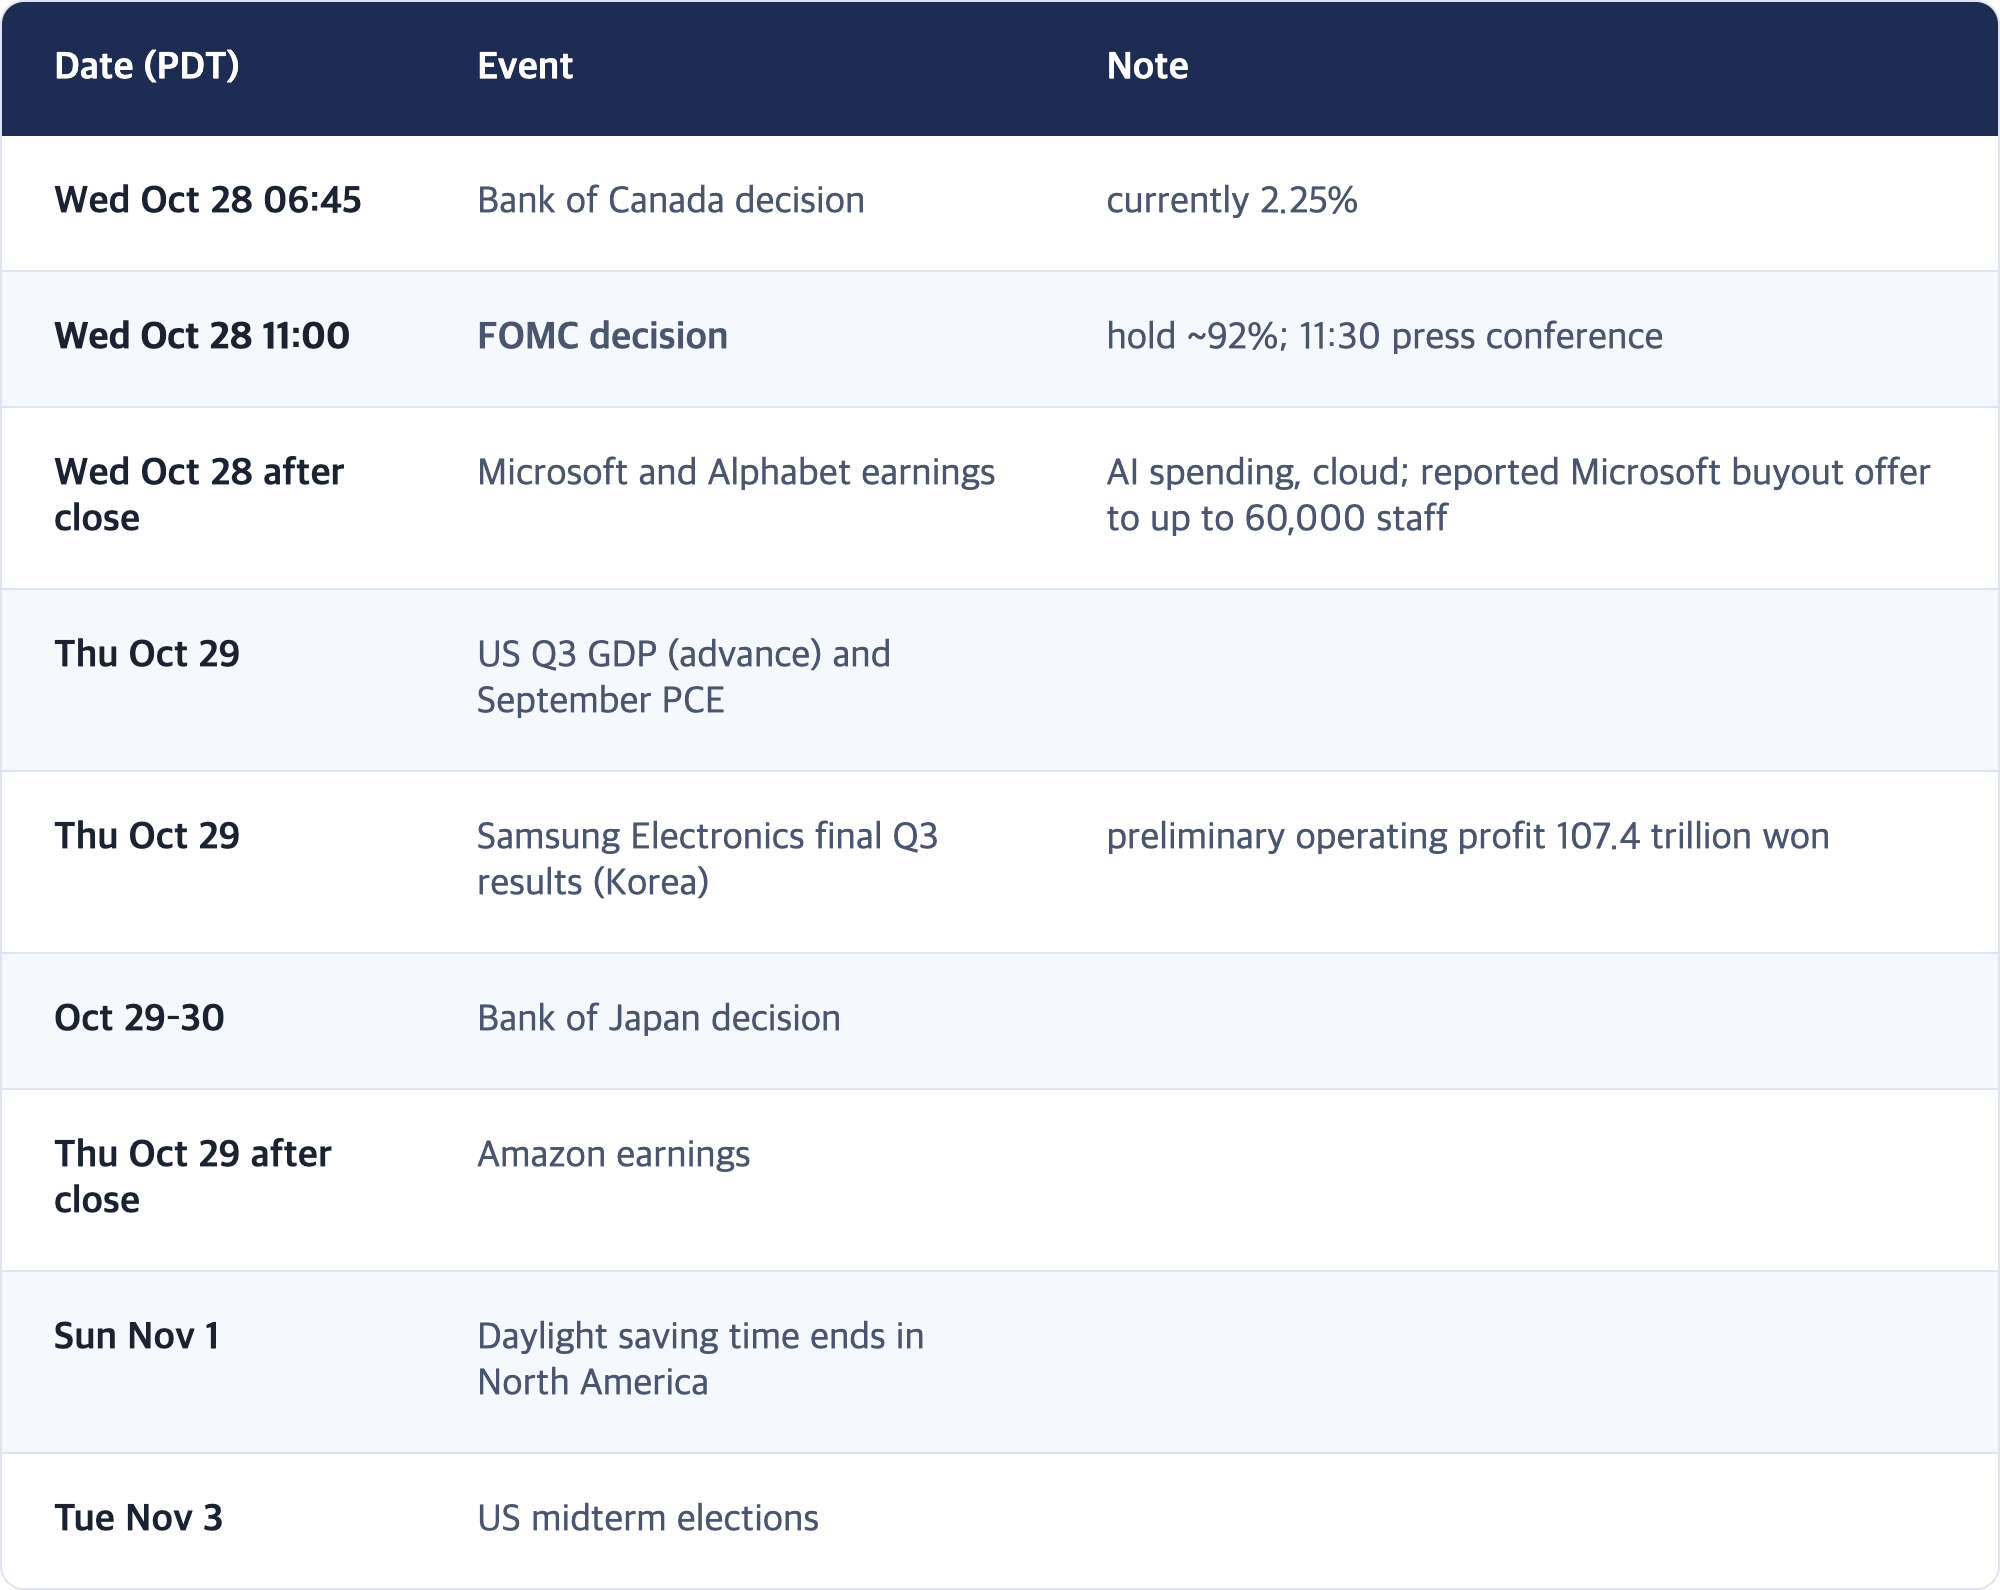
7. Event Calendar (PDT)
Sources
- SK hynix Q3 operating profit 83 trillion won, record | Digital Daily
- SK hynix Q3 record, 100 trillion won shareholder returns | EBN
- KOSPI surges 6% on SK hynix results, back above 6,000 | Hanyang Economy
- Asian stocks rise after a rally on Wall Street, while oil prices edge higher | AP via US News
- Japan and South Korean stock markets closed higher, with SK Hynix surging nearly 11% | TechFlow
- Stock market today, Wednesday October 28 | Yahoo Finance
- Alphabet, Microsoft to report; Fed decision ahead | Investing.com
- October Fed Meeting: Live Updates | Yahoo Finance
- Brent Crude Oil Price: $115.59 on Fed Decision Day After Houthi Ras Tanura Claim | FinanceFeeds
- Oil prices rise as Saudi Ras Tanura hub catches fire after Houthi attack | Türkiye Today
- European Stocks Trade Lower as Bank Earnings Provide Support | ADVFN
Market Analyst · This brief does not recommend buying or selling any individual security. It offers macro context and interpretation only.
📌 More market briefs
※ This post is market observation and organization intended to support your own judgment. It is not a recommendation to buy or sell any security. Figures are as of the time of writing and may differ between sources.
If this was useful, bookmark it or pass it along. It genuinely helps me write the next one.
I can survive. We can survive.