Oct 7, 2026 KOSPI Market Brief — What to Watch Before the Korean Open
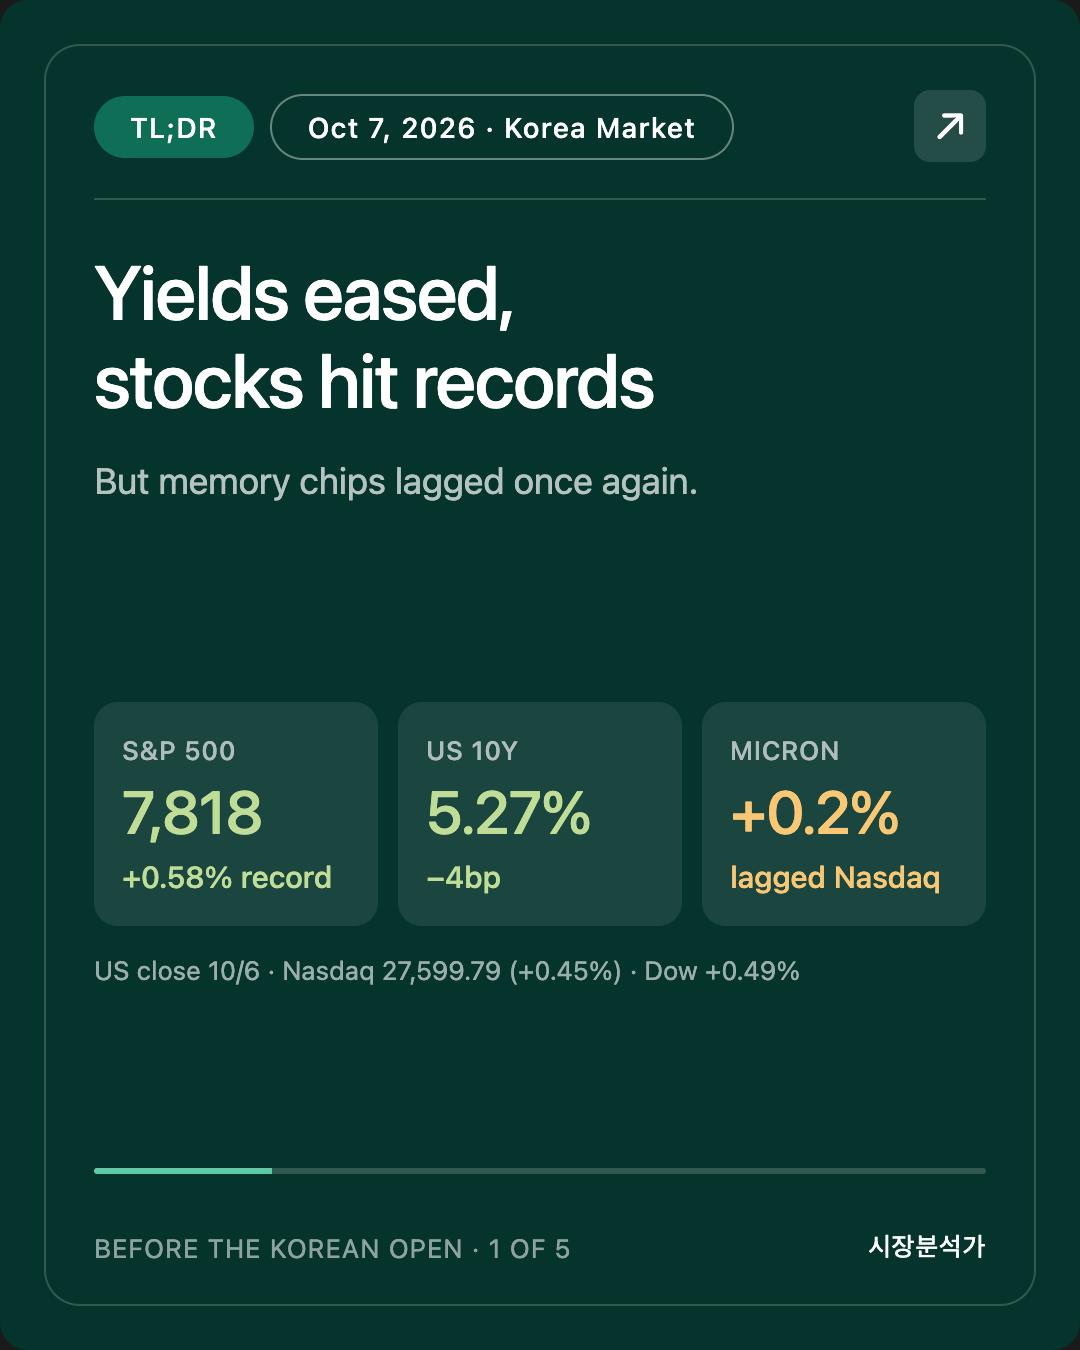
- ★ Yields took a breather, stocks hit another record. S&P 500 7,818.93 (+0.58%, record) · Nasdaq 27,599.79 (+0.45%, record) · Dow 51,521.28 (+0.49%). 10-year 5.27% (−4bp), 30-year 5.64%. VIX 15.01 (−3.29%).
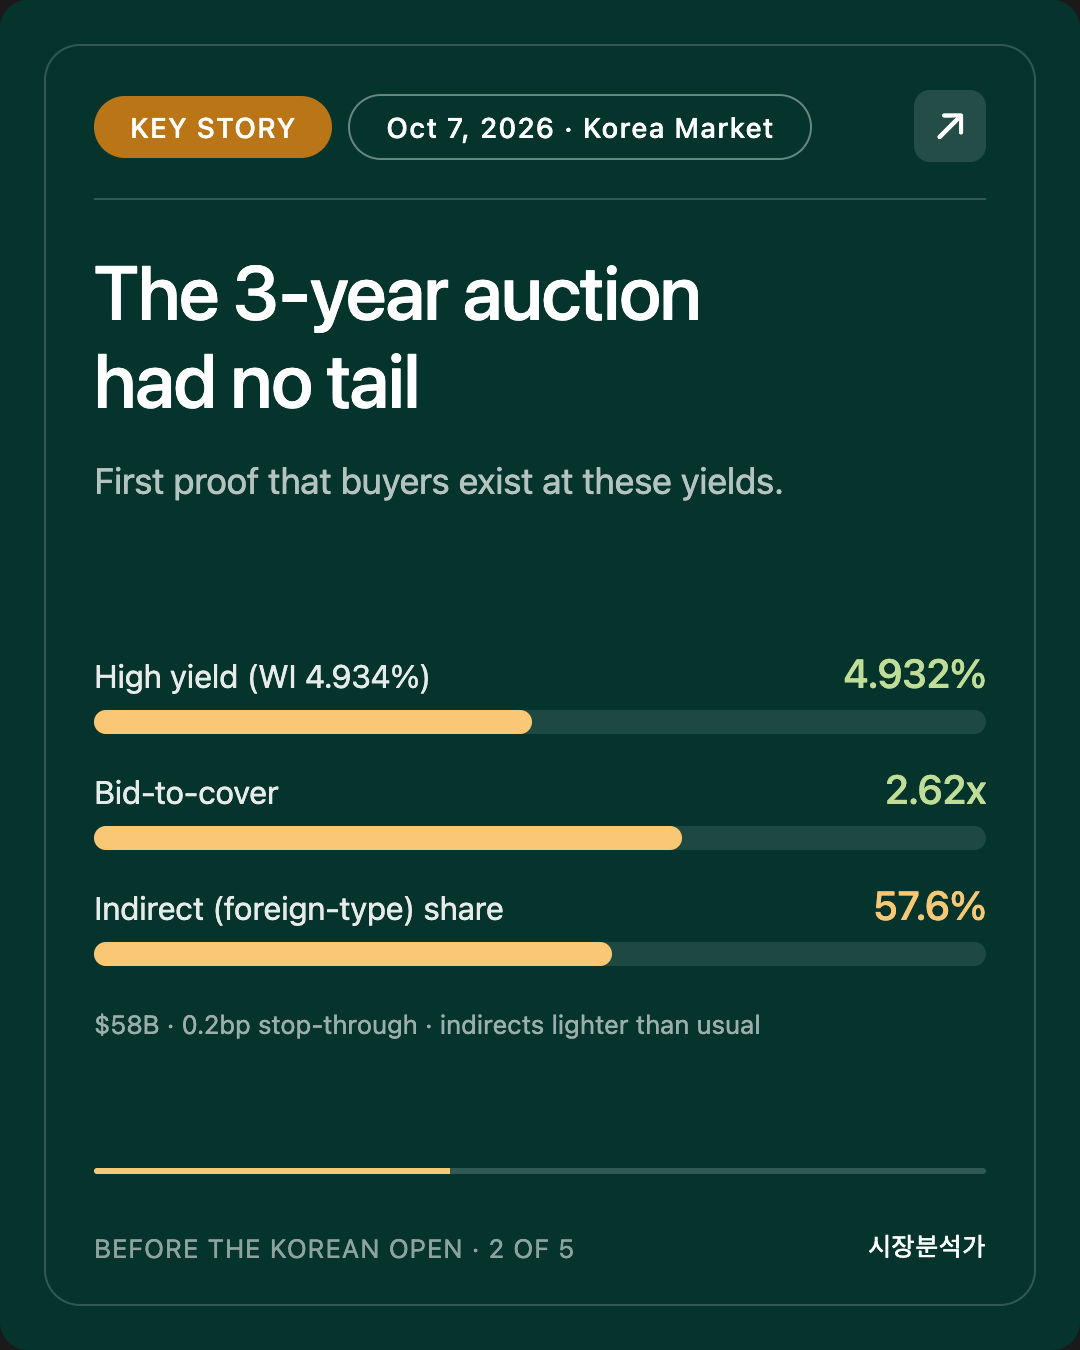
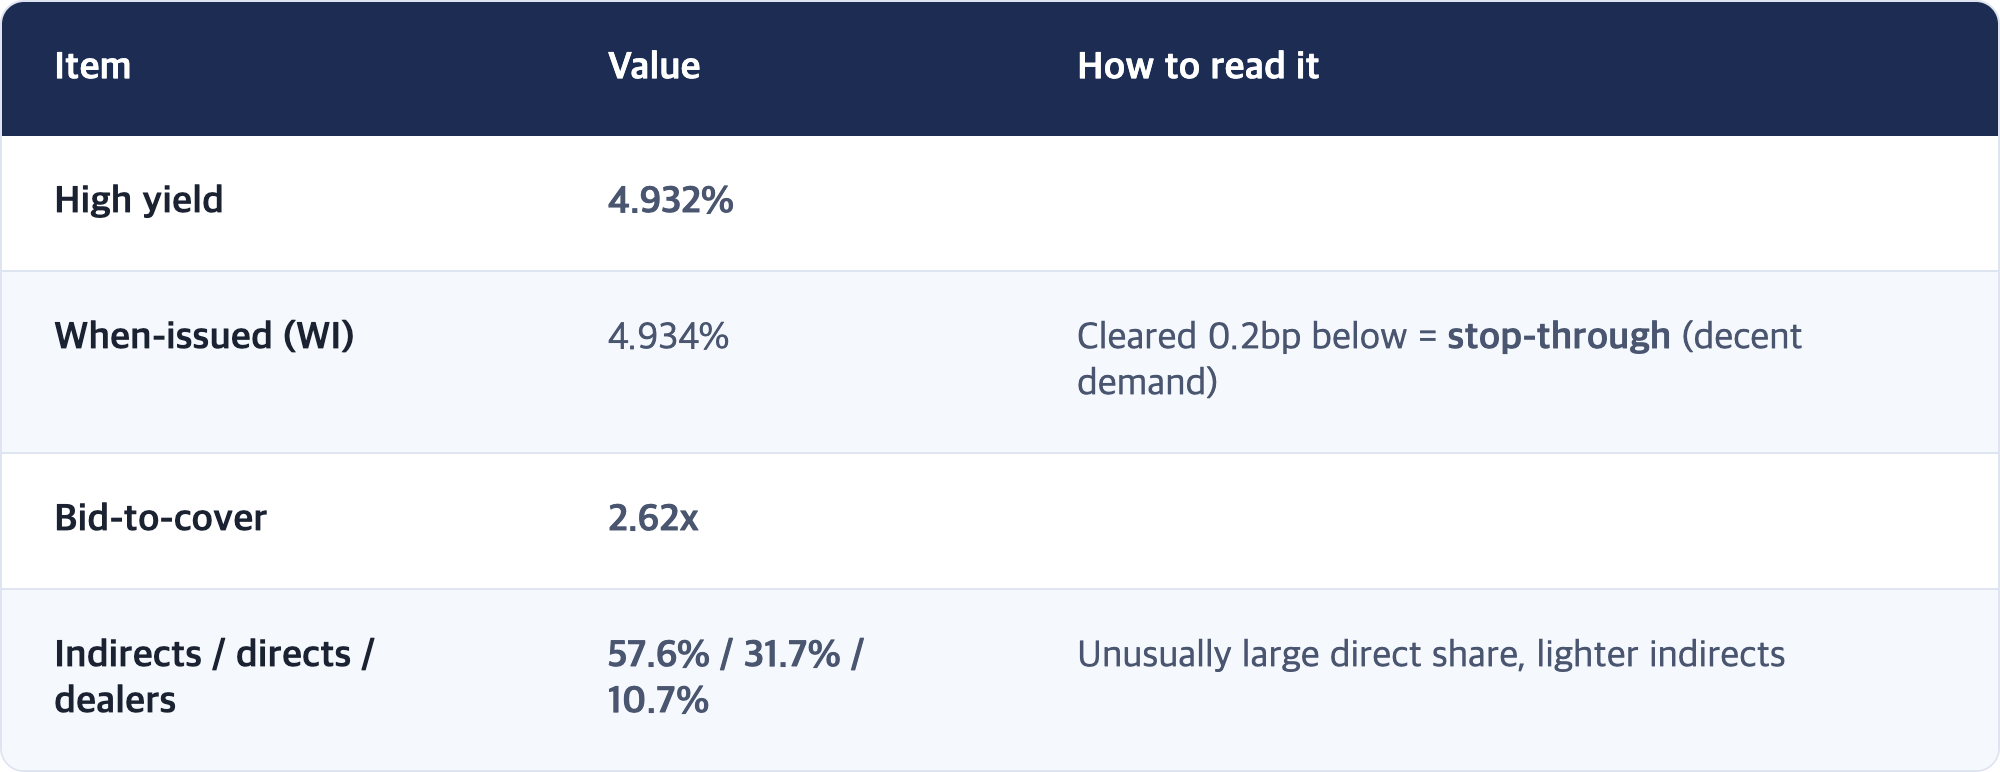
- ★ The 3-year auction cleared with no "tail." High yield 4.932%, 0.2bp below the when-issued level of 4.934% (a stop-through), bid-to-cover 2.62x. The first real-money evidence that buyers exist at these yields. Foreign-type demand (indirects 57.6%) was lighter than usual, though.
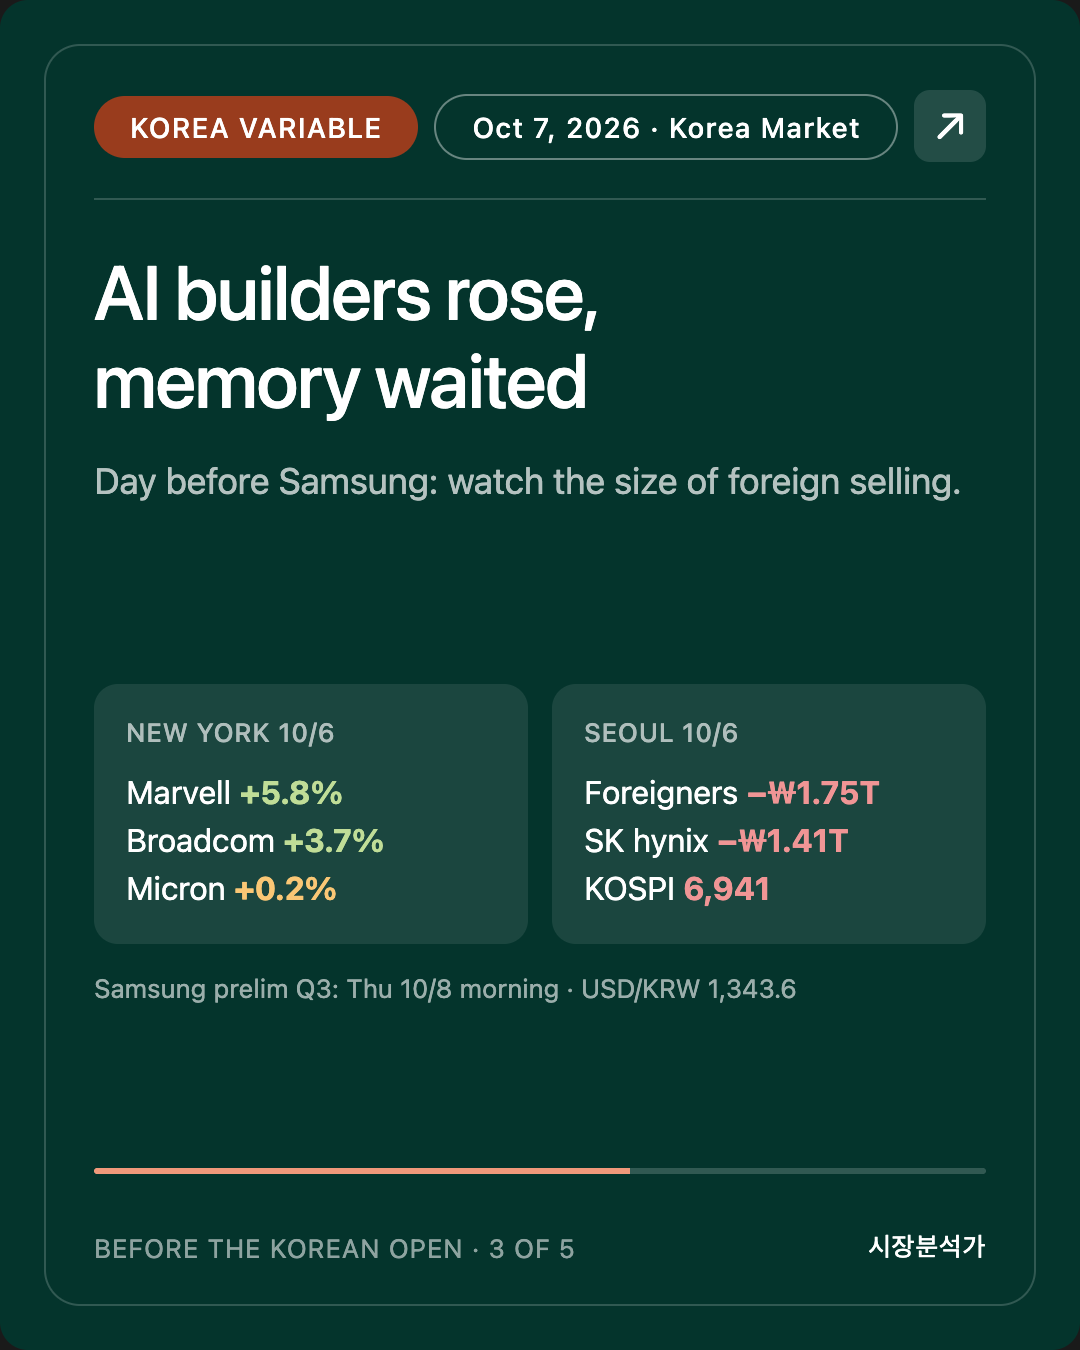
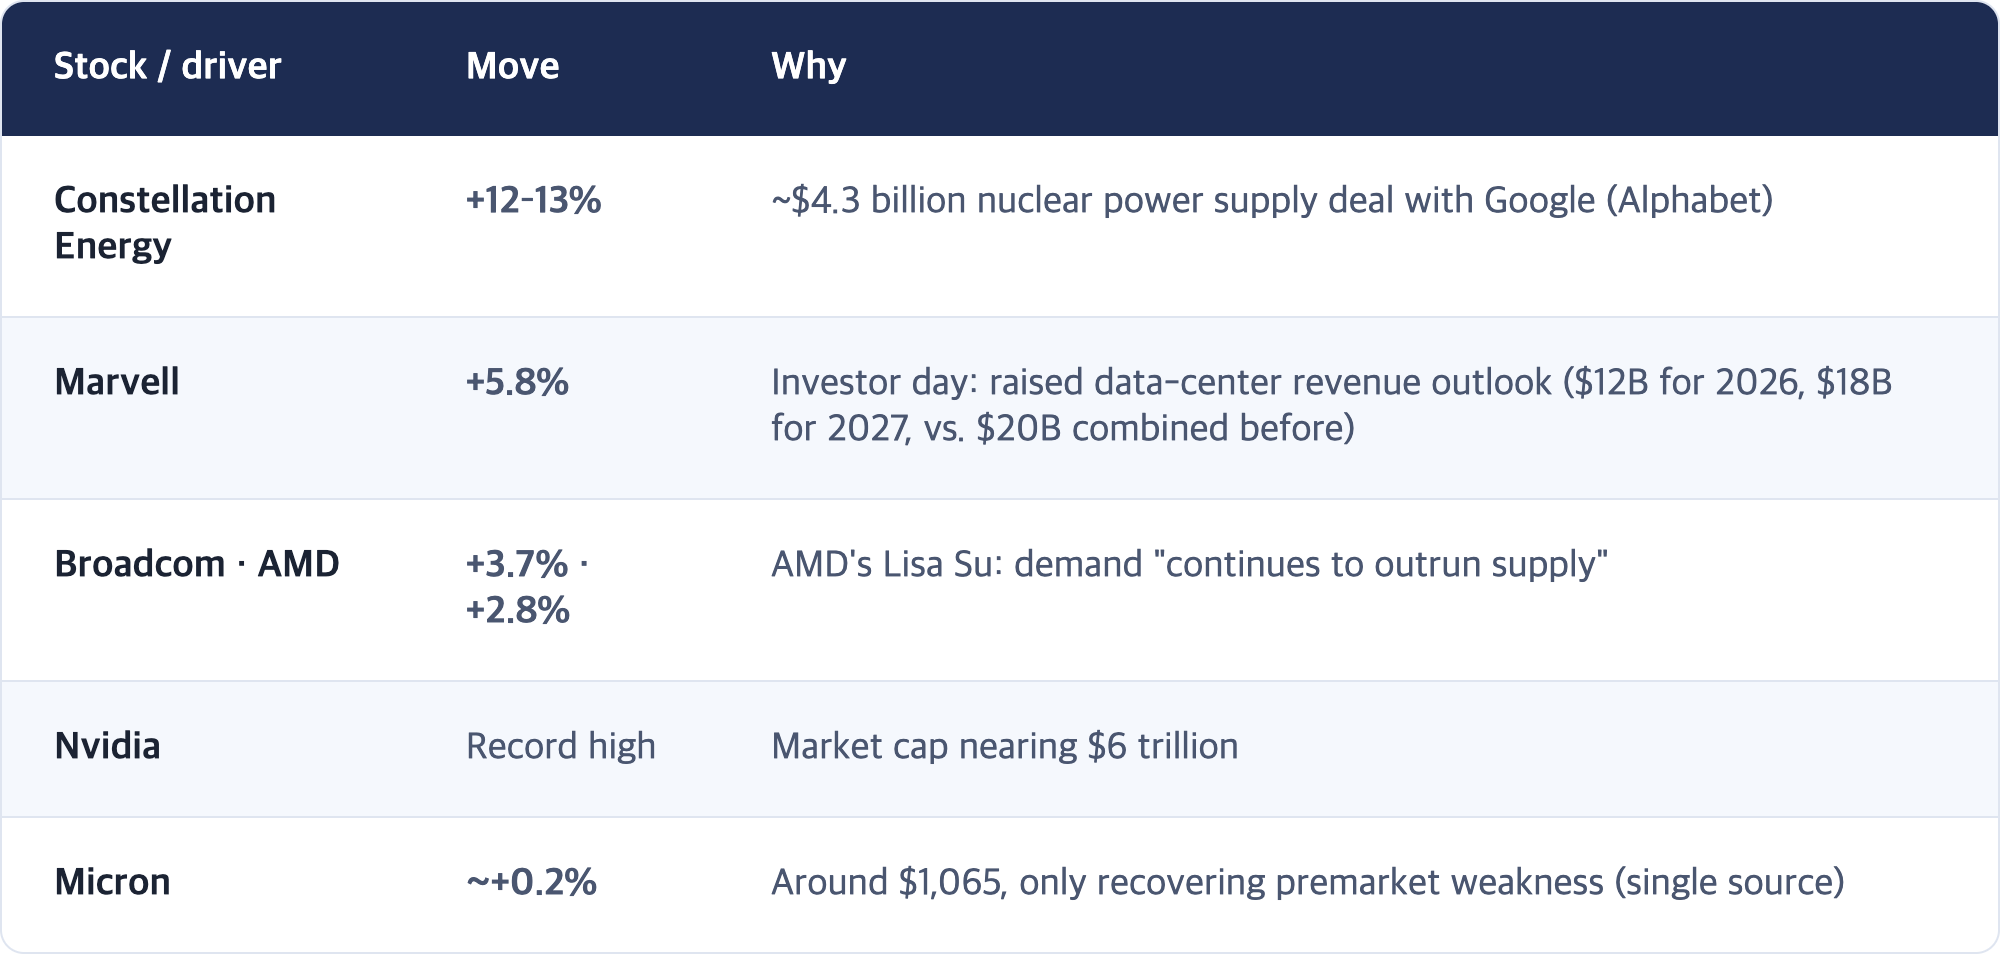
- ★ Chips rose, but memory still lagged. The Philadelphia Semiconductor Index (SOX) closed at 13,248.23 (+0.57%), edging out the Nasdaq, but the leaders were AI networking and compute names (Marvell, Broadcom, AMD). Micron rose about 0.2% (single source).
- The rally is narrow. Russell 2000 −0.59%, and only about 25% of S&P 500 stocks trade above their 50-day moving average (Yahoo Finance). The record is being carried by a handful of giants.
- Seoul's question today: one day before Samsung reports, does foreign selling of memory stocks stop? Yesterday foreigners sold a net ₩1.75 trillion (about $1.3 billion), of which ₩1.41 trillion was SK hynix alone. USD/KRW 1,343.6.
This is Mr. Can. Here is the Oct 7, 2026 brief ahead of the Korean market open.
Written: 2026-10-07 08:07 KST (Vancouver 10/6 16:07 PDT)
Basis: US regular-session close for Tue 10/6 + US 3-year note auction results + oil futures settlements on 10/6 + Seoul close for Tue 10/6 + Tokyo close for 10/6
🟢 Scheduled 16:00 PDT, started 16:01 PDT. On time.
🟡 Seoul has a three-day week (Tue–Thu) and today is the middle day. Tomorrow (Thu 10/8) brings the September FOMC minutes at 3:00 a.m. KST, followed the same morning by Samsung Electronics' preliminary Q3 results. Friday 10/9 is a holiday in Korea (Hangul Day).
SEO Intro
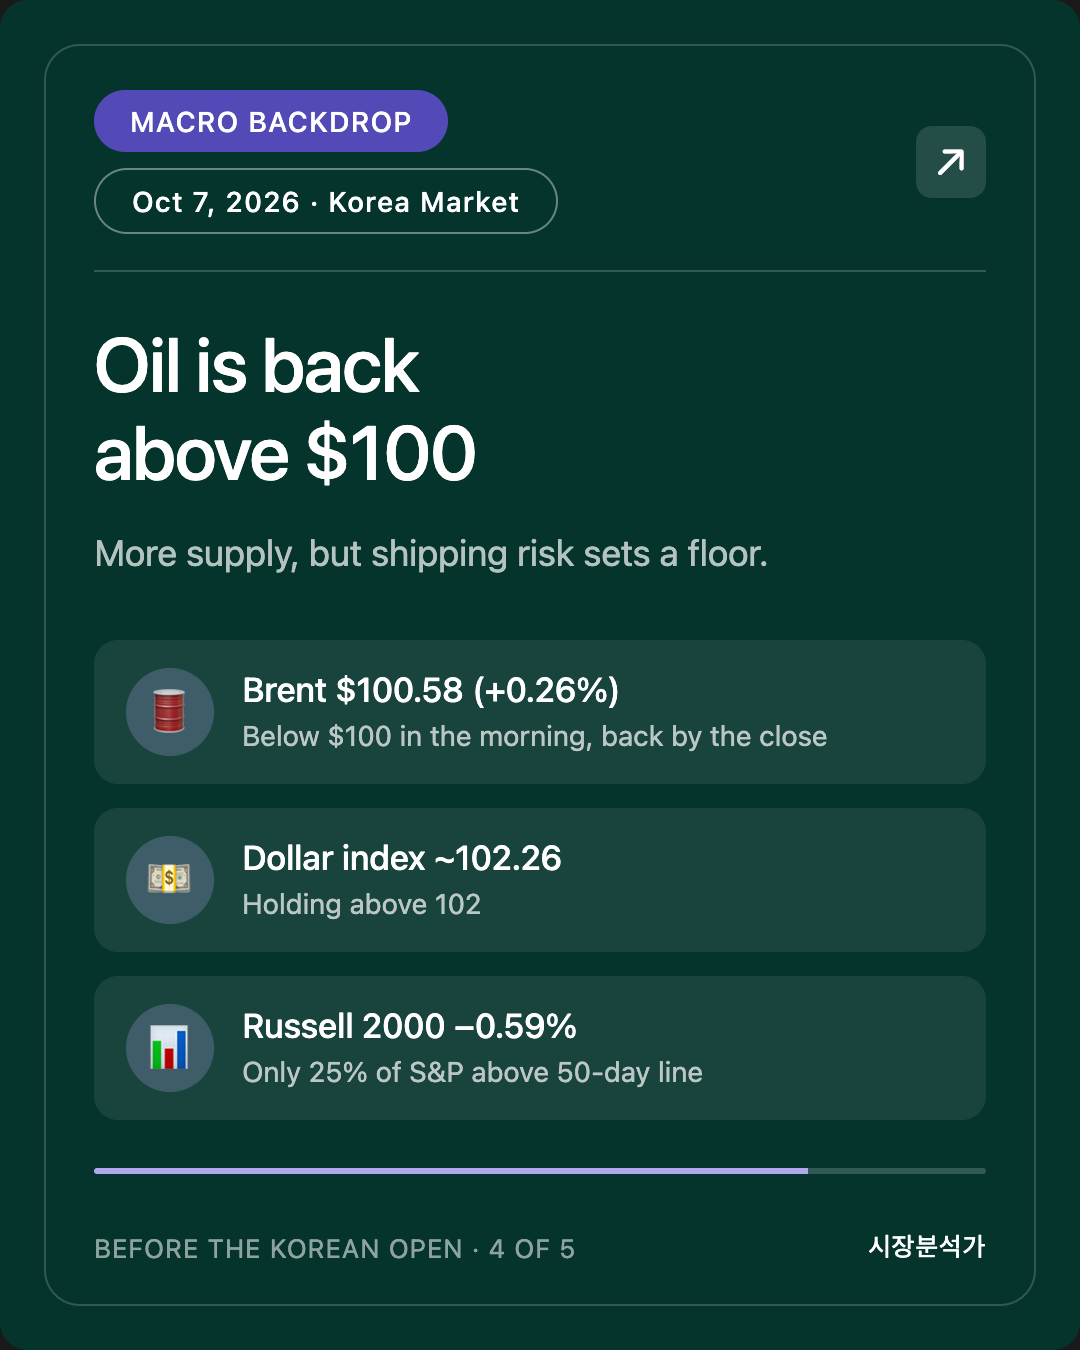
Wall Street set records for a second straight day. The S&P 500 closed at 7,818.93 (+0.58%), its first close above 7,800 and a new all-time high, and the Nasdaq Composite finished at 27,599.79 (+0.45%), also a record. The 10-year Treasury yield, which touched its highest level since 2002 the day before (5.349% intraday), eased back to 5.27%, and a $58 billion 3-year note auction was absorbed without trouble.
But memory chips were again not the leaders. Marvell (+5.8%), Broadcom (+3.7%) and AMD (+2.8%) led, and Constellation Energy jumped more than 12% after a nuclear power deal with Google. Micron gained only about 0.2%. And while the index hit a record, the small-cap Russell 2000 fell 0.59%. Seoul, where foreign investors sold about $1 billion of SK hynix alone yesterday, now takes in this picture one day before Samsung reports.
1. Checkpoint Scorecard
The four from the 10/6 pre-US-open brief (US close 10/6)
The question was: "Is the retreat in long yields confirmed with real money, and do memory stocks benefit?"
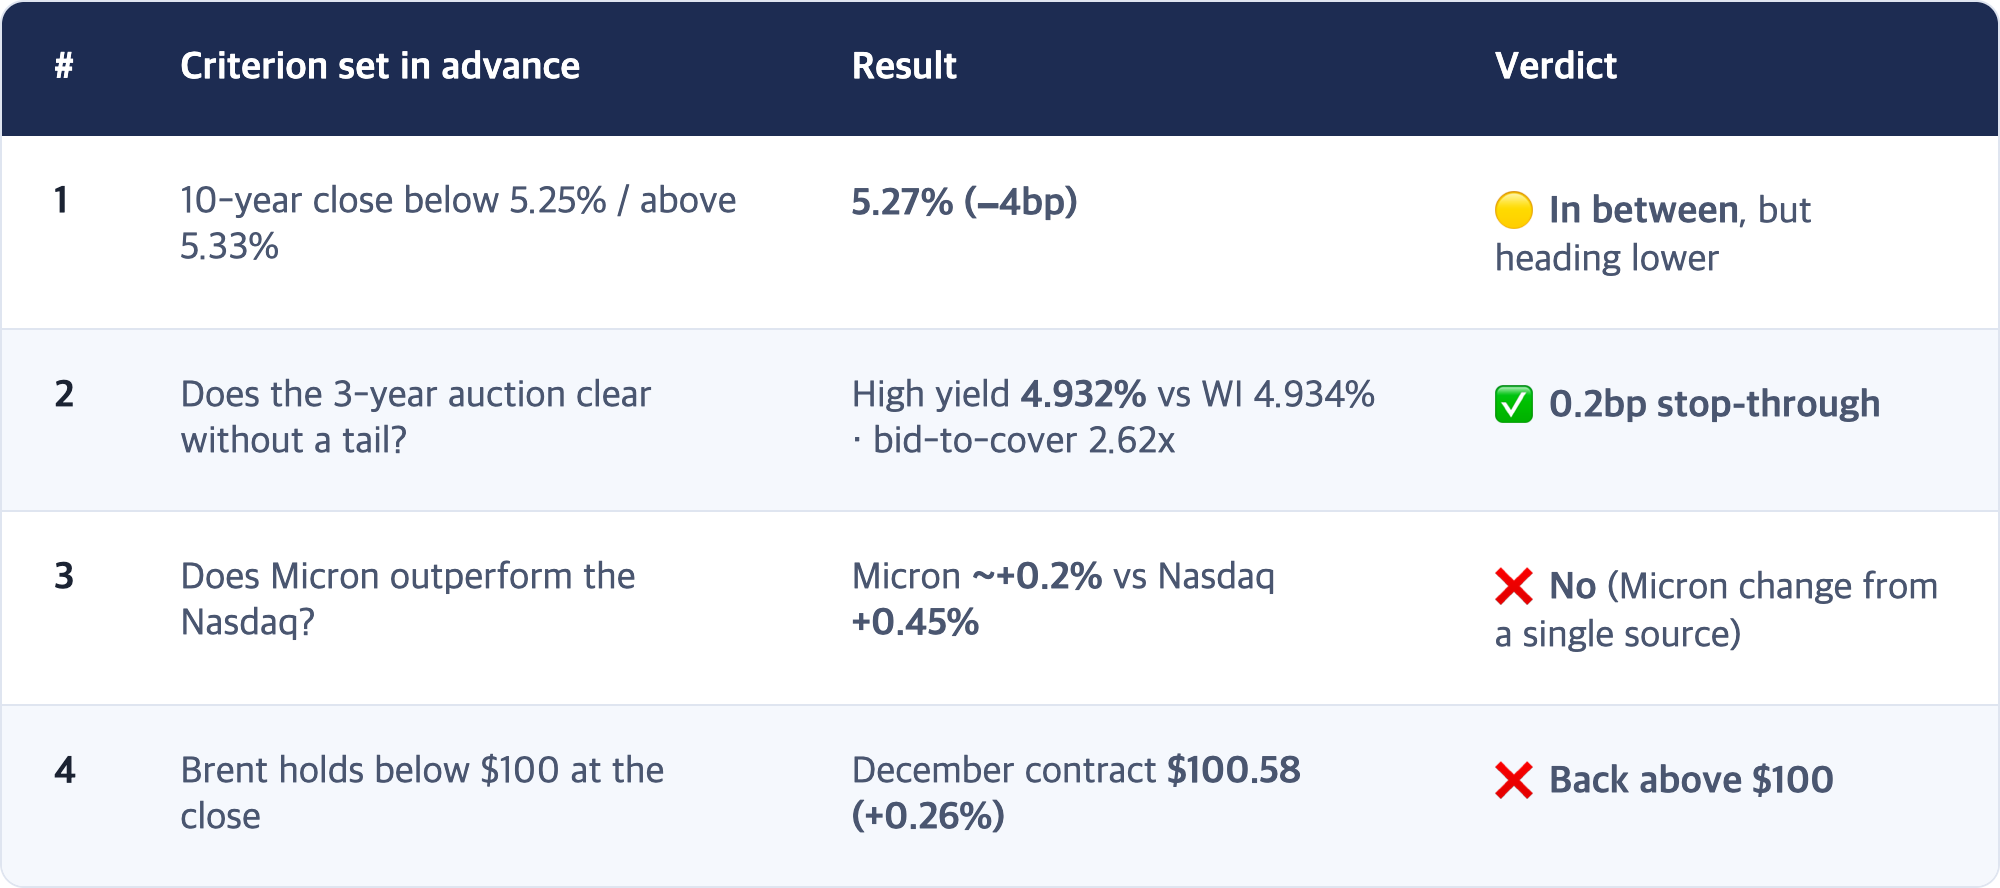
[Interpretation] We landed in exactly the box the morning brief had pre-labeled
The 10/6 morning brief wrote: "If yields fall and memory stocks still can't rise, Seoul's memory weakness is not about rates. It is the market repricing memory itself." That is what happened. The 10-year fell 4bp, the auction went fine, the S&P hit a record, and Micron barely moved.
So for Samsung tomorrow, the market will care less about "how big is the number" and more about "does management say memory prices keep rising next quarter" (guidance and pricing commentary).
The four Seoul checkpoints from the 10/5 Korea brief were already scored in the 10/6 morning brief
Foreign flows ❌ (−₩1.75 trillion) · chips vs KOSPI ❌ · USD/KRW below 1,345 ✅ (1,343.6) · KOSPI holding 7,000 ❌ (6,941.39).
2. Today's Key Story: Yields Caught Their Breath, Memory Only Caught Its Breath
[Fact] US close, Tue 10/6 (05:00 KST Wed)
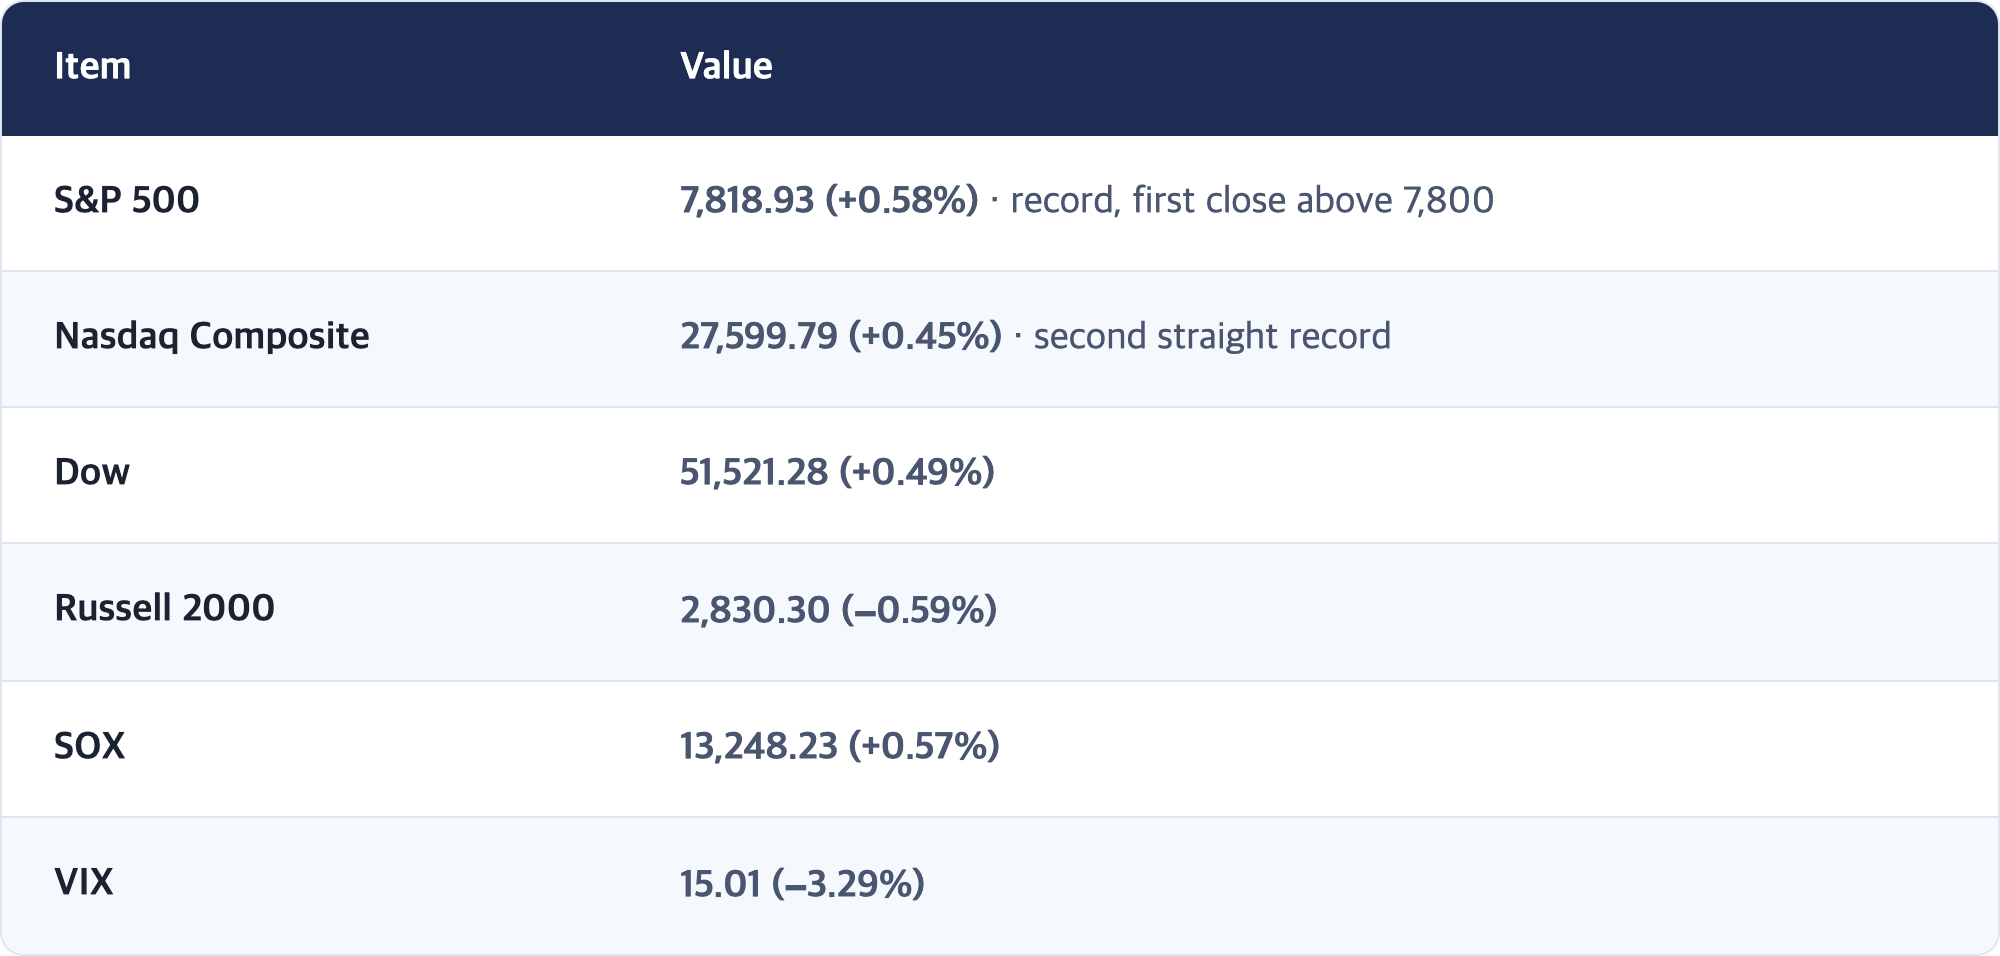
[Fact] Treasuries (10/6)
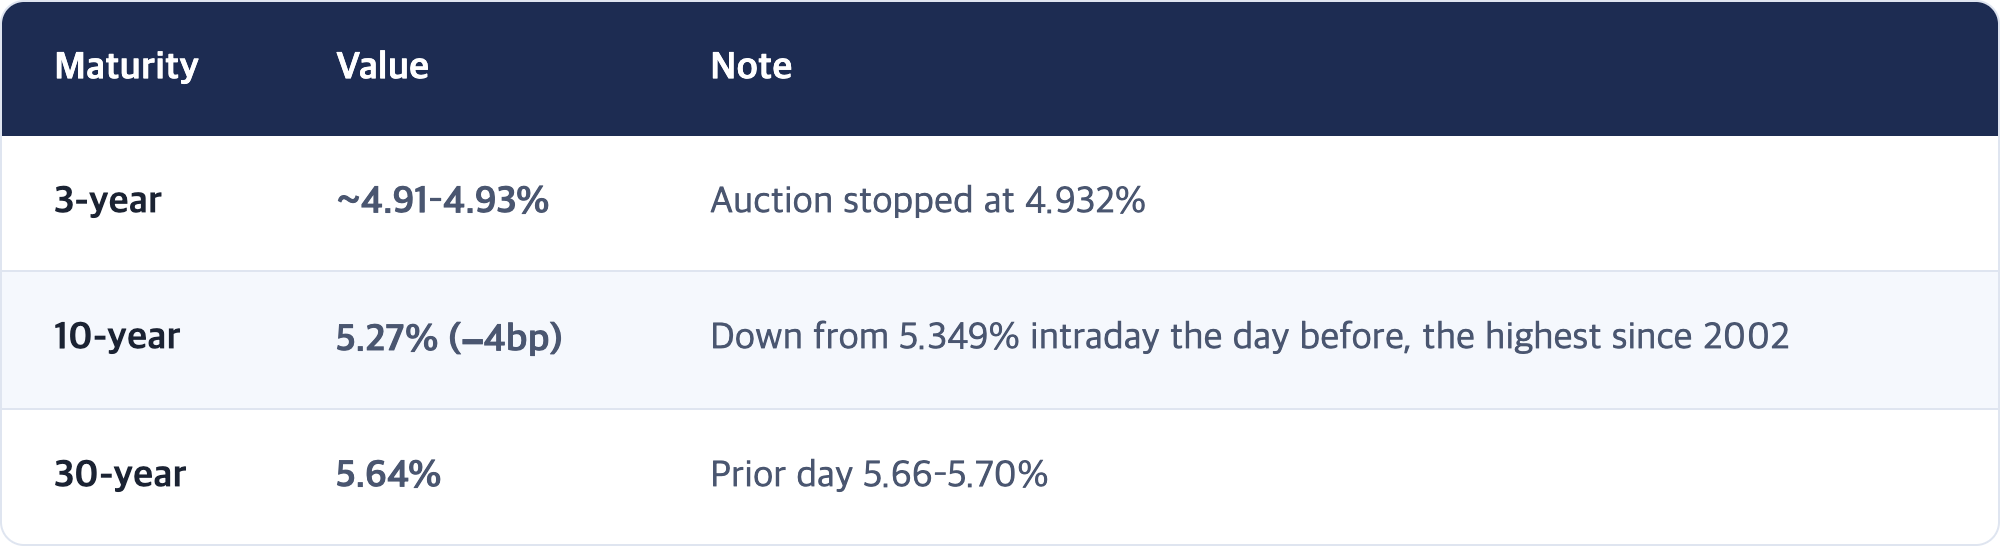
[Fact] 3-year note auction ($58 billion)
[Fact] What rallied
★ [Interpretation] What the market bought was "the cost of building AI"
Line up yesterday's winners and the pattern is clear: chips that connect data centers (Marvell, Broadcom), chips that compute (AMD, Nvidia), and the electricity that runs data centers (Constellation). All of them earn more in direct proportion to how much AI capacity gets built.
Memory also goes into AI data centers, but memory carries one extra variable: price. As the morning brief noted, you can sell more chips and still earn less if prices roll over. Micron posted record results on 9/30 and has gone sideways since. The market appears to be waiting for proof that prices keep rising next quarter.
[Interpretation] This is not a sign that AI is cracking. Within AI, the market is separating "more volume is always good" businesses from "volume is only good if prices hold" businesses. Korea's two chip giants, Samsung and SK hynix, sit in the second group.
[Observation] The record is narrow
The S&P 500 set a record while the Russell 2000 fell 0.59%, and only about 25% of S&P 500 members are above their 50-day moving average (Yahoo Finance). A few giants are pulling the index; most stocks are carrying the weight of high rates. The study note below unpacks this.
3. The Korea Variable: One Day Before Samsung, How Much More Memory Do Foreigners Sell?
[Fact] Seoul close, Tue 10/6
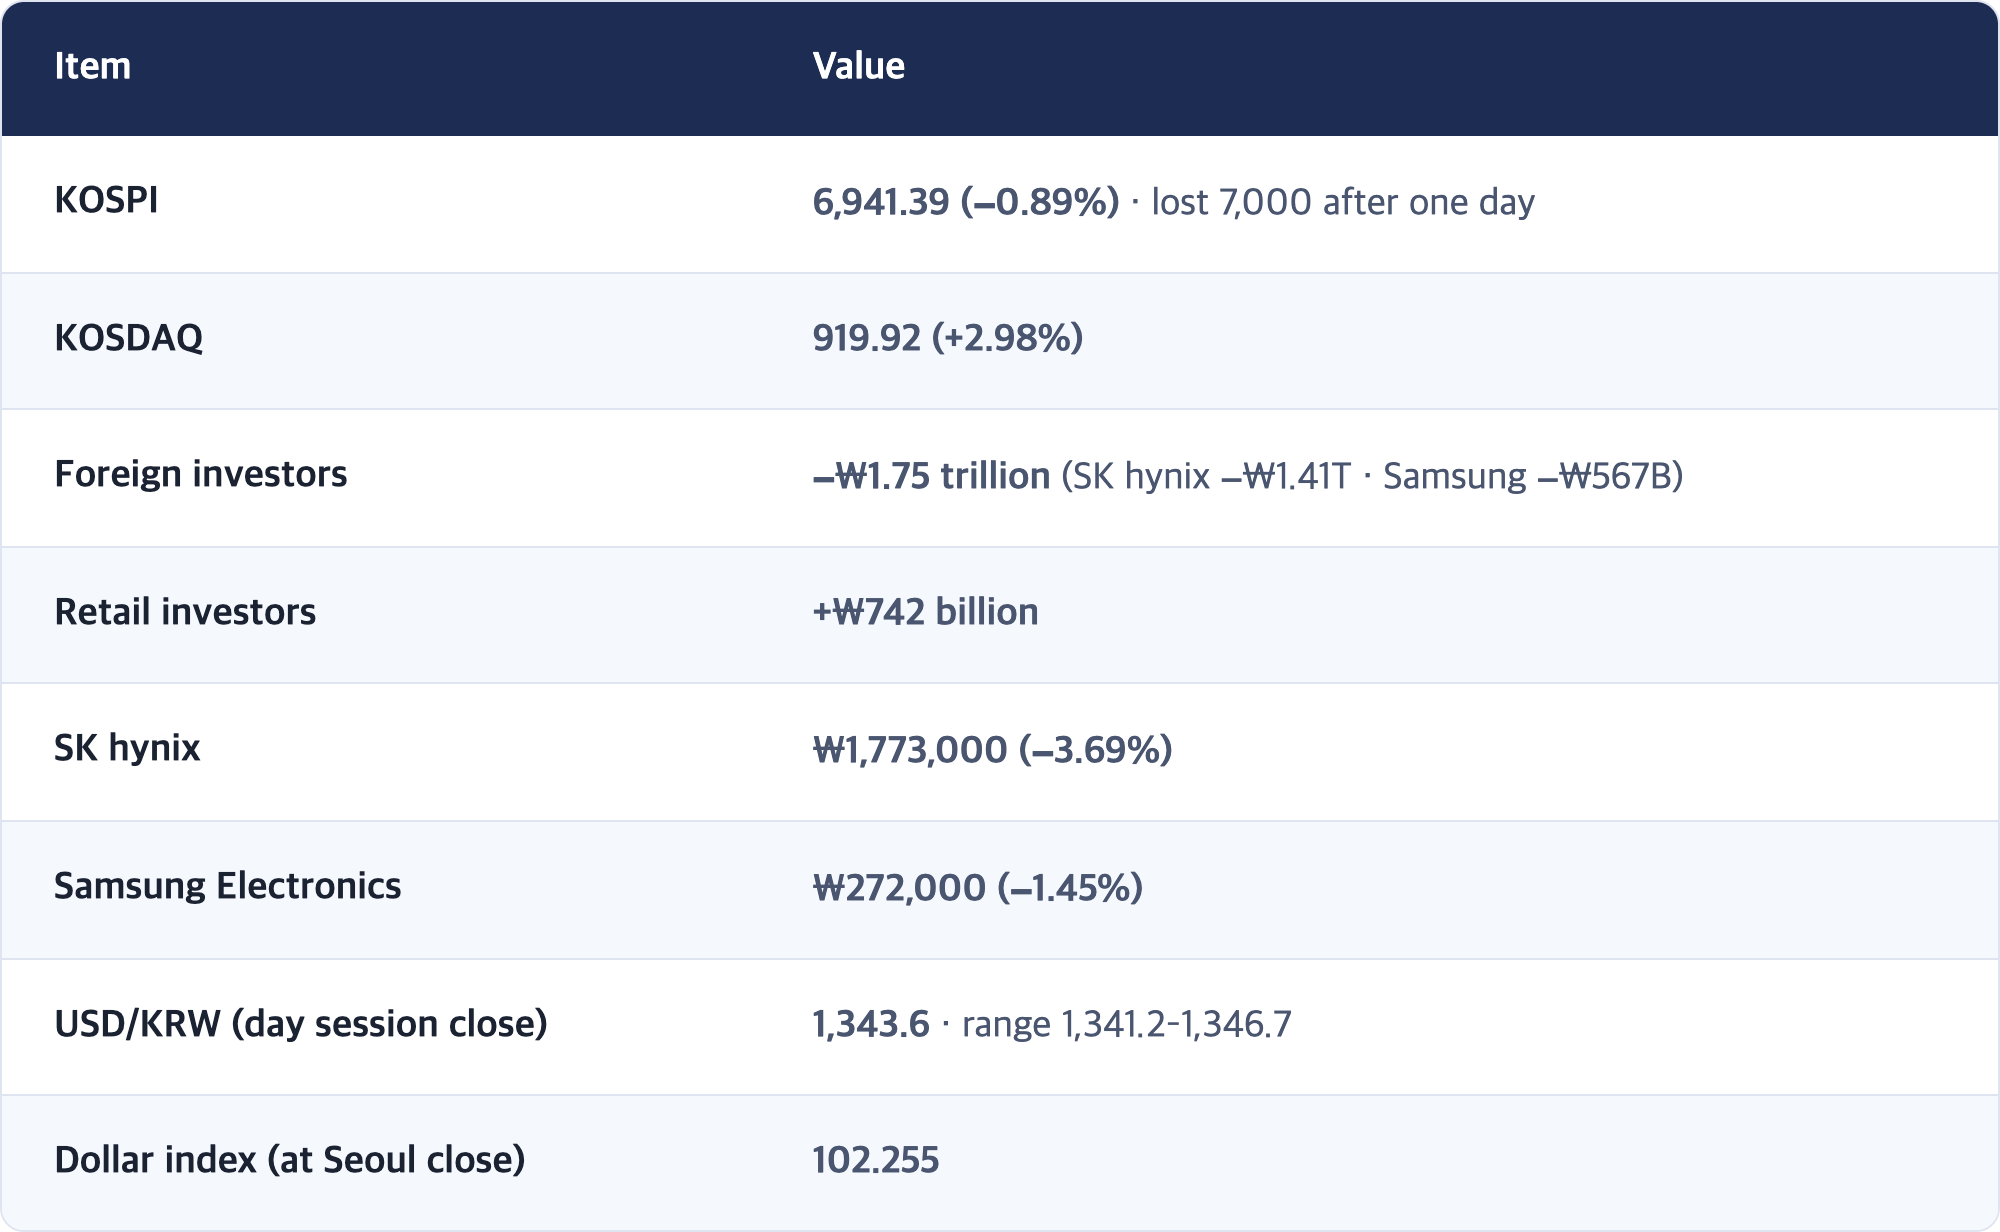
[Fact] What's left this week (KST)
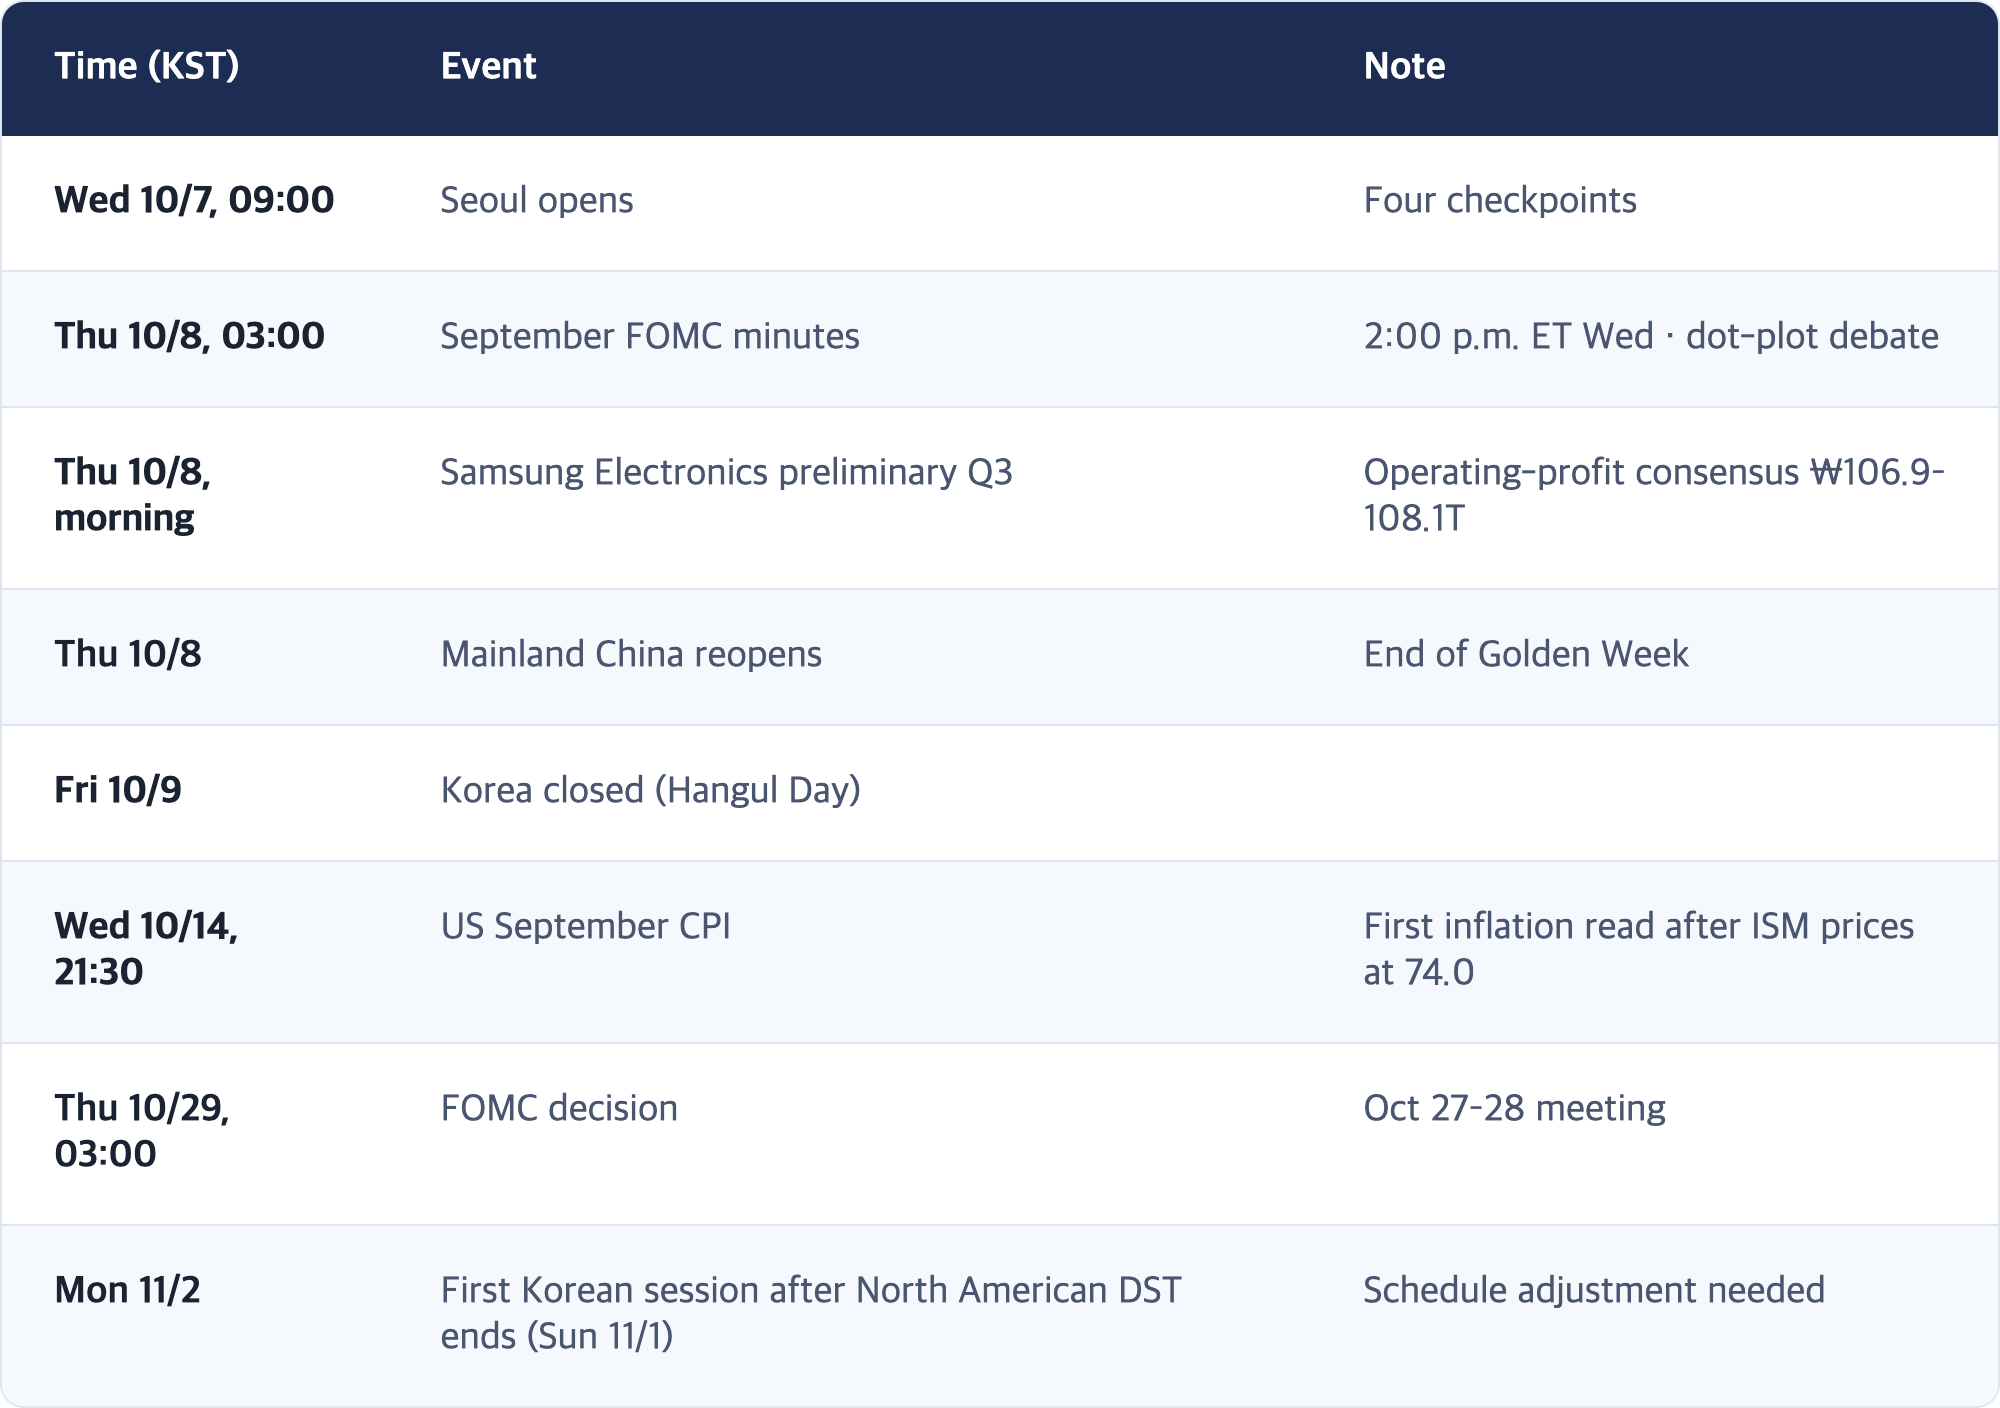
- Thu 10/8, 03:00 September FOMC minutes (the reasoning behind the dot plot's "one more hike")
- Thu 10/8, morning Samsung Electronics preliminary Q3 results. Operating-profit consensus about ₩108.1 trillion (WiseReport, a Korean consensus aggregator, reported 10/4) · another tally ₩106.9 trillion (YTN, 10/6, "cut about 6.2% since September")
- Thu 10/8 Mainland China reopens after the Golden Week holiday
- Fri 10/9 Korea closed for Hangul Day
★ [Interpretation] Today is about pre-earnings positioning
Eighty percent of yesterday's foreign selling was in one stock, SK hynix. Overnight, New York sent a picture of less rate pressure but continued repricing of memory. Seoul gets two forces at once today.
- Supportive: lower 10-year yield, a clean auction, record S&P and Nasdaq, SOX +0.57%. This is not a "rate scare plus memory selling" day like yesterday.
- Weighing: Micron flat. There is little outside catalyst to reverse Seoul's memory selling, and few investors want to make a big bet the day before the earnings number.
[Interpretation] So today, the size of foreign selling may say more than its direction. If foreign selling shrinks well below ₩1 trillion, yesterday was a one-day pre-earnings profit-take. If it stays near yesterday's level, memory is being repriced regardless of what the earnings number says.
[Observation] The fact that two consensus figures are circulating (₩106.9T vs ₩108.1T) is itself information. If some tallies have come down since September, the headline "₩100 trillion quarter" may already be the floor of expectations. The principle from our 10/1 brief, "measure surprise against the recent price path, not the consensus," gets tested tomorrow.
[Interpretation] The four Korean market commentators this brief tracks share a long-term view of a chip-led Korean market. That big picture and this week's day-to-day foreign memory selling run on different time horizons. Even if the big picture is right, pre-earnings flows can move on their own. Don't read one as evidence about the other.
4. Macro Backdrop: Oil Sticks Near $100, the Dollar Holds 102
[Fact] (10/6 close)
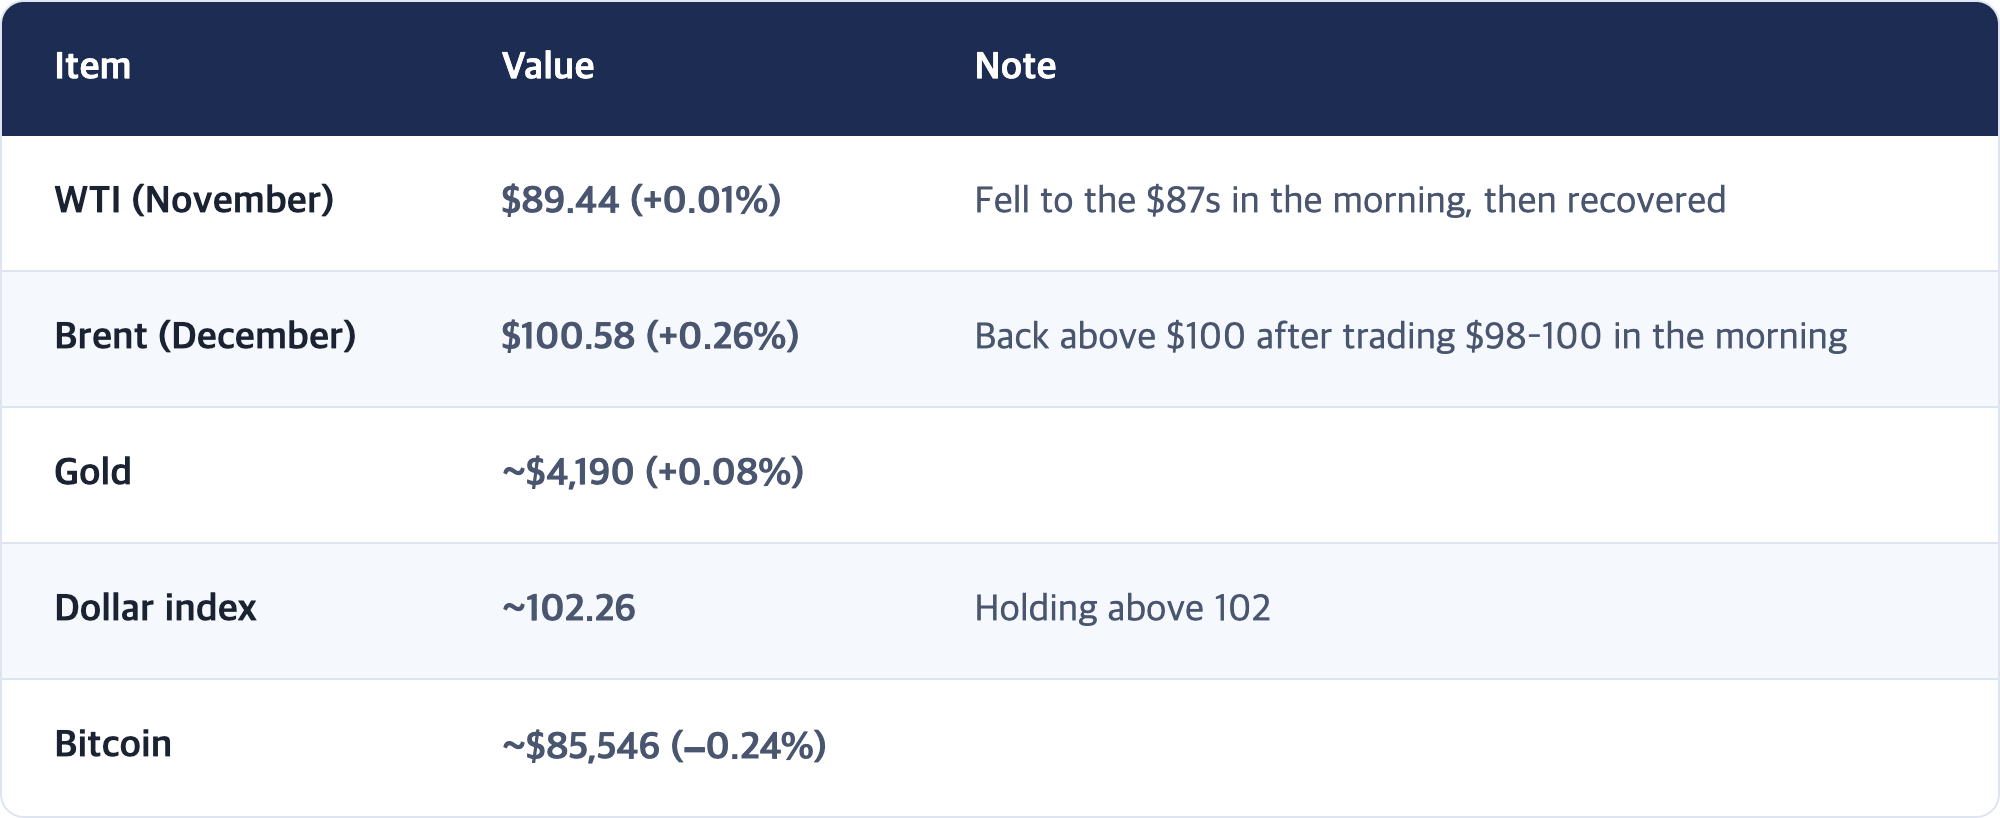
[Fact] What pushed oil down, and what held it up
- Down: the G7 plan to release 100 million barrels from emergency reserves; Gulf crude exports topping 18 million barrels a day on several days, above pre-war levels; Saudi price cuts for Asian buyers (Arab Light discounts up to $5 a barrel).
- Up: escalating fighting in Yemen between Saudi-backed government forces and the Houthis, and Houthi counterattacks; five incidents in the Strait of Hormuz in a single day, four of them tanker attacks (UKMTO, 10/5); Gulf tanker freight at a record of about $33 a barrel.
- A PVM analyst said Brent "is struggling again around the $100 psychological level."
[Interpretation] Oil is stuck between "supply is coming back" and "the route is dangerous"
In the morning, the supply story won and Brent dipped below $100; by the close it was back above. More crude is flowing, but shipping cost and risk ($33 freight) put a floor under prices. For now, oil looks close to neutral for long yields: not pushing them much higher, not pulling them much lower. What sets the direction of long yields now is inflation data (US CPI on 10/14) and fiscal worries.
5. Today's Korean Session (Wed 10/7 KST) Preview
The question
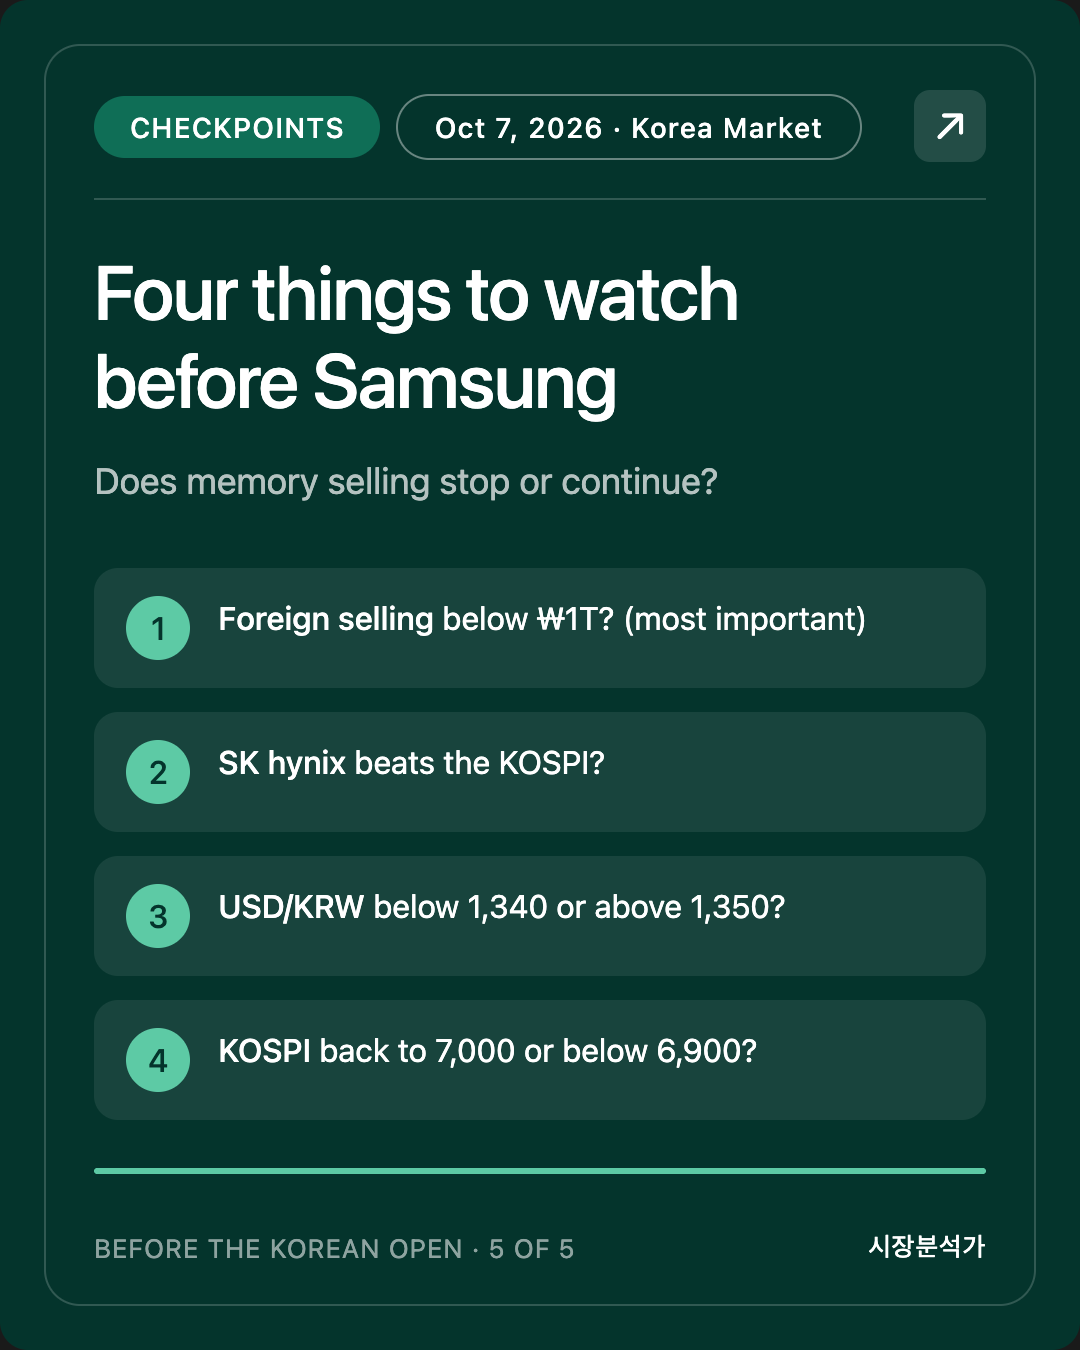
The four checkpoints ask: "On a day when rate pressure eased, does Seoul's memory selling stop, or does it continue regardless of earnings?" The answer sets Seoul's starting line for Samsung's numbers tomorrow morning.
✅ Four checkpoints (Seoul close today)
- Does foreign selling shrink below ₩1 trillion, or stay near yesterday's ₩1.75 trillion? A switch to net buying would itself be a big signal. (Most important)
- Does SK hynix beat the KOSPI? It took 80% of yesterday's selling. Outperforming would suggest yesterday was a one-off.
- USD/KRW below 1,340 / above 1,350. Does the odd pairing continue, with the won staying strong despite ₩1.7 trillion of foreign selling?
- KOSPI back above 7,000 / below 6,900. Which line does Seoul test in the middle of a three-day week?
[Interpretation] The most informative combination is #1 and #2. Shrinking foreign selling plus SK hynix outperforming = "the end of pre-earnings profit-taking." Continued selling plus SK hynix lagging again = "memory repricing in progress." If they split, hold judgment until tomorrow's earnings number.
6. Study Note: What Is "Market Breadth"?
Concept
A stock index is an average of stocks, but not a plain average. It is weighted by size (market cap). So if a few giant companies rise sharply, the index can climb even while most stocks fall. Market breadth is how you check for that illusion: how many stocks rose, and what share of stocks sit above their own trend line (say, the 50-day moving average).
Analogy
The class average goes up, but it turns out the top two students got perfect scores while the other thirty did worse. The average (the index) looks better; the class (the market) did not.
Real examples
- Yesterday (10/6): S&P 500 record, yet the Russell 2000 (2,000 smaller companies) fell 0.59%, and only about 25% of S&P 500 stocks are above their 50-day line (Yahoo Finance). Three out of four stocks have a weakening two-month trend.
- Why: smaller companies carry more debt and rely more on bank loans, so 5%-plus yields hurt them more. Mega-cap tech has lots of cash and AI-driven revenue growth, so it is less rate-sensitive. As long as the 10-year sits near a 24-year high, a narrow rally is a natural outcome.
- Same question in Seoul: the KOSPI leans heavily on two chip stocks. Yesterday the KOSPI fell 0.89% while the KOSDAQ rose 2.98%. Seoul had the opposite day: broad participation, weak leaders.
One-line takeaway
When an index is at a record, also ask how many stocks came along. A narrow record can crack quickly if the few leaders wobble.
7. Corrections and Open Items
Corrections
- Oil in the 10/6 morning brief: it described Brent at "about $98.5 (−1.8%), below $100" and WTI at "about $87.3–87.7 (around −2%)." Those were pre-US-open quotes. Final settlements were WTI $89.44 (+0.01%) and December Brent $100.58 (+0.26%), a full intraday reversal. The "oil below $100" framing did not hold at the close (hence checkpoint #4 ❌). The front Brent contract has rolled to December, so quote sites may have mixed contract months.
Source discrepancies (value used stated)
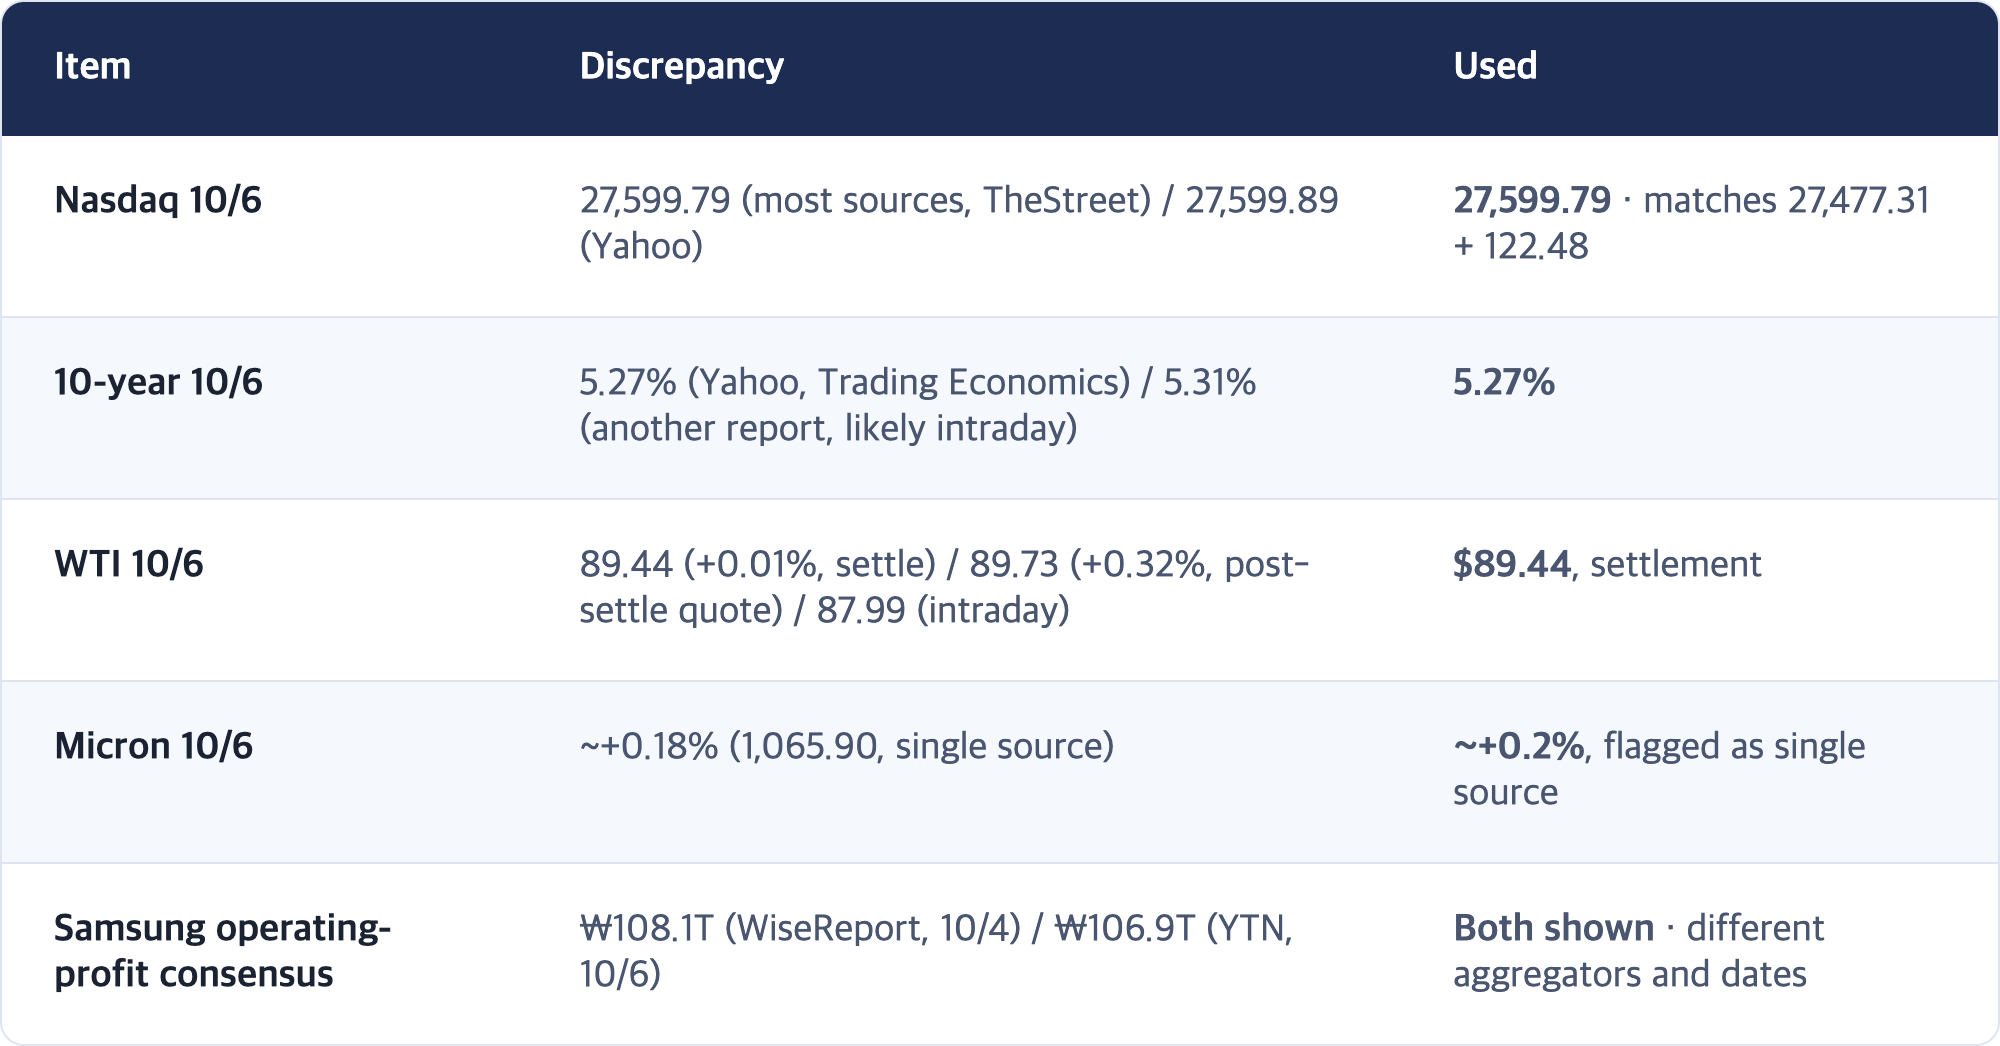
🔲 Not yet confirmed
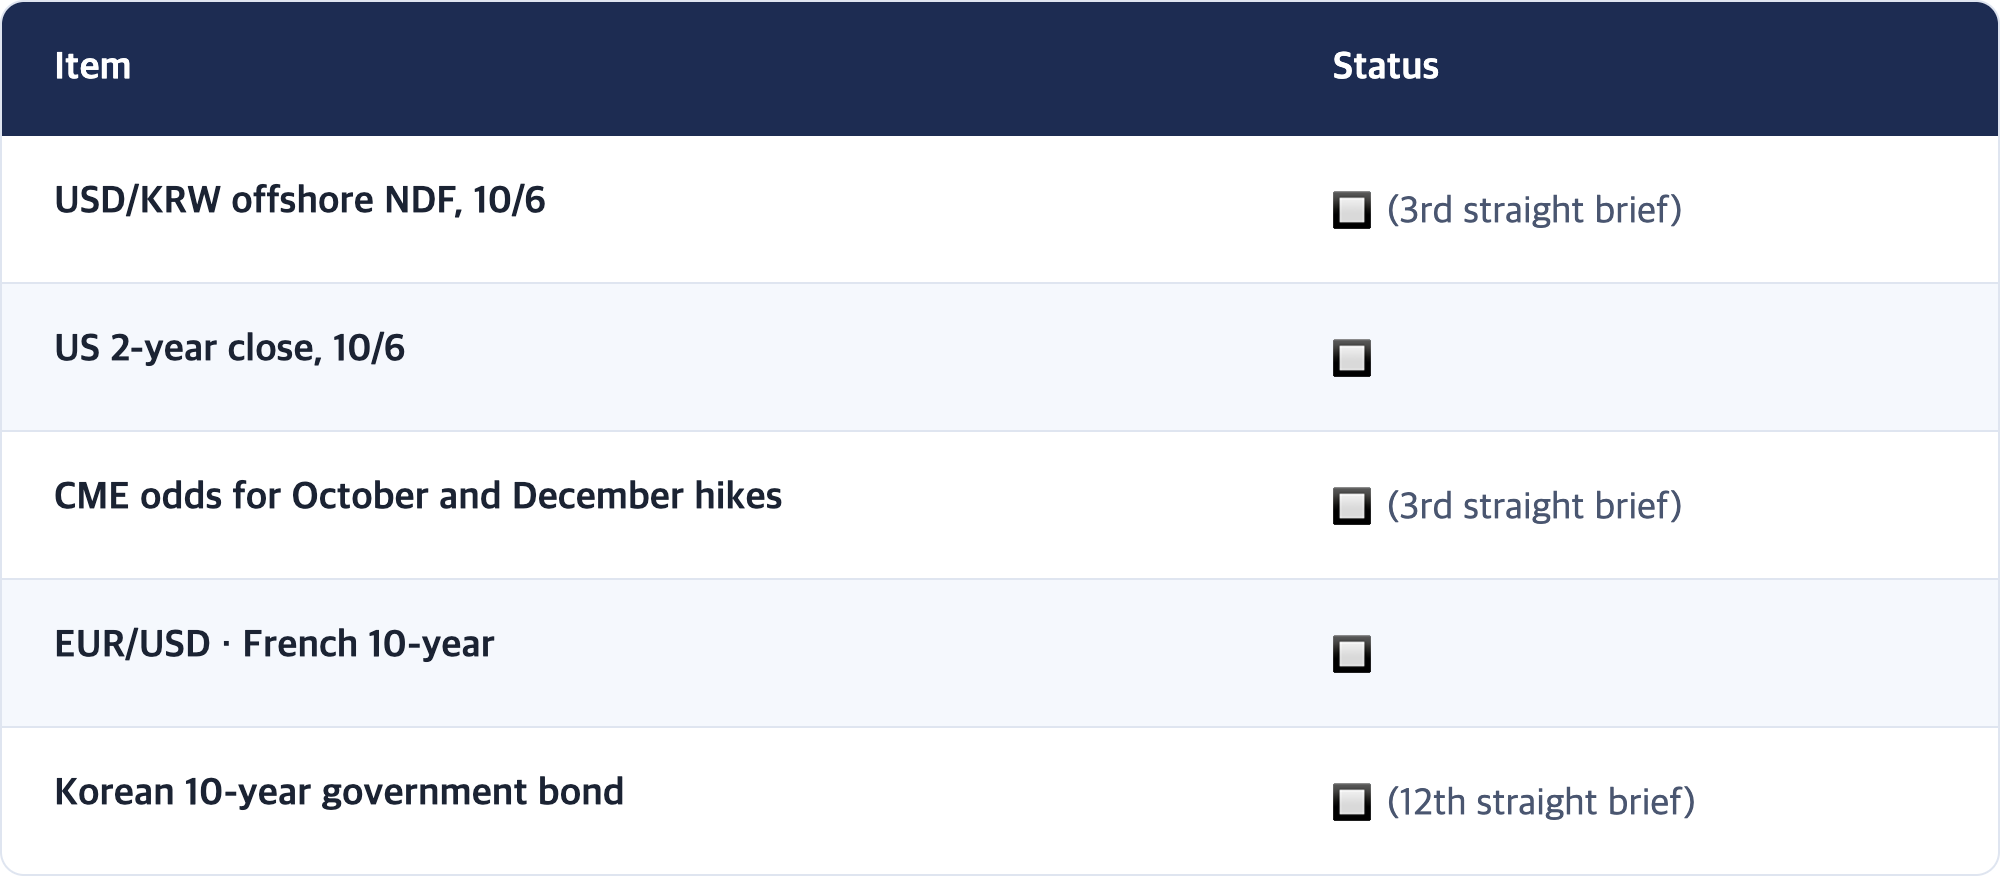
8. Event Calendar (KST)
Sources
- Stock market today: S&P 500, Nasdaq hit record highs as Nvidia, AMD lead tech higher | Yahoo Finance
- Stock Market Today (Oct. 6, 2026): S&P 500 sets new record as oil prices, Treasury yields settle | TheStreet
- AI·실적 기대에 뉴욕증시 또 사상 최고 … S&P500 7800선 돌파 | New Daily (Korean)
- US sells USD 58bln of 3-year notes; stop-through 0.2bps | Newsquawk
- US 10 Year Treasury Note Yield | Trading Economics
- International oil prices flat as Houthi counterattacks, Gulf exports offset | eToday (Korean)
- Oil prices fall, Brent settles at $100.32 as markets weigh higher Gulf exports, G7 supply boost | Gulf News
- Brent Holds $13.80 Over WTI as Gulf Freight Hits $33 a Barrel | Vantage Markets
- AI rally shrugs off rates; Nvidia nears $6 trillion | eToday (Korean)
- Marvell Technology Raises Revenue Guidance | MarketScreener
- PHLX Semiconductor Sector Index (SOX) | Nasdaq Global Indexes
- Micron Stock Price History | Investing.com
- Won closes at 1,343.6 per dollar | Single List (Korean)
- KOSPI slips to 6,900s as foreigners sell ₩1.7 trillion | EBN via Investing.com (Korean)
- KOSPI back at 7,000: "Samsung earnings the key variable this week" | YTN (Korean)
- FOMC Minutes Release Schedule 2026 | fedratecalc
Market Analyst · This brief does not recommend buying or selling any individual stock. It provides macro context and interpretation.
📌 More market briefs
※ This post is market observation and organization intended to support your own judgment. It is not a recommendation to buy or sell any security. Figures are as of the time of writing and may differ between sources.
If this was useful, bookmark it or pass it along. It genuinely helps me write the next one.
I can survive. We can survive.